
 Global Hydraulic Power Unit Market | 2026-2036
Global Hydraulic Power Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydraulic Power Unit Market Analysis
China is reconfiguring regional supply dynamics through expanded domestic production of high-pressure hydraulic systems for heavy machinery. Bosch Rexroth AG leverages its integrated drive and control portfolio to anchor premium positioning across European industrial channels. Parker Hannifin Corporation sustains broad geographic coverage through decentralized manufacturing footprints and aftermarket service density. Eaton Corporation Plc competes on energy-efficient system architectures that reduce parasitic losses in continuous-duty applications.
A hydraulic power unit is a self-contained system comprising a motor, pump, reservoir, and control valves that pressurize hydraulic fluid to transmit mechanical power. Operating pressures typically range from 1,000 to 6,000 psi depending on application duty cycles, with modular manifold designs enabling customization for specific force and flow requirements. Electric-type units now command structural attention as industrial electrification agendas displace diesel-driven alternatives in indoor and urban construction environments. The mining application segment retains durable demand for high-displacement diesel configurations where grid connectivity remains absent and ambient conditions punish electronic components. Component-level margin pools concentrate in precision pumps and accumulators where metallurgical specifications and sealing technologies create defendable specialization.
The EPA enforces Tier 4 Final emissions limits on off-road diesel engines, compelling OEMs to specify electric or hybrid hydraulic power units for domestic construction and agriculture equipment. ECHA's REACH framework restricts specific hydraulic fluid chemistries, reshaping formulation roadmaps for reservoir and seal compatibility across European supply chains. ISO 4413 standards govern hydraulic system safety and contamination control, establishing baseline design protocols that manufacturers must satisfy for international market access. Stakeholders should monitor how dual carbon targets in China and the EU Green Deal's industrial decarbonization timelines redirect procurement specifications toward regenerative and electrified fluid power architectures.
Market Dynamics
Electrification mandates from the EPA's Tier 4 Final standards are compressing diesel-driven unit demand while regenerative architectures capture momentum in continuous-duty industrial settings.
Growth Catalysts
- Infrastructure stimulus:Public works investment in Germany, India, and Brazil is accelerating orders for high-pressure fluid power systems in earthmoving and piling equipment.
- REACH fluid reformulation:ECHA's restrictions on mineral oil chemistries are forcing reservoir and seal redesigns that favor synthetic biodegradable alternatives with longer service intervals.
- Modular manifold adoption:Customizable manifold designs are reducing OEM engineering cycles for force-specific applications in injection molding and metal forming.
Market Restraints
- Specialized steel input volatility:Alloy specifications for high-pressure pump housings face price swings tied to nickel and chromium supply from South African and Indonesian concentrate.
- Accumulator supply concentration:Precision bladder and piston accumulator manufacturing clusters in southern Germany, creating vulnerability for non-European OEMs during logistics disruptions.
- Electric motor torque density limits:Battery-electric power units above 75 kW output suffer weight penalties that restrict adoption in heavy-lift mining and offshore applications.
Strategic Opportunities
- India domestic production:Local assembly partnerships for construction equipment OEMs can bypass import duties on complete power unit assemblies under the PLI scheme for heavy industry.
- EU Green Deal industrial decarbonization:Regenerative hydraulic architectures with energy recovery qualify for green procurement preference in public infrastructure tenders across member states.
- IoT-condition monitoring convergence:Sensor-integrated power units enabling predictive maintenance contracts are opening recurring revenue streams for distributors serving fleet operators.
Industry Challenges
- Fluid power engineering talent scarcity:Retirement waves among hydraulic system designers in Midwest US manufacturing regions are outpacing university program output.
- ISO 4413 certification timelines:Third-party validation for contamination control protocols adds six to nine months to new product qualification for international market entry.
- Legacy system integration friction:Retrofitting electrified power units into existing machine architectures requires custom manifold engineering that erodes margin on replacement contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydraulic Power Unit Market |
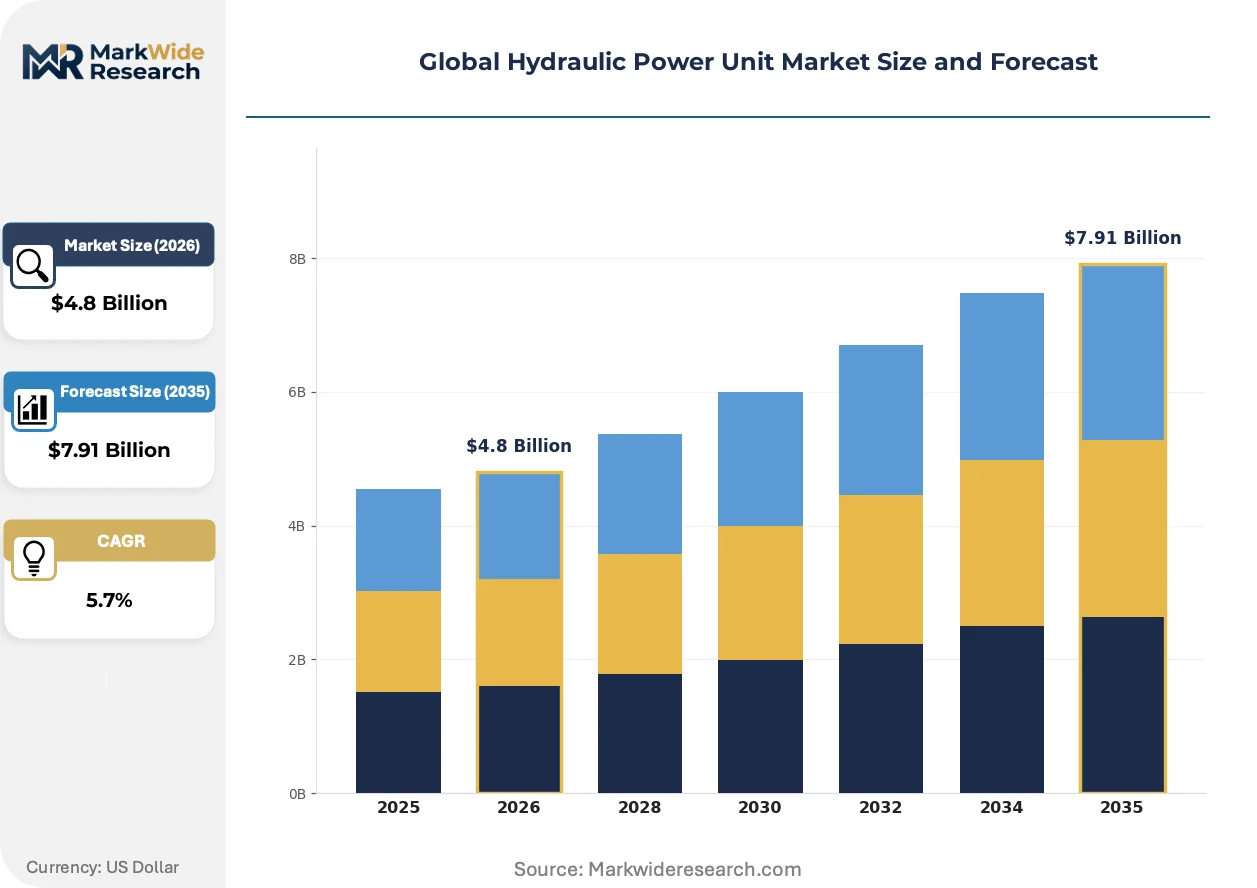
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Construction, Agriculture, Mining, Marine Type: Electric, Diesel, Hybrid, Pneumatic End User: Manufacturing, Energy, Transportation, Defense Component: Pumps, Reservoirs, Accumulators, Filters |
| Companies Covered | Danfoss Power Solutions, Nachi-Fujikoshi Corporation, Bosch Rexroth AG, Weber Hydraulik GmbH, HAWE Hydraulik SE, Parker Hannifin Corporation, Hydac International GmbH, Kawasaki Heavy Industries, Eaton Corporation Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydraulic Power Unit Market Emerging Trajectories
Fluid power architectures are splitting between electrified precision systems for indoor industrial duty and ruggedized diesel-hybrid configurations for remote heavy-lift environments.
Electro-hydraulic pump drives combining servo motors with variable displacement pumps are hybridizing system design by enabling precise flow-on-demand control. Warehouse automation OEMs in Japan and the Netherlands are specifying these configurations for energy recovery during load lowering. The technology is compressing hydraulic fluid consumption rates and reducing reservoir sizing requirements in material handling equipment.
EPA enforcement of Tier 4 Final particulate and NOx limits on off-road diesel engines is compelling construction equipment manufacturers to specify battery-electric or hybrid power units for domestic urban job sites. The regulation is reshaping OEM supplier qualification criteria, with fluid power vendors now required to demonstrate electromagnetic compatibility and thermal management for electric motor integration. Underground mining equipment in Australia and Canada faces parallel pressure from state-level diesel particulate exposure limits.
Equipment-as-a-service contracting is fragmenting traditional capital equipment purchasing in European industrial channels. Fleet operators in Germany and France are unbundling power unit maintenance from machine acquisition, favoring suppliers with dense regional service technician networks. The shift is most visible in injection molding and metal stamping verticals where uptime guarantees dominate supplier selection criteria.
Global Hydraulic Power Unit Market Segmentation
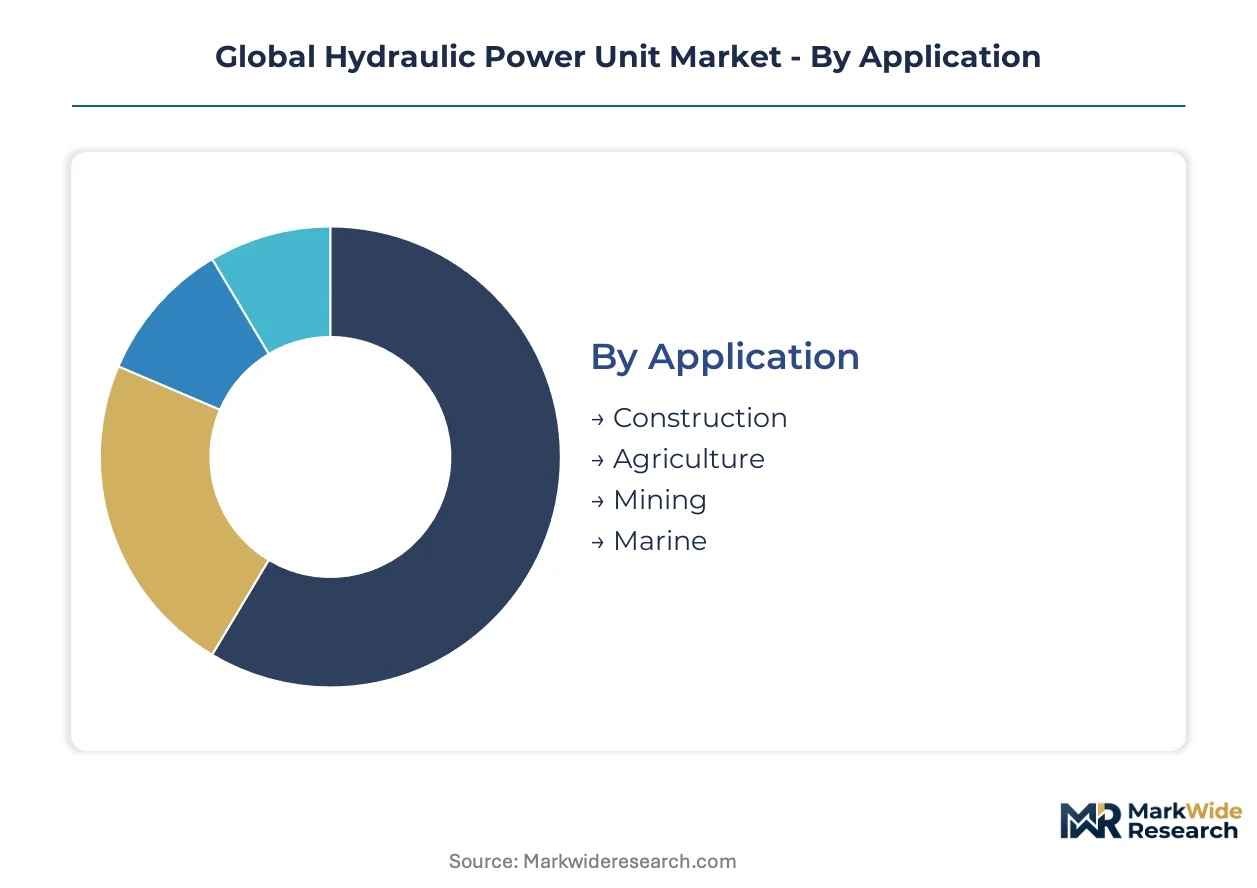
Segmentation in hydraulic power units reveals divergent engineering priorities across duty cycles and operating environments. Procurement specifications vary sharply between continuous industrial operations and intermittent heavy-lift applications, with electrification timelines creating new fault lines in technology selection.
Application:
Replacement cycles stretch from 8,000 hours in continuous manufacturing to 15,000+ hours in seasonal agriculture, compressing revenue recognition timing for aftermarket channels.
- Construction:High-pressure systems rated for 3,000-6,000 psi dominate earthmoving and piling equipment where duty cycles punish component fatigue. EPA Tier 4 Final enforcement in US urban job sites is accelerating electric unit penetration for excavators and compact loaders.
- Mining:Diesel configurations retain structural preference in Australian and Canadian underground operations where grid absence and particulate exposure limits create dual constraints on electrification timelines.
- Agriculture:Seasonal duty patterns favor modular serviceability and field-replaceable cartridge valves in tractors and harvesters across Brazilian soybean regions and Midwest US grain belts.
- Marine:Corrosion-resistant manifold materials and sealed reservoir designs address salt spray exposure in offshore winch and deck machinery applications.
Construction dominates installed base. Mining is where expansion concentrates.
Type:
Cost tiers separate premium electric precision from economy diesel displacement, with hybrid architectures capturing mid-market positioning through fuel efficiency guarantees.
- Electric:Servo-driven pump combinations enable flow-on-demand control with energy recovery during load lowering. Warehouse automation OEMs in Japan and the Netherlands specify these configurations for 40% hydraulic fluid consumption reduction.
- Diesel:High-displacement units above 75 kW output retain installed base in remote mining and offshore applications where battery weight penalties restrict electric alternatives.
- Hybrid:Parallel electric-diesel architectures capture municipal infrastructure tenders in Germany qualifying for EU Green Deal procurement preferences through regenerative energy recovery.
- Pneumatic:Compressed air alternatives address explosive atmosphere requirements in chemical processing and grain handling where hydraulic fluid ignition risks dominate specification.
Electric units command premium pricing. Hybrid configurations are gaining share fastest.
End User:
Customer concentration varies from fragmented fleet operators in transportation to consolidated utility procurement in energy infrastructure.
- Manufacturing:Injection molding and metal stamping verticals in Germany and France prioritize uptime guarantees and dense regional service technician networks.
- Energy:Wind turbine pitch control and hydraulic fracturing equipment drive demand for extreme-temperature sealing technologies in North Sea and Permian Basin operations.
- Transportation:Port cargo handling and rail maintenance equipment favor standardized manifold interfaces to reduce spare parts proliferation across multi-vendor fleets.
- Defense:Armored vehicle and naval specification requirements impose electromagnetic hardening and shock-resistant reservoir designs with extended qualification timelines.
Manufacturing dominates aftermarket revenue. Energy is where specification premiums concentrate.
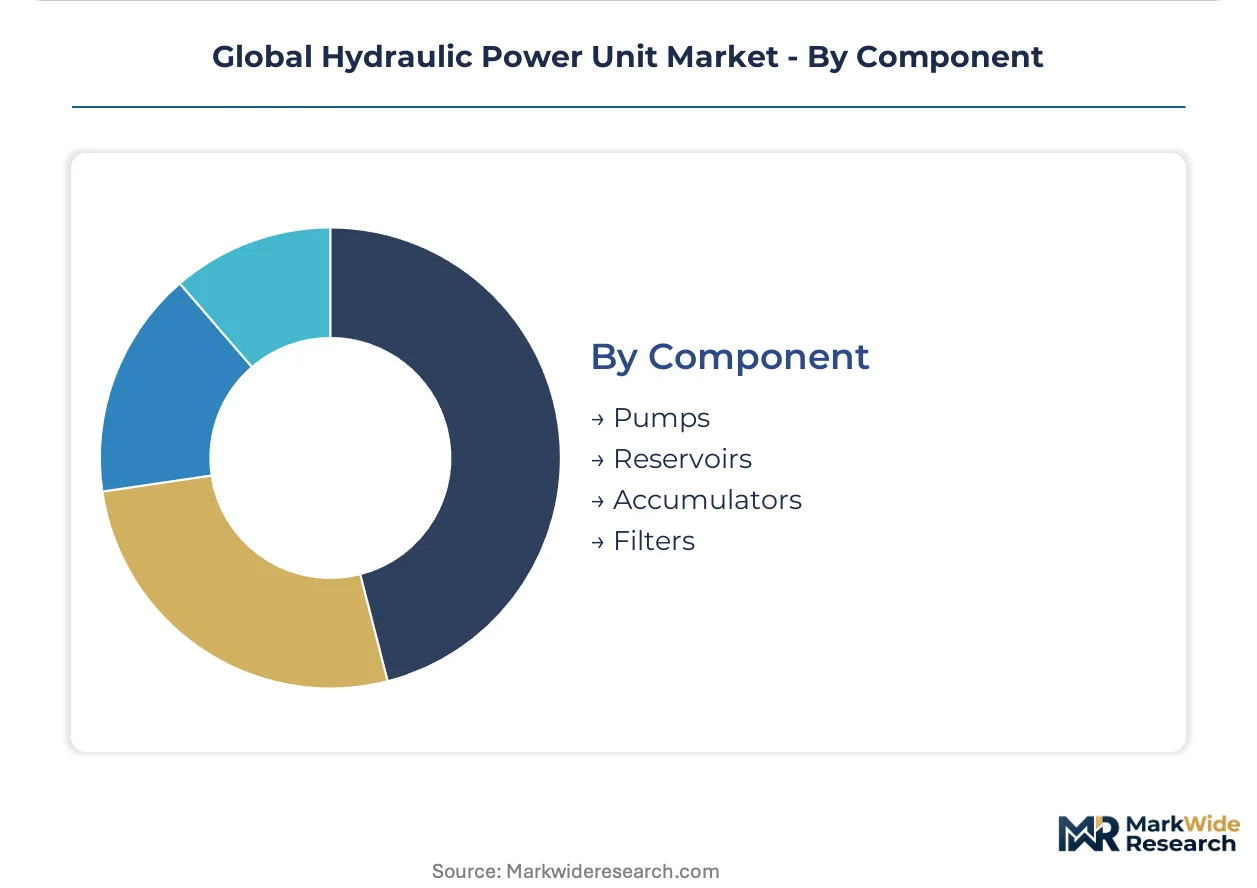
Component:
Margin pools concentrate in precision-machined elements where metallurgical specifications create defendable specialization, with commodity reservoirs facing price pressure from standardized fabrication.
- Pumps:Variable displacement axial piston designs with nickel-chromium alloy housings face input volatility from South African and Indonesian concentrate supply concentration.
- Accumulators:Precision bladder and piston manufacturing clusters in southern Germany create logistics vulnerability for non-European OEMs during supply disruptions.
- Reservoirs:Synthetic biodegradable fluid compatibility requirements under ECHA REACH are forcing seal material redesigns with extended service interval claims.
- Filters:Contamination control protocols under ISO 4413 establish baseline qualification requirements adding six to nine months to new product market entry.
Pumps dominate component margin capture. Accumulators face supply concentration risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision accumulator manufacturing clusters in southern Germany concentrate supply-side capacity for high-pressure hydraulic systems. Component fabrication for mining and construction equipment distributes across industrial corridors in China, Germany, and the United States.
United States
EPA Tier 4 Final enforcement compresses diesel-driven unit demand in urban construction while regenerative electric architectures capture share in continuous-duty manufacturing. The Inflation Reduction Act subsidizes industrial electrification retrofits for fluid power systems in Midwest manufacturing corridors. Detroit-area automotive stamping operations and Houston-based energy equipment fabricators anchor regional demand concentration.
Germany
EU Green Deal procurement preferences accelerate regenerative hydraulic adoption in municipal infrastructure tenders across Baden-Württemberg and Bavaria. ECHA REACH fluid restrictions force reservoir and seal redesigns favoring synthetic biodegradable alternatives with extended service intervals. Stuttgart and Munich precision engineering clusters anchor European supply chains for high-pressure pump housings and manifold assemblies.
China
Dual carbon targets redirect state-owned enterprise procurement toward electrified fluid power architectures in Yangtze River Delta manufacturing zones. MEE enforcement of industrial emissions standards tightens diesel equipment operating permits in Pearl River Delta construction markets. Domestic production of high-pressure hydraulic systems for heavy machinery expands through Shandong Peninsula and Sichuan-Chongqing industrial corridors.
India
PLI scheme incentives for heavy industry attract local assembly partnerships for construction equipment OEMs seeking import duty avoidance on complete power unit assemblies. CEA grid reliability mandates shape electrification feasibility assessments for mining and port cargo handling applications. Maharashtra and Gujarat industrial zones concentrate demand from injection molding and metal forming verticals.
Australia
State-level diesel particulate exposure limits in Queensland and Western Australia constrain underground mining equipment specifications despite grid absence in remote operations. TGA-equivalent mining safety frameworks impose contamination control protocols that extend ISO 4413 certification timelines for new market entrants. Perth-based energy services and Brisbane-area port automation anchor regional procurement.
Global Hydraulic Power Unit Market Vendor Landscape
Integrated drive specialists and component-focused fabricators split the market between premium system architectures and modular replacement part supply. Consolidation pressure concentrates around precision pump and accumulator manufacturing where metallurgical specifications create defendable specialization. Two strategic archetypes dominate: diversified industrial conglomerates with decentralized manufacturing footprints, and mid-cap hydraulic specialists with captive regional service networks. Competitive moves center on strategic partnerships for electric motor integration and geographic expansion through local assembly licensing.
Among diversified industrial conglomerates, Bosch Rexroth AG and Parker Hannifin Corporation occupy positions spanning integrated drive portfolios and broad geographic coverage. Eaton Corporation Plc exemplifies the energy-efficient system architecture archetype. HAWE Hydraulik SE and Hydac International GmbH represent the German mid-cap specialist model with precision component concentration. Weber Hydraulik GmbH anchors the regional fabricator tier. Danfoss Power Solutions and Nachi-Fujikoshi Corporation sit within the diversified industrial technology segment. Kawasaki Heavy Industries reflects heavy machinery integration patterns.
| Leading Market Players |
|---|
| Danfoss Power Solutions |
| Nachi-Fujikoshi Corporation |
| Bosch Rexroth AG |
| Weber Hydraulik GmbH |
| HAWE Hydraulik SE |
| Parker Hannifin Corporation |
| Hydac International GmbH |
| Kawasaki Heavy Industries |
| Eaton Corporation Plc |
| Others |
Supply Flow & Price Mechanics
Stuttgart precision engineering clusters concentrate high-pressure pump and accumulator manufacturing capacity, granting incumbent suppliers asymmetric pricing power over non-European OEMs during logistics disruptions. EPA Tier 4 Final compliance costs and ECHA REACH fluid reformulation requirements cascade downstream, compressing margins for standardized reservoir fabricators while defending premium positioning for integrated drive specialists.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across electric, hybrid, and diesel hydraulic power unit architectures. Three-tier pricing separates premium servo-driven configurations from standard fixed-displacement units and economy modular assemblies. Price differentiation rests on certification grade under ISO 4413 contamination protocols and aftermarket service bundling density. Pricing pressure stems from nickel-chromium alloy input volatility for high-pressure pump housings. Fleet operators in transportation applications exhibit highest price sensitivity; energy sector procurement tolerates specification premiums for extreme-temperature sealing technologies.
Supply Chain Analysis
Contract manufacturing for precision accumulators concentrates in southern Germany, with Bosch Rexroth AG and Hydac International GmbH holding captive capacity. Component fabrication draws from China, Germany, and the United States for mining and construction equipment applications. Raw material dependencies center on South African and Indonesian nickel-chromium concentrate, synthetic biodegradable hydraulic fluids, and precision-machined manifold blanks. Single-source vulnerability concentrates in German accumulator bladder manufacturing. Distribution runs through OEM direct procurement for original equipment and authorized distributor networks for aftermarket replacement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment creates asymmetric switching costs. OEMs face 6-9 month ISO 4413 requalification timelines that cement incumbent positions.
For Market Incumbents: Insulate precision component margins by deepening backward integration into nickel-chromium alloy supply and expanding captive accumulator manufacturing beyond southern Germany. Threat of electric motor torque density limits in heavy-lift mining applications preserves diesel-hybrid demand, yet battery-electric encroachment in urban construction requires electromagnetic compatibility certification investment to defend municipal tender eligibility. For New Entrants and Emerging Players: Pursue local assembly partnerships under India's PLI scheme for heavy industry, targeting import duty avoidance on complete power unit assemblies for construction equipment OEMs. Warehouse automation in Japan and the Netherlands presents most penetrable electrified precision segment given 40% hydraulic fluid consumption reduction claims and energy recovery specifications. Go-to-market angle: IoT-condition monitoring convergence with predictive maintenance contracting to capture recurring revenue from fleet operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified industrial conglomerates with decentralized manufacturing footprints over pure-play hydraulic specialists. Long-term viability rests on electrification architecture transition speed and service network density. Acquisition target archetype: mid-cap German specialists with captive regional technician networks and REACH-compliant fluid formulation capabilities. Signal to watch: state-level diesel particulate exposure limit adoption in Australian and Canadian mining jurisdictions as electrification inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive nickel-chromium sourcing defends pump housing margins against South African concentrate volatility. |
| Electrification Architecture Certification | EPA Tier 4 Final electromagnetic compatibility validation unlocks urban construction equipment procurement. |
| IoT-Condition Monitoring Platform | Sensor-integrated power units enable predictive maintenance contracts with German fleet operators. |
| Local Assembly Licensing | India PLI scheme partnerships bypass import duties for construction OEMs in Maharashtra industrial zones. |
| Biodegradable Fluid Formulation | ECHA REACH-compliant synthetic alternatives extend service intervals and defend European aftermarket share. |
Methodological Framework
A standing panel of OEM procurement directors, aftermarket service managers, plant engineers at injection molding facilities, and hydraulic system designers provided ongoing calibration across the analysis. Primary interviews with maintenance directors and fleet operators combined with secondary validation from SEC 10-K filings, customs and trade data, EPA enforcement disclosures, and ECHA REACH substance restriction updates. Bottom-up unit economics triangulated against top-down industrial production indices.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling application splits between construction, mining, agriculture, and marine; type categories spanning electric, diesel, hybrid, and pneumatic; and end-user concentration across manufacturing, energy, transportation, and defense. CAGRs derived from segment-level demand elasticity and replacement cycle dynamics, with electrification timeline assumptions and infrastructure stimulus disbursement schedules as hydraulic power unit-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, nickel-chromium concentrate pricing, and grid reliability in remote mining regions would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology substitution rates. Quarterly review of EPA waiver approvals, ECHA SVHC candidate list updates, and Indian PLI scheme beneficiary announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Natural Gas Turbine Market
Power Equipment
Wind Turbine Maintenance Market
Power Equipment
Power Conditioning Services Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
Australia Power EPC Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
Europe SCR Power Controller Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
India Power EPC Market
Power Equipment
Global Power System Simulator Market
Power Equipment
Submarine Power Cable Market
Power Equipment
China Power EPC Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Asia-Pacific Gas Turbine Market