
 Scoliosis Management Market | 2026-2036
Scoliosis Management Market Size, Share, and Industry Trends Forecast 2026-2036
Scoliosis Management Market Analysis
Orthopedic specialty distributor networks is reconfiguring around direct-to-hospital contracting models for scoliosis bracing and implant systems. Medtronic leverages its integrated spine platform to sustain bulk purchasing agreements with major pediatric hospital systems. NuVasive competes through differentiated lateral approach technologies that reduce tissue disruption in adolescent idiopathic procedures. Boston Orthotics & Prosthetics anchors its position in custom TLSO fabrication, controlling regional orthotist training pipelines that lock in referral flows.
Scoliosis management encompasses the clinical evaluation, non-surgical correction, and surgical stabilization of abnormal lateral spinal curvature, typically quantified by Cobb angle measurement exceeding ten degrees in the coronal plane. Bracing systems function as the primary non-surgical intervention for skeletally immature patients, employing rigid or dynamic orthotic designs to halt curve progression during growth spurts. Surgery represents the highest-value segment, where pedicle screw constructs and tethering systems command premium pricing tied to biomechanical complexity and OR time. AI-driven analysis is expanding fastest among technology segments, as machine learning algorithms trained on longitudinal radiographic datasets reduce inter-observer variability in Cobb angle assessment and predict curve progression risk with greater precision than manual measurement.
The FDA governs spinal implant PMA and 510(k) submissions, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for class III devices including growing rod systems. ISO 13485 quality management certification remains mandatory for manufacturers supplying both regulated markets, creating compliance barriers that favor established players with dedicated regulatory affairs infrastructure. Stakeholders must monitor reimbursement policy shifts for vertebral body tethering as payors evaluate long-term outcomes data against fusion alternatives.
Market Dynamics
Vertebral body tethering systems are compressing the surgical intervention window for adolescent idiopathic scoliosis, forcing pediatric orthopedic centers to reconfigure OR scheduling and instrument sterilization workflows around hybrid fusion-tethering capabilities.
Growth Catalysts
- EU Medical Device Regulation:Stricter clinical evidence requirements for class III growing rod systems are accelerating consolidation among manufacturers with dedicated regulatory affairs infrastructure, favoring established players with PMA track records.
- Pediatric orthopedic clinics:Expansion of non-surgical intervention protocols in academic medical centers is driving demand for dynamic bracing systems and AI-driven curve progression monitoring during growth spurts.
- Machine learning algorithms:Training on longitudinal radiographic datasets is reducing inter-observer variability in Cobb angle assessment and enabling predictive risk stratification that redirects borderline surgical cases toward extended bracing protocols.
Market Restraints
- Titanium alloy supply concentration:Pedicle screw raw material sourcing clusters around a limited supplier base in aerospace-adjacent titanium forging operations, exposing implant manufacturers to spot price volatility and allocation risk.
- Long-term fusion adjacent segment disease:Skeletally immature patients undergoing posterior spinal fusion face documented revision burdens at 10-15 year horizons, creating payer resistance and clinical hesitation in curve magnitudes below 50 degrees.
- Orthotist workforce pipeline constraints:Custom TLSO fabrication requires specialized training that regional orthotist programs in the United States and Germany cannot scale to match referral volume growth from expanded screening programs.
Strategic Opportunities
- Japan's aging scoliosis population:Adult degenerative scoliosis incidence in Japanese metropolitan corridors exceeds pediatric case volume, creating demand for minimally invasive lateral interbody fusion systems adapted to osteoporotic bone quality.
- Remote patient monitoring integration:Wearable posture sensors paired with cloud-based compliance tracking are opening subscription revenue streams that decouple orthotic provider economics from one-time brace fabrication fees.
- Biologics-enhanced fusion:Demineralized bone matrix and synthetic graft substitutes are converging with 3D-printed porous titanium interbody cages to accelerate arthrodesis in neuromuscular scoliosis patients with compromised bone healing capacity.
Industry Challenges
- Pediatric spine surgeon fellowship throughput:The specialized skill set for growing rod lengthening procedures and vertebral body tethering placement remains concentrated among a limited cohort of academic training programs, constraining procedure volume expansion regardless of device availability.
- ISO 13485 certification timeline:New market entrants face 18-24 month quality management system implementation cycles before regulatory submission eligibility, delaying revenue recognition and consuming pre-commercialization capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scoliosis Management Market |
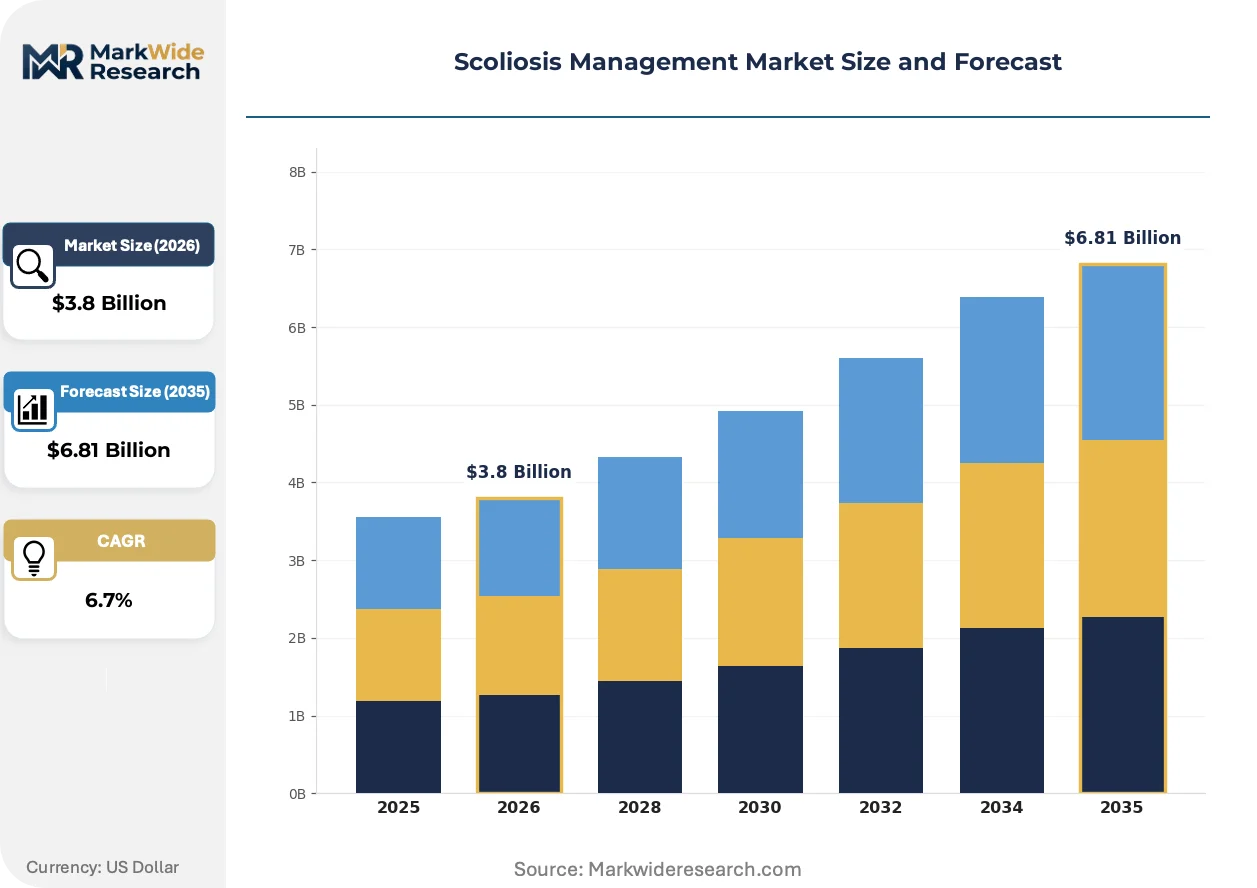
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Surgery, Physical Therapy, Consultations Technology: 3D Imaging, AI-Driven Analysis, Wireless Monitoring, Surgical Navigation End User: Pediatric Patients, Adult Patients, Healthcare Providers, Rehabilitation Centers Delivery Mode: Outpatient Services, Inpatient Services, Home Care, Telehealth |
| Companies Covered | Medtronic, Boston Orthotics & Prosthetics, NuVasive, Zimmer Biomet, Orthofix, Aspen Medical Products, Össur, Stryker Corporation, OrthoPediatrics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scoliosis Management Market Emerging Trajectories
Scoliosis management is experiencing convergence between biomechanical correction hardware and predictive analytics, with hardware commoditization pressures forcing differentiation through pre-operative planning software and post-operative monitoring ecosystems.
Dynamic compression-based tethering systems are migrating from experimental status toward standard-of-care consideration for skeletally immature patients with main thoracic curves between 40-65 degrees. Pediatric orthopedic departments at academic medical centers in the United States and Germany are adopting these systems at measured pace, constrained by payer coverage determination timelines and long-term outcome data accumulation requirements. This technology migration is compressing the addressable market for traditional fusion constructs in the adolescent demographic while expanding total procedural volume through earlier intervention thresholds.
The FDA's evolving 510(k) clearance pathway for spinal devices is requiring enhanced biomechanical testing and predicate device justification that extends submission preparation timelines by 6-12 months compared to historical norms. This regulatory friction is favoring manufacturers with existing predicate families and dedicated regulatory affairs teams capable of navigating substantive equivalence arguments. Growing rod systems and magnetically controlled lengthening devices face the most acute pathway complexity, with de novo classification requests becoming more frequent for novel mechanism-of-action submissions.
Hospital procurement departments are consolidating vendor contracts around integrated spine platform providers capable of supplying bracing, navigation, and implant systems under single master agreements. This buyer concentration is displacing independent orthotic fabricators and regional implant distributors that lack capital reserves for inventory consignment arrangements. The shift is most visible in United States pediatric hospital systems where value-based care contracts tie orthopedic device spending to episode-of-care cost targets.
Scoliosis Management Market Segmentation
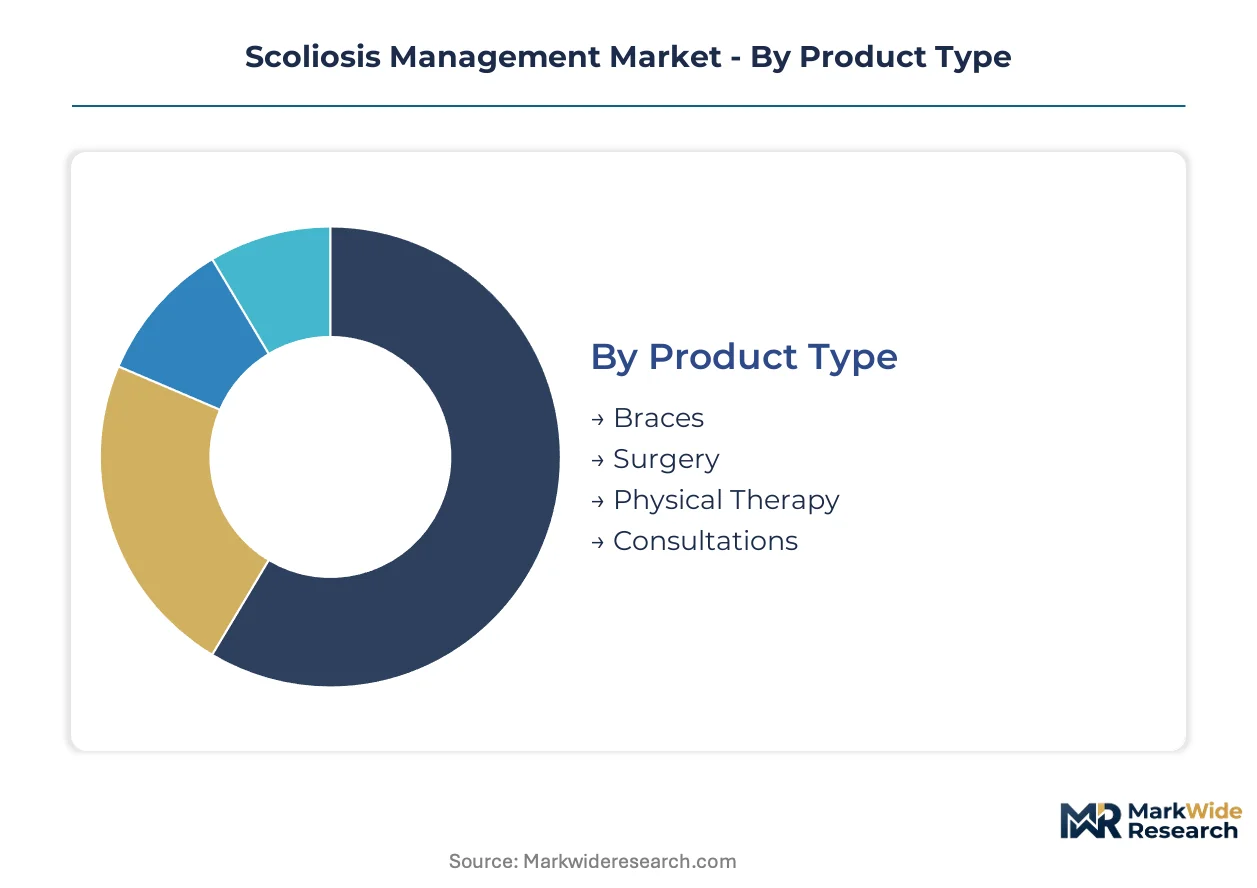
Scoliosis management spans divergent clinical pathways where non-surgical containment competes with surgical correction for patient volume and reimbursement dollars. Segmentation reveals how technology diffusion and care setting preferences redistribute value across hardware, software, and service delivery layers.
Product Type:
Use cases range from adolescent growth modulation through adult deformity correction, with each intervention tier commanding distinct pricing power and repeat purchase frequency.
- Braces:Rigid TLSO systems and dynamic orthotic designs apply corrective force during skeletal growth windows. Pediatric orthopedic clinics in the United States and Germany favor custom-fabricated options that lock in orthotist referral relationships through specialized training pipelines.
- Surgery:Pedicle screw constructs, growing rod systems, and vertebral body tethering command premium pricing tied to OR complexity and implant biomechanics. Academic medical centers with hybrid fusion-tethering capabilities capture the highest-margin procedures.
- Physical Therapy:Schroth method and SEAS protocols address curve-specific muscular imbalance. Rehabilitation centers integrate these into bundled post-operative care pathways.
- Consultations:Specialist evaluation and longitudinal monitoring generate recurring revenue through screening program referrals and progression surveillance.
Established volume favors braces; emerging adoption favors surgery as tethering systems compress intervention thresholds.
Technology:
Cost tiers separate capital-intensive intraoperative systems from software-enabled monitoring tools with lower deployment barriers.
- 3D Imaging:EOS low-dose radiography and surface topography scanning reduce cumulative radiation exposure in skeletally immature patients. Japanese metropolitan corridors deploy these for high-volume screening programs where repeat imaging is unavoidable.
- AI-Driven Analysis:Machine learning algorithms trained on longitudinal radiographic datasets automate Cobb angle measurement and progression risk stratification. This segment is climbing the fastest as FDA-cleared algorithms enter clinical workflow.
- Wireless Monitoring:Wearable posture sensors paired with cloud platforms track brace compliance and spinal loading. Home care providers leverage subscription revenue models that decouple economics from one-time device sales.
- Surgical Navigation:Robotic guidance and intraoperative imaging systems improve screw placement accuracy in complex deformity cases. Pediatric spine surgeons at academic centers demand these for growing rod lengthening procedures.
Capital intensity favors surgical navigation; margin expansion favors AI-driven analysis.
End User:
Customer type determines reimbursement pathway and purchasing authority, from parental decision-making in pediatric cases to surgeon-driven implant selection.
- Pediatric Patients:Skeletally immature individuals with adolescent idiopathic scoliosis represent the core addressable population for bracing and growth-friendly surgical interventions. Academic medical centers cluster specialized services around this demographic.
- Adult Patients:Degenerative scoliosis and prior fusion adjacent segment disease drive demand for revision surgery and pain management. Japanese aging demographics produce case volumes exceeding pediatric incidence in metropolitan corridors.
- Healthcare Providers:Orthopedic surgeons, physiatrists, and orthotists control referral flows and device selection. Hospital procurement departments consolidate vendor contracts around integrated platform providers.
- Rehabilitation Centers:Post-surgical recovery and conservative management protocols create recurring service demand. These facilities expand capacity to capture value-based care episode savings.
Procedure volume favors pediatric patients; revenue per case favors adult patients.
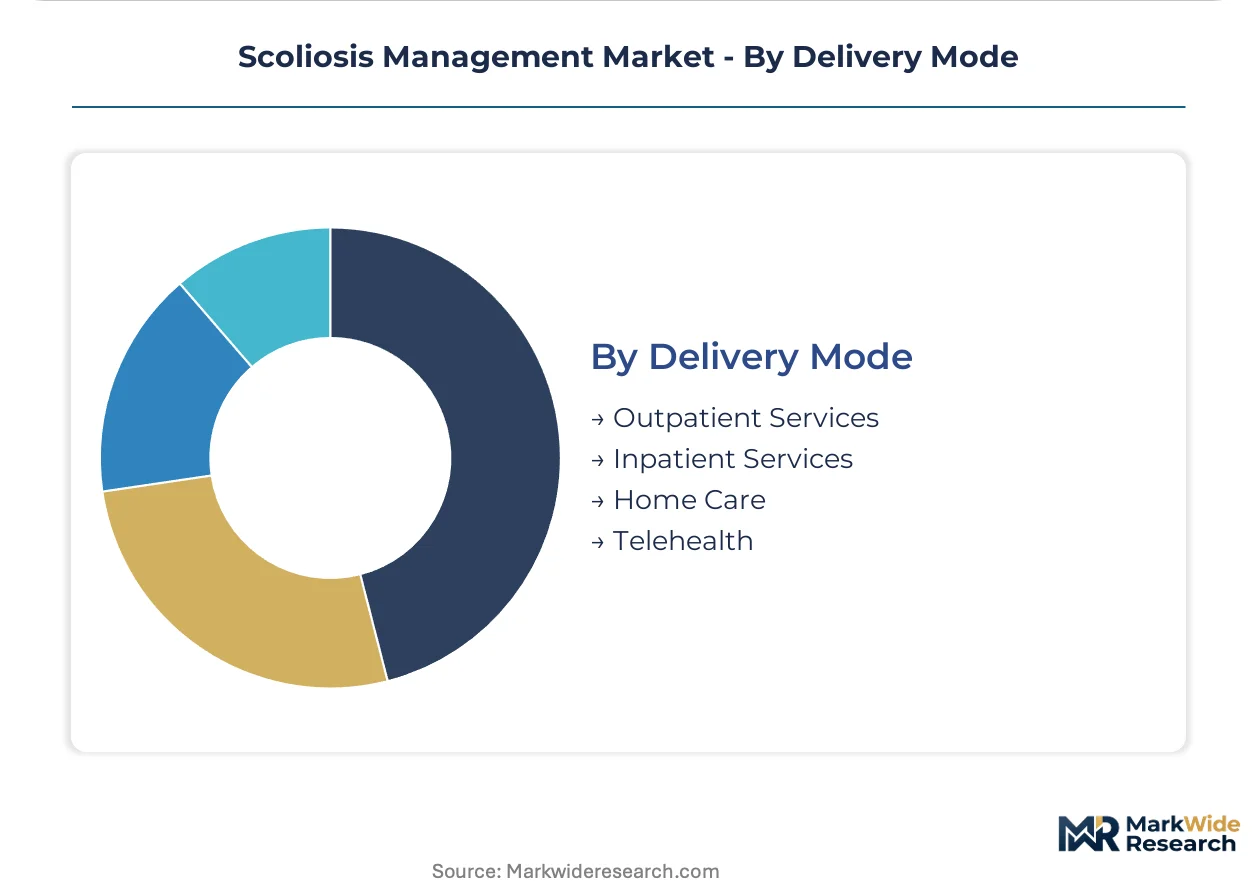
Delivery Mode:
Care setting selection reflects acuity, reimbursement, and patient convenience preferences across the treatment continuum.
- Outpatient Services:Brace fitting, physical therapy, and routine surveillance occur in ambulatory settings with lower overhead. Pediatric orthopedic clinics expand these capabilities to capture screening program referrals.
- Inpatient Services:Complex fusion procedures and growing rod implantation require hospital admission. Academic medical centers in the United States and Germany concentrate surgical volume for economies of scale.
- Home Care:Remote monitoring and patient-managed compliance tracking reduce clinical visit burden. Wearable sensor integration enables subscription-based revenue models for orthotic providers.
- Telehealth:Virtual consultation and AI-assisted image review extend specialist reach to underserved regions. Payer coverage determinations for remote scoliosis screening remain in development.
Reimbursement stability favors inpatient services; technology leverage favors home care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy reforms in the United States and Germany are accelerating capital deployment into pediatric orthopedic infrastructure. Japan's aging demographics are shifting clinical focus toward adult degenerative scoliosis interventions. Regulatory harmonization efforts between the FDA and Japan's PMDA are streamlining dual-market device approvals.
United States
Academic medical centers in Boston, Philadelphia, and Baltimore are expanding hybrid fusion-tethering surgical capabilities. The FDA's evolving 510(k) clearance pathway for spinal devices requires enhanced biomechanical testing that extends submission timelines. Pediatric hospital systems in Texas and California are consolidating vendor contracts around integrated spine platform providers.
Germany
Custom TLSO fabrication demand concentrates in Munich and Hamburg where orthotist training pipelines feed regional referral networks. The EU Medical Device Regulation imposes stricter clinical evidence requirements for class III growing rod systems. Baden-Württemberg manufacturers with ISO 13485 certification are capturing expanded market share as compliance barriers eliminate smaller competitors.
Japan
Adult degenerative scoliosis incidence in Tokyo and Osaka metropolitan corridors exceeds pediatric case volume. Japan's PMDA is aligning spinal device review timelines with FDA precedents to accelerate market entry. Yokohama-based screening programs deploy EOS low-dose radiography for high-volume repeat imaging in skeletally immature populations.
United Kingdom
NHS England's specialized commissioning frameworks are concentrating scoliosis surgery volume at designated pediatric centers in London and Birmingham. The Medicines and Healthcare products Regulatory Agency enforces EU MDR-equivalent standards for spinal implant market access. Manchester and Leeds rehabilitation centers are integrating Schroth method protocols into bundled post-operative care pathways.
Australia
TGA approval pathways for vertebral body tethering systems are creating first-mover advantages for manufacturers with established predicate families. Sydney and Melbourne pediatric orthopedic departments are adopting AI-driven Cobb angle analysis to reduce inter-observer variability. Queensland's rural telehealth initiatives are extending specialist screening reach to underserved regions.
Scoliosis Management Market Vendor Landscape
On the supply side, the industry is consolidating around integrated platform providers capable of spanning bracing, navigation, and implant systems under single master agreements. Three strategic archetypes dominate: diversified orthopedic conglomerates with spine-specific divisions, specialized pediatric device manufacturers, and regional orthotic fabricators with locked-in referral relationships. Competitive moves center on hospital procurement consolidation and regulatory affairs infrastructure acquisition to navigate FDA and EU MDR submission complexity.
Among diversified orthopedic conglomerates, Medtronic leverages its integrated spine platform to sustain bulk purchasing agreements, while NuVasive competes through differentiated lateral approach technologies. Boston Orthotics & Prosthetics anchors the custom fabrication tier, controlling regional orthotist training pipelines that lock in referral flows. These three exemplify how scale, surgical specialization, and service integration respectively command position across the value chain.
| Leading Market Players |
|---|
| Medtronic |
| Boston Orthotics & Prosthetics |
| NuVasive |
| Zimmer Biomet |
| Orthofix |
| Aspen Medical Products |
| Össur |
| Stryker Corporation |
| OrthoPediatrics |
| Others |
Supply Flow & Price Mechanics
Baden-Württemberg's ISO 13485-certified manufacturing cluster concentrates spinal implant production capacity, translating quality management infrastructure into pricing power over hospital procurement departments seeking compliant suppliers. Titanium alloy sourcing from aerospace-adjacent forging operations in the United States and Germany anchors cost structures, with spot price volatility feeding through to pedicle screw system quotations.
Pricing Analysis
Certification level creates the primary spread across spinal device tiers, with FDA PMA-track and EU MDR-compliant class III systems commanding premium positioning against 510(k) predicate-based alternatives. Three-tier pricing structure separates navigation-integrated constructs from standard pedicle screw kits and economy fixation options. Cost compression in the tethering segment intensifies as novel mechanism-of-action submissions trigger de novo classification delays. Pediatric hospital systems exhibit highest price sensitivity through value-based care contracts, while academic medical centers prioritize biomechanical performance over unit economics.
Supply Chain Analysis
Titanium alloy feedstock draws from specialized forging operations in the United States, Germany, and Japan, with medical-grade specifications requiring traceable metallurgical certification. Magnetically controlled growing rod components and 3D-printed porous interbody cages rest on precision machining capabilities concentrated in Baden-Württemberg and Swiss manufacturing corridors. Single-source vulnerability concentrates in pediatric spine surgeon training pipelines, constraining procedure volume regardless of device availability. Distribution runs through orthopedic specialty networks reconfiguring around direct-to-hospital contracting models with inventory consignment arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
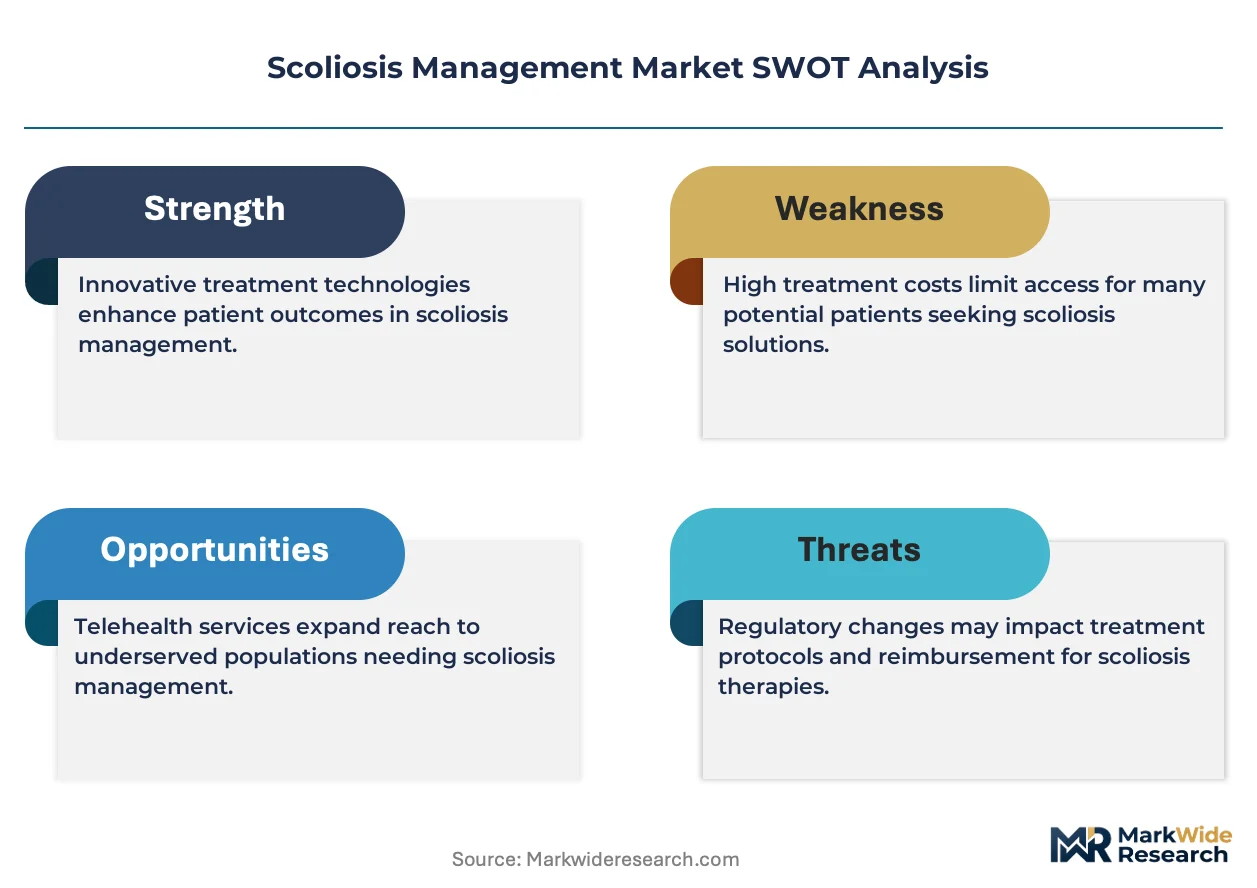
This market functions as a regulatory entrenchment story where ISO 13485 certification timelines and FDA PMA track records create switching costs that lock hospital procurement relationships. Network effects concentrate around academic medical centers with hybrid surgical capabilities that train referring orthotist networks.
For Market Incumbents: Harden regulatory affairs infrastructure against EU MDR clinical evidence requirements by acquiring dedicated PMA submission teams capable of navigating growing rod de novo classifications. Expand backward integration into titanium alloy sourcing to offset aerospace market spot price volatility affecting pedicle screw margins. Prioritize hospital system partnership consolidation before procurement departments complete vendor rationalization around integrated spine platforms.
For New Entrants and Emerging Players: Build out AI-driven Cobb angle analysis capabilities as the most penetrable technology segment, leveraging lower FDA 510(k) barriers compared to class III implant pathways. Target remote patient monitoring integration with wearable posture sensors and cloud-based compliance tracking, where subscription revenue models decouple economics from capital-intensive fabrication. Pursue telehealth-enabled screening partnerships with underserved regional health systems as the primary go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pediatric device manufacturers with vertebral body tethering predicate families and established surgeon training relationships. Long-term viability hinges on reimbursement policy shifts for fusion alternatives as payors accumulate outcomes data. Acquisition target archetypes include specialized orthotic fabricators controlling regional training pipelines and AI algorithm developers with FDA-cleared radiographic analysis tools. Monitor Japan's PMDA-FDA alignment progress as the signal to watch for accelerated dual-market device approval timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Navigation | Enhanced biomechanical testing requirements extend submission timelines for predicate-dependent spinal devices. |
| EU MDR Clinical Evidence Buildout | Stricter class III requirements favor manufacturers with dedicated regulatory affairs infrastructure and PMA track records. |
| Hospital System Partnership Consolidation | Integrated spine platform contracts displace independent distributors lacking consignment inventory capacity. |
| AI Algorithm Regulatory Clearance | FDA-cleared Cobb angle measurement tools reduce inter-observer variability and redirect borderline surgical cases. |
| Remote Monitoring Platform Development | Wearable posture sensors paired with cloud compliance tracking enable subscription revenue decoupled from brace fabrication. |
Methodological Framework
The analysis maps bracing systems, surgical implants, physical therapy protocols, and AI-driven monitoring technologies, each validated through pediatric orthopedic surgeons, hospital procurement managers, orthotist training program directors, and GPO contracts specialists. Primary interviews with academic medical center department heads and secondary validation against FDA 510(k) and PMA submission databases, EU MDR notified body opinions, and hospital procurement contract disclosures establish segment boundaries. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchor market sizing across the analysis window.
Assumptions held reimbursement policy trajectories for vertebral body tethering within current payer coverage determination timelines, while varying adoption curves for AI-driven analysis and remote monitoring integration. Segmentation dimensions modeled include product type, technology tier, end user demographic, and delivery mode across the projection horizon. CAGRs derive from procedure volume growth rates adjusted for pricing dynamics in tethering versus fusion alternatives. Forecast inputs incorporate pediatric spine surgeon fellowship throughput constraints and titanium alloy supply concentration risk.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified orthopedic conglomerates or rapid PMDA-FDA harmonization acceleration would shift outcomes. Cross-checking against Japan's aging scoliosis incidence trends and CMS episode-of-care cost target implementations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Thyroid Gland Disorders Treatment Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Gangrene Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Corneal Transplant Market
Medical Treatment
Nasopharyngeal Carcinoma Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market