
 Mast Cell Tumors Treatment Market | 2026-2036
Mast Cell Tumors Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Mast Cell Tumors Treatment Market Outlook
The capital-intensity divergence between large pharmaceutical conglomerates and mid-tier veterinary specialists is unwinding competitive boundaries in mast cell tumor therapeutics. Boehringer Ingelheim leverages its animal health division to sustain integrated development pipelines from human oncology spillover. Novartis anchors its position through targeted kinase inhibitor platforms originally validated in human medicine. Merck & Co. competes via checkpoint inhibitor research extending into veterinary immuno-oncology applications.
Mast cell tumors treatment encompasses pharmaceutical and biologic interventions targeting neoplastic mast cell proliferation in canines and felines, with tyrosine kinase inhibitors such as toceranib phosphate representing a cornerstone mechanism that interrupts KIT receptor signaling driving tumor angiogenesis. The primary purpose spans curative intent for localized disease, cytoreduction prior to surgery, and palliative management of metastatic or unresectable presentations. Immunotherapy approaches are capturing expanding margin pools as pet owners demonstrate willingness to absorb premium pricing for durable remission protocols, while oral administration routes dominate outpatient compliance due to reduced anesthesia requirements and owner convenience relative to injectable chemotherapy regimens. Injectable and subcutaneous delivery formats retain structural importance in hospital-based settings where therapeutic monitoring ensures protocol adherence.
FDA Center for Veterinary Medicine oversees approval pathways for animal drugs under the Federal Food, Drug, and Cosmetic Act, while EMA's Committee for Medicinal Products for Veterinary Use establishes centralized European authorization standards that shape cross-border market access. USDA Animal and Plant Health Inspection Service regulates veterinary biologics including certain immunotherapy candidates, creating a dual-track compliance environment that manufacturers must navigate for product commercialization. Stakeholders must monitor convergence between human oncology pipeline assets and veterinary indication expansion, as repurposing timelines and species-specific pharmacokinetic requirements will determine portfolio prioritization decisions.
Market Dynamics
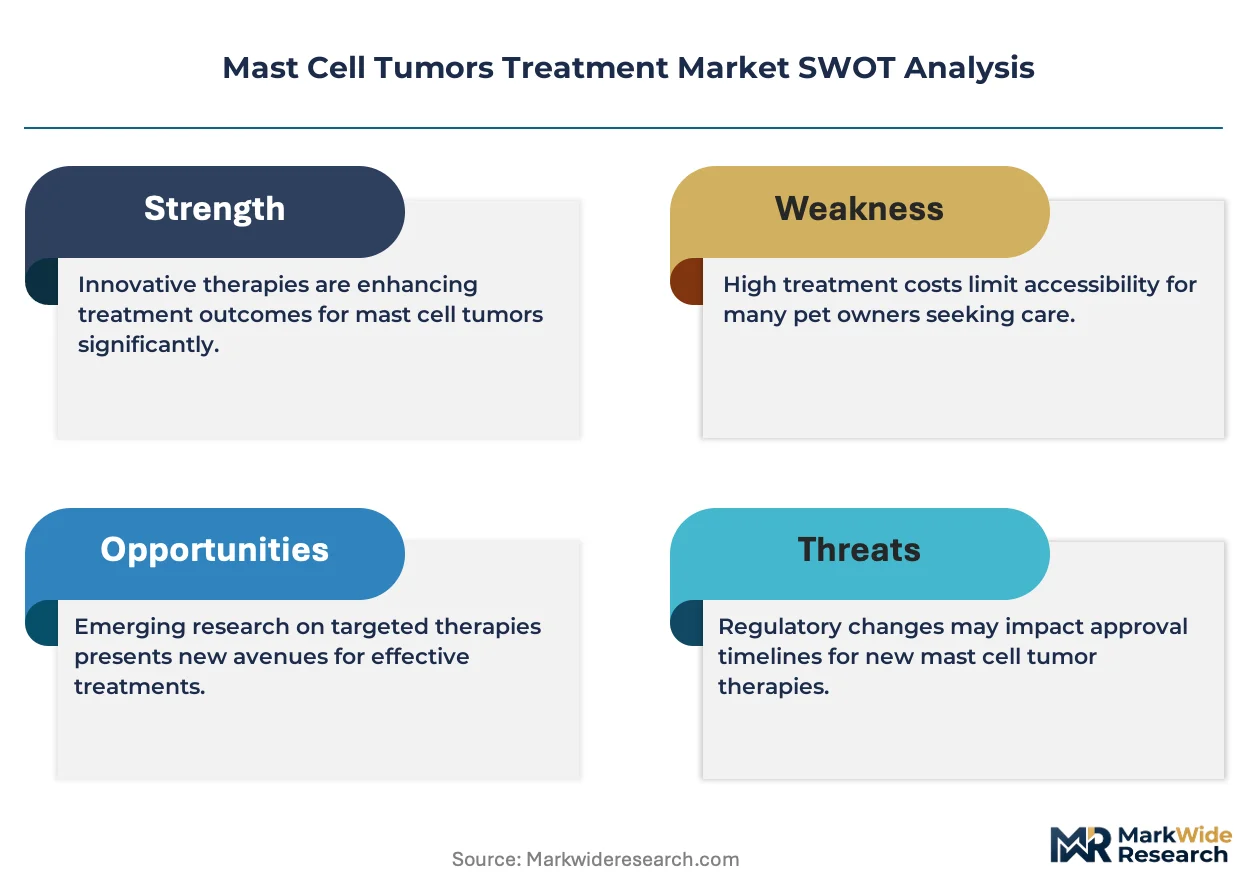
The convergence of human oncology pipeline spillover with streamlined veterinary approval pathways is compressing development timelines and redrawing competitive boundaries between pharmaceutical conglomerates and specialized animal health operators.
Growth Catalysts
- FDA Center for Veterinary Medicine Accelerated Pathways:The FDA's expanded conditional approval mechanisms for animal drugs reduce time-to-market for novel kinase inhibitors, enabling faster commercialization of KIT receptor antagonists.
- Companion Animal Practice Consolidation:Large specialty hospital networks are standardizing targeted therapy protocols, creating predictable demand pull for oral tyrosine kinase formulations across metropolitan veterinary referral centers.
- Biomarker-Guided Patient Selection:c-KIT mutation testing in diagnostic laboratories is refining treatment algorithms, expanding addressable populations for precision therapeutics beyond histologic grading alone.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for veterinary kinase inhibitors concentrates among a limited cohort of contract manufacturers in India and China, exposing sponsors to single-source risk.
- Species-Specific Pharmacokinetic Barriers:Canine metabolism of small-molecule inhibitors diverges substantially from human profiles, necessitating costly bridging studies that extend development expenditure timelines.
- Reimbursement Fragmentation:Pet insurance penetration remains uneven across state-level markets, with out-of-pocket payment requirements limiting protocol adherence among price-sensitive owner segments.
Strategic Opportunities
- Feline Mast Cell Neoplasia Underservice:Feline cutaneous and visceral mast cell disease represents a substantially untreated population, with no approved targeted therapies currently addressing this species segment.
- Adjuvant Immunotherapy Protocols:Post-surgical tumor vaccine platforms, regulated under USDA APHIS veterinary biologics pathways, offer margin expansion through recurring administration schedules.
- Telemedicine-Enabled Triage:Remote oncology consultation platforms are compressing referral timelines, accelerating patient enrollment into specialty therapeutic protocols before disease progression.
Industry Challenges
- Veterinary Oncologist Workforce Scarcity:Board-certified specialists remain concentrated in coastal metropolitan corridors, creating access bottlenecks that limit protocol adoption in interior markets.
- Cross-Species Formulation Complexity:Palatability engineering for oral tablets across divergent canine breed sizes and feline administration resistance demands specialized excipient development capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mast Cell Tumors Treatment Market |
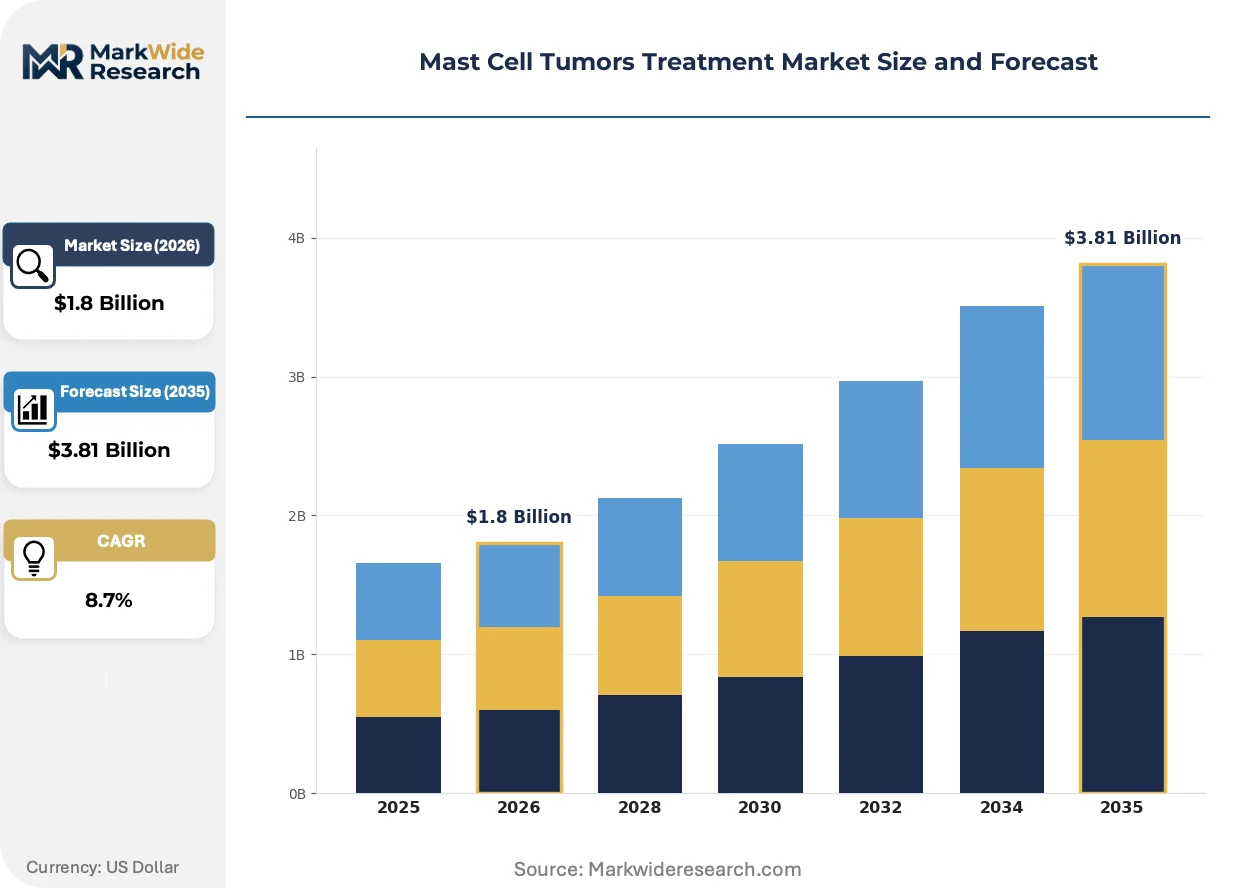
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Steroids, Chemotherapy, Immunotherapy Administration Route: Oral, Injectable, Topical, Subcutaneous End User: Veterinary Clinics, Animal Hospitals, Home Care, Research Labs Treatment Stage: Adjuvant Therapy, Palliative Care, Primary Treatment, Post-Operative Care |
| Companies Covered | Boehringer Ingelheim, Novartis, Merck & Co., Pfizer, Eli Lilly and Company, Bristol-Myers Squibb, Amgen, Bayer, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mast Cell Tumors Treatment Market Strategic Shifts
Targeted molecular therapies are supplanting cytotoxic chemotherapy as the foundational approach to mast cell neoplasia management, while regulatory convergence and owner behavioral shifts reshape how value is captured across the treatment continuum.
Liquid biopsy platforms detecting circulating tumor DNA are displacing repeat surgical biopsies for treatment monitoring, enabling serial assessment of clonal evolution without anesthesia exposure. Specialty practices in the United States and Western Europe are integrating these diagnostics into standard-of-care protocols. This displacement is compressing the addressable market for histopathology services while expanding recurring revenue pools for molecular diagnostics laboratories.
EMA's Committee for Medicinal Products for Veterinary Use has harmonized centralized authorization standards for novel animal drugs, reducing duplicate filing requirements across EU member states. This regulatory convergence is accelerating market access for kinase inhibitors seeking European commercialization. Manufacturers are responding by prioritizing centralized European submissions alongside FDA Center for Veterinary Medicine filings.
Pet owner purchasing behavior is gravitating toward subscription-based medication delivery, with oral oncology therapeutics increasingly dispensed through veterinary-exclusive online pharmacies. This channel shift is disintermediating traditional wholesale distributors and compressing margin capture for hospital-based dispensing. The transformation is most pronounced in United States markets where specialty pharmacy networks have achieved veterinary accreditation.
Mast Cell Tumors Treatment Market Segmentation
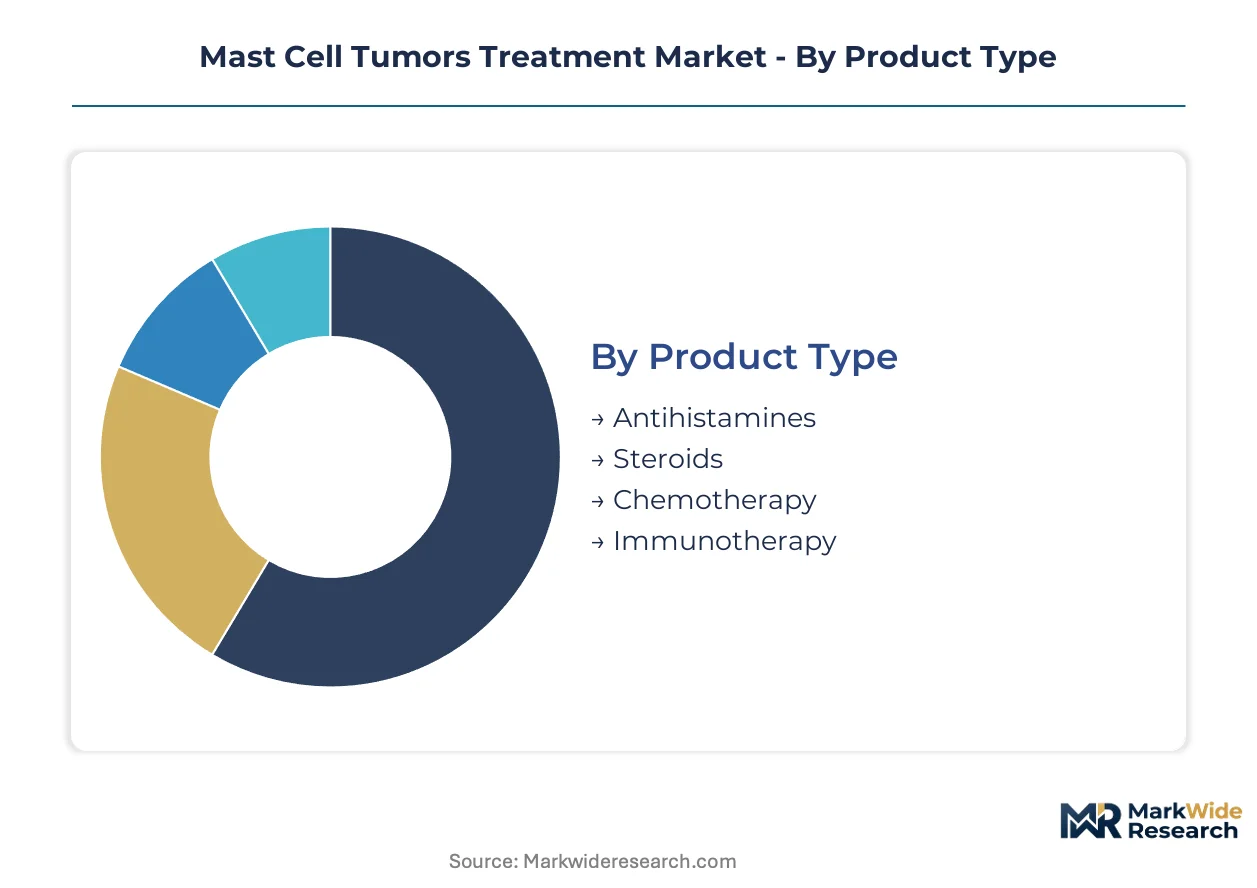
Mast cell tumor therapeutics distribute through divergent channel architectures depending on product form and clinical setting. Understanding segment-channel alignment reveals where margin pools concentrate and which administration formats capture outpatient versus institutional demand.
Product Type:
Channel access determines commercial priority across therapeutic modalities, with oral formulations penetrating retail pharmacy networks while biologics remain captive to hospital dispensing.
- Antihistamines:First-line symptomatic control agents targeting histamine-mediated pruritus and gastrointestinal distress. Companion animal practices in the United States prescribe diphenhydramine and famotidine protocols most heavily in suburban metropolitan corridors where owner compliance monitoring is feasible.
- Steroids:Corticosteroid protocols reduce peritumoral inflammation and modulate mast cell degranulation. Prednisone tablets dominate outpatient dispensing through veterinary-exclusive online pharmacies, displacing hospital-based medication sales.
- Chemotherapy:Cytotoxic regimens including vinblastine and lomustine target rapidly dividing neoplastic populations. Specialty referral hospitals in coastal California and New York metropolitan areas retain protocol control due to therapeutic monitoring requirements.
- Immunotherapy:Tumor vaccine platforms and checkpoint modulators represent the steepest expansion trajectory as USDA APHIS regulatory pathways mature for veterinary biologics commercialization.
Antihistamines dominate installed base. Immunotherapy is where expansion concentrates.
Administration Route:
Cost tier stratification separates premium hospital-administered injectables from economy oral generics, with subcutaneous formats capturing mid-tier positioning.
- Oral:Tablet and capsule formulations of tyrosine kinase inhibitors and corticosteroids. Toceranib phosphate tablets achieve highest owner adherence in United States markets where specialty pharmacy networks have achieved veterinary accreditation.
- Injectable:Intravenous chemotherapy and supportive care agents requiring anesthesia and monitoring. University veterinary teaching hospitals in Texas, Florida, and Pennsylvania anchor institutional demand for this route.
- Topical:Limited application for cutaneous mast cell tumor palliation, primarily intralesional triamcinolone injections.
- Subcutaneous:Emerging delivery format for depot formulations and monoclonal antibody candidates, bridging hospital oversight with reduced visit frequency.
Oral administration commands volume leadership. Subcutaneous delivery is gaining share fastest among novel biologics.
End User:
Customer type fragmentation concentrates high-margin therapeutics in institutional settings while commoditized agents flow through general practice.
- Veterinary Clinics:Primary care gatekeepers managing initial diagnosis and referral triage. General practices in the United States Midwest and Southeast handle the majority of first-line antihistamine and corticosteroid prescribing.
- Animal Hospitals:Specialty oncology centers administering chemotherapy protocols and targeted kinase inhibitors. These facilities capture premium pricing for immunotherapy enrollment and therapeutic monitoring services.
- Home Care:Owner-administered oral maintenance protocols following hospital induction. This segment expands as palatability engineering improves across canine breed size variation.
- Research Labs:Academic and contract research organizations conducting pharmacokinetic and efficacy studies for novel therapeutic candidates.
Animal hospitals dominate revenue per patient. Home care is where volume scaling concentrates.
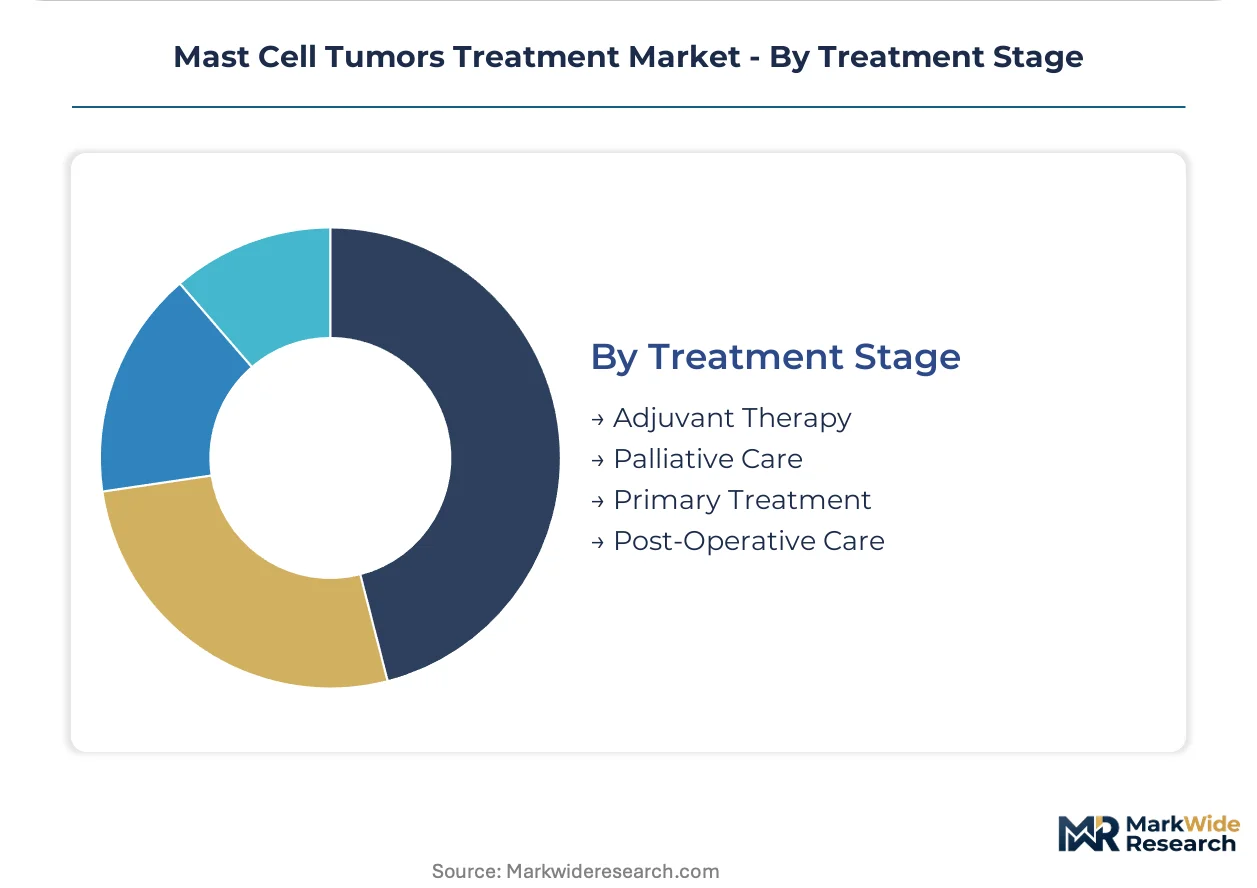
Treatment Stage:
Maturity differentiation separates established adjuvant protocols from emerging palliative modalities, with primary treatment representing the most contested positioning.
- Adjuvant Therapy:Post-surgical protocols reducing recurrence risk following complete excision. Kinase inhibitor maintenance regimens concentrate in United States specialty networks with board-certified surgical oncologists.
- Palliative Care:Quality-of-life focused management of metastatic or unresectable disease. This stage captures expanding margin pools as pet owners demonstrate willingness to absorb premium pricing for durable remission.
- Primary Treatment:Neoadjuvant cytoreduction or definitive therapy for localized disease. Oral tyrosine kinase inhibitors displace cytotoxic chemotherapy as first-line targeted approaches in metropolitan referral centers.
- Post-Operative Care:Wound management and surveillance protocols following tumor excision, overlapping with adjuvant therapeutic decision points.
Primary treatment commands protocol initiation volume. Palliative care is where pricing power expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States specialty referral networks while European markets operate under tighter reimbursement constraints. This asymmetry shapes where novel kinase inhibitors achieve first commercial traction and where manufacturers prioritize launch sequencing.
United States
Pet insurance penetration exceeds forty percent in metropolitan coastal corridors, enabling premium absorption for oral tyrosine kinase protocols. FDA Center for Veterinary Medicine conditional approval mechanisms compress regulatory timelines for KIT receptor antagonists. University veterinary teaching hospitals in Texas, Florida, and Pennsylvania anchor clinical trial enrollment and therapeutic protocol standardization.
Germany
Specialty small animal oncology practices concentrate in North Rhine-Westphalia and Bavaria, driving demand for precision therapeutics. EMA Committee for Medicinal Products for Veterinary Use centralized authorization reduces duplicate filing burdens across EU member states. Munich and Berlin metropolitan clusters host the majority of board-certified veterinary oncologists conducting biomarker-guided patient selection.
United Kingdom
Referral hospital networks in London and the Southeast capture disproportionate oncology case volume relative to national pet population. The Veterinary Medicines Directorate aligns with EMA centralized procedures while maintaining national pharmacovigilance requirements. The Animal Health Trust in Newmarket anchors translational research bridging human and veterinary oncology pipeline assets.
Japan
Companion animal expenditure concentrates in Tokyo and Osaka metropolitan corridors with elevated willingness-to-pay for durable remission protocols. PMDA veterinary pharmaceutical review divisions coordinate with METI on cross-species drug development incentives. The Japan Veterinary Oncology Society in Kansai region standardizes treatment algorithms and drives adoption of targeted molecular therapies.
France
Specialty veterinary oncology capacity clusters in Île-de-France and Auvergne-Rhône-Alpes, supporting advanced therapeutic protocol penetration. ANSM veterinary product authorization pathways operate within EMA harmonized frameworks while maintaining national prescribing controls. Lyon and Paris academic veterinary hospitals conduct the majority of pharmacokinetic bridging studies for species-specific formulation development.
Mast Cell Tumors Treatment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated pharmaceutical conglomerates commanding novel biologic development and mid-tier specialists capturing manufacturing efficiency. Market structure concentrates around three to five dominant sponsors with established veterinary divisions, while fragmented regional distributors handle last-mile dispensing. Two strategic archetypes predominate: human oncology pipeline repurposers leveraging cross-species kinase platforms, and dedicated animal health operators with species-specific formulation expertise. Competitive dynamics center on portfolio diversification into feline indications and strategic partnerships with specialty pharmacy networks.
Within the human-oncology repurposer archetype, Boehringer Ingelheim and Novartis occupy anchor positions, each representing distinct approaches to cross-species therapeutic translation. Boehringer Ingelheim exemplifies integrated animal health division structures that sustain development pipelines from human pharmaceutical spillover. Novartis sits within the targeted kinase inhibitor specialization, drawing on platforms originally validated in human medicine. Merck & Co. represents the checkpoint inhibitor research extension model, applying immuno-oncology capabilities into veterinary applications. These three conglomerates collectively shape regulatory engagement patterns and pricing benchmarks across United States and European markets.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Novartis |
| Merck & Co. |
| Pfizer |
| Eli Lilly and Company |
| Bristol-Myers Squibb |
| Amgen |
| Bayer |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Oral tyrosine kinase inhibitor tablet formulations displacing injectable chemotherapy protocols simultaneously shift manufacturing toward contract pharmaceutical sites in India and China while compressing per-dose pricing through reduced anesthesia and hospital visit requirements. This substitution dynamic redistributes margin capture from specialty referral hospitals toward veterinary-exclusive online pharmacy networks.
Pricing Analysis
The customization-premium spread between compounded palatability-engineered tablets and standard generic kinase inhibitors spans roughly three-to-one in United States metropolitan markets. Subscription-based medication delivery through accredited specialty pharmacies now dominates the pricing model, with price differentiation resting on c-KIT mutation biomarker certification tier and after-sales therapeutic monitoring bundling. Cost compression in standard oral generics is intensifying because of Indian API manufacturer overcapacity, while price-insensitive owners in coastal specialty hospital networks absorb premium pricing for personalized immunotherapy protocols.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Mumbai pharmaceutical hubs through Los Angeles and Rotterdam container terminals have exposed veterinary kinase inhibitor sponsors to rolling port congestion surcharges. Active pharmaceutical ingredient manufacturing concentrates in India and China, with formulation finishing distributed across United States and European Union secondary processing facilities. Raw material dependencies span toceranib phosphate intermediates, gelatin capsule shells, and species-specific flavor masking excipients. Single-source vulnerability in Chinese KIT receptor antagonist precursor synthesis threatens continuity, while distribution runs through veterinary-exclusive online pharmacy networks disintermediating traditional wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USDA APHIS streamlined approval pathways for veterinary biologics have compressed development timelines below human oncology benchmarks, creating a high-growth disruption window for immunotherapy platform sponsors.
For Market Incumbents: Shield proprietary kinase inhibitor market share through backward integration into Indian API manufacturing and captive supply of c-KIT mutation diagnostic testing. Board-certified veterinary oncologist workforce scarcity in interior United States markets threatens protocol standardization, making channel control through specialty hospital network partnerships the priority defensive lever.
For New Entrants and Emerging Players: FDA Center for Veterinary Medicine conditional approval fast-track offers regulatory entry velocity unmatched in human pharmaceutical markets. Feline mast cell neoplasia represents substantially white-space territory with no approved targeted therapies, while telemedicine-enabled remote oncology consultation platforms provide the most penetrable go-to-market angle for bypassing coastal specialist concentration.
For Investors and Strategic Acquirers: The market sits at a platform-expansion phase that favors human-oncology repurposers with species-specific formulation capabilities. Long-term viability over the next decade hinges on portfolio diversification into feline indications and immunotherapy adjuvant protocols. The signal to watch is USDA APHIS veterinary biologics approval velocity as inflection indicator for margin pool migration from small-molecule inhibitors toward tumor vaccine platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| USDA APHIS Veterinary Biologics Approval | Accelerates commercialization timelines for canine tumor vaccine candidates beyond FDA drug pathways. |
| Specialty Pharmacy Network Partnership | Captures recurring revenue through subscription-based oral oncology therapeutic delivery. |
| c-KIT Mutation Diagnostic Integration | Enables precision patient selection that expands addressable populations for kinase inhibitors. |
| Feline Indication Pipeline Expansion | Addresses substantially untreated species segment with no approved targeted therapies currently. |
| Telemedicine-Enabled Referral Compression | Accelerates patient enrollment into specialty protocols before disease progression limits options. |
Study Parameters
Operator-level perspectives from veterinary oncologists, specialty hospital pharmacy directors, pet insurance underwriting leads, and USDA APHIS regulatory affairs specialists anchored the qualitative base. Secondary validation drew from FDA Center for Veterinary Medicine drug approval databases, EMA Committee for Medicinal Products for Veterinary Use centralized authorization records, and companion animal practice management software utilization statistics. Bottom-up protocol adoption modeling triangulated against top-down pharmaceutical sponsor revenue disclosures.
Sensitivity analysis tested forecast robustness across alternative pet insurance penetration scenarios and regulatory approval timeline compressions. Segmentation dimensions spanned product type, administration route, end user facility tier, and treatment stage maturity. CAGRs were derived from iterative reconciliation of historical protocol adoption curves with projected biomarker-guided patient selection expansion. Species-specific pharmacokinetic bridging study requirements and veterinary oncologist workforce geographic concentration served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained pet owner willingness-to-pay for durable remission and stable FDA-EMA regulatory convergence assumptions; material deviation in either would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Refsum Disease Treatment Market
Medical Treatment
Angioedema Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Cephalic Disorders Treatment Market
Medical Treatment
Liver Transplantation Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Menopause Treatment Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Endovenous Laser Therapy Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
Nontuberculous Mycobacterium Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Global Nano Therapy Market