
 Nasopharyngeal Carcinoma Treatment Market | 2026-2036
Nasopharyngeal Carcinoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Nasopharyngeal Carcinoma Treatment Market Foresight
China is narrowing its radiotherapy equipment gap through provincial hospital upgrades and dedicated proton center construction. Pfizer Inc. leverages its kinase inhibitor portfolio to sustain positioning in recurrent disease settings. Merck & Co., Inc. anchors immuno-oncology penetration through checkpoint inhibitor access programs across Asia-Pacific. Bristol Myers Squibb competes on combination regimen data, differentiating its PD-1 assets in frontline protocols.
Nasopharyngeal carcinoma treatment encompasses multimodal therapeutic interventions targeting malignant epithelial tumors arising in the nasopharyngeal mucosa, typically combining platinum-based chemotherapy with intensity-modulated radiotherapy to preserve adjacent cranial nerve function while achieving locoregional control. Its primary purpose centers on improving overall survival in populations with high Epstein-Barr virus seroprevalence, particularly where undifferentiated non-keratinizing histology predominates. Immunotherapy segments lead investment intensity as PD-1 inhibitors reshape first-line standards, with intravenous delivery modes capturing the dominant administration share due to infusion monitoring requirements in hospital settings. Targeted therapy segments occupy narrower but higher-margin positions where EGFR or VEGF pathway inhibition offers salvage options after platinum failure.
FDA orphan drug designations and EMA accelerated assessment pathways shape development priorities for sponsors targeting this indication, while China's NMPA conditional approval framework enables earlier patient access based on single-arm Phase II data. REACH compliance and ISO 13485 quality management standards govern biologic manufacturing scale-up for regional supply security. Stakeholders must monitor biomarker-driven patient selection criteria and radiotherapy fractionation innovations to align portfolio priorities with evolving standard-of-care definitions.
Market Dynamics
PD-1 inhibitor biosimilars approved under China's NMPA accelerated pathway are compressing pricing premiums and forcing originators to defend positioning through combination regimen differentiation rather than monotherapy dominance.
Growth Catalysts
- Intensity-modulated radiotherapy (IMRT) diffusion:Provincial hospital upgrades across Guangdong Province are expanding curative-intent treatment capacity for locally advanced disease. Equipment procurement cycles favor linear accelerator vendors with integrated planning software.
- EBV DNA plasma monitoring:Circulating tumor DNA assays are enabling risk-stratified adjuvant therapy decisions. Diagnostic laboratories in high-incidence clusters are validating liquid biopsy protocols for post-treatment surveillance.
- REACH compliance harmonization:European biologic manufacturing standards are streamlining cross-border supply security for checkpoint inhibitor production. Contract manufacturers are consolidating quality management systems under unified ISO 13485 certification.
Market Restraints
- Platinum supply concentration:Cisplatin and carboplatin active pharmaceutical ingredient production clusters in India create single-source vulnerability for chemotherapy backbone regimens.
- Proton center capex thresholds:Dedicated particle therapy facilities require $150-300 million capital commitments with decade-long depreciation horizons, limiting deployment to tertiary referral centers.
- Radiation oncologist training pipelines:Fellowship completion rates in Southeast Asia lag facility expansion plans, creating treatment planning bottlenecks at newly commissioned centers.
Strategic Opportunities
- salvage immunotherapy protocols:Patients progressing after platinum-based chemoradiation represent an addressable population for PD-1 inhibitor retreatment with radiotherapy re-irradiation.
- Artificial intelligence contouring:Deep learning algorithms for organs-at-risk segmentation are reducing planning time from hours to minutes. Academic medical centers are licensing these tools to community radiation oncology practices.
- ASEAN referral network formalization:Cross-border patient flows from Indonesia and Vietnam to Singapore and Thailand treatment centers are creating demand for standardized clinical trial eligibility and insurance pre-authorization pathways.
Industry Challenges
- Adaptive trial design execution:Master protocol studies with embedded biomarker cohorts require biostatistical expertise scarce in regional contract research organizations.
- Cold chain integrity for biologics:Checkpoint inhibitor temperature excursions during last-mile distribution to tropical climate clinics risk potency degradation and pharmacovigilance reporting obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasopharyngeal Carcinoma Treatment Market |
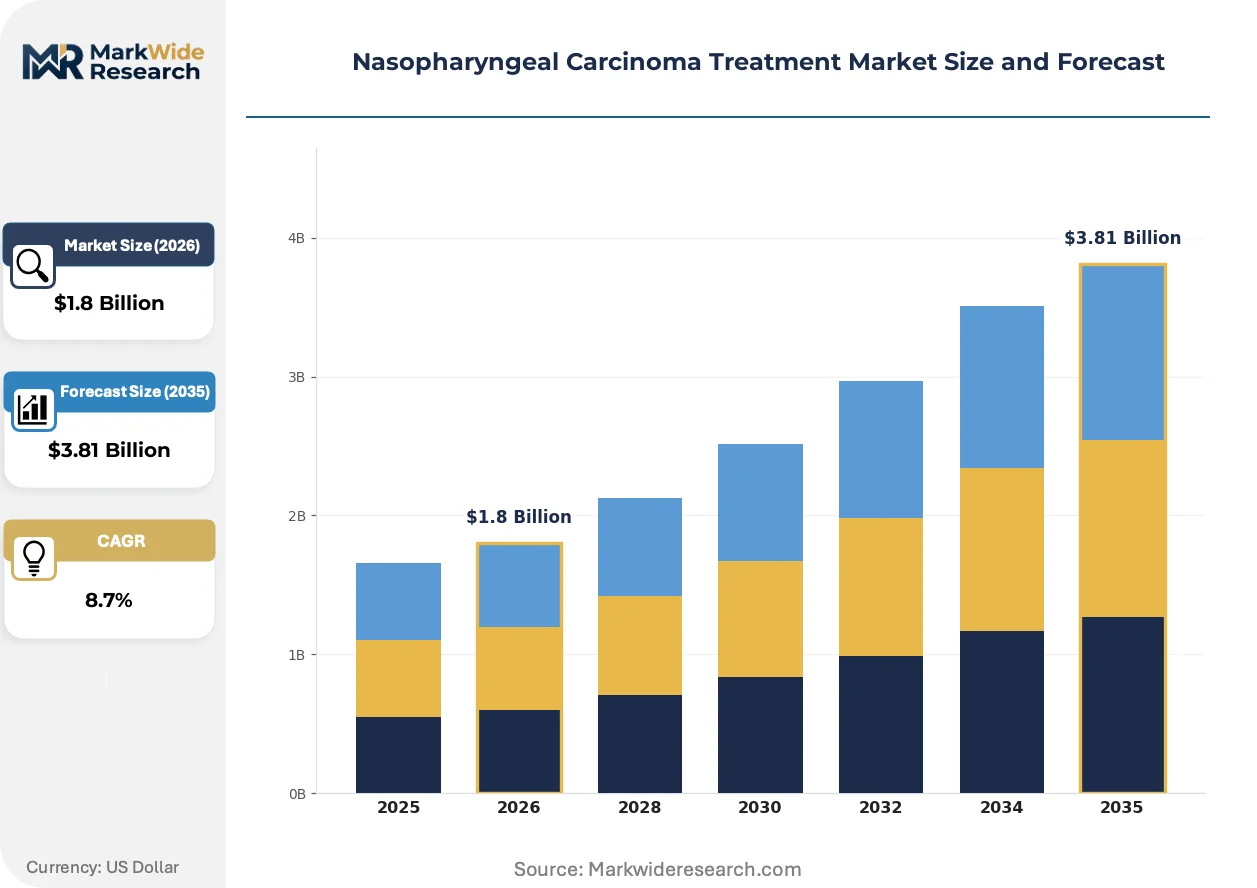
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiotherapy, Immunotherapy, Targeted Therapy Delivery Mode: Intravenous, Oral, Subcutaneous, Intranasal End User: Hospitals, Oncology Clinics, Research Institutions, Home Care Application: Treatment, Palliative Care, Research, Clinical Trials |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Sanofi, Eli Lilly and Company, Teva Pharmaceutical Industries Ltd., F. Hoffmann-La Roche Ltd, Bristol Myers Squibb, Novartis AG, Junshi Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasopharyngeal Carcinoma Treatment Market Shifts & Advancements
Artificial intelligence applications are penetrating treatment planning and response assessment workflows, compressing specialist labor requirements while raising validation standards for algorithmic decision support.
Magnetic resonance-guided radiotherapy (MRgRT) is virtualizing daily adaptive replanning by enabling soft-tissue visualization during beam delivery. Major cancer centers in Guangzhou and Singapore are commissioning MR-linac systems for nasopharyngeal target tracking. This capability is compressing planning target volume margins and reducing parotid gland toxicity rates.
China's NMPA conditional approval framework is enabling earlier patient access based on single-arm Phase II data with post-marketing confirmatory requirements. Sponsors are restructuring development timelines to prioritize Asian enrollment for global registration packages. The framework is accelerating biosimilar entry for PD-1 inhibitors and reshaping competitive dynamics in frontline therapy.
Hospital procurement consortia in Southeast Asia are consolidating radiotherapy equipment purchasing through centralized tender processes. Single-source contracting for linear accelerator maintenance and software upgrades is displacing fragmented vendor relationships. Thailand's universal coverage scheme and Vietnam's social health insurance program are the primary channels where this consolidation is visible.
Nasopharyngeal Carcinoma Treatment Market Segmentation
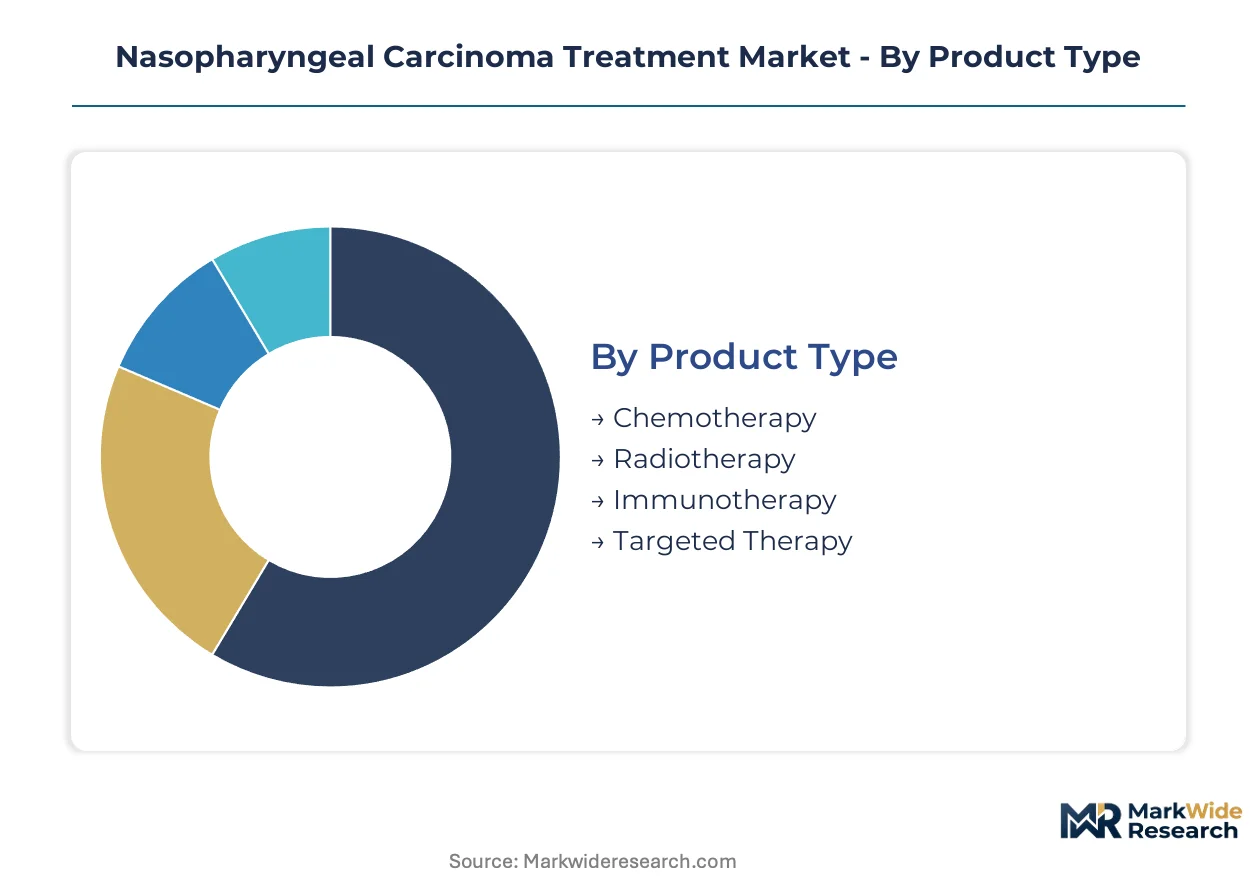
Treatment modality selection in nasopharyngeal carcinoma hinges on histology, EBV status, and cranial nerve involvement patterns. Segmentation reveals where capital investment concentrates versus where biological innovation reshapes clinical protocols.
Product Type:
Use-case spectrum spans curative-intent multimodal regimens through salvage interventions for platinum-refractory disease.
- Chemotherapy:Platinum-based doublets remain the systemic backbone for locally advanced disease, with cisplatin-gemcitabine protocols dominating Guangdong Province treatment centers. Demand concentrates in provincial hospitals where radiotherapy capacity constraints extend chemotherapy windows.
- Immunotherapy:PD-1 checkpoint inhibitors are displacing chemotherapy in frontline metastatic settings through NMPA accelerated approvals. Guangzhou and Singapore academic centers drive adoption through biomarker-enriched trial enrollment.
- Radiotherapy:Intensity-modulated techniques with simultaneous integrated boost achieve parotid-sparing dose distributions.
- Targeted Therapy:EGFR and VEGF pathway inhibitors serve salvage indications after platinum progression.
The dominant share belongs to Chemotherapy, while Immunotherapy is closing the gap fastest.
Delivery Mode:
Route selection reflects institutional monitoring capabilities and patient ambulatory status across treatment phases.
- Intravenous:Infusion suites in tertiary oncology centers administer checkpoint inhibitors with mandatory cardiac and pulmonary monitoring. Hospital procurement consortia in Thailand and Vietnam standardize pump specifications and tubing sets.
- Oral:Tyrosine kinase inhibitors enable outpatient maintenance after initial response, with pharmacy benefit managers in Singapore managing prior authorization workflows.
- Subcutaneous:Reduced infusion time appeals to capacity-constrained day units.
- Intranasal:Investigational locoregional delivery targets residual mucosal disease.
Intravenous administration holds the largest volume share, though Oral routes are expanding most quickly as kinase inhibitors penetrate adjuvant settings.
End User:
Site-of-care decisions balance technical sophistication against patient travel burden in high-incidence clusters.
- Hospitals:Academic medical centers in Guangzhou, Singapore, and Bangkok perform complex re-irradiation and salvage surgery. Equipment procurement cycles favor vendors with integrated planning software and physics support.
- Oncology Clinics:Community-based radiation oncology practices handle definitive chemoradiation for early-stage disease. Linear accelerator upgrades across Guangdong Province expand curative-intent capacity.
- Research Institutions:Master protocol studies with embedded biomarker cohorts require biostatistical expertise.
- Home Care:Oral targeted therapy administration shifts monitoring to telemedicine platforms.
Hospitals command the dominant share, while Oncology Clinics are gaining share fastest through provincial network expansion.
Application:
Clinical purpose determines reimbursement pathway and regulatory evidence requirements.
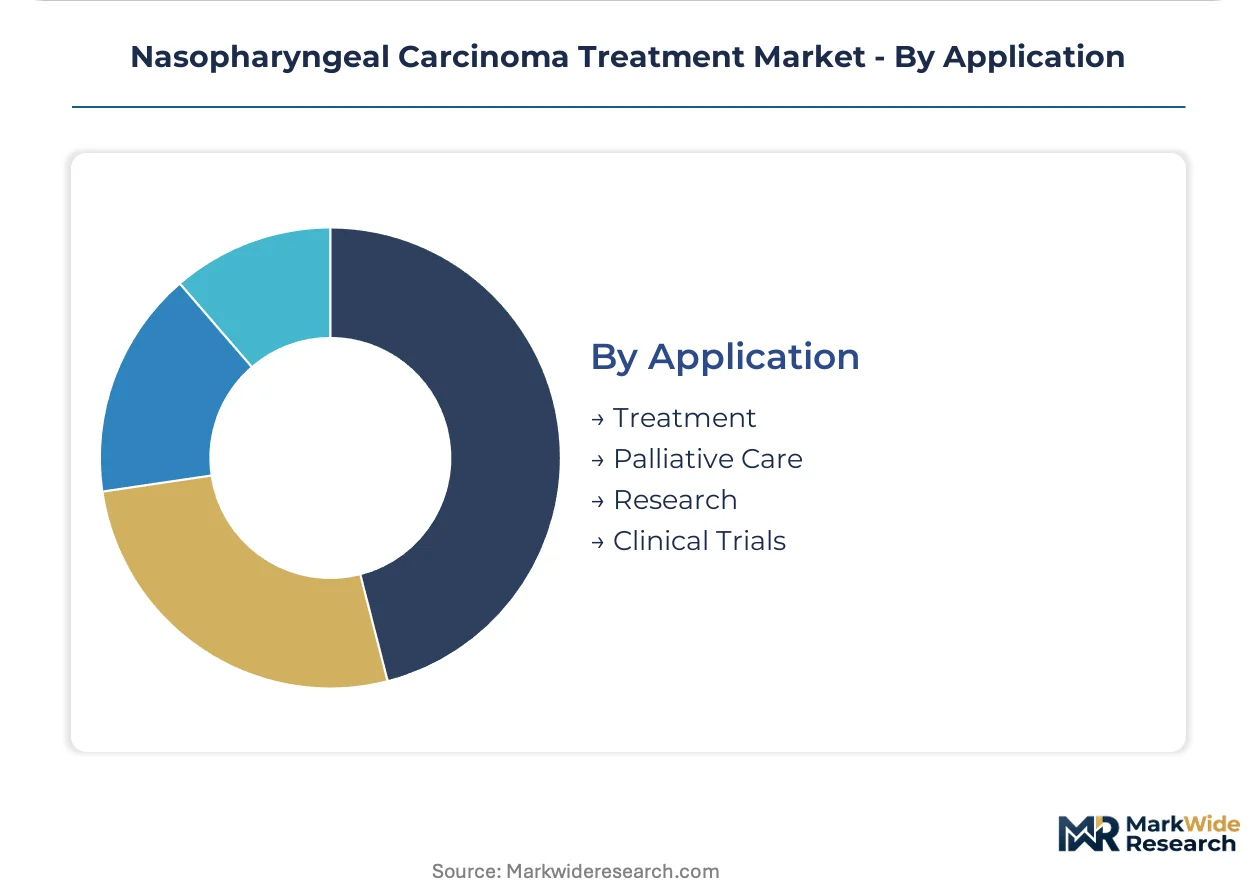
- Treatment:Definitive chemoradiation with or without adjuvant chemotherapy achieves locoregional control in non-metastatic disease. EBV DNA plasma monitoring guides adjuvant therapy intensity decisions.
- Clinical Trials:Single-arm Phase II designs under NMPA conditional approval accelerate access for novel combinations. Sponsors prioritize Asian enrollment for global registration packages.
- Palliative Care:Symptom-directed radiotherapy addresses bleeding and pain from recurrent disease.
- Research:Circulating tumor DNA assay validation supports post-treatment surveillance protocols.
Treatment applications dominate expenditure, while Clinical Trials are climbing the fastest as conditional approval frameworks reshape development timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between high-incidence Asian clusters where curative-intent multimodal therapy dominates and Western markets where salvage protocols and clinical trial enrollment concentrate. The former deploys platinum-based chemoradiation as first-line standard; the latter prioritizes immunotherapy access through expanded access programs and academic referral networks.
China
Guangdong Province drives Asia-Pacific treatment volume through EBV-associated disease clustering and provincial hospital network expansion. NMPA conditional approval frameworks accelerate PD-1 inhibitor access based on single-arm Phase II data. Guangzhou academic medical centers anchor proton therapy commissioning and MR-linac adoption for adaptive replanning.
Singapore
The city-state functions as a regional referral hub for Indonesian and Vietnamese patients seeking definitive chemoradiation. MOH reimbursement pathways prioritize intensity-modulated techniques with simultaneous integrated boost protocols. National Cancer Centre Singapore leads ASEAN master protocol enrollment for biomarker-driven immunotherapy combinations.
United States
FDA orphan drug designations shape sponsor development priorities for this rare indication, with academic centers in California and Massachusetts driving salvage immunotherapy trial density. NCI-designated cancer centers concentrate re-irradiation expertise for platinum-refractory populations. Medicare coverage determinations for circulating tumor DNA monitoring influence adjuvant therapy intensity decisions.
Thailand
Universal coverage scheme procurement consolidates linear accelerator purchasing through centralized hospital consortia. Bangkok's tertiary oncology network handles definitive chemoradiation for locally advanced disease from provincial catchment areas. Social security reimbursement pathways are expanding PD-1 inhibitor access for metastatic first-line settings.
Japan
PMDA Sakigake designation pathways accelerate review for combination regimens targeting recurrent disease. Tokyo and Osaka academic centers specialize in re-irradiation protocols for nasopharyngeal salvage. National health insurance pricing negotiations for biosimilar checkpoint inhibitors are compressing originator premiums in frontline metastatic care.
Nasopharyngeal Carcinoma Treatment Market Competitive Landscape
Capability concentration sits with large-cap pharmaceutical developers possessing integrated oncology portfolios; scale advantage sits with regional biosimilar manufacturers exploiting accelerated regulatory pathways. The market structure reflects a bifurcation between originators defending frontline positioning through combination regimen differentiation and emerging players capturing share through price-access strategies. Two archetypes dominate: diversified oncology majors with kinase inhibitor and checkpoint inhibitor assets, and Asia-Pacific biotech specialists leveraging NMPA conditional approval frameworks. Competitive moves center on M&A for radiotherapy-immunotherapy combination assets and strategic partnerships for circulating tumor DNA diagnostic co-development.
Among diversified pharmaceutical majors, Pfizer Inc., Merck & Co., Inc., and Bristol Myers Squibb exemplify contrasting strategic postures. Pfizer occupies a position anchored in small-molecule kinase inhibition for recurrent disease settings. Merck exemplifies the checkpoint inhibitor access-program archetype across Asia-Pacific markets. Bristol Myers Squibb represents combination regimen differentiation through PD-1 asset positioning in frontline protocols. These three entities collectively illustrate how originator strategies diverge between molecule-class defense and regimen-complexity expansion.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Sanofi |
| Eli Lilly and Company |
| Teva Pharmaceutical Industries Ltd. |
| F. Hoffmann-La Roche Ltd |
| Bristol Myers Squibb |
| Novartis AG |
| Junshi Biosciences |
| Others |
Supply & Pricing Matrix
Platinum API production concentration in India creates single-source vulnerability that compresses chemotherapy backbone margins while forcing hospital procurement consortia toward multi-year offtake contracts. This dependency structure simultaneously widens price spreads between originator immunotherapy and biosimilar tiers while reshaping regional inventory positioning across Southeast Asia.
Pricing Analysis
Guangdong Province treatment centers command 15-25% premiums over provincial hospital networks for IMRT protocols with integrated boost capability. Pricing stratifies across premium, standard, and economy tiers based on equipment vendor brand and physics support bundling. Cost compression in the chemotherapy segment is intensifying because NMPA-accelerated PD-1 biosimilars are eroding originator premiums in frontline metastatic care. Community oncology clinics exhibit highest price sensitivity due to capital constraints on linear accelerator procurement.
Supply Chain Analysis
Tariff exposure between India and China dominates active pharmaceutical ingredient flow security for platinum-based regimens. Cisplatin and carboplatin API manufacturing clusters in India, China, and South Korea feed formulation facilities across Guangdong and Singapore. Cold chain integrity for checkpoint inhibitors hinges on last-mile distribution partnerships with temperature-validated logistics providers in tropical climate zones. Distribution runs through hospital procurement consortia in Thailand and Vietnam with centralized tender processes displacing fragmented vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nasopharyngeal carcinoma treatment market sits at a platform-economics inflection where MR-linac interoperability standards and EBV DNA assay integration are consolidating technical ecosystems around adaptive radiotherapy workflows.
For Market Incumbents: Entrench positioning through backward integration into circulating tumor DNA diagnostic co-development and proton center joint ventures in Guangzhou and Singapore. Pfizer's kinase inhibitor portfolio defense against PD-1 combination encroachment requires accelerated biomarker-enriched trial enrollment. NMPA conditional approval pathway exploitation by Junshi Biosciences and regional biotech specialists threatens originator frontline share. For New Entrants and Emerging Players: Build out salvage immunotherapy retreatment protocols for platinum-refractory populations as the most penetrable white space, with artificial intelligence contouring tools for community radiation oncology practices as secondary entry vector. Indonesia and Vietnam patient referral flows to Bangkok and Singapore centers create demand for standardized insurance pre-authorization platforms. Partner with ASEAN academic medical centers for master protocol enrollment access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors radiotherapy-immunotherapy combination asset holders with NMPA approval track records. Long-term viability centers on adaptive trial execution capabilities and biostatistical expertise scarcity in regional CROs. Watch for MR-linac commissioning announcements in Guangdong as inflection signal for technical leadership shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Single-arm Phase II designs under NMPA conditional approval accelerate patient access timelines. |
| Manufacturing Scale-Up | ISO 13485 certification consolidation streamlines checkpoint inhibitor cross-border supply security. |
| Regulatory Approval Pathway | PMDA Sakigake designations in Japan accelerate combination regimen review for recurrent disease. |
| Strategic Partnership | AI contouring licensing agreements reduce planning time for community radiation oncology practices. |
| Pipeline Diversification | EGFR and VEGF pathway inhibitor development addresses salvage indications after platinum progression. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA orphan drug filings, EMA accelerated assessment pathways, ClinicalTrials.gov enrollment data, and NMPA conditional approval records. Oncology drug development executives, hospital procurement managers at Guangdong provincial networks, regulatory affairs leads, and payer access specialists provided structured input. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored value estimates.
Forecast inputs span treatment modality adoption curves, radiotherapy equipment procurement cycles, and immunotherapy biosimilar penetration rates across the projection horizon. Segmentation dimensions include product type, delivery mode, end user, and application with regional regulatory cluster overlays. CAGRs derive from historical procedure volume trends and pricing trajectory analysis. EBV DNA plasma monitoring diffusion rates and MR-linac commissioning schedules served as industry-specific forecast inputs.
Stress conditions across platinum API supply disruption, NMPA approval pathway delays, and proton center capital commitment failures were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding biomarker-driven patient selection criteria adoption. Material shifts in China's dual carbon goals affecting hospital energy infrastructure or ASEAN cross-border reimbursement harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Sepsis Treatment Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Surgical Procedures Volume Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Global Leishmaniasis Treatment Market
Medical Treatment
Precocious Puberty Treatment Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Celiac Disease Treatment Market
Medical Treatment
Global Plasma Therapy Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market
Medical Treatment
Burns Treatment Market
Medical Treatment
House Dust Mite Allergy Treatment Market