
 Hemorrhagic Shock Treatment Market | 2026-2036
Hemorrhagic Shock Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hemorrhagic Shock Treatment Market Outlook
Specialized trauma surgery and critical care nursing capacity is redrawing competitive boundaries in hemorrhagic shock therapeutics. F. Hoffmann-La Roche Ltd leverages its diagnostics-to-therapeutics pipeline to anchor hospital protocol integration. Boehringer Ingelheim International GmbH sustains R&D intensity in coagulation science, while Johnson & Johnson Services Inc. controls surgical hemostasis portfolios that complement fluid resuscitation workflows. NuvOx Pharma LLC specializes in oxygen therapeutic platforms, occupying a distinct technology niche against conventional volume expanders.
Hemorrhagic shock treatment encompasses fluid resuscitation, hemostatic agents, blood component therapy, and vasopressor support administered to restore tissue perfusion following acute blood loss exceeding circulatory compensatory capacity. Crystalloid and colloid solutions serve as first-line volume expanders, though blood products command premium positioning where hemorrhage severity demands oxygen-carrying capacity restoration. Blood products capture the dominant margin pool due to supply chain complexity and stringent cold-chain requirements, while intravenous delivery mode dominates procedural standardization across emergency departments and trauma centers. Military medical units represent the most structurally constrained segment, with battlefield requirements driving compact formulation and extended shelf-life innovation.
FDA blood product guidance, EMA advanced therapy medicinal product frameworks, and WHO emergency essential medicines lists collectively shape product registration pathways and reimbursement thresholds for novel resuscitation therapies. Regulatory stringency around pathogen reduction and compatibility testing elevates barriers for substitute fluid entrants while reinforcing incumbent blood banking infrastructure. Stakeholders must monitor evolving damage control resuscitation protocol adoption across civilian trauma networks and assess how oxygen-carrying substitute candidates navigate pivotal efficacy thresholds without traditional transfusion infrastructure.
Market Dynamics
Damage control resuscitation protocols are compressing the therapeutic window for hemorrhagic shock interventions, forcing manufacturers to integrate diagnostics, hemostatics, and oxygen therapeutics into unified emergency workflows rather than standalone product categories.
Growth Catalysts
- Level I Trauma Network Expansion:Civilian hospital systems in the United States are replicating military damage control resuscitation protocols, creating procurement pull for integrated blood product and hemostatic portfolios.
- FDA Blood Product Substitute Guidance:Accelerated clinical trial pathways for oxygen-carrying volume expanders are redirecting R&D investment toward shelf-stable alternatives to refrigerated blood components.
- Prehospital Tourniquet-to-Transfusion Continuity:Emergency medical services are extending hemorrhage control timelines, expanding addressable demand for point-of-injury hemostatic dressings and field-deployable resuscitation systems.
Market Restraints
- Plasma Supply Volatility:Fractionated blood product output fluctuates with donor availability and collection center geography, constraining manufacturers dependent on plasma-derived coagulation factors.
- Cold-Chain Infrastructure Concentration:Blood banking networks in the United States and Western Europe control distribution access, elevating barriers for substitute fluid entrants lacking established storage partnerships.
- Pathogen Reduction Mandates:EMA advanced therapy medicinal product frameworks impose costly validation requirements on novel resuscitation biologics, extending time-to-revenue for developmental candidates.
Strategic Opportunities
- Rural Trauma Center Certification:Underserved regions in the United States are achieving Level III and IV trauma designations, creating demand for compact, extended-shelf-life resuscitation systems requiring minimal blood banking infrastructure.
- Freeze-Dried Plasma Convergence:Lyophilization technology paired with pathogen-inactivated plasma is enabling military-civilian technology transfer into commercial emergency departments.
- Direct-to-Hospital Distribution:Manufacturers are bypassing traditional blood bank intermediaries to supply hemostatic agents and crystalloid solutions through integrated delivery networks.
Industry Challenges
- Perfusionist and Trauma Surgeon Scarcity:Specialized surgical capacity limits protocol adoption speed, constraining revenue realization even where product registration is secured.
- Compatibility Testing Complexity:Novel oxygen therapeutic platforms face extended validation timelines against established ABO typing and cross-matching workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemorrhagic Shock Treatment Market |
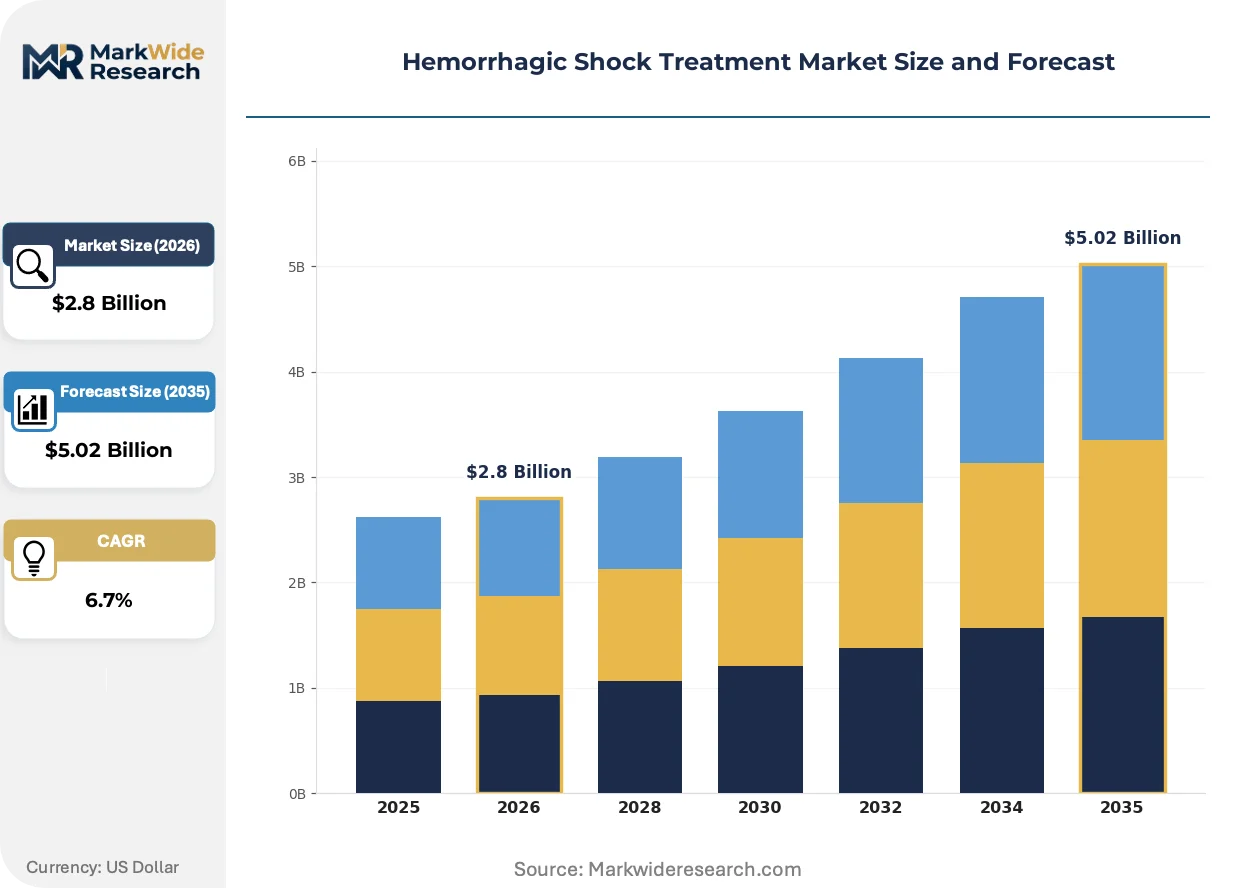
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalloids, Colloids, Blood Products, Vasopressors Delivery Mode: Intravenous, Intraosseous, Topical, Subcutaneous End User: Hospitals, Emergency Departments, Trauma Centers, Military Medical Units Application: Surgical Interventions, Emergency Medicine, Trauma Care, Critical Care |
| Companies Covered | Biomedica Management Corporation, NuvOx Pharma LLC, Leading BioSciences, Inc, F. Hoffmann-La Roche Ltd, Bristol-Myers Squibb Company, Boehringer Ingelheim International GmbH, Johnson & Johnson Services Inc., AstraZeneca plc, Daiichi Sankyo Company, Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemorrhagic Shock Treatment Market Strategic Shifts
Resuscitation science is fragmenting into component-specific interventions that target distinct physiological endpoints—oxygen delivery, coagulation restoration, and vascular tone—rather than relying on whole blood replacement as the default therapeutic anchor.
Synthetic oxygen carriers based on perfluorocarbon emulsions and hemoglobin-based oxygen carriers are decomposing the traditional blood product monopoly on oxygen delivery. Trauma centers in the United States are piloting these platforms in mass casualty scenarios where type-specific blood inventory depletes rapidly. The structural consequence is a bifurcation between premium blood component therapy for complex surgical cases and shelf-stable substitutes for stabilization and transport.
EMA advanced therapy medicinal product frameworks are tightening efficacy evidentiary standards for cell-derived and biologic resuscitation agents. Manufacturers must now demonstrate non-inferiority to standard-of-care blood products across mortality and organ failure endpoints, not merely physiological surrogates. European trauma networks are responding by consolidating procurement around established plasma and platelet suppliers with existing hospital contracts.
Integrated service contracts bundling hemostatic agents, diagnostic platforms, and clinical training are displacing transactional product purchasing in United States trauma centers. Hospital systems are consolidating vendor relationships to reduce protocol variation across emergency departments. This concentration is most visible in the Southeast and Southwest regions where hospital network mergers have created regional procurement consortia with standardized resuscitation guidelines.
Hemorrhagic Shock Treatment Market Segmentation
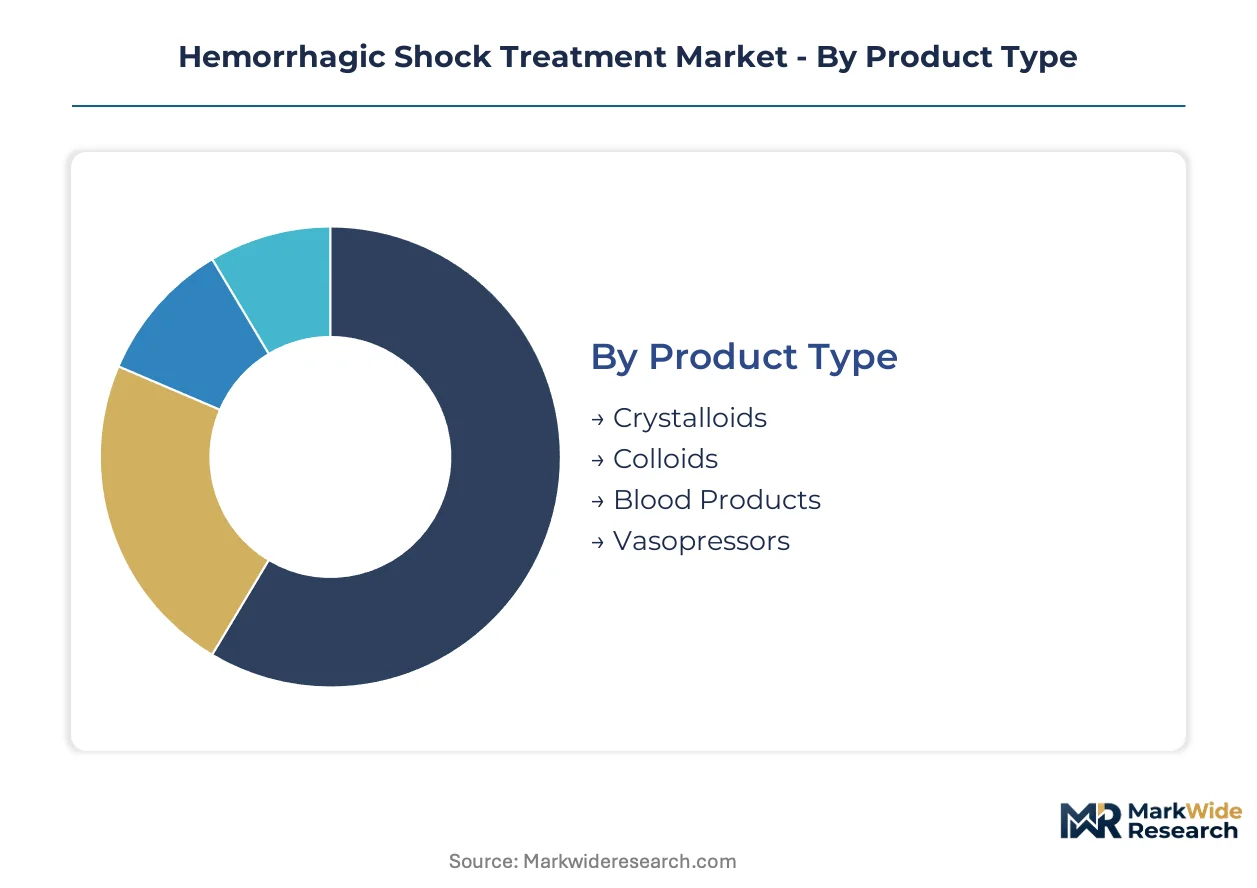
Segmentation in hemorrhagic shock treatment reveals how product categories, delivery modes, and care settings intersect with procurement channels and clinical workflows. Understanding these divides exposes where manufacturers can bypass traditional blood banking intermediaries and where protocol standardization creates vendor consolidation pressure.
Product Type:
Channel mix varies sharply across fluid categories—blood products flow through established blood bank networks with cold-chain dependencies, while crystalloids and synthetic alternatives penetrate through direct-to-hospital distribution and integrated delivery networks.
- Blood Products:Plasma, platelets, and red blood cell concentrates restore oxygen-carrying capacity in severe hemorrhage. Demand concentrates in Level I trauma centers across the United States where damage control resuscitation protocols mandate early component therapy. Cold-chain requirements and ABO compatibility testing reinforce incumbent supplier positions.
- Crystalloids:Isotonic saline and lactated Ringer's solutions serve as first-line volume expanders for initial resuscitation. Emergency departments in the United States drive procurement volume through standardized massive transfusion protocols that specify crystalloid ratios before blood product escalation. Shelf stability enables direct distribution bypassing blood bank intermediaries.
- Colloids:Albumin and hydroxyethyl starch solutions extend intravascular volume through oncotic pressure maintenance.
- Vasopressors:Norepinephrine and vasopressin support vascular tone when fluid resuscitation alone fails to restore perfusion pressure.
Blood products dominate installed base. Crystalloids are where expansion concentrates as prehospital protocols extend resuscitation timelines.
Delivery Mode:
Cost tier separation is pronounced—intravenous delivery commands premium pricing through catheter technology and infusion pump integration, while intraosseous and topical modes compete on emergency accessibility and field-deployability.
- Intravenous:Peripheral and central venous access remains the procedural standard for high-volume fluid resuscitation. Trauma centers in the United States specify IV delivery in massive transfusion protocols, driving catheter and infusion set procurement through group purchasing organizations. Compatibility with automated pressure infusers accelerates adoption in emergency departments.
- Intraosseous:Sternum and tibia access devices enable vascular access when peripheral collapse prevents cannulation. Military medical units in the United States drive demand for compact, battery-powered drivers suitable for battlefield conditions. Extended shelf-life and minimal training requirements support civilian emergency medical services adoption.
- Topical:Hemostatic dressings and powders control external bleeding at the point of injury.
- Subcutaneous:Limited application for vasopressor administration in resource-constrained settings.
Intravenous delivery dominates installed base. Intraosseous is where expansion concentrates as prehospital capabilities extend.
End User:
Customer type determines procurement sophistication—trauma centers and military units specify integrated resuscitation systems, while general hospitals prioritize cost-minimized crystalloid and basic hemostatic portfolios.
- Trauma Centers:Level I and II designated facilities manage the most severe hemorrhagic shock cases with protocol-driven blood product escalation. The United States trauma network expansion is concentrating procurement pull in verified centers with 24-hour surgical capability. Damage control resuscitation standardization is consolidating vendor relationships around integrated fluid-hemostatic-diagnostic suppliers.
- Emergency Departments:Hospital-based emergency services initiate resuscitation before trauma center transfer or surgical intervention. United States emergency departments are adopting tourniquet-to-transfusion continuity protocols, expanding demand for point-of-injury hemostatics and field-deployable blood warmers. Volume scale supports group purchasing organization leverage.
- Hospitals:General acute care facilities manage less severe hemorrhage without specialized trauma designation.
- Military Medical Units:Battlefield medicine drives compact formulation and extreme environment stability requirements.
Trauma centers dominate installed base. Emergency departments are where expansion concentrates as prehospital protocols extend.
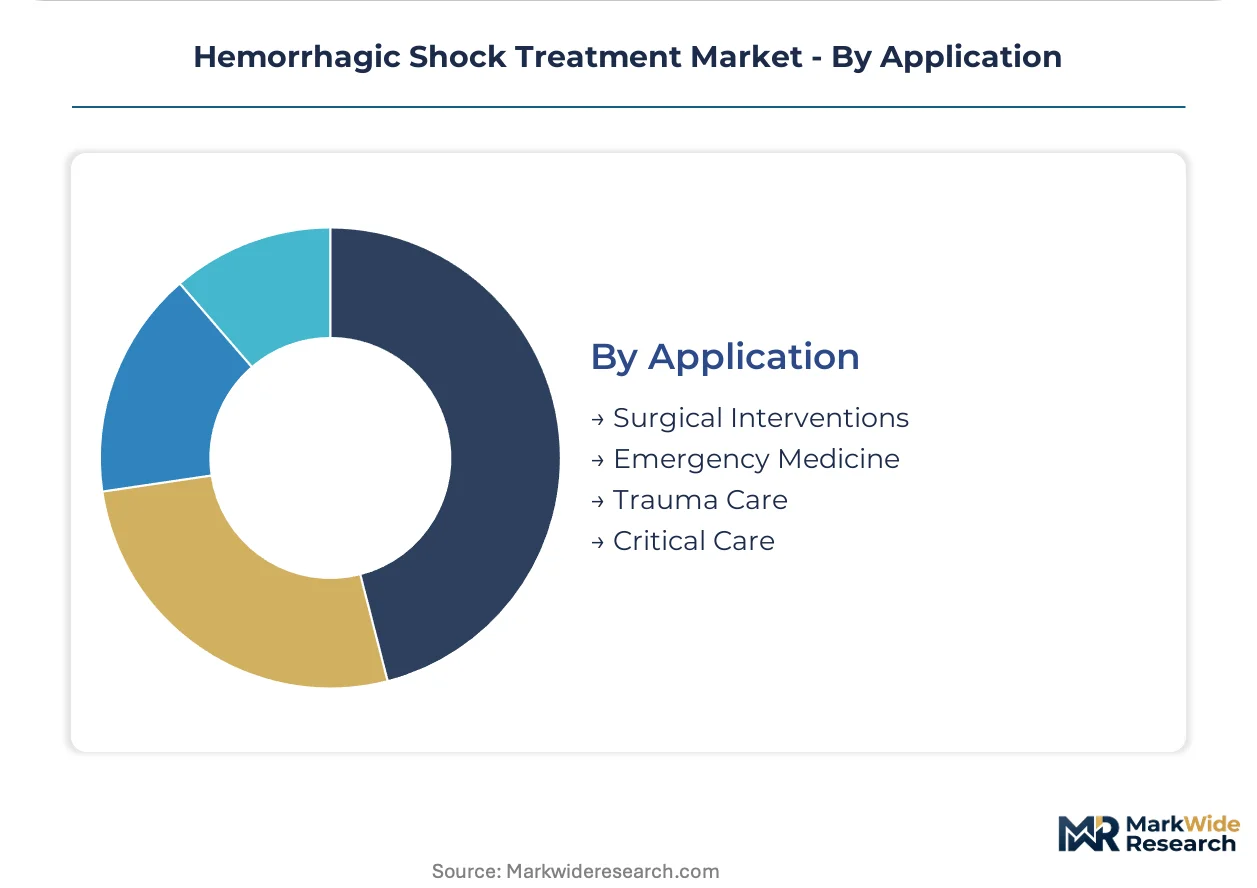
Application:
Volume distribution tracks surgical caseload density—trauma care and surgical interventions absorb the highest fluid and blood product intensity per patient, while critical care represents sustained lower-dose consumption.
- Trauma Care:Acute injury resuscitation demands rapid volume replacement and coagulation management. United States civilian trauma networks replicating military damage control protocols are driving integrated blood product and hemostatic procurement. Time-to-intervention metrics favor suppliers with trauma surgeon training programs and protocol integration services.
- Surgical Interventions:Perioperative hemorrhage management requires predictable fluid availability and compatibility testing workflows. United States surgical suites specify blood product cross-matching through hospital blood banks, reinforcing incumbent supplier relationships. Elective surgery scheduling enables inventory optimization absent in emergency settings.
- Emergency Medicine:Undifferentiated resuscitation before diagnosis or specialty consultation.
- Critical Care:Sustained support following initial stabilization in intensive care units.
Surgical interventions dominate installed base. Trauma care is where expansion concentrates as civilian protocols militarize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on blood product substitutes anchors procurement patterns in the United States, while EMA frameworks and WHO essential medicines lists shape parallel pathways across Europe and emerging markets.
United States
Level I trauma network expansion and military-civilian protocol transfer drive concentrated demand. FDA accelerated pathways for oxygen-carrying volume expanders redirect R&D investment toward shelf-stable alternatives. The Southeast and Southwest hospital network mergers create regional procurement consortia with standardized resuscitation guidelines.
Germany
EMA advanced therapy medicinal product frameworks impose stringent efficacy evidentiary standards on novel biologics. German trauma networks consolidate procurement around established plasma and platelet suppliers with existing hospital contracts. The Rhine-Ruhr industrial corridor anchors cold-chain logistics infrastructure serving Central European blood banking networks.
Japan
PMDA regulatory timelines and aging trauma surgeon capacity constrain protocol adoption speed. METI industrial policy supports domestic plasma fractionation capacity to reduce import dependency. The Kanto region around Tokyo concentrates Level I trauma center designation and university hospital research partnerships.
United Kingdom
NHS Blood and Transplant procurement frameworks favor incumbent suppliers with established compatibility testing workflows. MHRA post-Brexit regulatory autonomy creates divergence from EMA pathways for novel resuscitation agents. London and the Southeast corridor concentrate trauma research consortia and military-civilian medical partnerships.
Australia
TGA regulatory alignment with FDA and EMA standards enables parallel registration strategies for multinational manufacturers. Remote trauma care requirements in Western Australia and Northern Territory drive demand for extended-shelf-life field-deployable systems. The Sydney-Melbourne corridor anchors national blood banking infrastructure and trauma research networks.
Hemorrhagic Shock Treatment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in hemorrhagic shock therapeutics. Diagnostics-to-therapeutics pipelines and surgical hemostasis portfolios define the upper tier, while oxygen therapeutic platforms and coagulation science specialists populate the mid-market. Strategic moves concentrate on protocol integration services and military-civilian technology transfer partnerships rather than standalone product competition.
Within the integrated diagnostics-therapeutics tier, F. Hoffmann-La Roche Ltd and Johnson & Johnson Services Inc. exemplify hospital protocol anchoring strategies. NuvOx Pharma LLC occupies a distinct position among oxygen therapeutic specialists, representing the technology niche against conventional volume expanders. Boehringer Ingelheim International GmbH sits within the coagulation science specialist archetype, sustaining R&D intensity in hemostatic agents.
| Leading Market Players |
|---|
| Biomedica Management Corporation |
| NuvOx Pharma LLC |
| Leading BioSciences, Inc |
| F. Hoffmann-La Roche Ltd |
| Bristol-Myers Squibb Company |
| Boehringer Ingelheim International GmbH |
| Johnson & Johnson Services Inc. |
| AstraZeneca plc |
| Daiichi Sankyo Company, Limited |
| Others |
Value Chain & Pricing Dynamics
Fractionated plasma capacity utilization at North American collection centers creates scale economies that simultaneously depress spot pricing for commodity immunoglobulins and elevate barriers for substitute fluid entrants lacking captive plasma supply. Cold-chain infrastructure concentration in the United States and Western Europe thus locks in price floors for blood products while compressing margins on crystalloid volume expanders competing through direct distribution channels.
Pricing Analysis
United States trauma centers command 15-25% premiums over European equivalents for pathogen-reduced plasma due to FDA-mandated nucleic acid testing add-ons and litigation risk loading. Contract-based long-term offtake dominates procurement, with pricing stratifying across premium pathogen-inactivated components, standard screened plasma, and economy-tier crystalloid alternatives. Cost compression in crystalloid segments intensifies as group purchasing organizations consolidate emergency department formularies around generic saline and lactated Ringer's. Military medical units exhibit lowest price sensitivity given operational exigency, while rural Level III trauma centers face acute budget constraints driving economy-tier procurement.
Supply Chain Analysis
Trans-Pacific container availability fluctuations and port congestion at Los Angeles-Long Beach elevate inbound logistics costs for Asian-manufactured intraosseous access devices and hemostatic raw materials. Plasma fractionation concentrates in the United States, Germany, and Japan, with production drawing from domestic donor pools tethered to collection center geography and regulatory compensation frameworks. Single-source vulnerability pervades recombinant coagulation factor supply given patent-protected cell line dependencies. Distribution runs through hospital blood banks for temperature-controlled components, while shelf-stable hemostatics and crystalloids bypass intermediaries through integrated delivery network direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Damage control resuscitation protocol standardization is reconfiguring this market toward platform economics where integrated fluid-diagnostic-hemostatic bundles displace standalone product competition. Interoperability between tourniquet systems, point-of-care coagulation assays, and massive transfusion protocol algorithms now determines vendor selection.
For Market Incumbents: Consolidate trauma surgeon training programs and protocol integration services to lock in hospital system loyalty against emerging oxygen therapeutic substitutes. Acquire freeze-dried plasma lyophilization capabilities to capture military-civilian technology transfer opportunities. Deepen backward integration into plasma collection center networks to secure fractionation feedstock against donor availability volatility. For New Entrants and Emerging Players: Anchor in rural Level III and IV trauma center certification waves across the Southeast and Southwest United States, where blood banking infrastructure gaps favor shelf-stable synthetic oxygen carriers. Target emergency medical services prehospital tourniquet-to-transfusion continuity protocols with compact, extended-shelf-life field-deployable systems. Pursue direct-to-hospital distribution partnerships with regional procurement consortia to bypass incumbent blood bank intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated diagnostics-therapeutics platform vendors with hospital protocol anchoring and GPO contract longevity. Five-to-ten year viability favors manufacturers with FDA master file submissions for oxygen-carrying volume expanders and established trauma surgeon advisory boards. Monitor FDA accelerated pathway approval velocity for hemoglobin-based oxygen carriers as inflection indicator for substitute fluid category legitimacy.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Oxygen Therapeutic | Accelerated pathway designation unlocks military-civilian procurement channels and trauma center pilot adoption. |
| Hospital System Partnership | Integrated delivery network contracts bundle hemostatics with diagnostics, displacing transactional blood bank purchasing. |
| Freeze-Dried Plasma Manufacturing Scale-Up | Lyophilization capacity captures shelf-stable plasma demand from rural trauma centers lacking cold-chain infrastructure. |
| Reimbursement Strategy Development | CPT code establishment for point-of-injury hemostatic application expands emergency medical services addressable spend. |
| Software Companion Development | Massive transfusion protocol algorithms integrating real-time coagulation monitoring cement vendor protocol anchoring. |
Study Parameters
Cross-validation between trauma surgeon interviews and FDA 510(k) filing analysis anchors the qualitative findings on protocol adoption timelines. Primary fieldwork encompassed emergency department directors, blood bank medical directors, military medical procurement officers, and group purchasing organization contract managers. Secondary validation drew from ClinicalTrials.gov hemorrhagic shock intervention listings, CMS Medicare trauma care reimbursement databases, and Defense Health Agency medical materiel procurement records. Bottom-up trauma center census data and top-down plasma fractionation capacity estimates were triangulated against massive transfusion protocol penetration surveys.
Sensitivity analysis across damage control resuscitation adoption curves and plasma donor availability scenarios frames the projection horizon. Segmentation dimensions modeled include product category, delivery mode, trauma center designation tier, and regional regulatory cluster. CAGRs were derived from installed base growth rates adjusted for protocol conversion timing and military-civilian technology transfer velocity. Forecast inputs incorporated Level I trauma network expansion pipelines and FDA guidance document publication schedules.
Decision-makers should treat outputs as directional under assumptions of sustained military-civilian medical partnership funding and stable plasma collection center economics; material deviation would warrant model refresh. Specific risk factors include FDA blood product substitute efficacy standard elevation and trauma surgeon workforce contraction constraining protocol rollout speed. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Premenstrual Syndrome Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Angioedema Treatment Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market
Medical Treatment
Global Nano Therapy Market
Medical Treatment
Asthma Treatment Market
Medical Treatment
Behcet's Disease Treatment Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Stereotactic Radiation Therapy Market
Medical Treatment
US and Japan Platelet Rich Plasma Market