
 Hypogonadism Treatment Market | 2026-2036
Hypogonadism Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hypogonadism Treatment Market Outlook
The hypogonadism treatment market is decoupling along a sharp fault line between premium long-acting depot injectables and commodity topical gels facing generic saturation. AbbVie Inc leverages its AndroGel heritage and patent-protected sequel formulations to sustain premium positioning in US urology clinics. Pfizer Inc anchors European hospital tenders through its established testosterone undecanoate depot portfolio, while Eli Lilly and Company competes via differentiated rare-disease hormone adjacency expertise.
Hypogonadism treatment encompasses exogenous testosterone replacement and gonadotropin-based therapies administered to restore physiological hormone levels in patients with primary or secondary testicular failure, typically targeting serum testosterone thresholds of 300 ng/dL. These interventions serve commercial and clinical purposes spanning metabolic health maintenance, bone density preservation, fertility restoration, and quality-of-life management across outpatient and homecare settings. Injectables command the dominant revenue share due to physician preference for controlled dosing intervals and reduced adherence risk, while gels face margin compression from compounded pharmacy alternatives and payer step-therapy requirements. The homecare segment represents the fastest-growing delivery setting as self-administration training protocols expand, though specialty pharmacies retain outsized influence over brand access through limited distribution networks.
FDA testosterone labeling mandates, EMA cardiovascular safety monitoring requirements, and DEA Schedule III controlled-substance controls collectively elevate compliance costs and restrict promotional flexibility for manufacturers. These frameworks shape demand by privileging formulations with established REMS-compatible risk profiles and documented cardiovascular outcome data. Stakeholders must monitor evolving FDA guidance on testosterone replacement cardiovascular endpoints and anticipate how state-level pharmacy compounding restrictions will redirect volume toward approved drug pathways.
Market Dynamics
FDA testosterone labeling mandates and EMA cardiovascular safety monitoring requirements are compressing promotional flexibility for manufacturers while elevating compliance costs across all formulation categories.
Growth Catalysts
- Specialty pharmacy channel expansion:Limited distribution networks in the United States are consolidating patient access under REMS-compatible protocols, accelerating brand preference for depot formulations with established risk profiles.
- Metabolic health maintenance protocols:Endocrinology clinics in Germany and Japan are integrating testosterone replacement into comprehensive diabetes and obesity management pathways, extending treatment candidacy beyond classical hypogonadism definitions.
- Homecare self-administration training:Nurse-led injection education programs are reducing clinic visit dependency and expanding addressable patient populations in suburban and rural catchment areas.
Market Restraints
- API supply concentration:Testosterone active pharmaceutical ingredient manufacturing concentrates in Chinese and Indian chemical synthesis facilities, exposing formulation sponsors to import inspection delays and geopolitical supply friction.
- Compounded pharmacy substitution:State-level pharmacy compounding exemptions in the United States permit customized topical preparations at price points below approved gel formulations, eroding commercial margin for transdermal segments.
- Cardiovascular outcome data requirements:FDA-mandated long-term safety studies impose extended trial timelines and substantial clinical trial expenditure before label expansion or new indication approval.
Strategic Opportunities
- Fertility preservation protocols:Gonadotropin-based restoration therapies for secondary hypogonadism represent an underpenetrated adjacency, with reproductive endocrinology clinics in Spain and Italy expanding off-label protocol development.
- Digital therapeutic adherence platforms:Smartphone-connected injection reminder systems and telemedicine follow-up protocols are reducing discontinuation rates among self-administering patients.
- Bone density co-therapies:Osteoporosis screening integration in Japanese geriatric practice guidelines is positioning testosterone replacement as a skeletal health intervention for men over 65.
Industry Challenges
- REMS program administration complexity:Risk evaluation and mitigation strategy compliance requires dedicated pharmacy liaison teams, patient registry maintenance, and prescriber certification tracking that strains operational bandwidth.
- Controlled substance distribution controls:DEA Schedule III quotas and state-level prescription monitoring program integration impose inventory management constraints and dispensing verification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypogonadism Treatment Market |
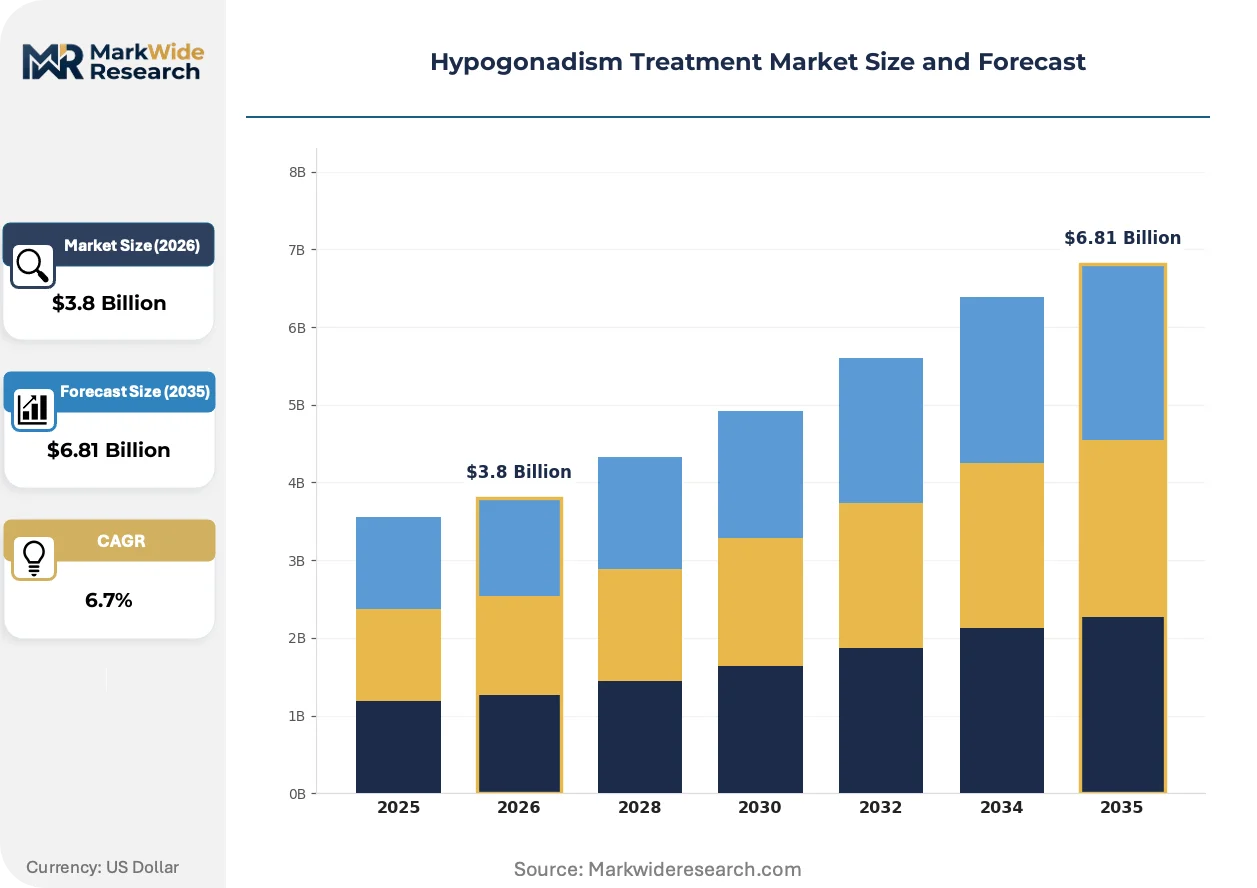
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Gels, Implants, Tablets Delivery Mode: Topical, Injectable, Oral, Transdermal End User: Hospitals, Clinics, Homecare, Specialty Pharmacies Therapy Area: Men's Health, Hormonal Disorders, Infertility, Sexual Dysfunction |
| Companies Covered | AbbVie Inc, Pfizer Inc, Endo International, Eli Lilly and Company, Bayer AG, Teva Pharmaceutical Industries Ltd, Ferring B.V., Merck KGaA, Besins Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypogonadism Treatment Market Strategic Shifts
Formulation science and delivery mechanism engineering are converging to reshape competitive differentiation, with long-acting depot technologies displacing daily administration burdens and digital health tools embedding into patient management protocols.
Subcutaneous testosterone autoinjector systems are integrating precision dosing microchips with Bluetooth connectivity to capture adherence data and transmit injection timestamps to electronic health records. Urology practices in the United States are piloting these devices for patient cohorts with documented compliance gaps. The technology is integrating real-world evidence generation capabilities that manufacturers can leverage for payer contract negotiations and label expansion submissions.
EMA's 2023 cardiovascular safety monitoring guidance revision requires testosterone sponsors to submit periodic benefit-risk assessment reports with structured adjudication of major adverse cardiac events. This regulatory tightening is accelerating investment in prospective outcome studies among European market participants. Hospital pharmacy committees in France and Germany are now demanding documented cardiovascular safety profiles before adding new testosterone products to institutional formularies.
Patients are demanding discreet, travel-compatible administration options that eliminate gel transfer risk and cold-chain dependency. This behavioral shift favors subcutaneous depot formulations over intramuscular injections requiring clinical administration. The preference is most visible among professional-class men aged 35-55 in the United States and United Kingdom, where workplace flexibility constraints and international travel frequency complicate clinic-based injection schedules.
Hypogonadism Treatment Market Segmentation
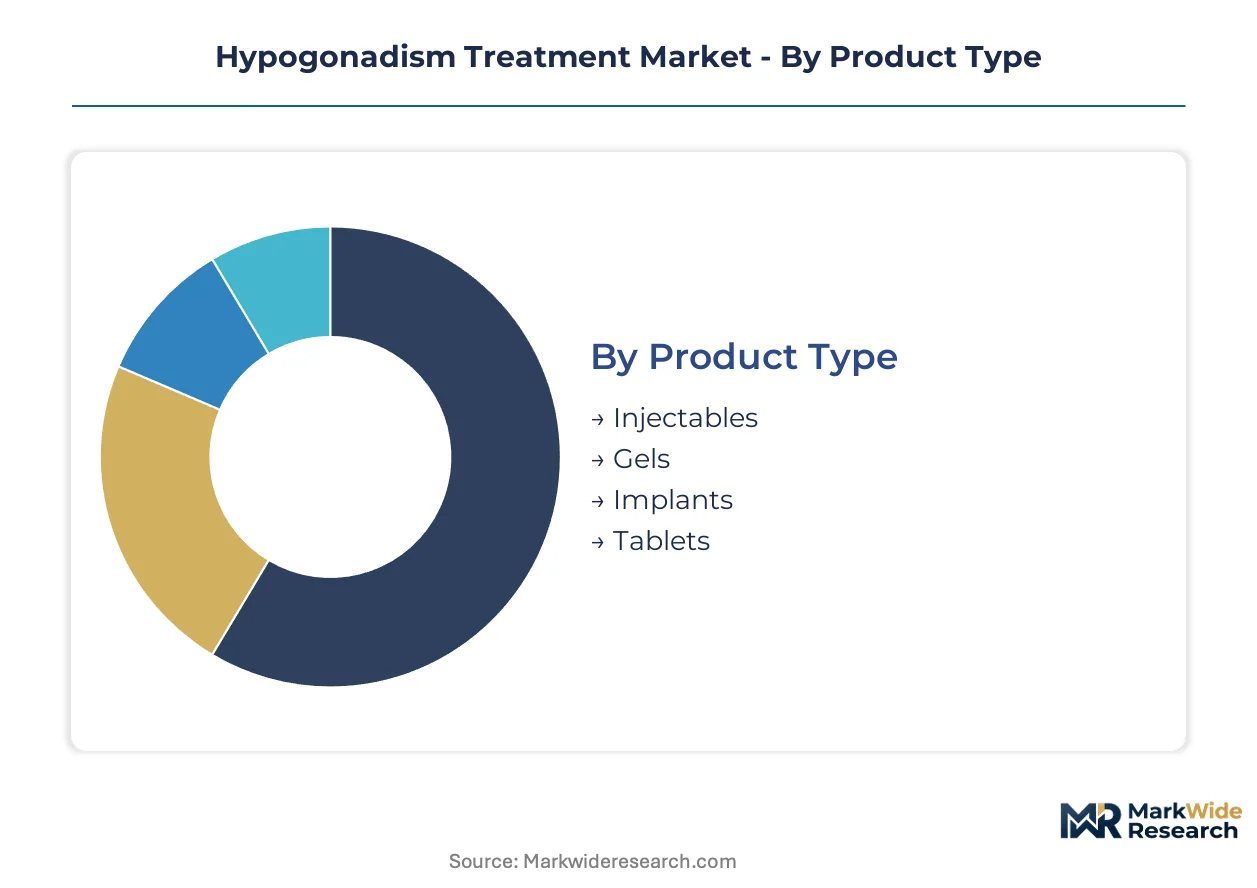
Hypogonadism treatment segmentation reveals how formulation technology, delivery convenience, and care setting economics allocate patient volume across competing therapeutic modalities. Each dimension carries distinct reimbursement profiles and compliance requirements that shape manufacturer portfolio strategy.
Product Type:
Formulation chemistry and release kinetics define therapeutic reliability and prescriber preference across outpatient and institutional channels.
- Injectables:Oil-based testosterone esters and long-acting undecanoate depots provide sustained serum concentration curves with dosing intervals spanning 2-12 weeks. Demand concentrates in United States urology clinics where prior authorization protocols favor established depot formulations with documented REMS compliance.
- Gels:Hydroalcoholic transdermal preparations enable patient-controlled daily dosing with pharmacokinetic profiles mimicking circadian testosterone variation. German endocrinology practices are expanding gel protocols for metabolic syndrome patients requiring dose titration flexibility.
- Implants:Subcutaneous pellet systems deliver 3-6 month testosterone release through erosion-controlled polymer matrices.
- Tablets:Buccal and oral testosterone formulations offer discreet administration for patients rejecting injections or gels.
Mature deployment sits with Injectables. Newer deployment is concentrated in Gels.
Delivery Mode:
Patient autonomy and administration burden trade off against pharmacokinetic precision and transfer risk containment.
- Topical:Direct skin application of gels, creams, and solutions requires drying time protocols to prevent interpersonal transfer. Japanese homecare programs are piloting topical education modules for self-administering patients in rural prefectures.
- Injectable:Intramuscular and subcutaneous routes dominate institutional prescribing where controlled dosing intervals reduce adherence failure.
- Oral:Testosterone undecanoate softgels bypass first-pass metabolism through lymphatic absorption.
- Transdermal:Patch systems provide steady-state delivery with visible application sites that support compliance monitoring.
Institutional procurement favors Injectable delivery. Patient-directed expansion is strongest in Topical.
End User:
Care setting determines reimbursement tier, prescriber specialty mix, and patient support service requirements.
- Hospitals:Inpatient and emergency departments manage acute hypogonadism presentations and complication cases. United States hospital formularies are restricting testosterone access to endocrinology consult services following FDA labeling revisions.
- Clinics:Outpatient endocrinology and urology practices conduct longitudinal hormone monitoring and dose optimization. Spanish reproductive clinics are integrating gonadotropin protocols for secondary hypogonadism with fertility objectives.
- Homecare:Self-administration training programs expand addressable populations beyond urban clinic catchments.
- Specialty Pharmacies:Limited distribution networks control brand access through REMS-compliant dispensing and patient registry maintenance.
Volume concentration remains with Clinics. Steepest expansion trajectory belongs to Homecare.
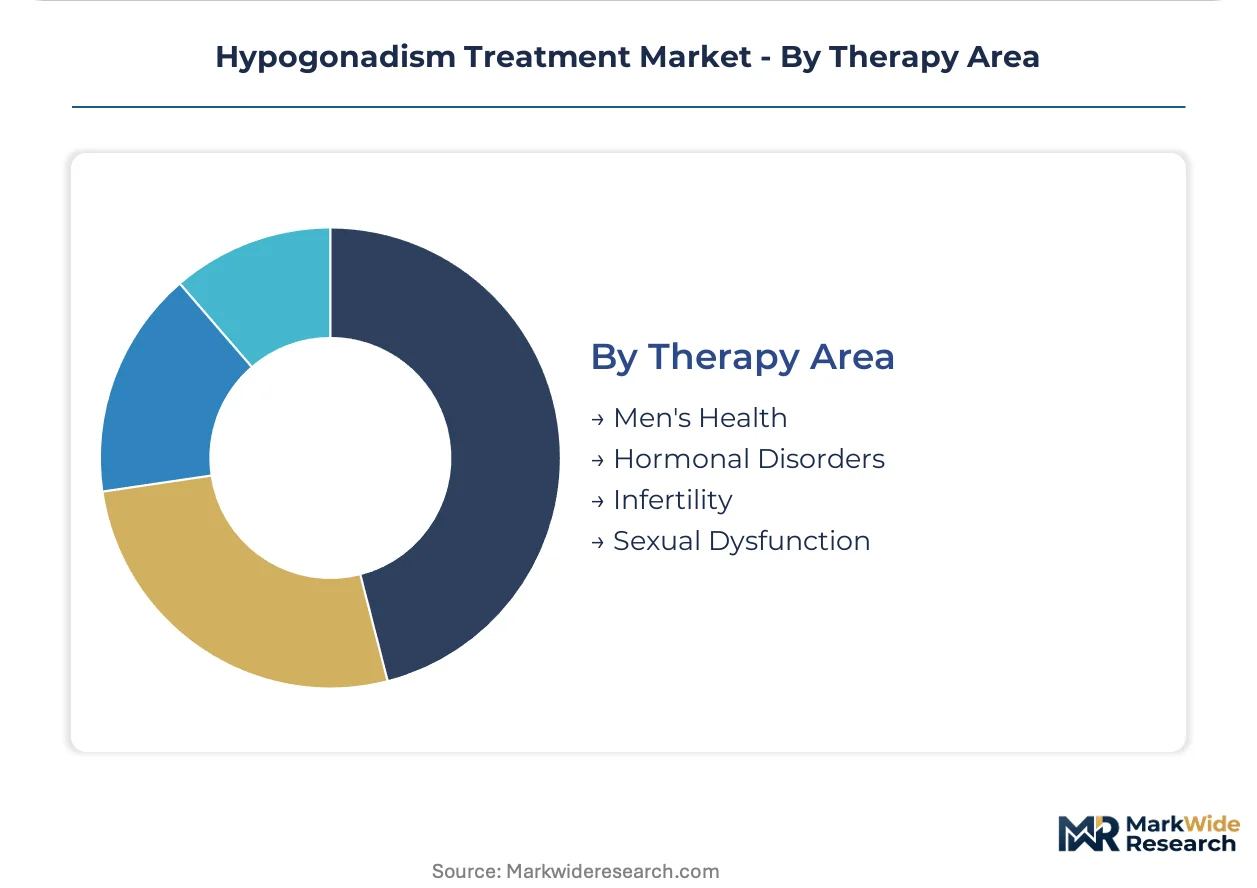
Therapy Area:
Clinical indication framing determines reimbursement coding, prior authorization requirements, and prescriber specialty targeting.
- Men's Health:Comprehensive wellness protocols in United States concierge practices bundle testosterone replacement with cardiovascular and metabolic screening.
- Hormonal Disorders:Classical primary and secondary hypogonadism diagnoses carry established ICD-10 coding and pharmacy benefit coverage.
- Infertility:Gonadotropin-based restoration for secondary hypogonadism addresses spermatogenesis preservation.
- Sexual Dysfunction:Testosterone augmentation for libido and erectile function operates at label edge with variable payer acceptance.
Established reimbursement sits with Hormonal Disorders. Protocol innovation is concentrating in Men's Health.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American hypogonadism treatment activity through its concentration of endocrinology research hospitals and specialty pharmacy distribution hubs serving the Northeast corridor.
United States
Urology clinics in Texas and Florida are expanding testosterone replacement protocols for metabolic syndrome patients. FDA labeling mandates require cardiovascular safety documentation for new depot formulations. Philadelphia's specialty pharmacy corridor controls REMS-compliant distribution networks for long-acting injectables.
Germany
Endocrinology practices in Bavaria integrate hormone replacement into diabetes management pathways for men over 50. EMA cardiovascular monitoring guidance drives hospital formulary requirements for documented safety profiles. The Munich-Stuttgart medical cluster hosts clinical trial sites for testosterone undecanoate outcome studies.
Japan
Geriatric clinics in Tokyo and Osaka are adopting testosterone protocols for bone density preservation in aging males. PMDA review standards emphasize long-term safety data for subcutaneous depot approvals. The Kansai region's homecare nursing networks facilitate self-injection training programs.
United Kingdom
Private men's health clinics in London bundle hormone replacement with cardiovascular screening services. NHS commissioning guidelines restrict gel prescriptions to patients failing injectable therapy. The Cambridge-Oxford research corridor generates real-world evidence for digital adherence platforms.
Spain
Reproductive endocrinology centers in Barcelona and Madrid are developing gonadotropin protocols for fertility preservation in secondary hypogonadism. National pharmaceutical pricing references limit reimbursement for premium depot formulations. The Catalonia hospital network pilots subcutaneous autoinjector systems for rural patient cohorts.
Hypogonadism Treatment Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation technology tiers, with patent-protected depot injectables commanding higher reimbursement rates than generic-exposed topical gels. The vendor base organizes around three strategic archetypes: legacy pharmaceutical conglomerates with urology heritage, specialty hormone manufacturers with reproductive medicine expertise, and emerging device-integrated delivery specialists. Consolidation pressures favor players with integrated REMS administration capabilities and established specialty pharmacy relationships. Competitive moves concentrate on portfolio diversification into fertility adjacencies and geographic expansion through European hospital tenders.
Within the legacy pharmaceutical tier, AbbVie Inc and Pfizer Inc exemplify scale-driven incumbents with decades of testosterone market presence. Eli Lilly and Company occupies a differentiated position through rare-disease hormone adjuvancy expertise that translates into reproductive endocrinology credibility. These three anchors represent contrasting strategic postures: heritage brand leverage, European institutional anchoring, and clinical specialization depth.
| Leading Market Players |
|---|
| AbbVie Inc |
| Pfizer Inc |
| Endo International |
| Eli Lilly and Company |
| Bayer AG |
| Teva Pharmaceutical Industries Ltd |
| Ferring B.V. |
| Merck KGaA |
| Besins Healthcare |
| Others |
Value Chain & Pricing Dynamics
EMA cardiovascular safety monitoring guidance gates qualified supply access for European hospital tenders while privileging depot formulations with documented risk profiles at premium reimbursement tiers. Manufacturers lacking structured adjudication data for major adverse cardiac events face automatic exclusion from institutional formularies in France and Germany, compressing pricing power to commodity levels.
Pricing Analysis
Value-based pricing anchored to cardiovascular outcome documentation determines formulary placement across European hospital systems. Three-tier pricing structure across premium depot injectables, standard transdermal gels, and economy compounded alternatives separates AbbVie's patent-protected formulations from generic gel saturation. Price differentiation reflects REMS compliance certification and documented safety profiles rather than manufacturing cost. Pricing pressure stems from state-level pharmacy compounding exemptions in the United States permitting customized topical preparations below approved gel price points. Payer pharmacy benefit managers exhibit highest price sensitivity for transdermal segments, while urology clinics demonstrate lowest sensitivity for long-acting depot formulations with established prior authorization pathways.
Supply Chain Analysis
Domestic-content mandates in Indian and Chinese API manufacturing are reshaping sourcing strategies for testosterone active pharmaceutical ingredient sponsors. Testosterone ester synthesis concentrates in chemical facilities across China, India, and Italy, drawing from sterol precursor feedstocks and specialized fermentation capacity. Raw material dependencies include pharmaceutical-grade sesame oil, cottonseed oil carriers, and polymer matrices for depot formulations. Single-source vulnerability persists for long-acting undecanoate ester production where qualified manufacturing sites number fewer than five globally. Distribution runs through specialty pharmacy limited distribution networks in the United States and hospital pharmacy committees in Europe, with cold-chain logistics for depot formulations adding cost layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hypogonadism treatment market is becoming a vertical-integration race as manufacturers pursue backward control over testosterone API synthesis to secure supply continuity and margin defense against generic erosion.
For Market Incumbents: Hedge against compounded pharmacy substitution by acquiring or partnering with certified API synthesis facilities in India and China. Secure dedicated manufacturing capacity for testosterone undecanoate esters before regulatory inspection backlogs tighten further. Channel control through exclusive specialty pharmacy networks offers defensive moats against gel commoditization.
For New Entrants and Emerging Players: Telemedicine platforms for hormone replacement consultation represent the most penetrable digital-channel route for patient acquisition without legacy clinic infrastructure. Target suburban and rural patient cohorts in the United States where nurse-led self-injection training programs expand addressable populations beyond established urology clinic catchments. Direct-to-patient subscription models bypassing traditional pharmacy benefit manager gatekeepers offer viable go-to-market angles.
For Investors and Strategic Acquirers: FDA guidance publication on testosterone replacement cardiovascular endpoints is the leading indicator that prospective outcome study investments will differentiate surviving players from margin-compressed competitors. Five-to-ten year viability favors manufacturers with integrated REMS administration capabilities and established European hospital tender relationships. Acquisition target archetypes include specialty hormone manufacturers with reproductive medicine expertise and digital therapeutic adherence platform developers. Monitor state-level pharmacy compounding restriction legislation as the signal for volume redirection toward approved drug pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Prospective cardiovascular outcome studies satisfy EMA benefit-risk assessment requirements for European formulary access. |
| Regulatory Approval Pathway | PMDA long-term safety data submissions unlock Japanese geriatric bone density preservation indications. |
| Backward Integration | Captive testosterone API production insulates against Chinese and Indian import inspection delays. |
| Software Companion Development | Bluetooth-enabled autoinjector adherence data strengthens payer contract negotiations for premium depot formulations. |
| Hospital System Partnership | Exclusive distribution agreements with Philadelphia specialty pharmacy corridor control REMS-compliant patient access. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with endocrinology practice directors, specialty pharmacy procurement managers, hospital formulary committee members, and reproductive endocrinology clinic administrators provided demand-side validation. FDA 510(k) submissions, EMA periodic safety update reports, ClinicalTrials.gov protocol registries, and DEA controlled substance quota publications supplied structured regulatory intelligence. Bottom-up patient volume estimates by formulation category triangulated against top-down manufacturer revenue disclosures and regional prescription audit data.
Data-stream reconciliation across modeled treatment lines, dosage forms, administration routes, and patient population segments generated volume and value outputs across the projection horizon. CAGRs derived from logistic growth curve fitting to historical prescription trends adjusted for regulatory event impacts. Forecast inputs included payer prior authorization approval rates by formulation type, specialty pharmacy network expansion trajectories, and state-level compounding exemption legislative status.
The model holds under stable DEA Schedule III quota allocation and EMA cardiovascular monitoring guidance continuity; deviation in FDA testosterone labeling mandates or major API manufacturing facility regulatory actions would shift volume projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Infertility Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Giardiasis Treatment Market
Medical Treatment
Refsum Disease Treatment Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Peripheral Nerve Injuries Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
Isovaleric Acidemia Treatment Market
Medical Treatment
Middle Ear Infection Treatment Market
Medical Treatment
Onchocerciasis Treatment Market
Medical Treatment
Morquio Syndrome Treatment Market
Medical Treatment
Hyperammonemia Treatment Market
Medical Treatment
Dyspareunia Treatment Market
Medical Treatment
Global Autoimmune Treatment Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Endovenous Laser Therapy Market