
 Cervical Cancer Treatment Market | 2026-2036
Cervical Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Cancer Treatment Market Analysis
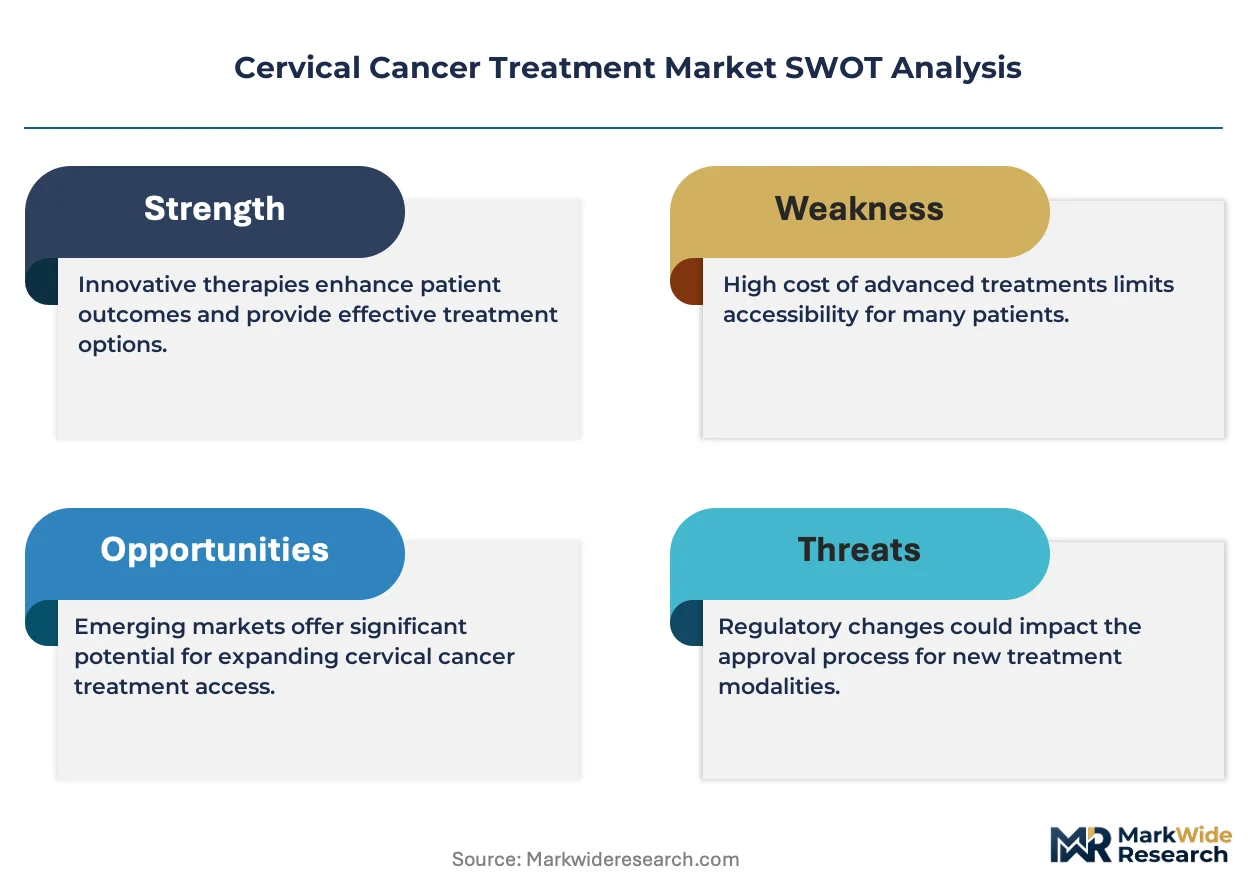
HPV-targeted immunotherapy is narrowing the gap between first-line chemotherapy and precision biologics in cervical cancer care. Merck & Co., Inc. leverages its established PD-1 franchise to anchor clinical trial networks across major oncology centers. Bristol-Myers Squibb Company competes through checkpoint inhibitor combinations, while Seagen Inc. specializes in antibody-drug conjugate development for recurrent and metastatic settings.
Cervical cancer treatment encompasses surgical intervention, radiation therapy, systemic chemotherapy, immunotherapy, and targeted biologics administered to eliminate or control malignant squamous cell and adenocarcinoma lesions of the cervix, with modern protocols emphasizing concurrent chemoradiation followed by adjuvant immunotherapy for locally advanced disease. Immunotherapy now leads product type expansion as pembrolizumab gains label extensions, while targeted therapy captures concentrated margin pools in biomarker-selected patient subsets. Hospitals dominate end user demand due to infrastructure requirements for radiation delivery and infusion monitoring, though clinics are capturing shift volumes for stable maintenance regimens.
FDA oncology center of excellence review standards, EMA centralized marketing authorization procedures, and WHO prequalification pathways collectively determine market access timelines and reimbursement eligibility for novel cervical cancer agents. These frameworks elevate evidence requirements for overall survival endpoints while creating differentiated access corridors across regulated and emerging markets. Stakeholders must monitor biomarker testing penetration and biosimilar entry sequencing to calibrate portfolio positioning and geographic prioritization.
Market Dynamics
Checkpoint inhibitor label expansions are restructuring cervical cancer treatment hierarchies by elevating immunotherapy from salvage settings to first-line concurrent protocols alongside chemoradiation.
Growth Catalysts
- Accelerated Approval Pathways:FDA Oncology Center of Excellence breakthrough designations compress Phase II-to-commercialization timelines for novel biologics, compressing development cycles for PD-1/PD-L1 combinations.
- HPV Screening Infrastructure:Germany's statutory health insurance reimbursement for liquid biopsy-based recurrence monitoring expands addressable patient pools for adjuvant immunotherapy initiation.
- Antibody-Drug Conjugate Platforms:Tissue factor-directed ADCs are penetrating recurrent metastatic settings where chemotherapy resistance previously terminated therapeutic sequences.
Market Restraints
- Platinum Salt Supply Concentration:Cisplatin and carboplatin API manufacturing concentrates in Chinese and Indian contract manufacturers, exposing oncology networks to single-source disruption risks.
- Biomarker Testing Access Gaps:PD-L1 immunohistochemistry and MSI-high profiling remain inconsistently reimbursed outside tertiary academic centers, fragmenting precision therapy eligibility.
- Radiation Equipment Capex Barriers:Linear accelerator installation requires $3-5 million facility investments plus shielded vault construction, limiting brachytherapy-chemoradiation access in community hospital settings.
Strategic Opportunities
- Maintenance Immunotherapy Protocols:Post-chemoradiation pembrolizumab consolidation creates durable prescribing relationships between oncology practices and infusion center networks.
- India's PLI Scheme for Biologics:Production-linked incentives for biosimilar manufacturing attract contract development investments serving emerging market access programs.
- Telemedicine-Enabled Rural Outreach:Remote patient monitoring platforms extend clinical trial recruitment into underserved U.S. counties lacking gynecologic oncology subspecialists.
Industry Challenges
- Gynecologic Oncology Workforce Scarcity:Fellowship program graduation rates lag incidence growth, forcing community hospitals to rely on medical oncologists without cervix-specific surgical training.
- Cold Chain Logistics Complexity:Temperature-controlled distribution for checkpoint inhibitors demands validated packaging across last-mile delivery to infusion clinics.
- Companion Diagnostic Co-Development:Synchronous FDA review of novel agents with predicate biomarker assays extends regulatory submission preparation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Cancer Treatment Market |
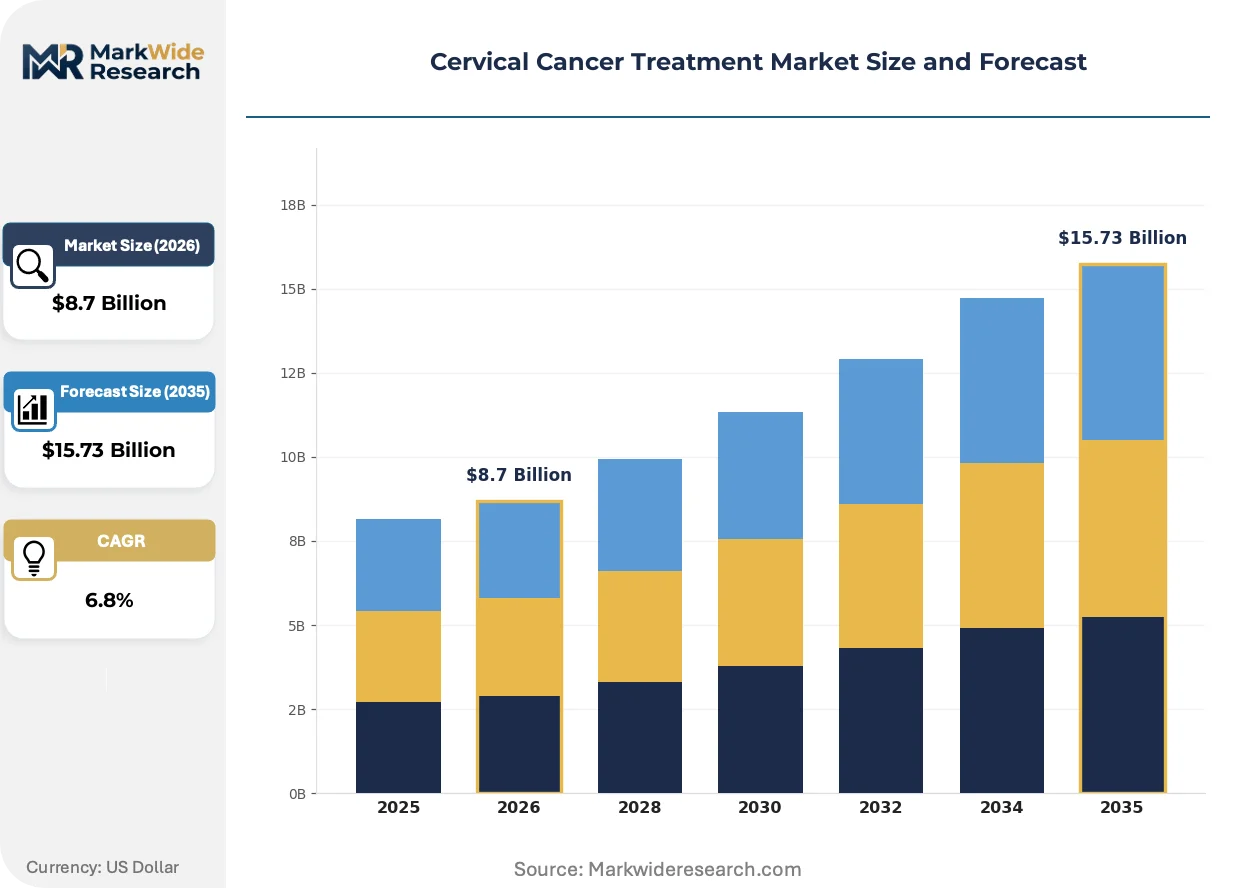
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Immunotherapy, Targeted Therapy End User: Hospitals, Clinics, Home Care, Research Institutions Administration Route: Intravenous, Oral, Subcutaneous, Topical Age Group: Adolescents, Adults, Elderly, Others |
| Companies Covered | Merck & Co., Inc., Pfizer Inc., F. Hoffmann-La Roche Ltd, GSK plc, AstraZeneca, Bristol-Myers Squibb Company, Novartis AG, Johnson & Johnson Services, Inc., Seagen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Cancer Treatment Market Emerging Trajectories
Clinical development pipelines are pivoting toward combination immunotherapy architectures that layer checkpoint blockade with angiogenesis inhibitors or costimulatory agonists to overcome primary resistance mechanisms.
ADC payload technology is migrating from tubulin-binding maytansinoids to DNA-alkylating exatecans, enabling higher drug-antibody ratios without dose-limiting neuropathy. Academic medical centers in the United States and Germany are prioritizing these constructs for platinum-resistant cohorts. This platform evolution is compressing chemotherapy's residual role in third-line settings.
EMA's centralized marketing authorization procedures now mandate pediatric investigation plans for all novel oncology agents, including those with adult-only cervical cancer indications. This regulatory expansion forces sponsors to commit to adolescent toxicity studies regardless of primary target population. European trial networks are responding by embedding young adult expansion cohorts into Phase I dose-escalation designs.
Hospital procurement committees are consolidating radiation oncology capital purchases into multi-year managed equipment service agreements. Vendor risk-sharing contracts now tie linear accelerator uptime guarantees to reimbursement-adjacent outcome metrics. This purchasing transformation is most advanced in U.S. integrated delivery networks and select German hospital federations seeking to offload technical obsolescence exposure.
Cervical Cancer Treatment Market Segmentation
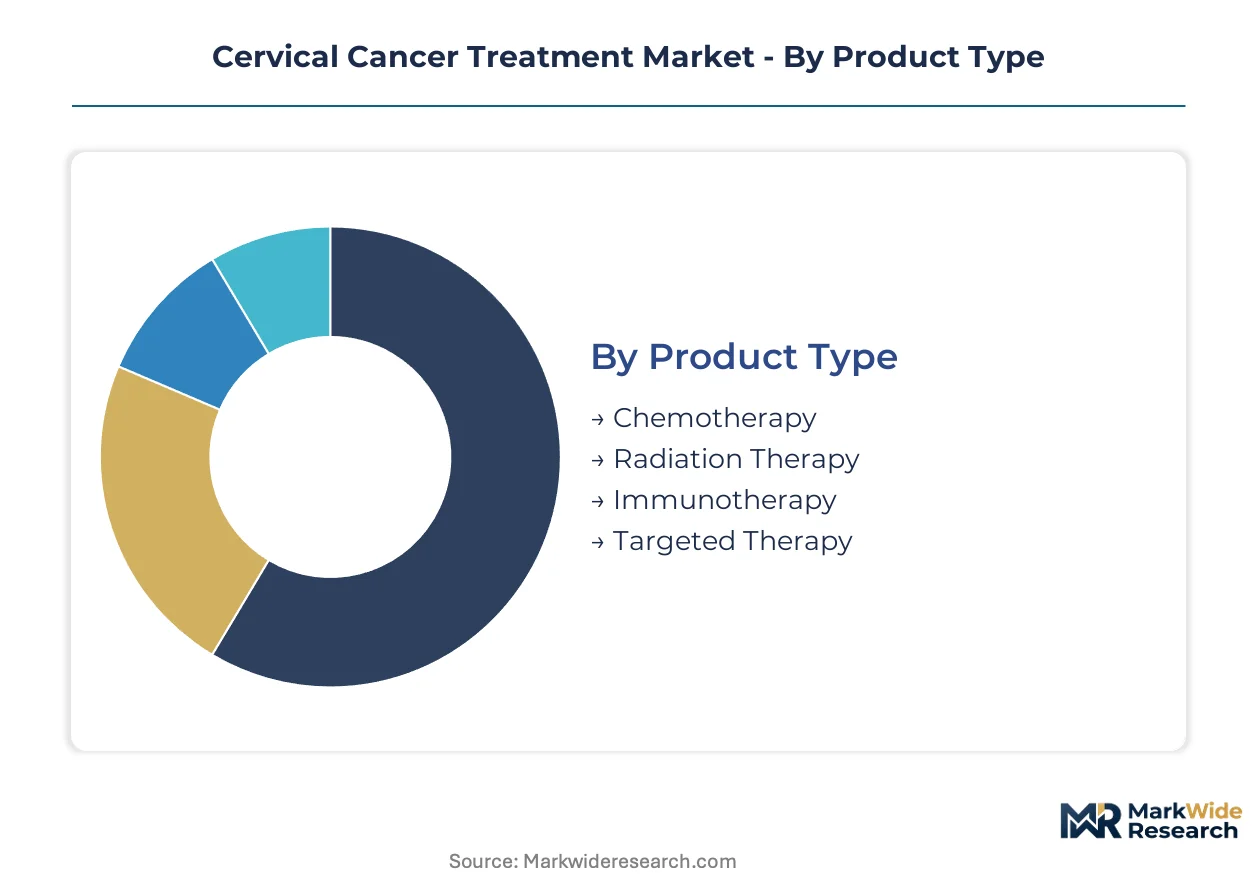
Treatment modality selection in cervical cancer care follows distinct velocity patterns across product categories, with immunotherapy protocols turning over fastest as label expansions reshape prescribing hierarchies. Patient access infrastructure and reimbursement granularity fragment demand concentration across end-user settings and administration routes.
Product Type:
Cycle times vary sharply across modalities, with chemotherapy regimens refreshing slowest due to entrenched protocol standardization while immunotherapy combinations iterate fastest through checkpoint inhibitor label expansions.
- Chemotherapy:Platinum-based agents (cisplatin, carboplatin, paclitaxel) remain backbone therapy for locally advanced disease in concurrent chemoradiation protocols. Demand concentrates in tertiary hospitals across the United States, China, and Germany where radiation oncology infrastructure supports combined-modality delivery, though API supply concentration in Asian contract manufacturers exposes networks to disruption.
- Immunotherapy:PD-1 inhibitors now anchor first-line maintenance protocols following chemoradiation completion, with pembrolizumab gaining accelerated FDA approvals for recurrent and metastatic settings. Prescribing velocity outpaces all other modalities as oncology practices build infusion center capacity for consolidation regimens.
- Radiation Therapy:External beam and brachytherapy combinations require linear accelerator infrastructure and shielded vault construction limiting deployment to capital-rich hospital systems.
- Targeted Therapy:Antibody-drug conjugates and angiogenesis inhibitors serve biomarker-selected subsets in platinum-resistant recurrence.
Chemotherapy anchors the volume base while immunotherapy gains share at the steepest rate.
End User:
Capital intensity requirements stratify patient flow, with high-acuity settings capturing initial diagnosis and complex protocols while lower-intensity venues absorb stable maintenance volumes.
- Hospitals:Integrated delivery networks dominate through radiation oncology capital investments and gynecologic oncology subspecialist concentration. Linear accelerator service agreements and shielded vault requirements create structural barriers to entry, concentrating advanced protocol access in academic medical centers and large community hospital systems across the United States and Germany.
- Clinics:Outpatient infusion centers capture shift volumes for stable immunotherapy maintenance regimens following hospital-based induction, with reimbursement parity driving site-of-care migration for pembrolizumab consolidation.
- Home Care:Oral oncolytic administration and remote patient monitoring extend reach into rural counties lacking subspecialist proximity.
- Research Institutions:Academic medical centers anchor clinical trial recruitment for novel combination architectures and ADC platforms.
Hospitals retain the highest acuity concentration while clinics capture the fastest volume migration.
Administration Route:
Infusion infrastructure dependence versus patient convenience trade-offs reshape route selection across treatment phases.
- Intravenous:Checkpoint inhibitors, platinum agents, and ADCs require infusion center capacity with cold chain validation and nursing oversight for hypersensitivity monitoring. United States and German hospital networks invest in dedicated gynecologic oncology infusion suites to capture maintenance protocol volumes.
- Oral:Small-molecule targeted agents enable home administration for stable patients, though adherence monitoring requirements limit penetration in publicly funded systems.
- Subcutaneous:Emerging delivery format for select immunotherapy formulations reduces infusion chair time and center capacity constraints.
- Topical:Limited to intraoperative and intracavitary applications in surgical and brachytherapy settings.
Intravenous delivery dominates value concentration while subcutaneous formats show the steepest adoption trajectory.
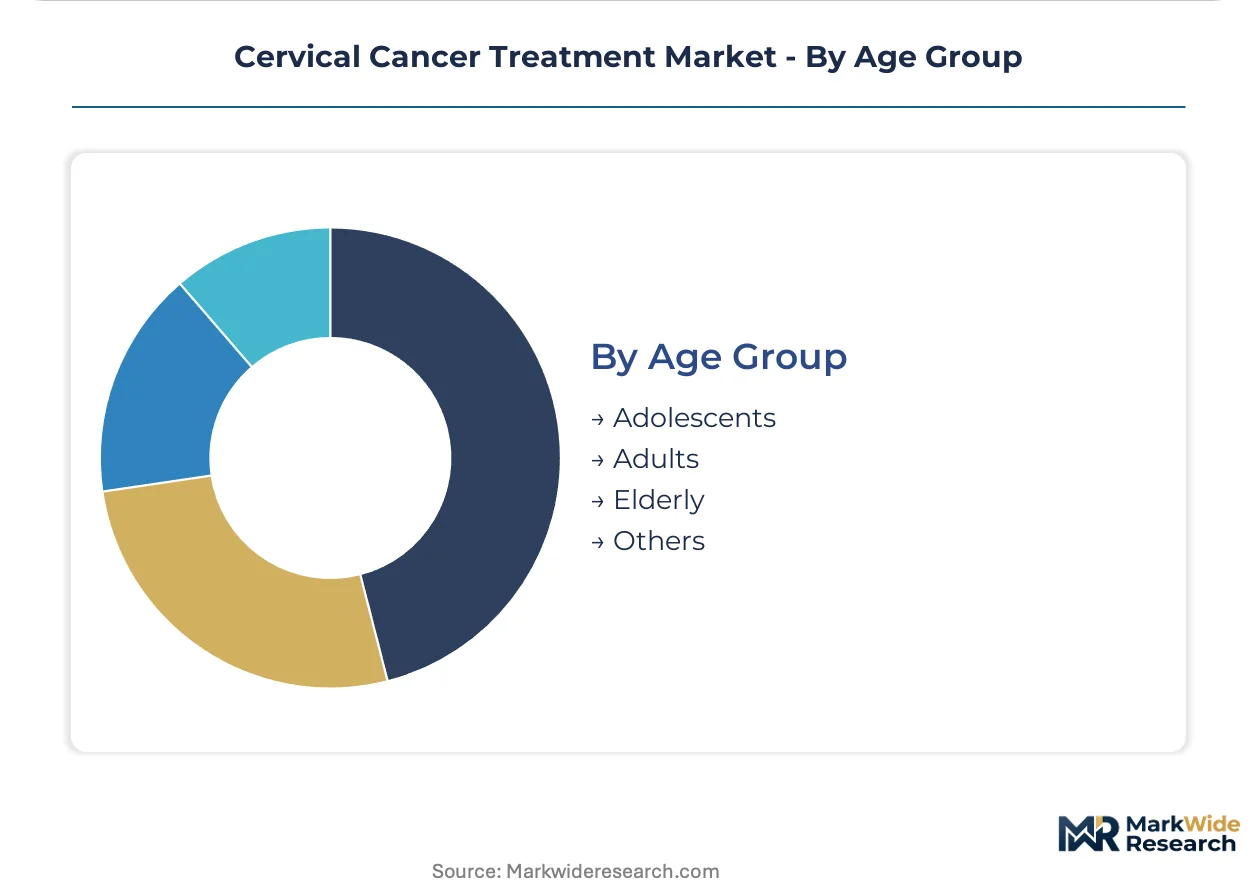
Age Group:
Screening program reach and HPV vaccination coverage create distinct incidence patterns across demographic cohorts.
- Adults:Women aged 30-50 represent the core incident population in markets with established cytology-based screening, with stage distribution shifting toward locally advanced disease where chemoradiation-immunotherapy combinations apply. China's expansion of HPV screening programs in provincial hospital networks targets this cohort for earlier detection.
- Elderly:Comorbidity burden and performance status constraints limit eligibility for combined-modality protocols, shifting demand toward palliative systemic options and hypofractionated radiation schedules in German statutory health insurance frameworks.
- Adolescents:Rare invasive presentations require pediatric investigation plans under EMA mandates, with academic centers embedding young adult cohorts into early-phase trials.
- Others:Immunocompromised and transgender patient subsets require protocol modifications outside standard guidelines.
Adults anchor the incident case base while elderly segments expand most quickly with population aging trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian API manufacturers export platinum salts to oncology networks across Germany and the United States, establishing a critical supply corridor for first-line chemoradiation protocols.
United States
FDA Oncology Center of Excellence breakthrough designations compress development timelines for PD-1 combinations, while Medicare reimbursement parity drives site-of-care migration toward outpatient infusion centers. Academic medical centers in Boston and Houston anchor clinical trial recruitment for novel ADC platforms.
Germany
Statutory health insurance reimbursement for liquid biopsy-based recurrence monitoring expands addressable pools for adjuvant immunotherapy initiation. EMA centralized procedures mandate pediatric investigation plans for novel agents. Hospital federations in Bavaria and North Rhine-Westphalia consolidate radiation oncology capital purchases into multi-year managed service agreements.
China
Provincial hospital networks expand HPV screening infrastructure to capture earlier-stage detection in the 30-50 cohort. NMPA accelerated review pathways for imported biologics reshape competitive access timelines. Yangtze River Delta oncology clusters in Shanghai and Hangzhou concentrate infusion center capacity for maintenance pembrolizumab protocols.
India
Production-linked incentive schemes for biosimilar manufacturing attract contract development investments serving emerging market access programs. CDSCO streamlined approval pathways for reference biologics reduce regulatory lag. Mumbai-Pune pharmaceutical corridors concentrate API manufacturing for platinum-based agents exported to European and North American buyers.
Japan
PMDA sakigake designation system prioritizes review of immuno-oncology combinations for recurrent metastatic settings. Aging demographics expand elderly patient segments eligible for palliative systemic options. Kanto region academic centers in Tokyo and Yokohama embed young adult expansion cohorts into early-phase trial designs per EMA-aligned protocols.
Cervical Cancer Treatment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across the cervical cancer treatment hierarchy. Large-cap pharmaceutical incumbents leverage established PD-1 franchises to anchor clinical trial networks and secure maintenance protocol prescribing relationships. Mid-scale biotechnology specialists concentrate development resources on antibody-drug conjugate platforms for platinum-resistant recurrence. Competitive dynamics center on checkpoint inhibitor label expansion velocity and biomarker co-development partnerships with diagnostic manufacturers.
Among diversified oncology incumbents, Merck & Co., Inc. and Bristol-Myers Squibb Company occupy positions reflecting established immunotherapy infrastructure, while Seagen Inc. exemplifies the ADC-specialist archetype targeting resistant disease settings. These three anchors represent distinct competitive vectors: franchise breadth versus combination agility versus payload innovation.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| GSK plc |
| AstraZeneca |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Johnson & Johnson Services, Inc. |
| Seagen Inc. |
| Others |
Supply Flow & Price Mechanics
Single-source API dependency for platinum salts concentrates manufacturing in Indian and Chinese contract facilities, compressing margin structures for first-line chemotherapy while simultaneously dictating three-tier pricing stratification across originator, authorized generic, and commodity biosimilar tiers.
Pricing Analysis
Next-generation checkpoint inhibitor maintenance protocols command substantial premiums over prior-generation platinum-taxane combinations, while oral small-molecule candidates in development threaten intravenous pricing architecture. Pricing stratifies across premium, standard, and economy tiers based on biomarker selection requirements and cold chain logistics intensity. Cost compression in the chemotherapy segment intensifies as Indian API exports expand, though brand premiums persist for FDA-certified manufacturing. Hospital procurement committees exhibit highest price sensitivity for radiation oncology capital equipment, while specialty oncology practices absorb immunotherapy premiums with limited pushback.
Supply Chain Analysis
Upstream platinum salt feedstock refining centers on Chinese smelters and Indian chemical processors, with secondary concentration in South African mining operations for raw ore. Finished dose formulation draws from United States and German sterile manufacturing facilities, while antibody-drug conjugate payload-linker technology sources from specialized Swiss and Japanese chemical synthesis houses. Single-source vulnerability pervades the cisplatin API tier, where three contract manufacturers service global oncology networks. Distribution runs through temperature-validated logistics partnerships extending from manufacturing sites to hospital infusion centers, with regional hub consolidation in Rotterdam and Singapore for Asia-Pacific access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power concentrates in United States integrated delivery networks and German hospital federations, consolidating procurement volume and extracting price concessions across therapeutic categories.
For Market Incumbents: Entrench maintenance protocol relationships through dedicated gynecologic oncology infusion suite investments in academic medical centers. Prioritize backward integration into ADC payload manufacturing to capture margin pools currently flowing to Swiss chemical synthesis specialists. Defensive patent strategy around subcutaneous formulation delivery will forestall biosimilar erosion in the immunotherapy tier.
For New Entrants and Emerging Players: Build out remote patient monitoring platforms targeting rural United States counties lacking subspecialist proximity, where telemedicine-enabled clinical trial recruitment remains underdeveloped. India's production-linked incentive scheme for biosimilar manufacturing offers the most penetrable regulatory entry point. Go-to-market positioning should emphasize cost-advantaged maintenance regimen delivery against hospital-based infusion center incumbents.
For Investors and Strategic Acquirers: FDA Oncology Center of Excellence breakthrough designation velocity reshapes the acquisition landscape by compressing Phase II-to-commercialization timelines for platform technologies. Five-to-ten year viability favors ADC-specialist archetypes with tissue factor-directed payloads and existing Seagen-competitive intellectual property. Monitor EMA pediatric investigation plan compliance rates as signal for European regulatory execution capability among target pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Checkpoint inhibitor label expansions restructure first-line treatment hierarchies across NCI-designated cancer centers. |
| Manufacturing Scale-Up | Indian PLI scheme incentives attract biosimilar CDMO investments serving emerging market access programs. |
| Regulatory Approval Pathway | FDA breakthrough designations compress development cycles for PD-1 combination protocols in cervical cancer. |
| Pipeline Diversification | ADC platform migration to DNA-alkylating exatecan payloads targets platinum-resistant recurrence settings. |
| Strategic Partnership | Companion diagnostic co-development agreements with IVD manufacturers secure biomarker-selected patient access. |
Methodological Framework
Desk research of FDA oncology approval databases, EMA centralized procedure records, and ClinicalTrials.gov protocol registries preceded structured interviews with gynecologic oncology division chiefs, hospital pharmacy directors, payer formulary managers, and biologics manufacturing executives. Secondary validation drew from SEC 10-K oncology segment disclosures, CMS Medicare Part B reimbursement data, and WHO prequalification pathway documentation. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Assumptions held HPV screening coverage rates and immunotherapy reimbursement parity constant across the projection horizon, while varying biosimilar entry sequencing and platinum salt supply disruption scenarios. Segmentation modeling incorporated treatment line, administration route, patient age cohort, and regional regulatory cluster dimensions. CAGRs derived from fitted adoption curves for checkpoint inhibitor maintenance protocols, cross-referenced against historical analogs from immuno-oncology expansion in other tumor types.
The forecast holds incumbent behavior within observed patterns; aggressive moves by mid-scale ADC specialists or unexpected FDA label restrictions would shift outcomes beyond modeled ranges. Cross-checking against IQVIA prescription audit data and hospital procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Otoplasty Market
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
North America Chronic Disease Management Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Mercury Poisoning Treatment Market
Medical Treatment
Single Dose Radiotherapy Services Market
Medical Treatment
Transplantation Market
Medical Treatment
Mexico Hair Transplant Market
Medical Treatment
Myasthenia Gravis Treatment Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Anemia Treatment Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
Scalp Care Treatment Market