
 Gangrene Market | 2026-2036
Gangrene Market Size, Share, and Industry Trends Forecast 2026-2036
Gangrene Market Analysis
Aftermarket service revenue for hyperbaric oxygen chamber maintenance is narrowing as manufacturers shift toward bundled therapy contracts. Integra LifeSciences Corporation dominates advanced wound matrix supply through its regenerative tissue portfolio. Pfizer Inc. anchors systemic antibiotic protocols with established anti-infective manufacturing scale. Smith+Nephew competes in negative pressure wound therapy with integrated dressing-to-device platforms.
Gangrene constitutes tissue necrosis arising from compromised blood supply, infection, or trauma, typically requiring prompt surgical intervention combined with antimicrobial therapy and vascular restoration; hyperbaric oxygen therapy delivers oxygen at pressures exceeding standard atmospheric levels to enhance tissue oxygenation and inhibit anaerobic bacterial proliferation. Surgical debridement commands the largest share of procedural revenue due to its irreplaceable role in necrotic tissue removal, while hyperbaric oxygen therapy represents the fastest-growing segment as hospitals expand chamber installations for limb salvage programs. Dressings capture concentrated margin pools where antimicrobial silver-impregnated and collagen-based formats differentiate on reimbursement coding.
FDA 510(k) and PMA pathways govern advanced wound device approvals in the United States, while EU MDR and CE marking requirements elevate clinical burden for dressings and hyperbaric systems across European markets. Japan's PMDA enforces stringent QMS inspections for imported wound care products, shaping market access timelines for foreign manufacturers. Stakeholders must monitor reimbursement recalibrations for limb salvage versus amputation procedures as value-based care contracts reshape provider economics.
Market Dynamics
Hospital procurement of advanced wound dressings is accelerating as diabetic foot ulcer incidence rises, tightening vendor qualification standards and compressing supplier margins through volume consolidation.
Growth Catalysts
- EU MDR clinical evidence requirements:Manufacturers investing in robust clinical data packages are securing premium reimbursement tiers for antimicrobial dressings across German and French hospital networks.
- Hyperbaric oxygen chamber installations:Tertiary wound care centers in the United States are expanding chamber capacity to support limb salvage programs for diabetic patients.
- Silver-impregnated collagen matrices:Advanced dressing formats are capturing concentrated margin pools through differentiated reimbursement coding in Japanese tertiary hospitals.
Market Restraints
- Raw material concentration:Pharmaceutical-grade collagen supply concentrates among a limited set of bovine and porcine tissue processors, exposing dressing manufacturers to input volatility.
- EU MDR transition costs:Small and mid-sized device manufacturers face disproportionate clinical trial burdens for legacy dressing products, forcing portfolio rationalization.
- Amputation cost benchmarks:Reimbursement frameworks in several markets still favor amputation over limb salvage procedures, limiting hyperbaric oxygen therapy penetration.
Strategic Opportunities
- Underpenetrated vascular restoration:Peripheral artery disease screening programs in rural United States regions remain below diagnostic targets, creating addressable pools for early intervention.
- Japan PMDA QMS pathway optimization:Foreign manufacturers streamlining quality management documentation can compress market access timelines for advanced wound matrices.
- Remote patient monitoring integration:Connected dressing sensors and telemedicine platforms are converging to enable home-based wound surveillance post-discharge.
Industry Challenges
- Hyperbaric technician certification:Chamber operation requires specialized training credentials that remain scarce in secondary hospital markets, constraining service expansion.
- FDA 510(k) predicate device drift:Evolving substantial equivalence standards for antimicrobial dressings are extending clearance timelines and increasing regulatory consulting expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gangrene Market |
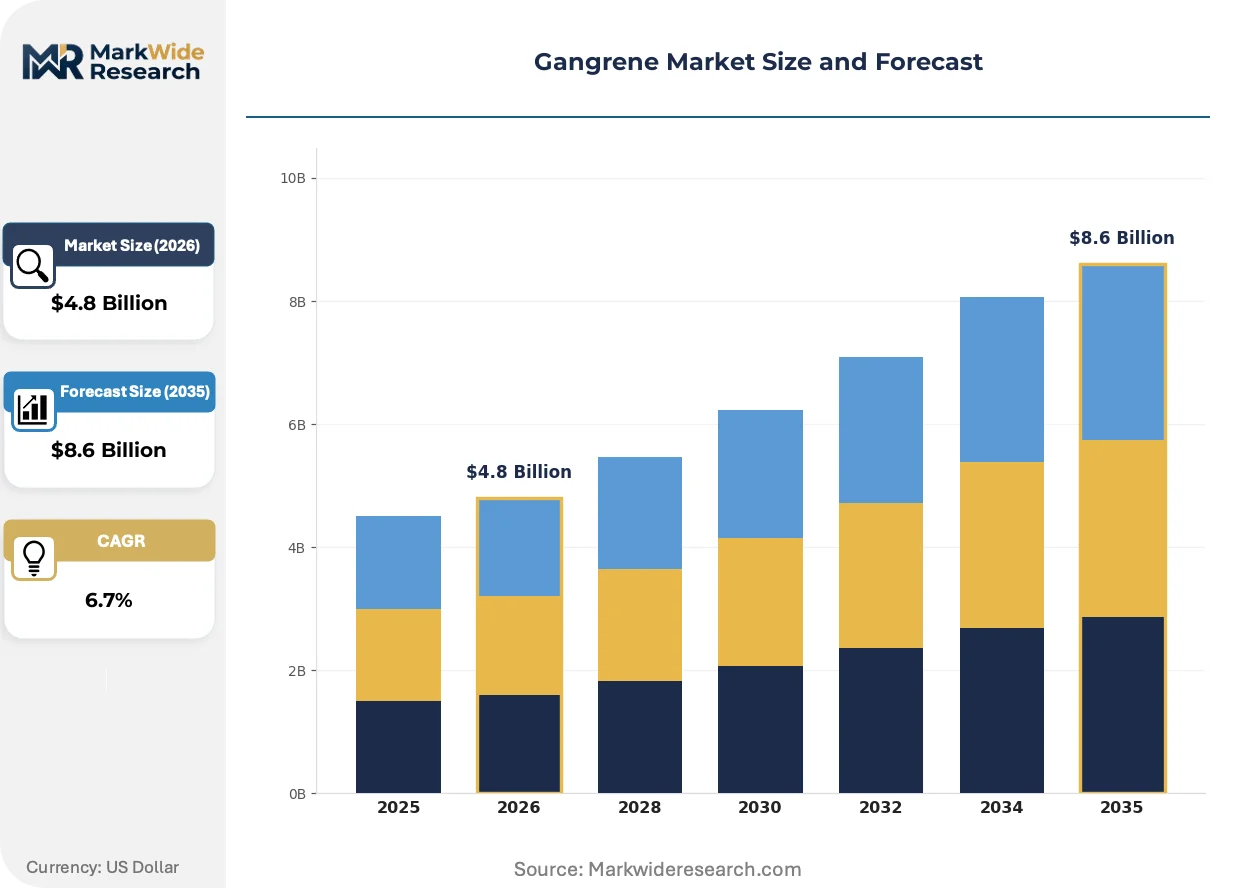
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Surgical Debridement, Dressings, Hyperbaric Oxygen Therapy Application: Diabetes, Trauma, Infectious Diseases, Vascular Disorders End User: Hospitals, Outpatient Clinics, Home Healthcare, Rehabilitation Centers Treatment Type: Medical, Surgical, Combination Therapy, Palliative Care |
| Companies Covered | Integra LifeSciences Corporation, Pfizer Inc., Smith+Nephew, Sanofi, Novartis AG, 3M Health Care, Johnson & Johnson, Cardinal Health, Coloplast A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gangrene Market Emerging Trajectories
Advanced wound care is pivoting from passive dressings toward active biological interventions, with reimbursement frameworks struggling to keep pace with technological complexity.
Antimicrobial silver-collagen composite dressings are hybridizing traditional moisture management with sustained ion release, enabling longer wear times and reduced dressing change frequency. Outpatient wound clinics in the United States are adopting these formats at accelerated rates to manage diabetic foot ulcer caseloads. The convergence is compressing demand for conventional gauze and basic hydrocolloid products.
Japan's PMDA has tightened QMS inspection protocols for imported wound care devices, elevating documentation requirements for sterilization validation and biocompatibility testing. Domestic manufacturers with established quality infrastructure are capturing share from foreign entrants facing extended audit cycles. Advanced wound matrix suppliers are responding by establishing in-country technical representation and localized sterilization partnerships.
Hospital supply chains are consolidating vendor relationships for advanced wound care, with integrated dressing-to-device platforms displacing fragmented single-product contracts. Negative pressure wound therapy systems bundled with proprietary dressing kits are capturing preference in United States health system procurement. Germany's hospital procurement cooperatives are driving this consolidation most aggressively, leveraging volume commitments for price transparency.
Gangrene Market Segmentation
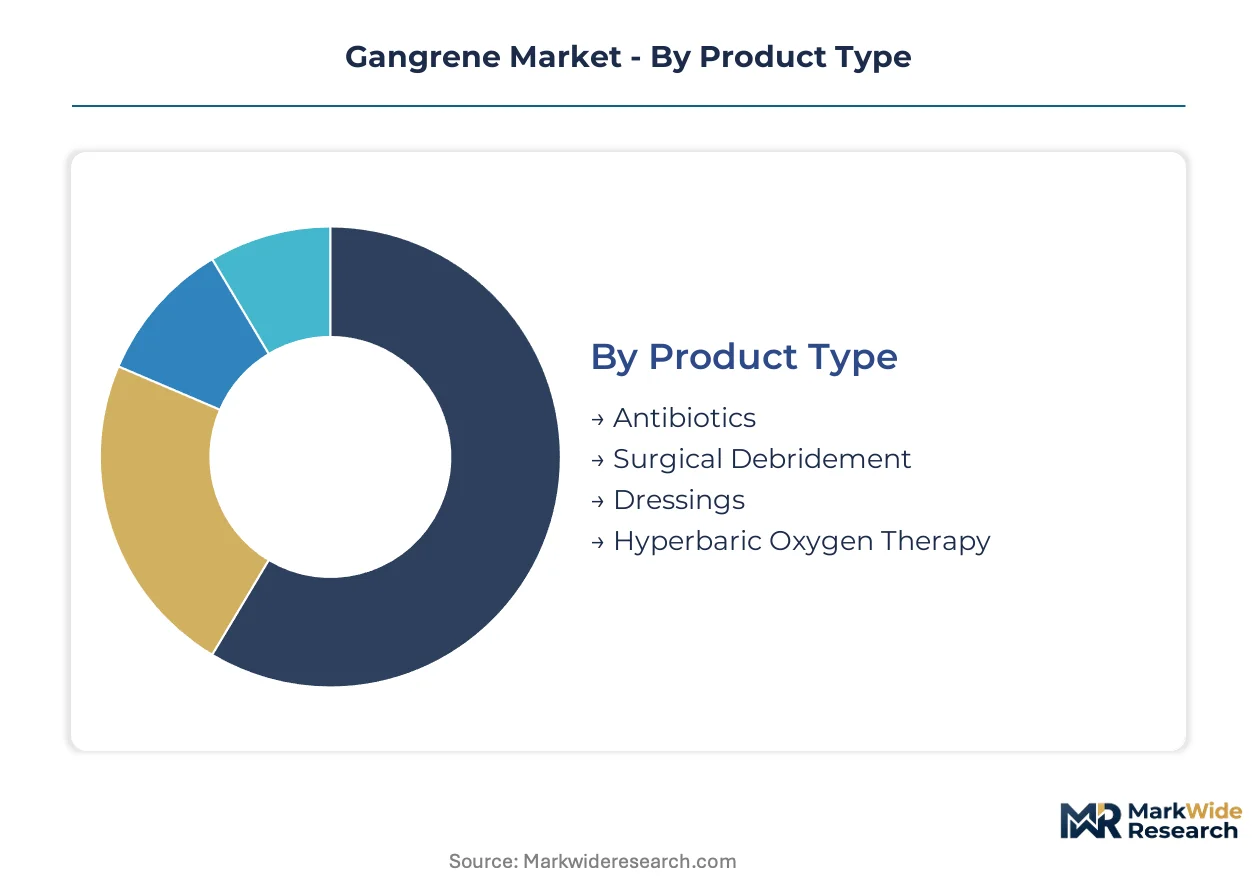
Gangrene treatment markets fragment across intervention intensity, from acute surgical emergency to chronic wound maintenance. Segment boundaries blur as hospitals bundle antibiotics with debridement and hyperbaric protocols into episode-based contracts.
Product Type:
Dressings and hyperbaric systems turn inventory fastest, while surgical platforms and antibiotic formularies anchor longer procurement cycles.
- Antibiotics:Systemic anti-infective protocols rely on broad-spectrum IV formulations for polymicrobial necrotizing infections. Hospital formularies in the United States concentrate procurement through group purchasing organizations, compressing supplier margins through volume consolidation.
- Surgical Debridement:Excisional and autolytic techniques remove necrotic tissue to restore viable wound beds. German tertiary centers command the largest procedural volumes, driven by integrated limb salvage programs for diabetic foot complications.
- Dressings:Antimicrobial silver-impregnated and collagen-based formats manage exudate and bacterial load.
- Hyperbaric Oxygen Therapy:Pressurized chamber systems deliver oxygen at elevated partial pressures to enhance tissue oxygenation.
Surgical debridement dominates installed base. Hyperbaric oxygen therapy is where expansion concentrates.
Application:
Cost tiering separates acute infectious emergencies from chronic vascular management, with trauma cases commanding premium intervention intensity.
- Diabetes:Diabetic foot ulcers constitute the primary addressable pool, with peripheral neuropathy masking early tissue compromise. United States Medicare reimbursement for limb salvage procedures shapes provider economics and technology adoption thresholds.
- Trauma:Crush injuries and compound fractures precipitate acute compartment syndrome requiring emergent fasciotomy. Level I trauma centers in Japan maintain dedicated wound teams for polytrauma necrosis protocols.
- Infectious Diseases:Necrotizing fasciitis and gas gangrene demand urgent surgical source control combined with targeted antimicrobial therapy.
- Vascular Disorders:Peripheral artery disease produces chronic limb-threatening ischemia with insidious tissue loss patterns.
Diabetes anchors revenue concentration. Trauma represents the highest-margin acute intervention profile.
End User:
Patient acuity and reimbursement intensity concentrate in institutional settings, with risk stratification pushing stable cases toward lower-cost venues.
- Hospitals:Tertiary wound care centers integrate vascular surgery, infectious disease, and hyperbaric medicine into multidisciplinary limb salvage programs. FDA 510(k) and PMA pathways govern device procurement standards for these facilities.
- Outpatient Clinics:Dedicated wound clinics manage debridement schedules and dressing changes for stabilized patients. United States health systems are expanding these footprints to reduce emergency department utilization.
- Home Healthcare:Skilled nursing visits support dressing changes and wound surveillance for mobility-limited patients.
- Rehabilitation Centers:Post-acute facilities manage wound healing during functional recovery protocols.
Hospitals capture procedure value. Outpatient clinics are gaining share fastest as site-of-care migration accelerates.
Treatment Type:
Margin structure favors combination protocols that layer device, pharmaceutical, and procedural revenue streams.
- Medical:Pharmaceutical and device-based interventions address infection and moisture balance without operative intervention. EU MDR clinical evidence requirements elevate documentation burdens for antimicrobial dressing claims.
- Surgical:Operative debridement, revascularization, and amputation procedures command facility fees and physician reimbursement. German hospital networks concentrate specialized surgical volume through referral hierarchies.
- Combination Therapy:Integrated medical-surgical protocols pair debridement with advanced dressings and adjunctive hyperbaric sessions. Japan's PMDA QMS inspections shape supply availability for these bundled approaches.
- Palliative Care:Symptom-focused management for non-salvageable limbs emphasizes pain control and infection suppression.
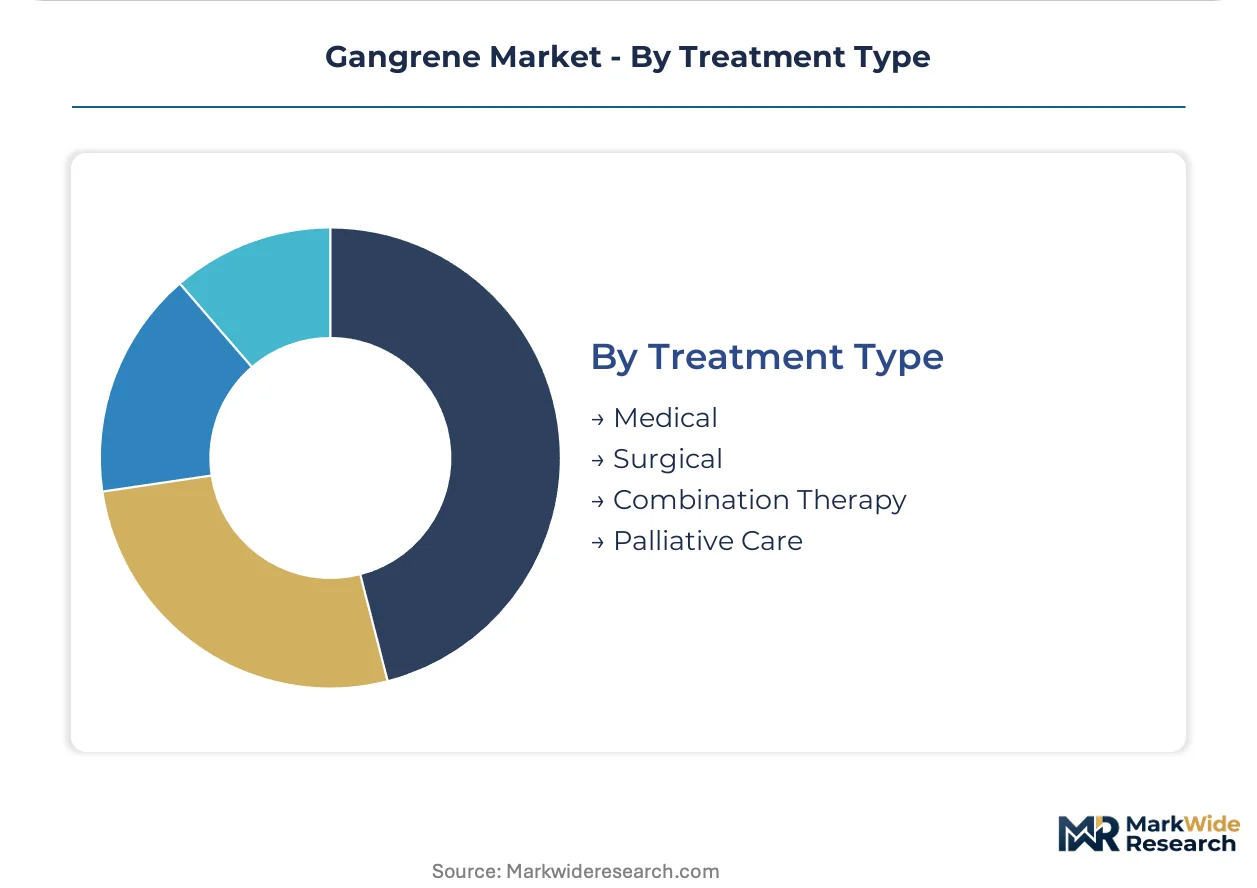
Combination therapy dominates commercial investment. Palliative care remains underaddressed in value-based contracting frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement elasticity varies sharply by geography. United States buyers prioritize clinical efficacy over unit cost for limb salvage protocols. German and Japanese purchasers enforce rigorous quality audits that compress supplier margins regardless of therapeutic differentiation.
United States
Diabetic foot ulcer caseloads drive tertiary wound center expansion across Texas and Florida hospital networks. FDA 510(k) pathways govern advanced dressing clearances with escalating predicate device scrutiny. Limb salvage programs in Houston and Miami concentrate hyperbaric chamber installations for polytrauma necrosis protocols.
Germany
Hospital procurement cooperatives leverage volume commitments to extract price transparency from wound matrix suppliers. EU MDR clinical evidence requirements elevate documentation burdens for antimicrobial dressing reimbursement tiers. Integrated limb salvage networks in Bavaria and North Rhine-Westphalia command the largest procedural volumes for diabetic foot complications.
Japan
Aging demographics expand chronic limb-threatening ischemia addressable pools beyond current diagnostic capture. PMDA QMS inspections enforce stringent sterilization validation protocols for imported advanced wound devices. Tokyo and Osaka tertiary centers maintain dedicated wound teams with established quality infrastructure advantages over foreign entrants.
United Kingdom
NHS cost-effectiveness thresholds compress margins for premium dressing formats despite clinical differentiation. MHRA post-Brexit regulatory divergence creates parallel compliance burdens for EU-registered device suppliers. London and Manchester academic medical centers pilot episode-based contracts bundling debridement with adjunctive hyperbaric sessions.
India
Peripheral artery disease underdiagnosis in rural regions creates latent demand for vascular restoration interventions. CDSCO medical device rules tighten import licensing for advanced wound care products. Maharashtra and Karnataka urban hospital networks concentrate specialized wound care capacity while tier-two cities remain underserved.
Gangrene Market Vendor Landscape
Integrated device-dressing platforms and standalone pharmaceutical suppliers split the market along intervention intensity lines. Consolidation pressures concentrate procurement leverage among United States health systems and German hospital cooperatives. Three archetypes dominate: regenerative tissue matrix specialists, systemic anti-infective manufacturers, and negative pressure therapy integrators. Strategic moves center on bundled therapy contracting and backward integration into pharmaceutical-grade collagen supply.
Among diversified health care conglomerates, Johnson & Johnson and 3M Health Care occupy positions spanning surgical platforms through advanced dressing portfolios. Within the regenerative tissue tier, Integra LifeSciences Corporation exemplifies specialization in wound matrix supply. Smith+Nephew anchors the integrated device-dressing archetype through negative pressure therapy platform dominance. These three represent distinct competitive vectors rather than overlapping market contestation.
| Leading Market Players |
|---|
| Integra LifeSciences Corporation |
| Pfizer Inc. |
| Smith+Nephew |
| Sanofi |
| Novartis AG |
| 3M Health Care |
| Johnson & Johnson |
| Cardinal Health |
| Coloplast A/S |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade collagen processors in the United States and Switzerland concentrate upstream supply for advanced wound matrices, anchoring margin capture in antimicrobial dressing tiers where silver-impregnated formats command premium reimbursement codes.
Pricing Analysis
Aftermarket service contracts for hyperbaric oxygen chamber maintenance drive lifetime value as manufacturers pivot from equipment sales to bundled therapy subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared antimicrobial matrices from basic hydrocolloid formats and commodity gauze. Cost compression in standard-tier dressings is intensifying because German hospital cooperatives extract volume transparency through consolidated procurement. Outpatient wound clinics exhibit highest price sensitivity, while tertiary limb salvage programs prioritize clinical efficacy over unit cost.
Supply Chain Analysis
Export-control restrictions on pressurized vessel technology limit hyperbaric chamber flows from United States and German manufacturers into select markets. Bovine and porcine tissue processors in Switzerland, New Zealand, and the United States anchor raw material supply for collagen matrices. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade collagen extraction. Distribution runs through hospital procurement cooperatives in Germany, group purchasing organizations in the United States, and centralized NHS frameworks in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as site-of-care migration splits demand between tertiary hospitals and outpatient clinics, enabling specialized positioning across intervention intensity tiers.
For Market Incumbents: Build regulatory data moats through EU MDR clinical evidence packages that smaller competitors cannot fund. Anchor backward integration into pharmaceutical-grade collagen supply to neutralize input volatility from Swiss and New Zealand processors. Defend against emerging negative pressure therapy integrators by locking hospital system contracts through bundled dressing-to-device platforms. For New Entrants and Emerging Players: Pursue white-space positioning in rural United States vascular restoration where peripheral artery disease screening remains below diagnostic targets. Target Japanese outpatient wound clinics as the most penetrable venue given PMDA QMS barriers that slow foreign incumbent expansion. Deploy telemedicine-integrated remote patient monitoring as the go-to-market angle for home-based wound surveillance post-discharge. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hyperbaric oxygen therapy chamber manufacturing as hospitals demand integrated software platforms for treatment documentation. Long-term viability favors regenerative tissue matrix specialists with captive collagen supply and established FDA 510(k) predicate libraries. Watch FDA substantial equivalence standard drift as the signal indicating whether clearance timelines will compress or extend competitive windows.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Investment | Secures premium reimbursement tiers across German and French hospital networks for antimicrobial dressing claims. |
| Backward Integration into Collagen Supply | Neutralizes input volatility from concentrated Swiss and New Zealand bovine tissue processors. |
| Hospital System Partnership Contracts | Locks procurement preference through bundled dressing-to-device platforms in United States health systems. |
| Telemedicine Platform Development | Enables remote wound surveillance for outpatient clinic expansion and post-discharge patient monitoring. |
| Japan PMDA QMS Localization | Compresses market access timelines through in-country technical representation and sterilization partnerships. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across wound care procurement, combining primary interviews with hospital purchasing committees, hyperbaric medicine directors, GPO contracts managers, and biomedical engineers with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR technical documentation, and hospital procurement records. Bottom-up patient volume modeling and top-down spending allocation triangulated market sizing across intervention categories.
Calibration against historical procedural volumes and reimbursement rate adjustments anchored projections across the analysis window. Segmentation dimensions included treatment intensity, product format, application etiology, end-user venue, and geographic regulatory cluster. CAGRs derived from procedure growth rates, technology penetration curves, and pricing trajectory assumptions for antimicrobial dressings and hyperbaric therapy sessions.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement policy, EU MDR enforcement intensity, or collagen raw material availability would shift the trajectory. Material shifts in FDA predicate device standards or Japan PMDA audit protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Beta Thalassemia Treatment Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Mexico Hair Transplant Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Cleft Lip Surgery Market
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Hemorrhoids Treatment Market
Medical Treatment
Babesiosis Treatment Market
Medical Treatment
Gallbladder Treatment Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Menopause Treatment Market
Medical Treatment
Europe Chronic Disease Management Market
Medical Treatment
Global Thyroid Disorder Treatment Market