
 Rotator Cuff Injury Treatment Market | 2026-2036
Rotator Cuff Injury Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Rotator Cuff Injury Treatment Market Outlook
Market Context
Modular implant kits is decoupling hardware from biologic adjuncts, forcing buyers to evaluate suture anchors, patch grafts, and cell therapies as separate line items rather than bundled procedures. Johnson & Johnson (DePuy Synthes) leverages its broad orthopedic portfolio to cross-sell biologics with anchor systems, while Arthrex anchors its market position through intensive surgeon education programs that lock in technique-specific purchases. Stryker Corporation competes by controlling hospital GPO channels that prioritize volume-based contract structures.
Technical and Segment Structure
Rotator cuff injury treatment encompasses the clinical management of tendon tears through pharmacologic intervention, structured rehabilitation protocols, arthroscopic surgical repair, and postoperative recovery regimens, with suture anchors typically fabricated from polyetheretherketone, biocomposite polymers, or allograft bone depending on reabsorption requirements and fixation strength demands. The primary commercial purpose centers on restoring glenohumeral joint function while minimizing retear rates that drive costly revision procedures. Surgery leads product type revenue due to high implant and instrument costs per procedure, while telehealth delivery mode represents the fastest-growing structural category as remote physical therapy monitoring expands patient reach without facility overhead. Conservative management through physical therapy occupies the largest patient volume segment but carries thinner margin pools compared to invasive procedures where implant manufacturers capture sustained pricing power.
Regulatory Environment
The FDA 510(k) clearance pathway shapes rotator cuff repair device entry timelines, while the EU MDR's heightened clinical evidence requirements extend certification cycles for suture anchor manufacturers seeking CE marking. Japan's PMDA enforces stringent biocompatibility testing protocols that filter out lower-tier suppliers from the world's third-largest orthopedic market. Stakeholders must monitor how CMS bundled payment expansion for outpatient shoulder procedures reshapes site-of-care economics and implant selection criteria.
Market Dynamics
Modular procurement architectures are fragmenting rotator cuff treatment purchasing decisions, compelling hospital supply chains to negotiate suture anchors, biologic scaffolds, and rehabilitation protocols as discrete spend categories rather than unified procedure bundles.
Growth Catalysts
- Aging surgical populations:Germany, Japan, and the United States are experiencing expanded volumes of arthroscopic shoulder procedures as demographic shifts elevate degenerative tendon pathology incidence.
- EU MDR clinical evidence mandates:The European Union's strengthened Medical Device Regulation is accelerating biocomposite suture anchor development by filtering out legacy metal implants lacking sufficient biocompatibility documentation.
- Outpatient surgery center expansion:Bundled payment models across the American Southeast are incentivizing same-day rotator cuff repair, driving capital equipment procurement for ambulatory surgical facilities.
Market Restraints
- Polyetheretherketone raw material concentration:Medical-grade PEEK resin supply concentrates among a limited cohort of specialized chemical manufacturers, exposing anchor producers to input cost volatility.
- FDA 510(k) pathway friction:The FDA's tightened substantial equivalence standards are extending clearance timelines for novel anchor geometries, compressing product launch windows.
- Conservative management substitution:Structured physical therapy protocols and platelet-rich plasma injections are capturing select patient populations who might otherwise proceed to surgical intervention.
Strategic Opportunities
- Telehealth rehabilitation penetration:Remote physical therapy monitoring platforms are expanding patient reach without facility overhead, creating new recurring revenue streams beyond implant sales.
- Biologics-surgical convergence:Cell therapy adjuncts combined with arthroscopic repair systems are opening premium pricing tiers for complex revision cases.
- Japan PMDA market access:Stringent biocompatibility testing protocols have filtered lower-tier suppliers, creating favorable competitive terrain for established anchor manufacturers with documented safety profiles.
Industry Challenges
- Surgeon training standardization:Technique-specific implant locking creates dependency on intensive education programs, raising customer acquisition costs and retention risk.
- CMS bundled payment complexity:Medicare reimbursement compression for outpatient shoulder procedures is forcing implant selection criteria toward lower-cost alternatives without clear quality differentiation frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotator Cuff Injury Treatment Market |
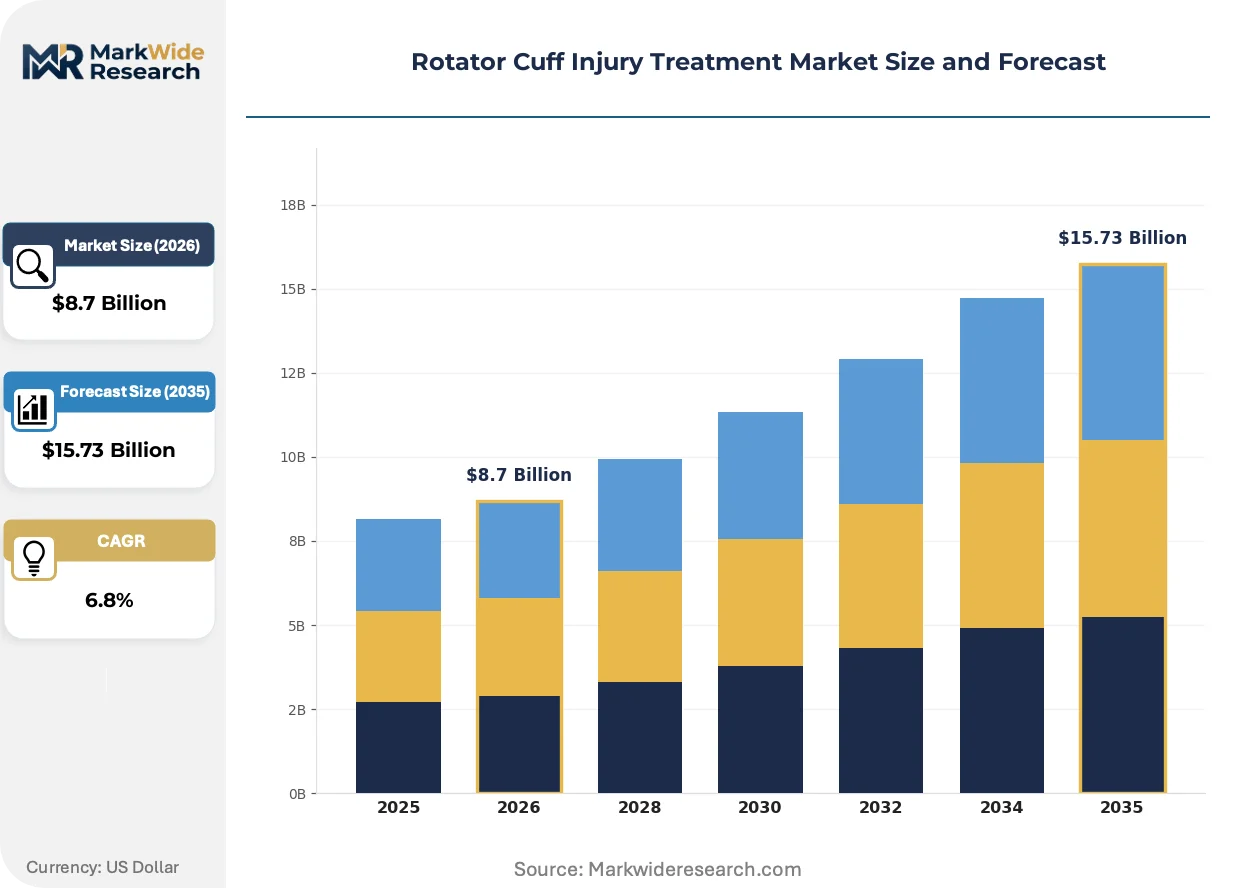
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Initial Care, Physical Therapy, Surgery, Rehabilitation Delivery Mode: In-Person, Telehealth, Outpatient, Home Care End User: Athletes, Older Adults, Pediatric Patients, Occupational Workers Treatment Approach: Conservative Management, Invasive Procedures, Supplementary Therapies, Advanced Techniques |
| Companies Covered | Johnson & Johnson (DePuy Synthes), CONMED Corporation, Arthrex, LimaCorporate, Integra LifeSciences Corporation, Stryker Corporation, Zimmer Biomet, FH ORTHOPEDICS S.A.S., Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotator Cuff Injury Treatment Market Strategic Shifts
Arthroscopic repair systems are undergoing material and digital transformation, with absorbable polymers, biologic augmentation, and remote monitoring platforms restructuring how tendon healing is managed across acute and postoperative phases.
Biocomposite suture anchors fabricated from poly-lactic acid and beta-tricalcium phosphate blends are converging with osteoconductive fixation demands in revision surgery settings. Academic medical centers in Germany and the United States are adopting these materials at accelerated cadence for patients with compromised bone quality. This convergence is compressing market share for traditional polyetheretherketone anchors in high-complexity procedures while opening premium pricing tiers for resorbable alternatives.
The EU MDR's heightened clinical evidence requirements are extending certification cycles for suture anchor manufacturers seeking CE marking. European notified bodies now demand prospective biomechanical data and longitudinal patient outcome registries that exceed legacy documentation standards. Small-to-mid-tier suppliers without dedicated clinical affairs infrastructure are exiting the European market, consolidating procurement options for hospital group purchasing organizations.
Site-of-care economics are restructuring implant selection criteria as CMS bundled payment expansion compresses per-procedure margins. Hospital supply chains are unbundling hardware from biologic adjuncts, forcing separate line-item negotiations for anchors, patch grafts, and cell therapies. This behavioral shift is most visible in the American Southeast, where outpatient surgery centers prioritize inventory velocity over brand loyalty in vendor selection protocols.
Rotator Cuff Injury Treatment Market Segmentation
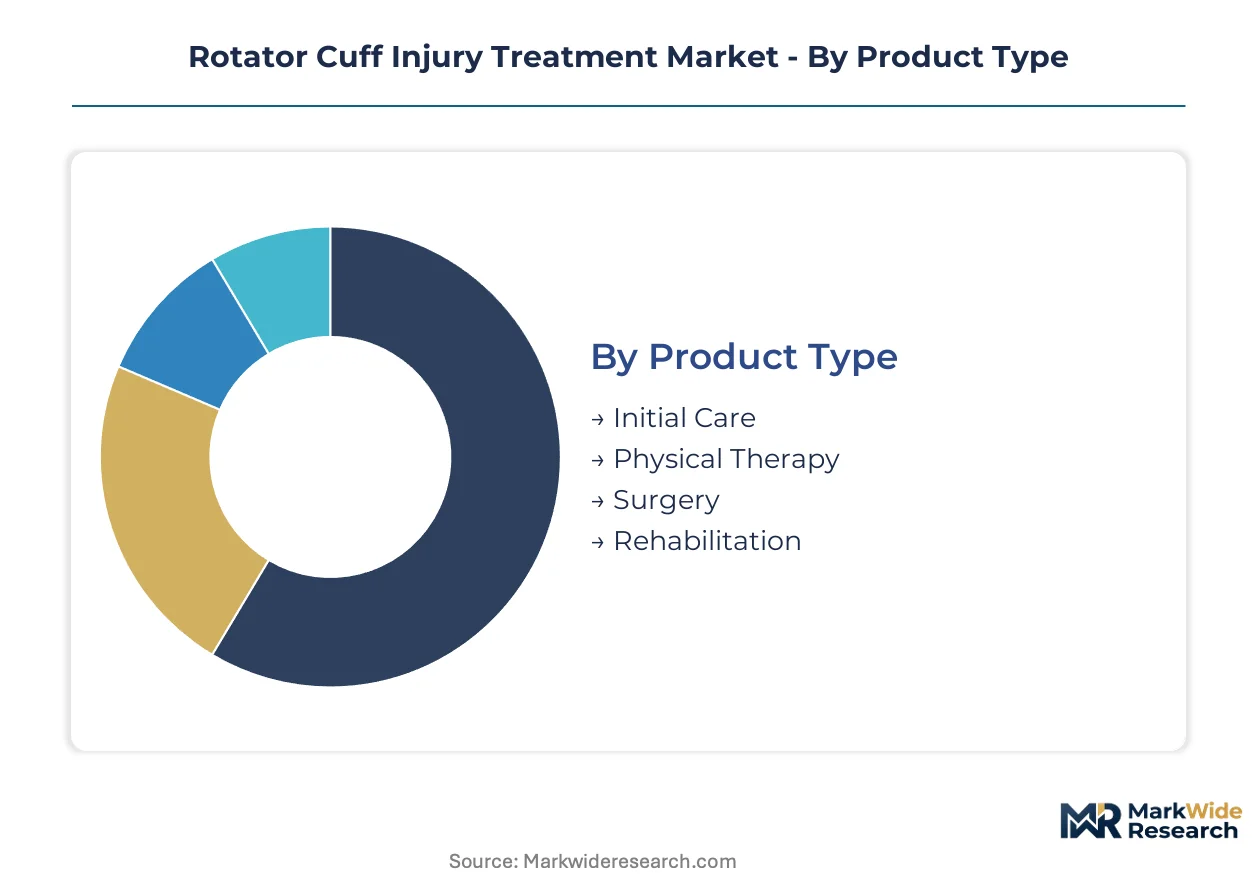
Rotator cuff treatment purchasing fragments across hardware, service delivery, and patient risk profiles. Procurement teams now negotiate implants, rehabilitation protocols, and monitoring platforms as discrete spend categories rather than bundled procedures.
Product Type:
Hospital supply chains evaluate hardware costs against recurring service revenues when allocating procurement budgets across the treatment continuum.
- Surgery:Arthroscopic repair systems command premium pricing through suture anchors fabricated from polyetheretherketone or biocomposite polymers. German and Japanese hospitals prioritize fixation strength metrics when selecting implant systems for aging surgical populations.
- Physical Therapy:Structured rehabilitation protocols occupy the largest patient volume segment but carry thinner margin pools compared to invasive procedures. American Southeast outpatient centers leverage bundled payment models to compress per-session costs while expanding patient throughput.
- Initial Care:Acute pain management and diagnostic imaging establish treatment pathways that determine downstream surgical candidacy.
- Rehabilitation:Postoperative recovery regimens focus on restoring glenohumeral joint function while minimizing costly revision procedures.
Volume sits with Physical Therapy; growth tilts toward Surgery.
Delivery Mode:
Site-of-care economics reshape vendor selection as reimbursement compression forces inventory velocity over brand loyalty.
- Telehealth:Remote physical therapy monitoring platforms eliminate facility overhead while expanding patient reach beyond geographic constraints. CMS bundled payment expansion accelerates adoption across American Southeast ambulatory networks.
- Outpatient:Same-day rotator cuff repair centers in the United States prioritize capital equipment with rapid turnover capabilities. Surgical volume concentrates in specialized facilities that optimize per-procedure economics.
- In-Person:Traditional clinic-based delivery maintains dominance for complex diagnostic and surgical interventions requiring physical presence.
- Home Care:Postoperative recovery support shifts toward residential settings as payers seek to reduce institutional care costs.
Outpatient captures current procedural volume; Telehealth climbs the fastest as remote monitoring platforms scale.
End User:
Demographic risk stratification determines treatment intensity and reimbursement pathways across patient populations.
- Older Adults:Degenerative tendon pathology drives surgical volumes in Germany, Japan, and the United States. Payers scrutinize implant selection criteria as procedure frequency rises with population aging.
- Athletes:High-performance demands accelerate adoption of biologic adjuncts and advanced repair techniques. Sports medicine centers command premium pricing for complex revision cases.
- Occupational Workers:Repetitive strain injuries generate conservative management demand through employer-sponsored health programs.
- Pediatric Patients:Congenital and traumatic presentations require specialized surgical approaches with distinct implant sizing protocols.
Older Adults dominate current caseload; Athletes show steepest expansion trajectory for premium intervention categories.
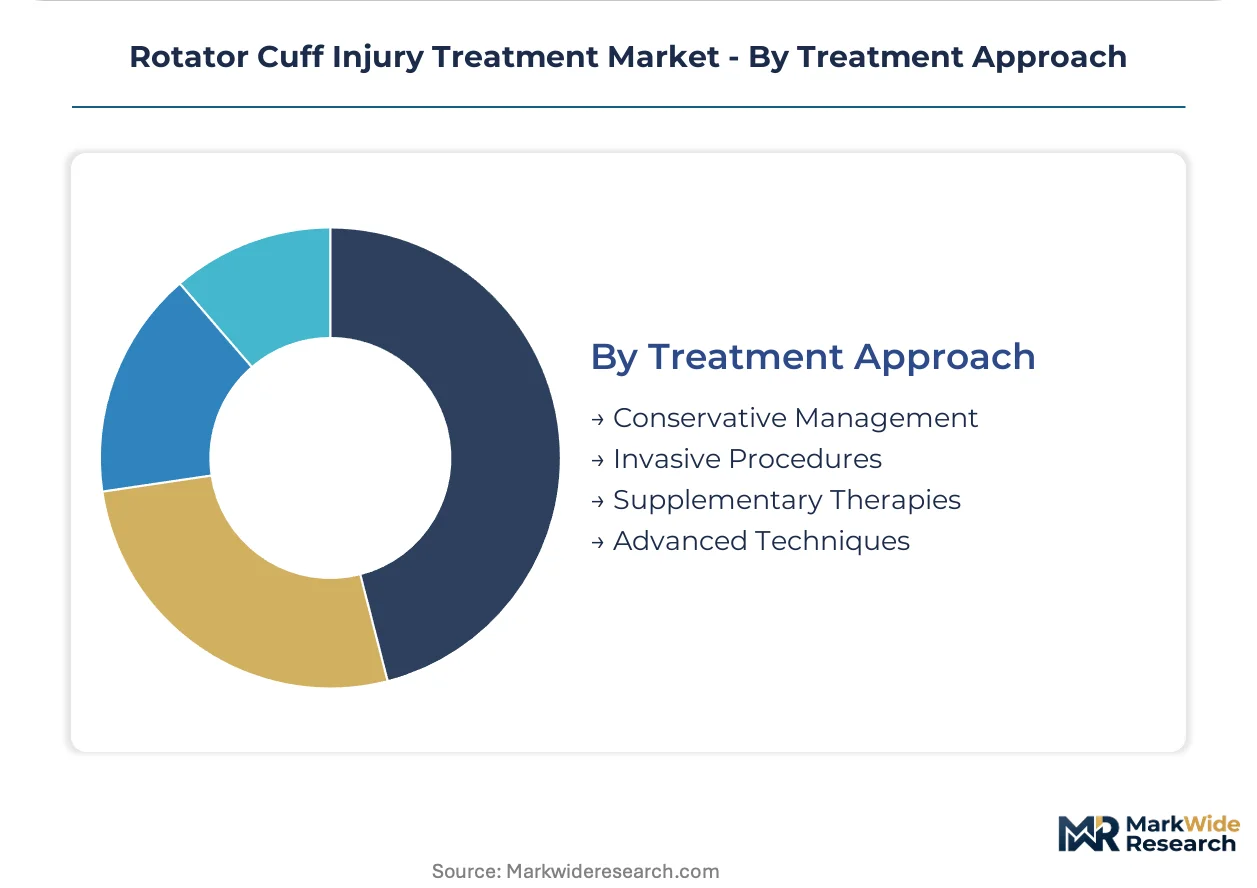
Treatment Approach:
Clinical decision frameworks balance retear risk against cost containment pressures when selecting intervention intensity.
- Conservative Management:Structured physical therapy and pharmacologic intervention capture select patient populations who might otherwise proceed to surgical intervention. Platelet-rich plasma injections compete for early-stage tendon pathology cases.
- Invasive Procedures:Arthroscopic repair with suture anchor fixation delivers sustained pricing power for implant manufacturers. EU MDR clinical evidence mandates filter lower-tier suppliers from European procurement options.
- Supplementary Therapies:Adjunctive modalities including electrical stimulation and cryotherapy support primary treatment protocols.
- Advanced Techniques:Cell therapy convergence with arthroscopic systems opens premium tiers for complex revision surgeries.
Conservative Management holds patient volume; Invasive Procedures gain share fastest as surgical candidacy expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device production concentrates among specialized manufacturers in Germany and the United States, while surgical consumption scales fastest in aging populations across Japan and the American Southeast. Regulatory divergence between the FDA's 510(k) pathway and the EU MDR's clinical evidence mandates is fragmenting market entry strategies by geography.
United States
Outpatient surgery centers across Florida, Georgia, and Texas are expanding same-day rotator cuff repair volumes under CMS bundled payment models. The FDA's tightened substantial equivalence standards are extending clearance timelines for novel anchor geometries. Hospital procurement in the American Southeast prioritizes inventory velocity over brand loyalty as reimbursement compression intensifies.
Germany
Academic medical centers in Munich and Berlin are accelerating adoption of biocomposite suture anchors for patients with compromised bone quality. The EU MDR's heightened clinical evidence requirements are filtering lower-tier suppliers from European procurement options. German hospitals prioritize fixation strength metrics when selecting implant systems for aging surgical populations.
Japan
PMDA's stringent biocompatibility testing protocols are filtering lower-tier suppliers from the world's third-largest orthopedic market. Tokyo and Osaka medical centers command premium pricing for complex revision cases combining cell therapy adjuncts with arthroscopic repair. Degenerative tendon pathology is driving expanded surgical volumes among Japan's elderly population.
United Kingdom
NHS procurement frameworks are unbundling hardware from biologic adjuncts, forcing separate line-item negotiations for anchors and patch grafts. London teaching hospitals are adopting telehealth rehabilitation platforms to expand patient reach without facility overhead. The Medicines and Healthcare products Regulatory Agency is aligning with EU MDR standards for clinical evidence requirements.
Switzerland
Swissmedic's rigorous device certification protocols favor established anchor manufacturers with documented longitudinal safety profiles. Basel and Zurich orthopedic centers specialize in sports medicine applications for high-performance athletes. The country's precision manufacturing base supplies specialized instrumentation for arthroscopic repair systems.
Rotator Cuff Injury Treatment Market Competitive Environment
The competitive structure tilts toward diversified orthopedic conglomerates with cross-selling capabilities across implant and biologic portfolios. Johnson & Johnson, Stryker, and Zimmer Biomet anchor the consolidated tier through hospital GPO channel control and volume-based contract structures. Mid-tier specialists compete through technique-specific surgeon education programs that lock in purchase loyalty. Dominant competitive moves include portfolio diversification into biologics and strategic partnerships with telehealth rehabilitation platforms.
Among diversified orthopedic conglomerates, Johnson & Johnson (DePuy Synthes) exemplifies the cross-selling archetype through its broad portfolio spanning anchors to biologics. Arthrex occupies a position within the surgeon-education specialists, anchoring market presence through intensive technique training programs. Stryker Corporation sits within the channel-control archetype, leveraging hospital GPO relationships that prioritize volume-based procurement structures.
| Leading Market Players |
|---|
| Johnson & Johnson (DePuy Synthes) |
| CONMED Corporation |
| Arthrex |
| LimaCorporate |
| Integra LifeSciences Corporation |
| Stryker Corporation |
| Zimmer Biomet |
| FH ORTHOPEDICS S.A.S. |
| Smith & Nephew |
| Others |
Value Chain & Pricing Dynamics
Medical-grade polyetheretherketone resin flows from specialized chemical manufacturers in Germany and the United States through three-tier pricing structures across premium, standard, and economy levels, with biocomposite polymer alternatives commanding premium positioning due to EU MDR clinical evidence requirements and Japan PMDA biocompatibility protocols.
Pricing Analysis
Margin tightening in economy-tier suture anchors reflects CMS bundled payment expansion across American Southeast outpatient surgery centers. Three-tier pricing structure across premium, standard, and economy levels stratifies by fixation strength metrics and bioresorption profiles, with biocomposite polymers carrying ISO 13485 certification premiums. Cost-down pressure on standard-tier PEEK anchors accelerates because hospital GPO contracts prioritize volume-based procurement structures. Outpatient surgery centers exhibit highest price sensitivity; academic medical centers in Germany and Japan show lowest sensitivity due to fixation performance requirements.
Supply Chain Analysis
Freight cost volatility from specialty polymer producers in Germany, the United States, and Japan elevates landed costs for biocomposite suture anchor manufacturers serving European and Asia-Pacific markets. Raw material sourcing draws from medical-grade PEEK resin, poly-lactic acid, and beta-tricalcium phosphate concentrate. Single-source vulnerability concentrates among limited cohorts of FDA-registered polymer compounders. Distribution runs through hospital GPO channels and specialized orthopedic distributors serving ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR clinical evidence mandates and FDA 510(k) pathway friction are forcing consolidation among mid-tier suture anchor suppliers lacking dedicated clinical affairs infrastructure.
For Market Incumbents: To counter surgeon training standardization costs that lock in technique-specific purchases, Johnson & Johnson and Stryker should deepen backward integration into biocomposite polymer compounding while expanding CE marking documentation for resorbable anchor portfolios. Channel control through hospital GPO relationships remains the priority defensive lever against pricing compression. For New Entrants and Emerging Players: Capture telehealth rehabilitation platform partnerships as white-space entry points, targeting American Southeast bundled payment networks where remote physical therapy monitoring lacks established vendor relationships. Japan PMDA market access offers secondary penetration opportunity given filtered competitive terrain. Lead with software companion development for postoperative recovery tracking rather than hardware commodity positioning. For Investors and Strategic Acquirers: Small-to-mid-tier supplier exit from European markets under EU MDR pressure is the leading indicator that biocomposite anchor manufacturing assets with documented longitudinal safety profiles will command scarcity premiums. Five-to-ten year viability favors established manufacturers with integrated clinical affairs and regulatory submission capabilities. Watch FDA 510(k) clearance timeline extensions as signal for distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Biocomposite Anchor Development | EU MDR clinical evidence mandates filter metal legacy implants from European procurement options. |
| Telehealth Platform Partnership | Remote physical therapy monitoring expands patient reach without facility overhead across American Southeast networks. |
| Surgeon Education Program Expansion | Technique-specific implant locking creates dependency that secures recurring purchase loyalty from orthopedic specialists. |
| Japan PMDA Regulatory Submission | Stringent biocompatibility testing protocols create favorable competitive terrain for documented safety profiles. |
| Hospital GPO Contract Consolidation | Volume-based procurement structures prioritize inventory velocity over brand loyalty in vendor selection protocols. |
Study Parameters
Multi-period observation of arthroscopic procedure volumes, suture anchor procurement patterns, and telehealth rehabilitation adoption rates anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, Japan PMDA submission records, and CMS bundled payment expansion filings. Bottom-up implant shipment modeling and top-down hospital expenditure analysis provided triangulation checks.
Input-output matrices structured volume and value projections across product type, delivery mode, end user risk profile, and treatment approach dimensions throughout the forecast period. CAGRs derived from procedure volume elasticity to aging demographic shifts, reimbursement pathway evolution, and material substitution curves for biocomposite polymers. Industry-specific inputs incorporated EU MDR certification cycle extensions and PMDA biocompatibility testing protocol changes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA substantial equivalence standard revisions and CMS outpatient shoulder procedure reimbursement compression. Forecasts reflect documented assumptions about surgical candidacy expansion and material innovation adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Single-Dose Therapy Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Postoperative Nausea and Vomiting (PONV) Management Market
Medical Treatment
Gallbladder Treatment Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Peripheral Nerve Injuries Market
Medical Treatment
Urea Cycle Disorders Treatment Market
Medical Treatment
Global Leukapheresis Market
Medical Treatment
Radiation Proctitis Treatment Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Adenomyosis Treatment Market
Medical Treatment
Infertility Treatment Market
Medical Treatment
Scabies Treatment Market