
 Knee Arthrodesis Implant Market | 2026-2036
Knee Arthrodesis Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Knee Arthrodesis Implant Market Foresight
EU MDR is consolidating the cost-of-entry calculus for knee arthrodesis implant manufacturers seeking European market access. Zimmer Biomet Holdings Inc leverages its broad orthopedic portfolio to sustain clinical trial infrastructure across multiple regulatory jurisdictions. Smith & Nephew anchors its competitive stance through specialized extremities and trauma hardware that competes directly in arthrodesis applications. Stryker Corporation dominates the North American hospital channel through integrated contract structures that control procurement decisions.
Knee arthrodesis implants are permanent orthopedic fixation devices designed to achieve bony fusion of the tibiofemoral joint through intramedullary nails, external fixation systems, or plate-screw constructs, typically manufactured from titanium alloys or stainless steel with surface treatments to enhance osseointegration. Their primary purpose is to eliminate motion and provide durable limb salvage for patients with failed total knee arthroplasty, severe periarticular infection, or catastrophic peri-prosthetic fracture. Metal implants occupy the largest revenue share due to established biomechanical performance and surgeon familiarity, while hybrid implants represent the fastest-growing category as manufacturers combine titanium structural elements with polymer bearing surfaces to modulate stress shielding. Hospitals remain the dominant end-user setting for complex revision arthrodesis procedures, though surgical centers are capturing an expanding volume of straightforward primary fusions.
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards govern implant biocompatibility, mechanical testing, and clinical performance claims across the two largest addressable markets. ISO 5832 materials specifications and ASTM F138 standards for surgical stainless steel establish baseline metallurgical properties that all commercially viable devices must satisfy. Stakeholders must monitor evolving CMS reimbursement determinations for arthrodesis procedures relative to above-knee amputation alternatives, as coverage decisions will directly influence surgeon preference and hospital capital allocation for implant inventory.
Market Dynamics
The knee arthrodesis implant market pivots on Medicare reimbursement arbitrage between limb salvage and amputation alternatives, with CMS coverage determinations directly shaping surgeon case selection and hospital inventory commitments across the United States.
Growth Catalysts
- Revision knee arthroplasty volume:Failed primary replacements generate a steady pipeline of candidates for fusion procedures, particularly among aging populations with multiple comorbidities.
- Ambulatory surgical center expansion:Payer pressure to reduce episode costs is migrating straightforward primary arthrodesis cases out of inpatient settings.
- EU MDR harmonization:Stricter technical documentation requirements are consolidating manufacturer bases and elevating barriers for marginal competitors.
Market Restraints
- Titanium alloy supply concentration:Primary sponge production clusters in limited jurisdictions, exposing device makers to input price volatility and export control risks.
- Above-knee amputation substitution:Vascular surgeons increasingly favor definitive amputation with modern prosthetic fitting over prolonged limb salvage attempts.
- FDA 510(k) clinical evidence escalation:Premarket notification pathways now demand more robust mechanical testing data, extending development timelines.
Strategic Opportunities
- Surgical center channel penetration:Orthopedic clinics with dedicated implant consignment programs can capture migrating procedure volume.
- Hybrid construct innovation:Combining titanium intramedullary nails with polymer bearing surfaces addresses stress shielding in osteoporotic bone.
- IRArisk corridor structures:Hospital systems participating in bundled payment models gain incentive to standardize on high-reliability implant suppliers.
Industry Challenges
- Surgeon training pipeline gaps:Complex revision arthrodesis demands fellowship-level expertise in deformity correction and infection management, with limited accredited programs.
- EU MDR notified body capacity:Technical file review backlogs are delaying certificate renewals and freezing new product introductions.
- Legacy EHR integration:Implant tracking systems must interface with hospital inventory platforms that lack standardized orthopedic device taxonomies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knee Arthrodesis Implant Market |
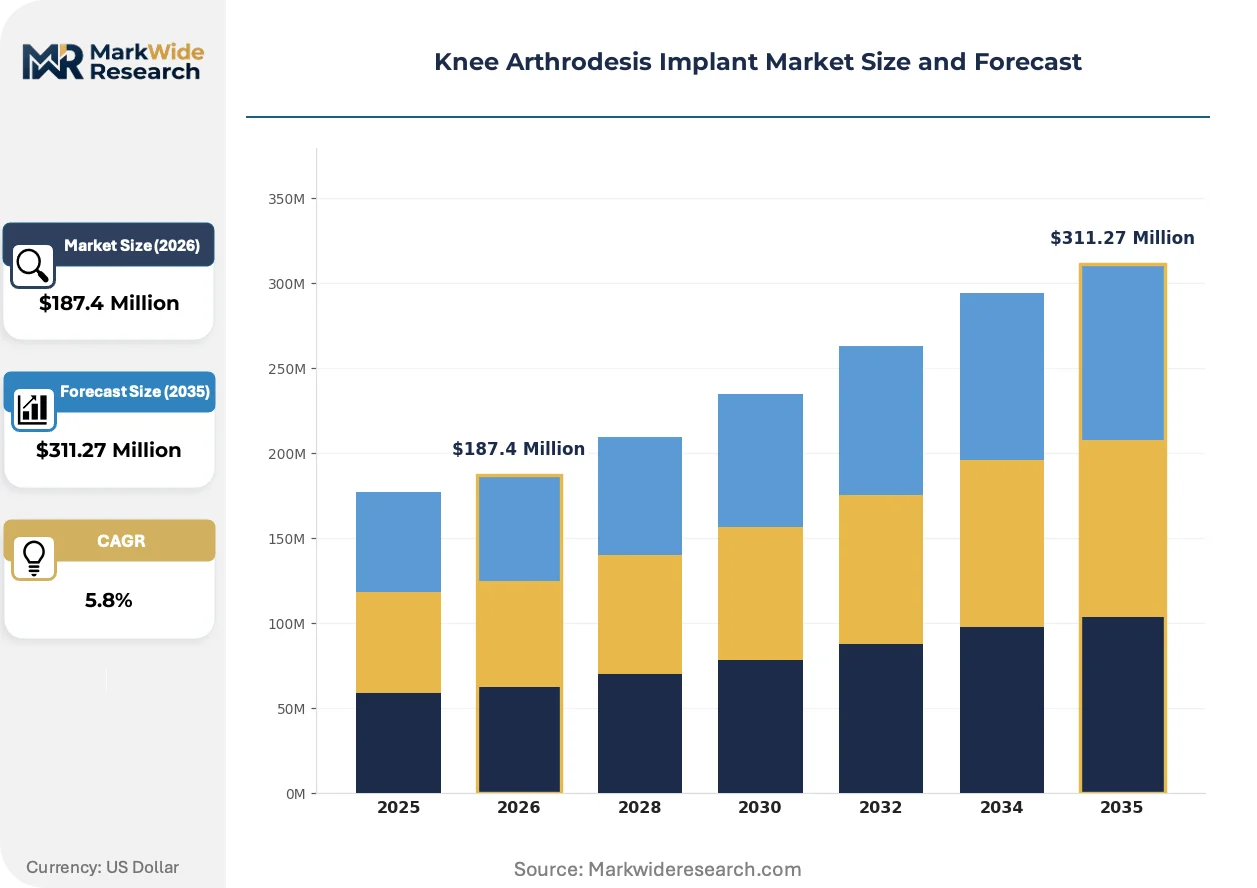
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Implants, Biodegradable Implants, Polymer Implants, Hybrid Implants End User: Orthopedic Clinics, Hospitals, Surgical Centers, Rehabilitation Facilities Material: Titanium Alloys, Stainless Steel, Polyether Ether Ketone, Carbon Fiber Application: Post-Traumatic Conditions, Osteoarthritis, Congenital Deformities, Revision Procedures |
| Companies Covered | Zimmer Biomet Holdings Inc, Smith & Nephew, Stryker Corporation, B. Braun Melsungen AG, DePuy Synthes, Medacta International, MicroPort Scientific Corporation, CONMED Corporation, Exactech Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knee Arthrodesis Implant Market Shifts & Advancements
Patient-specific instrumentation and additive manufacturing are collapsing the traditional trade-off between anatomic fit and operative efficiency, compressing case times while expanding treatable deformity complexity.
Patient-matched cutting guides derived from preoperative CT datasets are rewriting operative planning workflows for complex multiplanar deformities. Academic medical centers with embedded 3D printing laboratories are deploying these guides for salvage cases with severe bone loss. The technology is compressing fluoroscopy exposure and reducing revision rates in high-complexity fusions.
EU MDR Article 117 requirements for implantable devices are forcing manufacturers to recertify legacy products under strengthened clinical evaluation standards. Small-to-mid-cap orthopedic firms without dedicated regulatory affairs infrastructure are exiting the European market entirely. The regulation is concentrating market access among holders of robust quality management system certificates.
Hospital value analysis committees have displaced individual surgeon preference as the dominant implant selection mechanism in integrated delivery networks. These committees now mandate objective performance metrics and standardized vendor contracts. The shift is most visible in Medicare Advantage–dominated markets where capitated risk structures align procurement with total cost of care.
Knee Arthrodesis Implant Market Segmentation
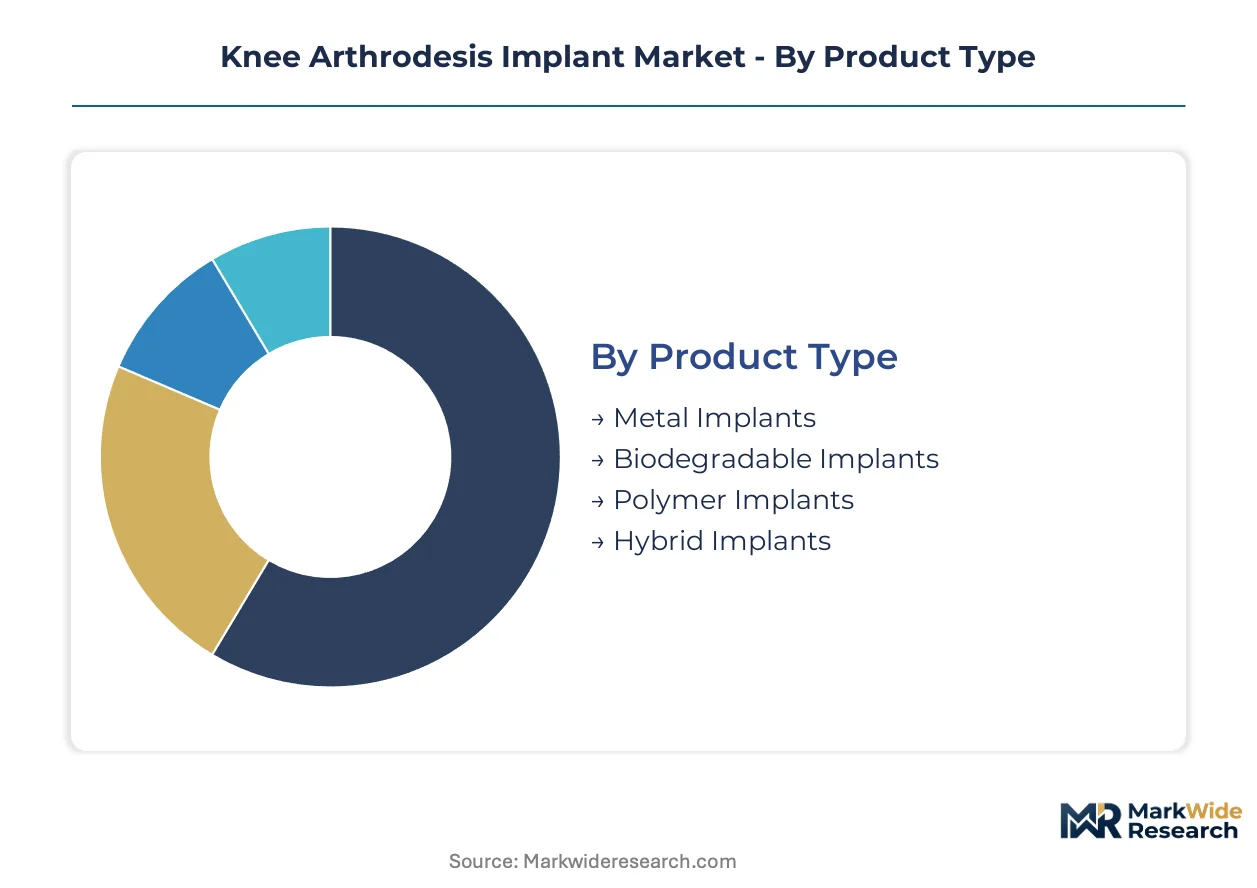
Segmentation in knee arthrodesis implants reveals how surgeon training, facility economics, and patient acuity stratify demand across hardware configurations and clinical settings. Each dimension exposes distinct procurement behaviors and reimbursement pathways that manufacturers must navigate.
Product Type:
Cost tier separates commodity fixation from premium hybrid systems that command differentiated pricing.
- Metal Implants:Titanium alloy and stainless steel constructs deliver established compressive strength for load-bearing fusion. Demand concentrates in United States academic medical centers managing complex revision cases where biomechanical reliability overrides cost sensitivity.
- Hybrid Implants:Titanium structural cores paired with polymer bearing surfaces modulate stress shielding in osteoporotic bone. Orthopedic clinics in Medicare Advantage–dominated markets are adopting these for straightforward primary fusions where accelerated ambulation drives episode economics.
- Biodegradable Implants:Magnesium-based fixation resorbs post-fusion, eliminating secondary removal procedures. Limited commercial penetration reflects unresolved degradation rate control in synovial environments.
- Polymer Implants:PEEK constructs offer radiolucency for postoperative imaging assessment. Niche applications in infection salvage where metal suppression of MRI diagnostics complicates surveillance.
Metal implants lead volumes today; hybrid configurations are gaining share fastest.
End User:
Customer type determines case complexity, capital equipment requirements, and contract negotiation leverage.
- Hospitals:Inpatient facilities manage multiplanar deformities, active infections, and bone loss requiring extended operative times. United States hospital systems with bundled payment contracts prioritize implant standardization to reduce supply chain variance.
- Orthopedic Clinics:Ambulatory settings capture straightforward primary arthrodesis with dedicated implant consignment programs. Payer pressure to reduce episode costs accelerates volume migration toward these lower-acuity venues.
- Surgical Centers:Focused orthopedic facilities with limited overnight capacity select patients with minimal comorbidity burden. Growth constrained by anesthesia infrastructure for tourniquet-dependent procedures.
- Rehabilitation Facilities:Post-acute settings influence implant selection indirectly through prosthetic fitting protocols and weight-bearing progression timelines. Coordination with index procedure sites remains fragmented.
Hospitals retain the dominant revenue position; orthopedic clinics are expanding most quickly.
Material:
Supply concentration and metallurgical specifications differentiate procurement risk across substrate categories.
- Titanium Alloys:Ti-6Al-4V and Ti-6Al-7Nb formulations dominate intramedullary nail construction. Sponge production concentration in limited jurisdictions exposes device makers to export control volatility and input price swings.
- Stainless Steel:ASTM F138-compliant 316L variants persist in plate-screw constructs for cost-sensitive markets. Surgeon familiarity sustains demand despite inferior fatigue performance versus titanium.
- Polyether Ether Ketone:High-performance polymer enables radiolucent fixation with modulus approaching cortical bone. Adoption limited by higher material cost and machining complexity.
- Carbon Fiber:Composite reinforcement in experimental hybrid constructs addresses stress shielding. Commercial scale constrained by manufacturing reproducibility and sterilization compatibility.
Titanium alloys command the largest material spend; PEEK substrates are climbing the fastest.
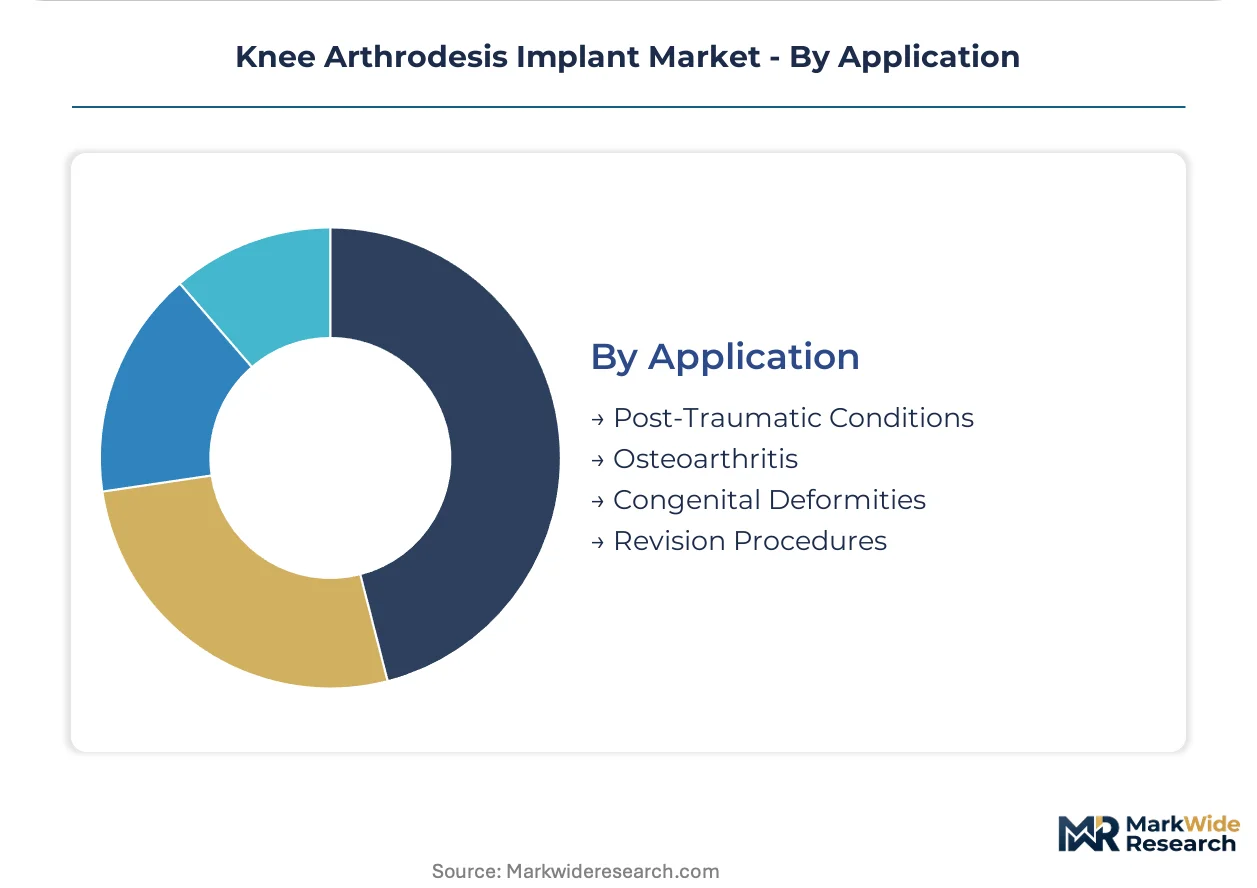
Application:
Clinical indication determines bone quality, fixation durability requirements, and salvage versus primary procedure economics.
- Revision Procedures:Failed total knee arthroplasty with component loosening, infection, or periprosthetic fracture demands extensive hardware and biologic adjuncts. United States Medicare reimbursement arbitrage between limb salvage and amputation shapes case selection.
- Post-Traumatic Conditions:High-energy periarticular fractures with articular comminution require acute fusion for limb salvage. Trauma centers with fellowship-trained surgeons concentrate this volume.
- Osteoarthritis:End-stage degenerative disease in patients unsuitable for arthroplasty represents straightforward primary fusion candidates. Migration toward ambulatory surgical settings most pronounced in this segment.
- Congenital Deformities:Limb length discrepancy and angular deformity in pediatric or young adult populations necessitate growth-considerate fixation. Limited addressable volume due to rarity and alternative osteotomy approaches.
Revision procedures generate the highest implant revenue per case; post-traumatic applications are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthopedic surgeon density and revision arthroplasty fellowship programs concentrate demand in markets with established academic medical centers. Medicare reimbursement arbitrage between limb salvage and amputation alternatives shapes case selection economics. Titanium sponge supply chains and EU MDR notified body capacity constrain manufacturer market access strategies.
United States
Medicare Advantage capitated contracts and bundled payment models drive hospital value analysis committee standardization on high-reliability implant suppliers. FDA 510(k) premarket notification pathways govern biocompatibility and mechanical testing requirements for permanent implantable devices. The Midwest surgical corridor spanning Cleveland Clinic and Mayo Clinic systems anchors complex revision arthrodesis volume.
Germany
EU MDR technical documentation standards and notified body certificate renewal backlogs are consolidating manufacturer bases and elevating barriers for marginal competitors. The country's national pharmaceutical regulator enforces strengthened clinical evaluation standards under Article 117 for implantable devices. The Baden-Württemberg medical technology cluster around Tübingen and Stuttgart hosts orthopedic hardware specialists with embedded regulatory affairs infrastructure.
Switzerland
Swissmedic quality management system certificates and precision manufacturing heritage sustain premium implant positioning in European markets. The national pharmaceutical regulator maintains parallel recognition pathways with EU MDR to preserve market access continuity. The Lake Geneva arc from Lausanne to Geneva concentrates orthopedic research institutions and specialized trauma centers.
China
NMPA medical device registration pathways and volume-based procurement reforms are reshaping pricing dynamics for imported orthopedic hardware. The national pharmaceutical regulator accelerates review timelines for innovative devices while standardizing reimbursement catalogs. The Yangtze River Delta surgical corridor spanning Shanghai and Suzhou generates rising revision arthroplasty caseloads from aging urban populations.
Japan
PMDA medical device approval processes and national health insurance reimbursement determinations govern implant adoption timelines. The national pharmaceutical regulator emphasizes post-market surveillance data for permanent implantable devices. The Kanto metropolitan cluster around Tokyo anchors the highest concentration of orthopedic fellowship-trained surgeons in the Asia-Pacific region.
Knee Arthrodesis Implant Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the knee arthrodesis implant landscape, creating a tiered structure where scale-driven portfolio breadth confronts targeted extremities expertise. Market concentration reflects regulatory compliance infrastructure requirements under FDA and EU MDR frameworks rather than manufacturing scale economies alone. Three archetypes dominate: integrated orthopedic conglomerates with trauma and extremities divisions, specialized arthrodesis hardware manufacturers, and emerging Asia-Pacific fabricators with cost-optimized titanium processing. Competitive dynamics center on M&A activity to acquire regulatory certificate portfolios and strategic partnerships with academic medical centers for clinical evidence generation.
Among diversified orthopedic conglomerates, Zimmer Biomet Holdings Inc and Stryker Corporation exemplify the integrated archetype with broad trauma and extremities portfolios spanning multiple regulatory jurisdictions. Smith & Nephew occupies a focused position within extremities and trauma hardware that competes directly in arthrodesis applications. These three entities represent the dominant competitive anchors, with their market positions shaped by hospital contract structures and value analysis committee relationships rather than product differentiation alone.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings Inc |
| Smith & Nephew |
| Stryker Corporation |
| B. Braun Melsungen AG |
| DePuy Synthes |
| Medacta International |
| MicroPort Scientific Corporation |
| CONMED Corporation |
| Exactech Inc |
| Others |
Supply & Pricing Matrix
Fellowship-trained orthopedic surgeons concentrated in the Midwest United States surgical corridor command premium compensation differentials that widen pricing spreads between academic medical centers and ambulatory surgical centers. Labor-cost arbitrage between high-complexity revision settings and straightforward primary fusion venues stratifies implant procurement across three distinct tiers.
Pricing Analysis
Bundled payment models for arthrodesis episodes now dominate hospital procurement, while unbundled component pricing persists in orthopedic clinics with implant consignment arrangements. Three-tier pricing structure across premium hybrid systems, standard titanium constructs, and economy stainless steel plates reflects FDA 510(k) clearance tier and biomechanical testing depth. Price erosion runs through the economy tier as volume-based procurement reforms in China compress margins for commodity fixation. Medicare Advantage–dominated markets exhibit highest price sensitivity, while academic medical centers with bundled contracts prioritize reliability over unit cost.
Supply Chain Analysis
Direct-to-hospital channels with dedicated implant representatives handle complex revision cases requiring real-time inventory support, while distributor-mediated supply serves smaller orthopedic clinics. Titanium sponge production concentrates in China, Russia, and Japan, exposing device makers to export control volatility and input price swings. Raw material dependencies center on Ti-6Al-4V alloy feedstock, polymer bearing substrates, and precision-machined locking mechanisms. Single-source vulnerability in titanium sponge refining creates procurement risk for manufacturers without backward integration into primary metal processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The knee arthrodesis implant market represents a late-cycle quality story where surgeon demand is shifting toward hybrid constructs with enhanced osseointegration surfaces and patient-matched instrumentation capabilities.
For Market Incumbents: Cement hospital value analysis committee relationships through standardized vendor contracts that reduce supply chain variance in bundled payment environments. Prioritize EU MDR certificate renewal investments to defend European market access against regulatory consolidation. Threatened by emerging Asia-Pacific fabricators with cost-optimized titanium processing, incumbents must deepen backward integration into precision forging operations. For New Entrants and Emerging Players: Enter via orthopedic clinic channel penetration with dedicated implant consignment programs targeting straightforward primary arthrodesis migration out of inpatient settings. White-space targets include biodegradable magnesium fixation for infection salvage and polymer constructs enabling MRI surveillance. The most penetrable segment sits in Medicare Advantage–dominated ambulatory markets where accelerated ambulation drives episode economics. For Investors and Strategic Acquirers: Diversified orthopedic conglomerates with trauma and extremities divisions are the most active acquirer in this space, seeking regulatory certificate portfolios and clinical evidence infrastructure. Long-term viability hinges on sustained revision arthroplasty volume from aging populations with multiple comorbidities. Watch FDA 510(k) clinical evidence escalation timelines as an inflection indicator for development cost thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certificate Renewal | Technical file review backlogs freeze new product introductions, concentrating market access among certificate holders. |
| Patient-Specific Instrumentation Launch | CT-derived cutting guides compress fluoroscopy exposure and expand treatable deformity complexity in academic centers. |
| Orthopedic Clinic Channel Partnership | Dedicated implant consignment programs capture migrating primary arthrodesis volume under payer pressure. |
| Hybrid Construct R&D Investment | Titanium-polymer combinations modulate stress shielding in osteoporotic bone, commanding premium positioning. |
| Hospital System Standardization Contract | Integrated delivery networks with bundled payment models prioritize high-reliability suppliers to reduce variance. |
Research Methodology
Coverage spans the United States, Germany, Switzerland, China, and Japan, with primary inputs from each market informing demand calibration. The approach combines structured interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement determinations, and hospital procurement records. Bottom-up procedure volume estimates triangulate against top-down implant revenue assessments across the analysis window.
Rate-of-change decomposition separates volume effects from price-mix shifts across product type, end user, material, and application dimensions. The analytical framework models CAGRs through regression-based trending of revision arthroplasty incidence, ambulatory surgical center expansion rates, and regulatory compliance cost trajectories. Key forecast inputs include Medicare Advantage penetration curves, EU MDR notified body capacity constraints, and titanium alloy spot price volatility indices.
Inputs from regulatory filings, hospital procurement databases, and surgeon practice surveys were available through the study window; gaps in real-time implant utilization tracking introduce uncertainty bands around ambulatory setting volume estimates. Forecasts reflect assumptions regarding sustained bundled payment adoption and stable titanium sponge trade flows. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
3D Orthopedic Scanning System Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
Knee Implants Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
Animal External Fixation Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Orthopedic Extremity Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
3D Medical Implant Market
Orthopedic Devices
Orthopedic Consumables Market
Orthopedic Devices
Shoulder Arthroplasty Market