
 Passive Prosthetics Market | 2026-2036
Passive Prosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Passive Prosthetics Market Analytics
Certified prosthetist workforce shortages in North America and Western Europe are unwinding patient access timelines and compressing fitting capacity at major clinical centers. Össur leverages its Icelandic manufacturing base and carbon fiber fabrication expertise to sustain premium socket and liner output across transfemoral and transtibial categories. Ottobock anchors German-speaking markets through its extensive orthotic and prosthetic clinic network, while College Park Industries specializes in articulated foot-ankle systems that dominate trauma and dysvascular amputee segments in the United States.
Passive prosthetics are mechanically non-powered limb replacement devices that rely on gravity, body mass, and ground reaction forces to restore ambulatory function, with contemporary carbon fiber spring energy storage and return systems achieving deflection rates exceeding 90% in gait-cycle laboratory testing. Their primary commercial purpose is to restore basic mobility for amputees who do not qualify for or cannot afford powered bionic alternatives. Transtibial devices lead volume globally due to higher incidence rates and simpler fitting protocols, while carbon fiber laminates command the strongest margin pools among material categories because of raw material scarcity and specialized layup labor. Rehabilitation use cases are expanding fastest as post-acute facilities in OECD markets extend prosthetic fitting into earlier recovery phases.
FDA 510(k) clearance pathways govern passive lower-limb device commercialization in the United States, while the EU Medical Device Regulation requires notified body conformity assessment for CE marking access across European member states. ISO 10328 structural testing standards define static and cyclic load verification protocols that shape R&D investment and product liability exposure for manufacturers. Stakeholders must monitor reimbursement code consolidation at CMS and parallel health technology assessment shifts at EMA-influenced national agencies, as these mechanisms determine whether advanced carbon fiber systems receive adequate procedure pricing against basic aluminum alternatives.
Market Dynamics
Carbon fiber laminate processing advances are compressing device weight-to-strength ratios while statutory reimbursement frameworks in Germany and the US Veterans Affairs system expand access eligibility for advanced passive systems.
Growth Catalysts
- Statutory Health Insurance Reimbursement:Germany's GKV system covers advanced carbon fiber prosthetic systems without prior authorization, eliminating cost barriers for transfemoral and transtibial fittings.
- Veterans Affairs Coverage Expansion:US VA healthcare systems have broadened prosthetic benefit categories for lower-limb amputees, accelerating fitting volumes at designated polytrauma centers.
- Spring Energy Storage Systems:Deflection rates exceeding 90% in gait-cycle laboratory testing enable ambulatory function restoration comparable to early bionic alternatives at substantially lower cost points.
Market Restraints
- Raw Material Scarcity:Aerospace and automotive sectors consume priority allocations of high-modulus carbon fiber tow, constraining prosthetic-grade laminate supply from Toray and Hexcel.
- Certified Prosthetist Bottlenecks:North American and Western European clinical centers face workforce shortages that extend patient access timelines and compress fitting capacity.
- Aluminum Substitution Pressure:Basic aluminum prosthetic systems retain reimbursement preference in emerging markets and cost-constrained public health systems.
Strategic Opportunities
- Post-Acute Rehabilitation Integration:OECD market facilities are extending prosthetic fitting into earlier recovery phases, creating demand for expedited socket fabrication protocols.
- EU Medical Device Regulation Streamlining:MDR Article 120 transition provisions offer notified body conformity assessment pathways that reduce CE marking timelines for established manufacturers.
- Foot-Ankle Articulation Convergence:Integration of hydraulic ankle units with carbon fiber keel designs enables terrain adaptation without powered actuator costs.
Industry Challenges
- ISO 10328 Compliance Burden:Static and cyclic load verification protocols require specialized testing infrastructure that elevates R&D investment thresholds for new market entrants.
- CMS Reimbursement Code Consolidation:Procedure pricing compression for advanced carbon fiber systems against basic alternatives threatens margin sustainability at manufacturing scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passive Prosthetics Market |
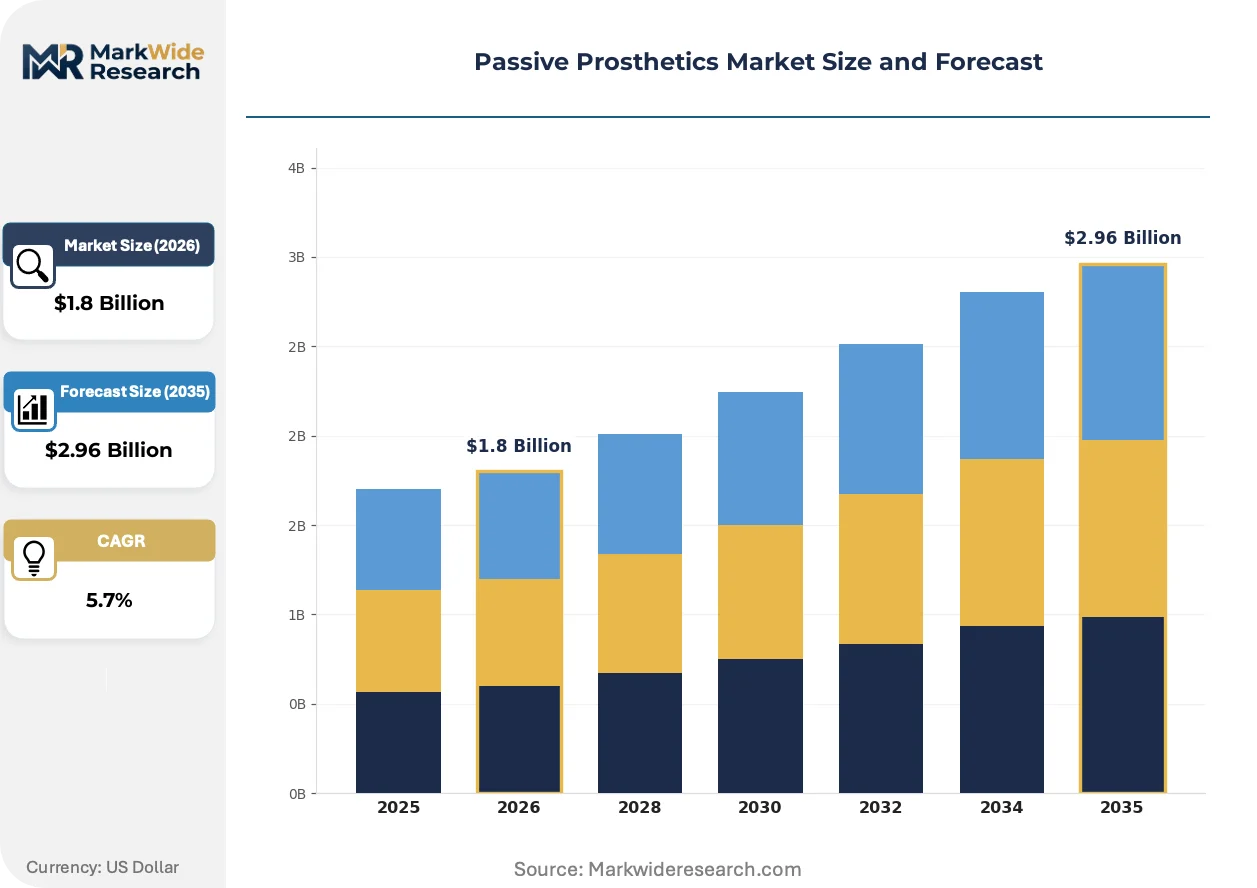
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transfemoral, Transtibial, Partial Foot, Shoulder Disarticulation Material: Carbon Fiber, Thermoplastic, Aluminum, Polyurethane Use Case: Recreational, Daily Living, Rehabilitation, Post-Surgery End User: Hospitals, Rehabilitation Centers, Home Care Providers, Clinics |
| Companies Covered | Össur, Ottobock, Fillauer LLC, WillowWood Global LLC, College Park Industries, Steeper Group, Blatchford Group, Trulife, COAPT LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passive Prosthetics Market Evolving Landscape
Material science breakthroughs and regulatory pathway refinements are restructuring competitive entry barriers while demand-side procurement evolution favors integrated clinical service models over discrete device transactions.
Pre-impregnated carbon fiber layup automation is displacing hand-laminated socket fabrication in high-volume manufacturing operations. German and Icelandic production facilities are adopting robotic fiber placement for transfemoral socket shells, cutting unit labor hours by half. This displacement is compressing cost structures for premium devices while widening the performance gap against aluminum alternatives.
EU Medical Device Regulation notified body capacity constraints are forcing restructuring of CE marking strategies. Manufacturers with existing MDD certificates leverage Article 120 transition timelines to maintain market access, while new entrants face 12-18 month conformity assessment queues. German and Austrian markets exhibit strongest response, with clinic networks consolidating supplier relationships to reduce regulatory exposure.
Hospital procurement departments are consolidating orthotic and prosthetic vendor panels to capture volume-based pricing and streamline clinical support. Integrated service contracts covering fitting, adjustment, and maintenance are replacing discrete device purchases in US academic medical centers and German hospital chains. This consolidation is most visible in trauma and dysvascular amputee segments where episode-of-care accountability pressures dominate.
Passive Prosthetics Market Segmentation
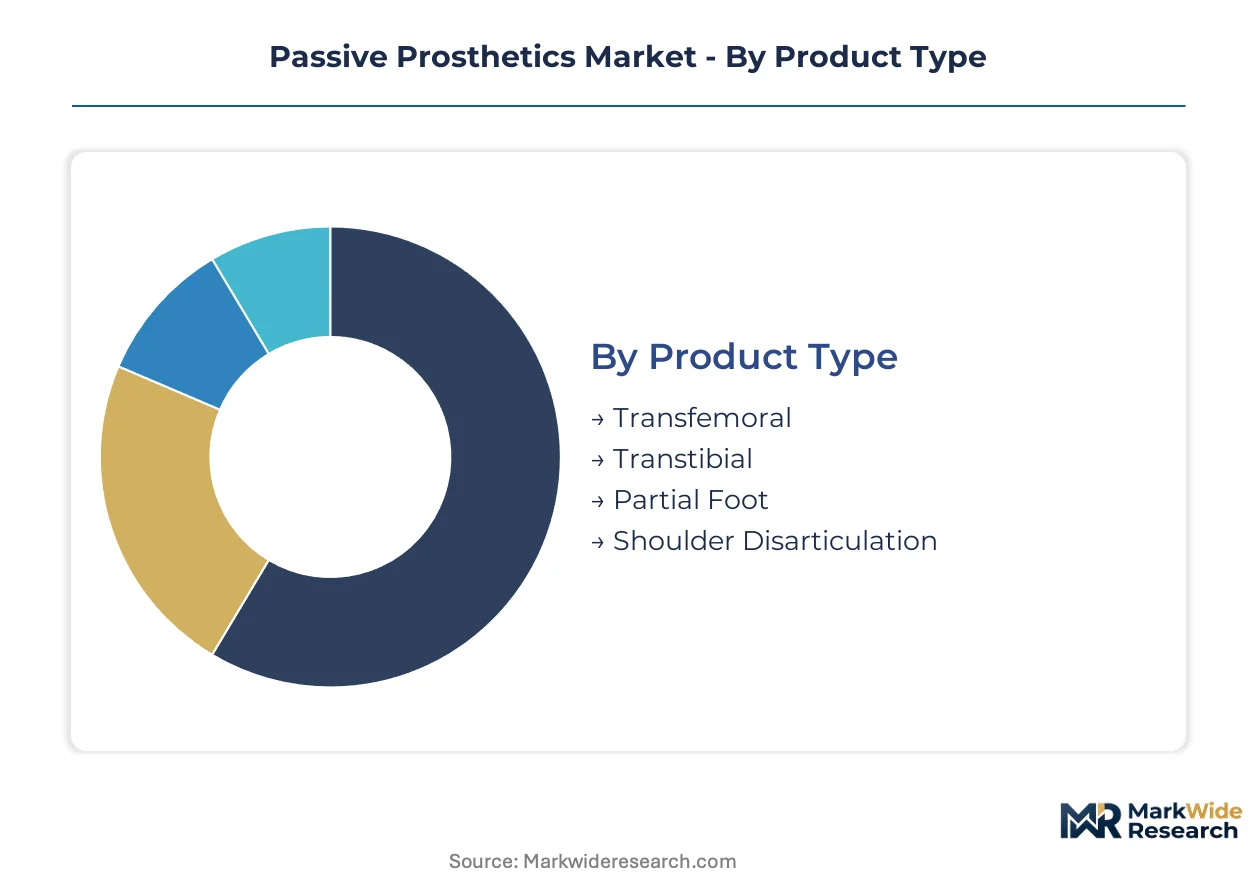
Passive prosthetics demand fragments across anatomical sites, material grades, and care settings. Channel economics and reimbursement tiers determine which configurations reach which patient populations.
Product Type:
Channel mix varies sharply by amputation level, with transtibial devices flowing through high-volume clinic networks and transfemoral systems concentrating at academic medical centers and VA polytrauma facilities.
- Transfemoral:Above-knee configurations incorporate carbon fiber spring energy storage systems with deflection rates exceeding 90%. Demand concentrates at US Veterans Affairs healthcare systems and German statutory insurance-funded fittings, driven by expanded coverage eligibility for advanced socket-liner combinations.
- Transtibial:Below-knee devices represent the highest fitting volumes globally due to elevated dysvascular and trauma incidence. German clinic networks and US rehabilitation centers channel these through expedited socket fabrication protocols that compress patient access timelines.
- Partial Foot:Toe and metatarsal-level prostheses address diabetes-related amputations through custom silicone socket designs.
- Shoulder Disarticulation:Upper-extremity passive systems rely on body-powered harness mechanisms for limited grasp function restoration.
Transtibial devices dominate installed base. Transfemoral is where expansion concentrates.
Material:
Cost tier stratification separates aerospace-grade carbon fiber laminates from commodity aluminum extrusions, with thermoplastic hybrids occupying mid-market positioning.
- Carbon Fiber:High-modulus tow layups achieve superior strength-to-weight ratios for premium transfemoral sockets and energy-return feet. Raw material scarcity from Toray and Hexcel priority allocations to aerospace and automotive sectors constrains prosthetic-grade supply and elevates margin pools.
- Thermoplastic:Polypropylene and polyethylene copolymer sockets enable rapid thermoforming for transtibial fittings in high-volume rehabilitation settings.
- Aluminum:Basic alloy pylons and exoskeletal frames retain reimbursement preference in cost-constrained public health systems and emerging markets.
- Polyurethane:Flexible liner materials interface between residual limb and rigid socket structures to distribute pressure loads.
Carbon fiber commands premium pricing tiers. Aluminum maintains volume leadership in basic coverage categories.
Use Case:
Application urgency shapes procurement velocity, with post-surgical fittings requiring immediate availability and recreational configurations permitting custom fabrication timelines.
- Rehabilitation:Post-acute facilities in OECD markets are extending prosthetic fitting into earlier recovery phases, creating demand for expedited socket fabrication protocols and integrated episode-of-care accountability.
- Daily Living:Standard ambulatory function restoration for community mobility represents the baseline reimbursement category across German GKV and US Medicare frameworks.
- Recreational:Activity-specific devices for running and swimming require specialized energy-return feet and waterproof materials.
- Post-Surgery:Immediate post-operative fittings demand rapid-turnaround thermoplastic sockets for edema management and early mobilization.
Daily Living anchors reimbursement volume. Rehabilitation is climbing the fastest as recovery protocols accelerate.
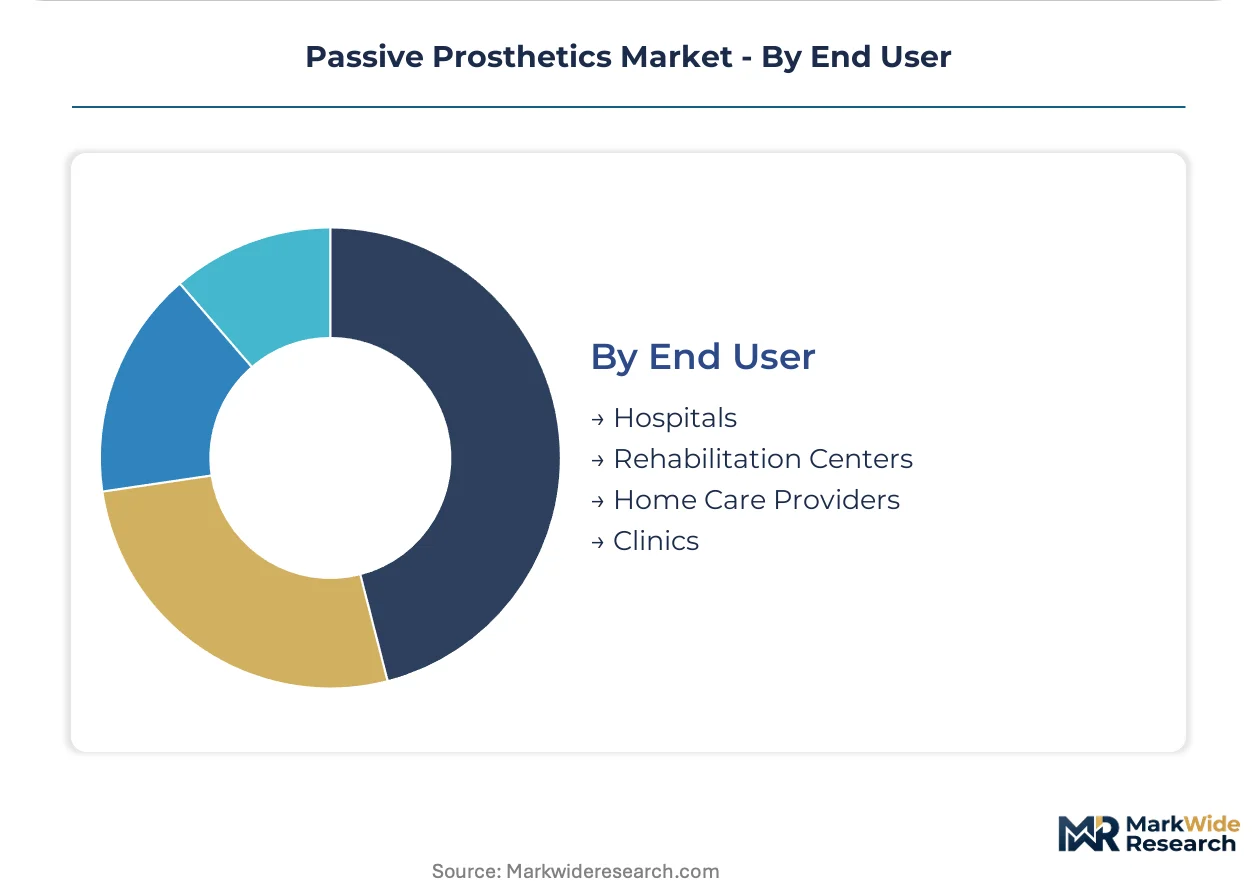
End User:
Customer type determines service intensity, with hospitals demanding integrated fitting-maintenance contracts and home care providers seeking simplified adjustment protocols.
- Rehabilitation Centers:Specialized post-acute facilities in the United States and Germany consolidate orthotic and prosthetic vendor panels to capture volume-based pricing and streamline clinical support through episode-of-care contracts.
- Hospitals:Academic medical centers and trauma centers require rapid-response socket fabrication for acute amputation cases, often specifying carbon fiber systems for younger trauma patients.
- Clinics:Private prosthetic practices handle routine transtibial fittings and maintenance adjustments for established amputees.
- Home Care Providers:Mobile fitting services address mobility-impaired patients unable to travel to clinical facilities.
Rehabilitation Centers concentrate advanced system demand. Hospitals represent the fastest-expanding channel for integrated service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways anchor the United States as the primary regulatory reference for passive prosthetic commercialization, while Germany's statutory reimbursement framework and Iceland's carbon fiber fabrication cluster shape supply-side dynamics across the Atlantic.
United States
Veterans Affairs healthcare systems and academic medical centers drive demand for advanced transfemoral systems. FDA 510(k) clearance governs lower-limb device commercialization, with ISO 10328 structural testing required for liability exposure management. Minneapolis and Salt Lake City host concentrated fitting capacity at designated polytrauma centers.
Germany
Statutory health insurance eliminates prior authorization barriers for carbon fiber prosthetic fittings. EU Medical Device Regulation notified body conformity assessment governs CE marking access, with Article 120 transition provisions benefiting established manufacturers. Duderstadt anchors Ottobock's clinic network dominance across German-speaking markets.
Iceland
Carbon fiber laminate fabrication expertise concentrates manufacturing gravity for premium socket and liner output. EMA-influenced regulatory alignment through EEA integration maintains market access across European member states. Reykjavik-based production facilities supply transfemoral and transtibial categories globally.
United Kingdom
NHS England procurement consolidation favors integrated service contracts over discrete device transactions. MHRA operates as the national regulator for medical device market authorization post-Brexit. Leeds and London concentrate rehabilitation center demand for post-acute fitting protocols.
Japan
Aging demographics and dysvascular amputation incidence expand addressable patient populations for daily living configurations. PMDA governs medical device approval pathways with JIS standards informing structural verification protocols. Osaka and Tokyo metropolitan areas concentrate certified prosthetist workforce capacity.
Passive Prosthetics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidation pressure intensifying as hospital procurement departments consolidate vendor panels. The upper tier combines carbon fiber fabrication expertise with clinic network ownership, while mid-tier players compete on expedited socket fabrication protocols. Strategic archetypes include vertically integrated manufacturers, rehabilitation-focused service contractors, and component specialists. Competitive moves center on M&A for clinic network expansion and strategic partnerships for regulatory pathway navigation.
Among Icelandic and German fabricators, Össur and Ottobock occupy positions exemplifying the integrated leader archetype, with College Park Industries representing the specialized foot-ankle system segment. These three anchors demonstrate how geographic clustering around carbon fiber expertise and statutory reimbursement frameworks shapes competitive positioning.
| Leading Market Players |
|---|
| Össur |
| Ottobock |
| Fillauer LLC |
| WillowWood Global LLC |
| College Park Industries |
| Steeper Group |
| Blatchford Group |
| Trulife |
| COAPT LLC |
| Others |
Value Network & Pricing Analysis
Carbon fiber laminate fabrication scale in Icelandic and German facilities compresses per-unit fixed costs while elevating minimum efficient scale thresholds for new socket and liner producers. This concentration anchors price floors for premium transfemoral systems and amplifies margin pressure on aluminum alternatives in cost-sensitive reimbursement categories.
Pricing Analysis
German statutory health insurance reimbursement spreads diverge sharply from US Veterans Affairs contracted rates, with CMS Medicare pricing occupying a mid-tier position. Three-tier pricing structure across premium carbon fiber, standard thermoplastic, and economy aluminum levels separates patient access tiers by amputation complexity and coverage eligibility. Cost compression in basic aluminum categories intensifies because emerging markets retain reimbursement preference for legacy alloy systems. Rehabilitation centers and hospital procurement departments exhibit lowest price sensitivity due to episode-of-care bundling, while home care providers face acute pressure from direct patient cost-sharing.
Supply Chain Analysis
Inventory cycles for high-modulus carbon fiber tow extend 16-20 weeks as aerospace and automotive sectors consume priority allocations from Toray and Hexcel. Manufacturing gravity centers on Iceland, Germany, and the United States for carbon fiber socket shells, with thermoplastic resin compounding concentrated in US Midwest and German chemical corridors. Supply chain vulnerability rests on single-source aerospace-grade fiber dependencies and tariff exposure on Chinese-sourced titanium alloy pylons. Distribution runs through orthotic and prosthetic clinic networks, hospital procurement departments, and consolidated vendor panels at academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
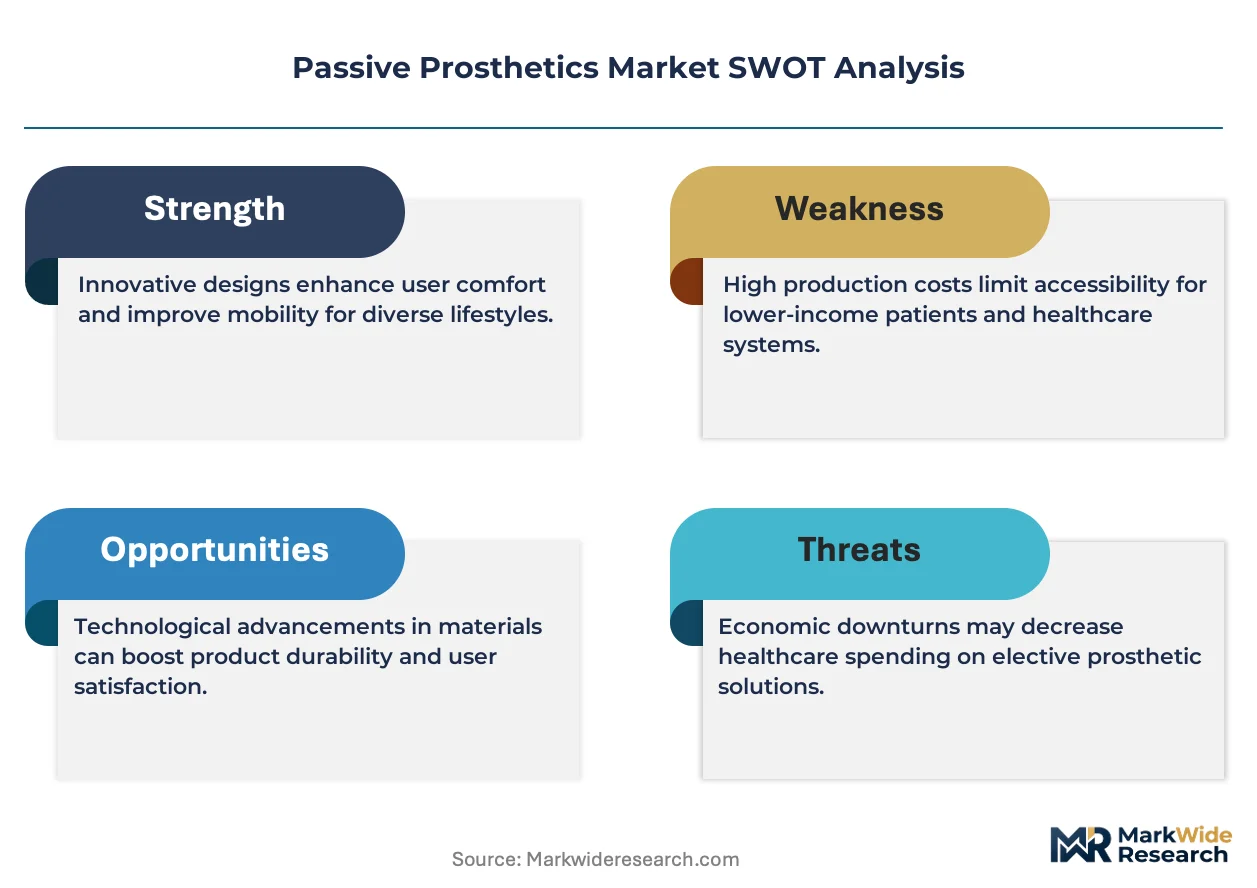
Passive prosthetics sits in early-cycle expansion as post-acute rehabilitation protocols accelerate fitting timelines and expand addressable patient populations beyond traditional dysvascular and trauma segments.
For Market Incumbents: Compound clinic network ownership density in German-speaking markets and US Veterans Affairs corridors to capture episode-of-care bundling momentum. Deepen backward integration into carbon fiber pre-preg layup automation to defend margin position against aluminum substitution pressure. Prioritize ISO 10328 testing infrastructure investment to sustain regulatory clearance velocity under EU MDR transition timelines. For New Entrants and Emerging Players: Lead with expedited socket fabrication protocols targeting post-acute rehabilitation facilities in OECD markets where fitting capacity shortages extend patient access timelines. White-space concentration appears in mobile home care fitting services for mobility-impaired amputees unable to travel to clinical centers. Pursue strategic partnerships with existing clinic networks rather than greenfield certification investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among rehabilitation center service contractors with integrated fitting-maintenance contracts, offering superior cash flow predictability against discrete device manufacturers. Long-term viability favors acquisition targets combining carbon fiber fabrication expertise with captive clinic network access. Watch CMS reimbursement code consolidation decisions as the primary inflection signal for margin sustainability in premium carbon fiber tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Clinic Network Acquisition | Episode-of-care bundling at US academic medical centers and German hospital chains captures integrated service contract volume. |
| Carbon Fiber Layup Automation | Robotic fiber placement in Icelandic and German facilities halves unit labor hours for premium socket shells. |
| EU MDR Article 120 Leverage | Established manufacturers with MDD certificates reduce CE marking exposure while new entrants face 12-18 month queues. |
| Post-Acute Rehabilitation Partnership | Earlier fitting protocol integration at OECD facilities accelerates demand for expedited socket fabrication. |
| Foot-Ankle Hydraulic Integration | College Park Industries and Blatchford terrain-adaptation convergence enables premium positioning without powered actuator costs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with certified prosthetists, rehabilitation center clinical directors, hospital procurement managers, GPO contracts administrators, and carbon fiber composite engineers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body conformity assessment records, CMS Medicare reimbursement code filings, German GKV statutory coverage determinations, and ISO 10328 structural testing protocols. Bottom-up fitting volume estimates and top-down carbon fiber laminate production data were triangulated to anchor market sizing.
Across the analysis window, the forecasting framework modeled demand trajectories by amputation level, material grade tier, end-use setting, and reimbursement framework cluster. CAGRs were derived from fitted trend extrapolation against statutory coverage expansion schedules and certified prosthetist workforce growth projections. Key inputs included Veterans Affairs prosthetic benefit category expansions, German GKV carbon fiber system reimbursement velocity, and post-acute rehabilitation protocol adoption curves.
Underlying assumptions cover statutory reimbursement stability, carbon fiber raw material allocation continuity, and certified prosthetist training pipeline output, with deviation risk concentrated in CMS code consolidation decisions and EU MDR notified body capacity constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
Global Scleral Lens Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
Diabetes Devices Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Global Vein Finders Market
Medical Devices
Cranial Stabilization Devices Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Latin America Insulin Delivery Devices Market
Medical Devices
Alpha Emitter Market