
 Corneal Transplant Market | 2026-2036
Corneal Transplant Market Size, Share, and Industry Trends Forecast 2026-2036
Corneal Transplant Market Analysis
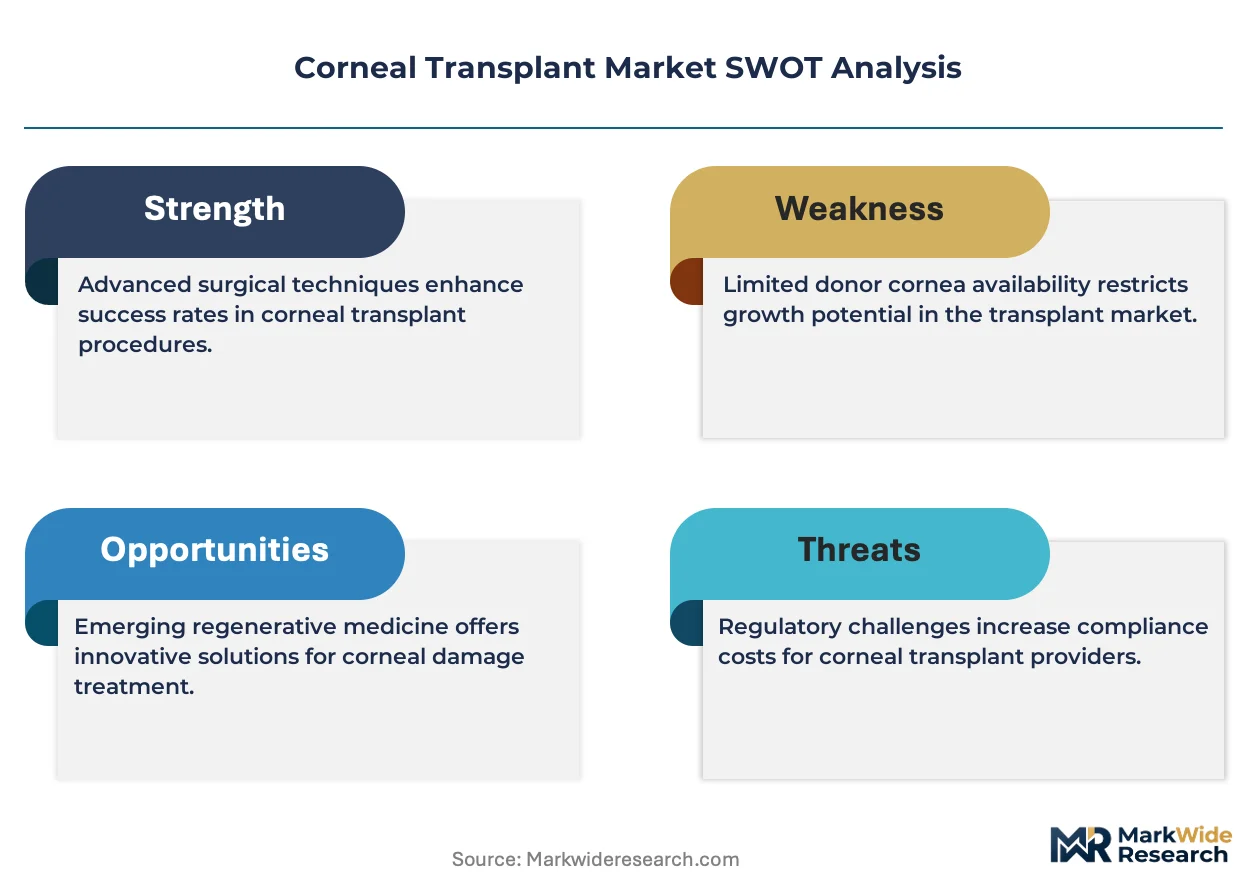
Endothelial-grade tissue specifications are rotating toward higher endothelial cell density thresholds and extended preservation media. Alcon leverages its surgical platform ecosystem to sustain instrument-tissue bundling across hospital networks. KeraLink International anchors North American supply through its eye bank consortium model. CorneaGen differentiates via vertical control over donor tissue acquisition and customized DMEK graft preparation.
Corneal transplant encompasses the surgical replacement of damaged corneal tissue with donor allograft material, typically requiring endothelial cell counts above 2000 cells per square millimeter for graft viability and optical clarity. The procedure restores visual acuity in patients with endothelial failure, stromal opacification, or ectatic disorders where conservative management fails. PKP retains the largest procedural volume among product types due to its applicability across full-thickness pathologies, though DMEK is gaining fastest as surgeons adopt selective endothelial replacement for Fuchs' dystrophy. Femtosecond laser technology commands premium positioning in the technology dimension while manual dissection occupies cost-sensitive segments across outpatient settings.
The FDA enforces donor eligibility and tissue safety standards under 21 CFR Part 1271, while the Eye Bank Association of America operationalizes these requirements through accreditation protocols that determine market access for domestic tissue distributors. The European Union's MDR and EMA oversight of human tissues and cells create parallel compliance obligations for any supplier seeking cross-border placement. Stakeholders must monitor how evolving optical coherence tomography guidance systems reshape surgical training requirements and graft selection criteria.
Market Dynamics
Endothelial keratoplasty techniques are restructuring surgical workflows as femtosecond laser platforms enable selective layer replacement, compressing procedure times while elevating graft survival thresholds. This technological pivot is redistributing volume from penetrating keratoplasty toward DMEK and DSAEK modalities.
Growth Catalysts
- 21 CFR Part 1271:FDA tissue safety standards are standardizing donor screening protocols, expanding eligible tissue pools for domestic eye banks while reducing seroconversion risk in recipient populations.
- Fuchs' dystrophy prevalence:Aging demographics in Germany and Japan are expanding the addressable patient base for endothelial replacement procedures, concentrating demand in markets with established preservation infrastructure.
- Optical coherence tomography:Intraoperative graft guidance systems are enabling thinner tissue handling, extending surgical candidacy to patients with complex anterior segment anatomy previously excluded from selective keratoplasty.
Market Restraints
- Donor tissue scarcity:Eye Bank Association of America accreditation requirements limit eligible recovery organizations, concentrating North American supply among consortium-affiliated distributors.
- Preservation media costs:Organ culture and hypothermic storage solutions face input cost volatility from pharmaceutical-grade reagent supply chains, squeezing margins at tissue processing facilities.
- Endothelial cell density thresholds:Rising clinical standards for graft viability are disqualifying marginal donor tissue, reducing effective yield per recovered cornea below historical baselines.
Strategic Opportunities
- Japan's aging surgical workforce:Underpenetrated DMEK adoption among prefectural ophthalmology departments creates white space for training partnerships and instrument-tissue bundling arrangements.
- EMA MDR harmonization:Cross-border tissue placement frameworks are simplifying multi-country distribution for accredited European eye banks, reducing per-market compliance overhead.
- Femtosecond-OCT convergence:Integration of laser dissection with real-time graft imaging is enabling automated endothelial scoring, potentially reducing surgeon-dependent variability in tissue selection.
Industry Challenges
- Microkeratome technician certification:DMEK graft preparation requires specialized dissection skills with limited training pipeline capacity, constraining tissue processing throughput at mid-volume eye banks.
- Legacy PKP instrument amortization:Hospital surgical suites face capex friction from underutilized penetrating keratoplasty equipment as procedure mix shifts toward endothelial techniques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corneal Transplant Market |
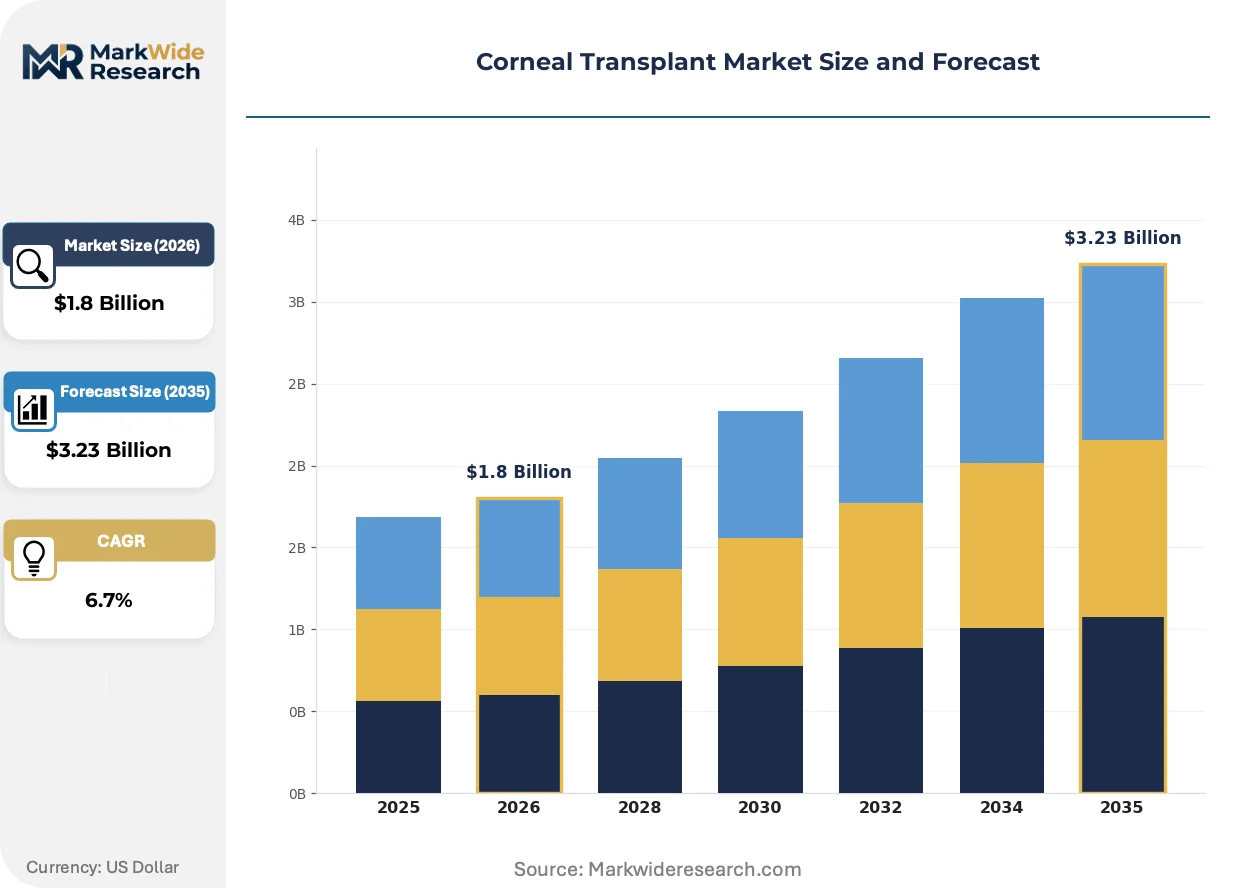
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PKP, DMEK, DALK, EK Indication: Keratoconus, Fuchs' Dystrophy, Corneal Scarring, Trauma End User: Hospitals, Eye Banks, Outpatient Clinics, Ambulatory Surgery Centers Technology: Femtosecond Laser, Manual Dissection, Automated Techniques, Optical Coherence Tomography |
| Companies Covered | CorneaGen, Alcon, KeraMed, Aurolab, AJL Ophthalmic, Presbia, Corneat Vision, Bausch + Lomb, KeraLink International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corneal Transplant Market Emerging Trajectories
Femtosecond laser platforms are redefining tissue preparation standards while regulatory frameworks tighten traceability requirements. These parallel developments are elevating capital intensity and compliance overhead across the value chain.
Descemet membrane endothelial keratoplasty is supplanting Descemet stripping automated endothelial keratoplasty in high-volume surgical centers. Academic medical centers in the United States and Germany are converting DSAEK-capable programs to DMEK-first protocols within 18-24 month adoption cycles. This modality shift is compressing average graft thickness specifications and demanding recalibration of eye bank processing workflows toward manual dissection capabilities.
EU MDR technical documentation requirements for human tissues and cells are extending conformity assessment timelines for cross-border tissue distributors. European eye banks must now maintain device-style quality management systems with notified body oversight, elevating operational overhead. Smaller national recovery organizations in Spain and Italy are consolidating under larger accredited entities to absorb compliance costs.
Hospital procurement departments are consolidating supplier relationships toward single-source tissue agreements with volume-commitment pricing. United States health systems with multiple surgical sites are negotiating system-wide contracts with eye bank consortiums, displacing facility-level purchasing autonomy. This concentration is most visible in integrated delivery networks across Texas and Florida, where procurement standardization is reducing tissue unit cost variability.
Corneal Transplant Market Segmentation
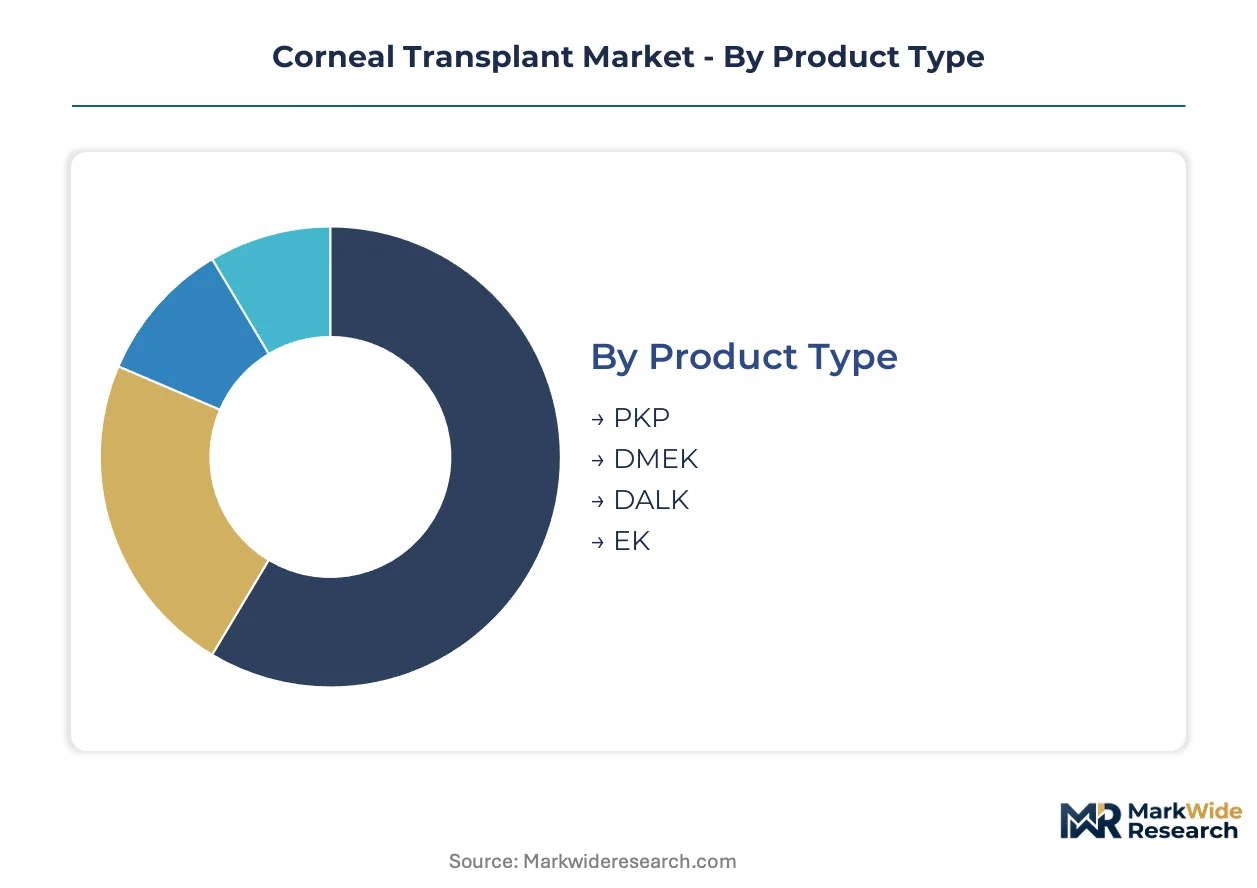
Corneal transplant segmentation reflects divergent reimbursement pathways, surgical training requirements, and tissue processing capabilities across procedure types and care settings. Understanding these divides clarifies where capital investment concentrates and which modalities face adoption friction from workforce constraints or regulatory complexity.
Product Type:
FDA's 21 CFR Part 1271 and parallel EMA MDR frameworks impose distinct tissue traceability and quality management obligations on full-thickness versus selective keratoplasty products, shaping which segments eye banks prioritize for processing investment.
- PKP:Full-thickness replacement of diseased cornea with donor allograft, applicable across stromal opacification, ectatic disorders, and combined endothelial-stromal failure. United States academic medical centers and German university hospitals sustain procedural volume through established fellowship training pipelines and mature tissue distribution networks, though reimbursement compression is redirecting selective cases toward endothelial techniques.
- DMEK:Descemet membrane endothelial keratoplasty replaces only the dysfunctional endothelial layer through a 2.8mm incision, demanding manual dissection of donor tissue to 15-20 micron thickness specifications. Japanese prefectural hospitals and United States integrated delivery networks are expanding DMEK-first protocols for Fuchs' dystrophy, constrained by microkeratome technician certification bottlenecks at mid-volume eye banks.
- DALK:Deep anterior lamellar keratoplasty preserves recipient endothelium while replacing stromal layers, indicated for keratoconus and anterior stromal scarring without endothelial compromise.
- EK:Encompassing DSAEK and predecessor endothelial keratoplasty techniques, this segment retains procedural volume in settings where DMEK conversion costs exceed equipment amortization timelines.
PKP handles the majority of throughput across combined stromal-endothelial pathologies; DMEK is the fastest mover on share as surgeons adopt selective replacement for isolated endothelial failure.
Indication:
Prevalence curves and diagnostic access determine addressable patient pools, with aging demographics in Germany and Japan expanding Fuchs' dystrophy caseloads while keratoconus concentrates in younger populations with variable screening penetration.
- Fuchs' Dystrophy:Progressive endothelial cell loss producing corneal edema and vision degradation, now the dominant driver for endothelial keratoplasty conversion in markets with optical coherence tomography diagnostic penetration. German statutory health insurance and Japanese social health coverage systems are expanding pre-surgical imaging reimbursement, accelerating surgical candidacy identification.
- Keratoconus:Ectatic thinning of central cornea typically presenting in second-third decade of life, with collagen cross-linking displacing transplant need in early-stage disease across United States and European markets. Deep anterior lamellar keratoplasty retains position for advanced cases where stromal replacement preserves native endothelium.
- Corneal Scarring:Post-infectious or degenerative opacification requiring optical clarity restoration, with penetrating keratoplasty remaining default modality when scarring extends to Descemet membrane.
- Trauma:Mechanical or chemical injury producing full-thickness laceration or stromal disruption, often requiring emergency PKP with subsequent graft failure risk elevated by vascularization and inflammation.
Fuchs' dystrophy commands the largest addressable surgical volume in aging markets; keratoconus is climbing the fastest as cross-linking delays shift transplant timing rather than eliminating need.
End User:
Capital intensity and case volume thresholds segment procurement authority, with hospital systems consolidating supplier relationships while ambulatory settings pursue instrument-tissue bundling for cost containment.
- Hospitals:Academic medical centers and tertiary referral hospitals in the United States, Germany, and Japan maintain femtosecond laser platforms and fellowship-trained corneal specialists, capturing complex cases and training revenue. Texas and Florida integrated delivery networks are negotiating system-wide tissue agreements, displacing facility-level purchasing autonomy.
- Eye Banks:Tissue recovery and processing organizations operating under Eye Bank Association of America or equivalent European accreditation, with KeraLink International and consortium-affiliated entities concentrating North American supply. EU MDR technical documentation requirements are extending conformity assessment timelines and elevating operational overhead.
- Outpatient Clinics:Lower-acuity settings performing diagnostic workup and postoperative management, with surgical referral relationships determining tissue procurement indirect influence.
- Ambulatory Surgery Centers:Cost-sensitive environments where manual dissection techniques and streamlined DSAEK workflows compete on procedure time and reimbursement efficiency.
Hospitals retain dominant case volume and technology investment; ambulatory surgery centers are expanding most quickly as reimbursement pressure drives site-of-care migration for routine endothelial replacement.
Technology:
Equipment lifecycle and training pipeline capacity determine adoption velocity, with femtosecond platforms commanding premium positioning while manual techniques persist where capital constraints or case volume insufficiently supports depreciation.
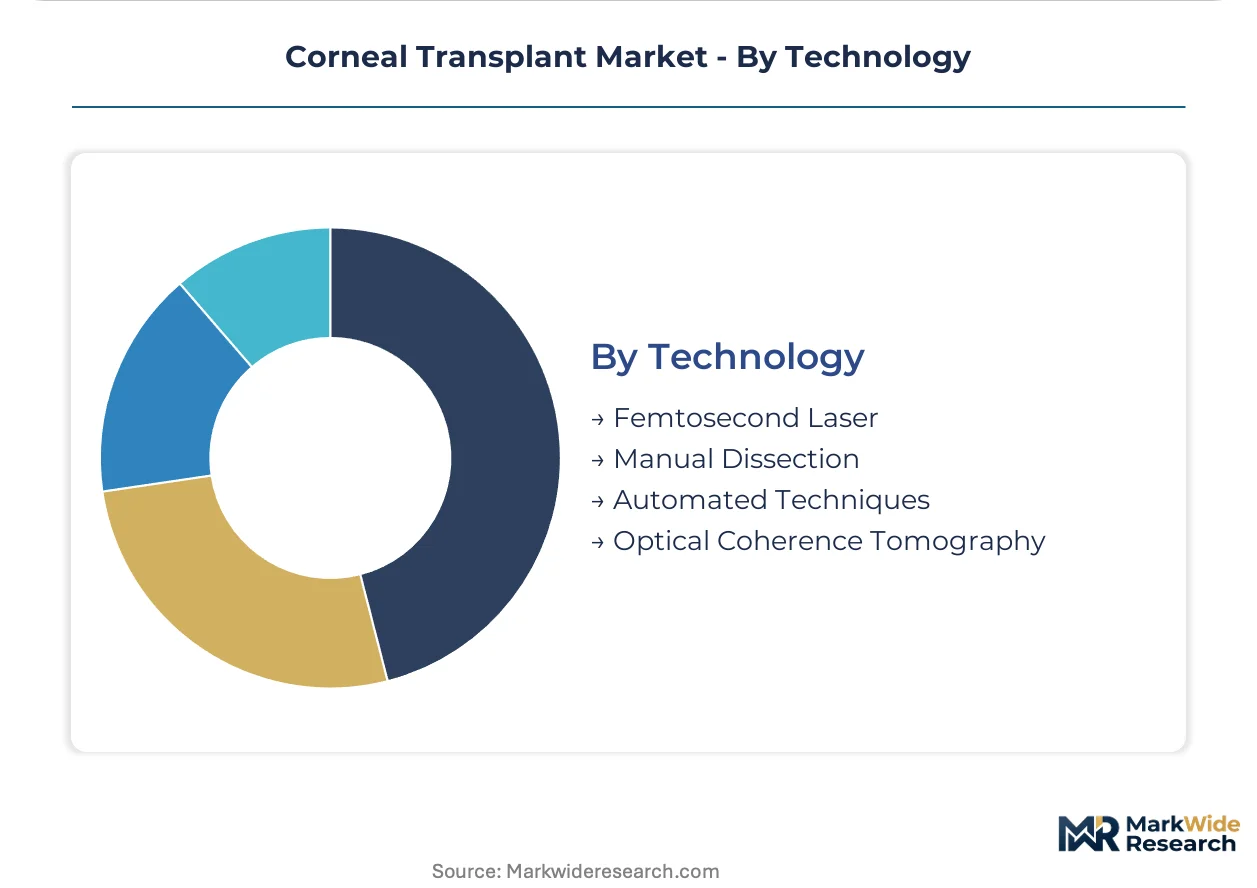
- Femtosecond Laser:Ultrafast infrared pulse platforms enabling precise stromal dissection, endothelial scoring, and customized graft geometry with reduced surgeon-dependent variability. Alcon leverages its surgical platform ecosystem to sustain instrument-tissue bundling across United States hospital networks, though capital outlay limits penetration in German community hospitals and Japanese prefectural settings.
- Manual Dissection:Microkeratome and hand-dissection techniques for DMEK graft preparation, requiring specialized technician certification with constrained training pipeline capacity. CorneaGen's vertical control over donor tissue acquisition includes captive manual dissection capabilities for customized graft specifications.
- Automated Techniques:Microkeratome-based systems for DSAEK lamellar dissection, retaining position in high-volume eye banks where throughput demands exceed manual preparation capacity.
- Optical Coherence Tomography:Intraoperative graft guidance and preoperative anterior segment imaging systems enabling thinner tissue handling and automated endothelial scoring, extending surgical candidacy to complex anatomy previously excluded from selective keratoplasty.
Manual dissection maintains plurality of graft preparation volume; femtosecond laser integration with OCT guidance is gaining share fastest as training protocols standardize and capital access expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The corneal transplant market exhibits pronounced import dependency in tissue supply, with eye bank consortiums managing cross-border recovery networks to address domestic donor shortfalls. Germany and Japan maintain net import positions for endothelial-grade tissue, while the United States balances domestic recovery against selective importation from accredited international partners.
United States
FDA's 21 CFR Part 1271 enforcement standardizes donor screening across Eye Bank Association of America-accredited facilities, expanding eligible tissue pools while elevating compliance overhead. Texas and Florida integrated delivery networks are consolidating procurement under system-wide tissue agreements, displacing facility-level purchasing autonomy. KeraLink International anchors North American supply through its consortium model, concentrating distribution among affiliated recovery organizations.
Germany
Statutory health insurance expansion for optical coherence tomography diagnostic reimbursement accelerates Fuchs' dystrophy case identification and surgical candidacy determination. EU MDR technical documentation requirements extend conformity assessment timelines for human tissues, elevating operational overhead at national eye banks. University hospitals in Bavaria and North Rhine-Westphalia sustain PKP volume through established fellowship training pipelines amid gradual DMEK conversion.
Japan
Social health coverage systems expand pre-surgical imaging reimbursement, concentrating demand among prefectural ophthalmology departments with established preservation infrastructure. PMDA oversight of imported human tissues creates parallel compliance tracks for domestic versus foreign-sourced graft material. Tokyo and Osaka academic centers lead DMEK adoption while underpenetrated prefectural settings present training partnership opportunities.
India
CDSCO regulation of imported ocular tissue establishes quality benchmarks for domestic eye bank accreditation, narrowing the compliance gap between public and private recovery facilities. Maharashtra and Karnataka host concentrated corneal processing capacity, with Mumbai and Bangalore centers managing multi-state distribution networks. Aurolab's not-for-profit manufacturing model exemplifies cost-sensitive graft preparation for regional markets.
United Kingdom
NHS England procurement frameworks standardize tissue pricing across hospital trusts, compressing unit cost variability through volume-commitment contracting. Human Tissue Authority licensing requirements enforce traceability standards that align with EU MDR transitional provisions post-Brexit. London and Manchester tertiary centers maintain femtosecond laser platforms for complex anterior segment reconstruction.
Corneal Transplant Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and tissue access dimensions, creating a tiered structure where scale-driven instrument platforms coexist with focused graft preparation services. Public ophthalmic device manufacturers leverage surgical ecosystem bundling to secure hospital network contracts, while private eye bank consortiums concentrate supply chain control through donor recovery relationships. Two archetypes dominate: integrated platform vendors combining laser systems with tissue distribution, and specialized processors commanding vertical control over donor acquisition and customized graft preparation. Competitive moves center on instrument-tissue bundling arrangements and eye bank consolidation to absorb regulatory compliance costs.
Within the integrated platform tier, Alcon and Bausch + Lomb occupy positions spanning femtosecond laser instrumentation and associated surgical consumables. CorneaGen exemplifies the specialized processor archetype through its captive control over donor tissue acquisition and manual dissection capabilities. KeraLink International anchors the consortium model, concentrating North American supply among affiliated recovery organizations. These three patterns—platform bundling, vertical tissue control, and consortium-based supply concentration—define the competitive geometry as regulatory overhead escalates and hospital procurement consolidates.
| Leading Market Players |
|---|
| CorneaGen |
| Alcon |
| KeraMed |
| Aurolab |
| AJL Ophthalmic |
| Presbia |
| Corneat Vision |
| Bausch + Lomb |
| KeraLink International |
| Others |
Supply Flow & Price Mechanics
Eye Bank Association of America accreditation protocols gate both tissue qualification and price differentiation simultaneously, compressing margins at non-consortium processors while elevating premium positioning for vertically integrated suppliers with captive donor recovery networks.
Pricing Analysis
Hospital procurement departments anchor pricing structure through system-wide tissue agreements with volume-commitment terms. Three-tier pricing structure across premium, standard, and economy levels stratifies by endothelial cell density thresholds and preservation media specifications. Cost compression in mid-tier segments is intensifying because EU MDR compliance overhead is elevating processing costs at smaller eye banks. Ambulatory surgery centers exhibit highest price sensitivity due to reimbursement pressure driving site-of-care migration.
Supply Chain Analysis
Inventory lead times for endothelial-grade tissue extend from recovery through distribution due to mandatory serological screening and culture periods. Supply concentrates in the United States, Germany, and Japan as these markets maintain accredited recovery infrastructure and preservation capabilities. Raw material dependencies include pharmaceutical-grade storage media, donor qualification reagents, and specialized microkeratome blades. Single-source vulnerability runs through consolidated eye bank consortiums controlling North American distribution. Distribution runs through hospital procurement departments and integrated delivery network contracts rather than open market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital systems and integrated delivery networks, with Texas and Florida health systems displacing facility-level purchasing autonomy through system-wide tissue agreements.
For Market Incumbents: Consolidate procurement relationships through instrument-tissue bundling arrangements that lock in hospital network contracts. Absorb EU MDR compliance costs via eye bank consolidation to maintain margin position against specialized processors with captive donor acquisition. Prioritize femtosecond laser platform penetration in Japanese prefectural settings where DMEK adoption lags. For New Entrants and Emerging Players: Differentiate on manual dissection capabilities for customized DMEK graft specifications where mid-volume eye banks face technician certification bottlenecks. Target underpenetrated Japanese prefectural ophthalmology departments through training partnerships and instrument placement programs. Pursue white-label tissue processing contracts with regional hospitals seeking to bypass consortium pricing. For Investors and Strategic Acquirers: Carve-out targets emerge from academic medical center eye banks seeking to monetize processing capabilities under compliance cost pressure. Long-term viability hinges on vertical control over donor acquisition rather than distribution relationships alone. Watch FDA enforcement patterns on 21 CFR Part 1271 as signal for regulatory burden trajectory and consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Eye Bank Consortium Expansion | KeraLink International's model concentrates North American supply among accredited recovery organizations. |
| Femtosecond Laser Platform Deployment | Alcon leverages surgical ecosystem bundling to secure hospital network contracts across United States markets. |
| EU MDR Compliance Investment | Notified body oversight elevates operational overhead, forcing consolidation among smaller European recovery facilities. |
| DMEK Training Partnership Programs | Tokyo and Osaka academic centers extend adoption protocols to underpenetrated prefectural settings. |
| Vertical Donor Acquisition Integration | CorneaGen's captive tissue control enables customized graft preparation outside consortium pricing structures. |
Methodological Framework
The analysis maps penetrating keratoplasty, endothelial keratoplasty, and deep anterior lamellar keratoplasty segments, each validated through corneal surgeons, eye bank technical directors, hospital procurement managers, and biomedical engineers. Primary interviews with tissue processing specialists and GPO contracts managers combined with secondary validation against FDA 21 CFR Part 1271 filings, EBAA accreditation records, CMS Medicare reimbursement data, and EMA MDR technical documentation. Bottom-up procedure volume estimates triangulated against top-down health system expenditure data.
Consistency checks validated outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include procedure type, indication category, end-user setting, and technology platform. CAGRs derived from logistic diffusion curves for surgical technique adoption overlaid with demographic prevalence projections for Fuchs' dystrophy and keratoconus. Forecast inputs incorporated eye bank recovery rates, preservation media cost trajectories, and femtosecond laser platform placement pipelines.
Forecasts assume regulatory continuity in FDA 21 CFR Part 1271 and EU MDR frameworks; material policy shifts would require re-modeling. Outputs reflect assumptions on surgical training pipeline capacity and donor tissue recovery efficiency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Bromhidrosis Disease Treatment Market
Medical Treatment
Single Dose Radiotherapy Services Market
Medical Treatment
Factor XIII Deficiency Treatment Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Menopause Treatment Market
Medical Treatment
Uterine Fibroid Treatment Drugs Market
Medical Treatment
Peripheral Nerve Injuries Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Epiglottitis Treatment Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Middle Ear Infection Treatment Market
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Anti-Fungal Treatment Market