
 Pain Management Software Market | 2026-2036
Pain Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Pain Management Software Market Intelligence
Subscription-based software-defined feature layers is rebalancing vendor economics toward recurring revenue models. RXNT leverages cloud-native architecture to serve ambulatory pain clinics. ModMed EMR anchors its position through specialty-specific EHR workflows. athenaOne competes on network-enabled interoperability across distributed care sites.
Pain management software encompasses digital platforms that capture patient-reported outcome measures, integrate multimodal analgesic protocols, and generate compliance documentation for value-based reimbursement. These systems process structured pain scores, medication logs, and functional status indices to support clinical decision-making and regulatory reporting. Patient Monitoring Software dominates current deployments through real-time opioid stewardship dashboards. Cloud-Based delivery is expanding fastest as health systems retire legacy on-premise infrastructure. Data Analytics Platforms concentrate margin pools through predictive risk stratification and population health contracting.
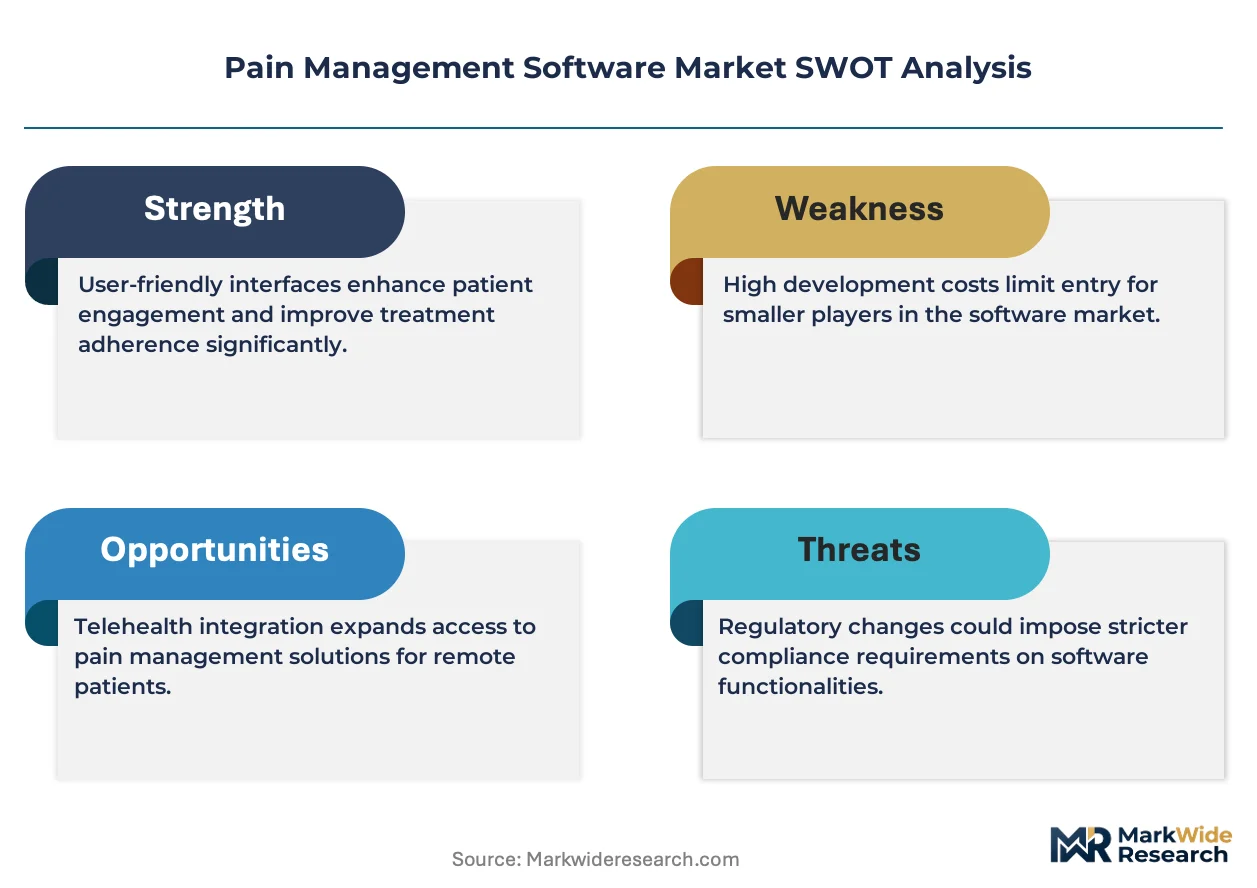
FDA 21 CFR Part 11 shapes electronic record integrity requirements for clinical pain data. HIPAA governs protected health information exchange between integrated care teams. CMS quality payment programs tie reimbursement to documented pain assessment completeness. Stakeholders must weigh interoperability investment against specialty-specific workflow customization as purchasing criteria harden.
Market Dynamics
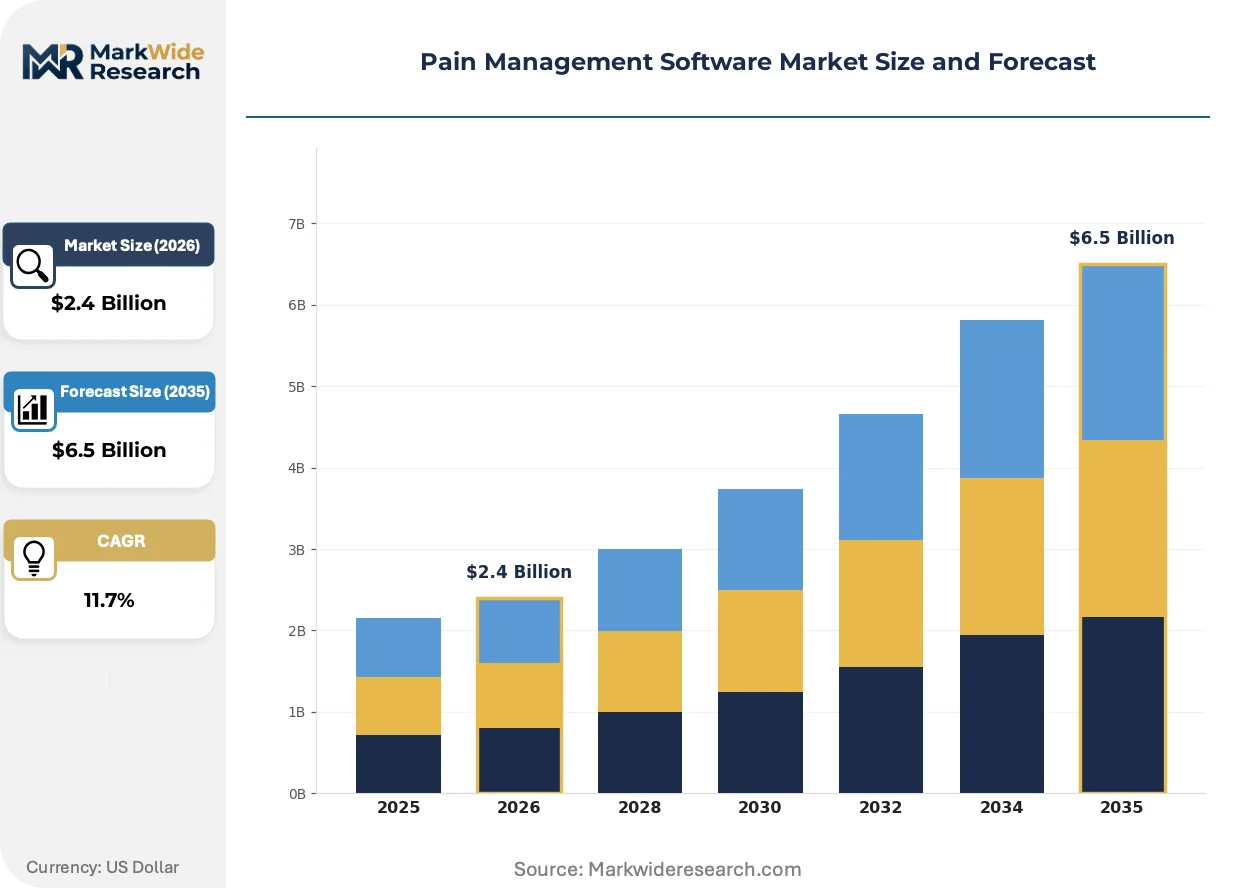
CMS value-based reimbursement mandates are compressing adoption timelines for integrated pain platforms, forcing hospital systems to retire fragmented point solutions in favor of unified cloud-native architectures that automate quality measure documentation.
Growth Catalysts
- CMS Quality Payment Programs:Medicare reimbursement penalties for incomplete pain assessment documentation push health systems toward automated capture platforms.
- Chronic Pain Prevalence:Rising multimorbidity populations in ambulatory settings generate recurring demand for longitudinal outcome tracking tools.
- Cloud-Native Architecture:API-first platforms enable real-time interoperability between EHR systems and specialized pain modules without on-premise infrastructure.
Market Restraints
- Interoperability Fragmentation:HL7 FHIR implementation gaps between legacy EHR vendors create data silos that stall platform deployments.
- Specialty Workflow Complexity:Pain management requires multimodal documentation (opioid logs, functional indices, PROs) that generic EHR templates cannot accommodate.
- Cybersecurity Liability:HIPAA breach penalties for cloud-based PHI storage deter smaller ambulatory clinics from SaaS migration.
Strategic Opportunities
- Remote Patient Monitoring Integration:Wearable-derived pain scores and medication adherence data open subscription revenue streams beyond traditional software licensing.
- Population Health Contracting:ACOs and Medicare Advantage plans seek predictive risk stratification tools to reduce opioid-related hospitalizations.
- FDA Digital Therapeutics Pathway:Software-as-medical-device designations for cognitive behavioral pain apps create reimbursement codes previously unavailable to pure software vendors.
Industry Challenges
- Clinical Informatics Talent Scarcity:Health systems lack specialists who bridge pain medicine workflows with data architecture design.
- Legacy System Integration Burden:Custom API development for on-premise EHR installations consumes 40-60% of implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pain Management Software Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Monitoring Software, Clinical Decision Support, Pain Assessment Tools, Data Analytics Platforms Application: Chronic Pain Management, Postoperative Pain Tracking, Cancer Pain Control, Rehabilitation Therapy End User: Hospitals, Ambulatory Surgery Centers, Physical Therapy Clinics, Pain Management Centers Deployment Model: On-Premise, Cloud-Based, Hybrid, Software as a Service |
| Companies Covered | RXNT, ModMed EMR, NextGen Office, eClinicalWorks, CureMD, athenaOne, AdvancedMD EHR, Nextech, DrChrono, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pain Management Software Market Strategic Shifts & Innovations
Artificial intelligence is compressing clinical decision cycles in pain management, replacing retrospective chart review with real-time risk scoring and protocol recommendations embedded directly into provider workflows.
Machine learning algorithms trained on multimodal pain datasets is overtaking rule-based clinical decision support in opioid stewardship applications. Large hospital systems in the United States are deploying these tools across emergency departments and surgical wards within 12-18 month procurement cycles. The technology is overtaking traditional morphine milligram equivalent calculators by predicting respiratory depression risk 6-8 hours before clinical manifestation.
EU Medical Device Regulation (MDR) Class IIa classification requirements are forcing pain software vendors to establish quality management systems and clinical evidence portfolios previously unnecessary for wellness applications. Manufacturers must now submit post-market surveillance plans for algorithm updates that modify diagnostic or therapeutic recommendations. European health technology assessment bodies in Germany, France, and the Netherlands are prioritizing MDR-certified platforms in procurement frameworks.
Subscription-based platform economics are displacing perpetual license arrangements as the dominant procurement model for ambulatory pain clinics. Private equity-backed clinic rollups in Texas, Florida, and Arizona are negotiating enterprise SaaS contracts that bundle EHR, practice management, and pain-specific analytics. This concentration of purchasing power is compressing pricing for standalone point solutions while favoring integrated platform vendors.
Pain Management Software Market Segmentation
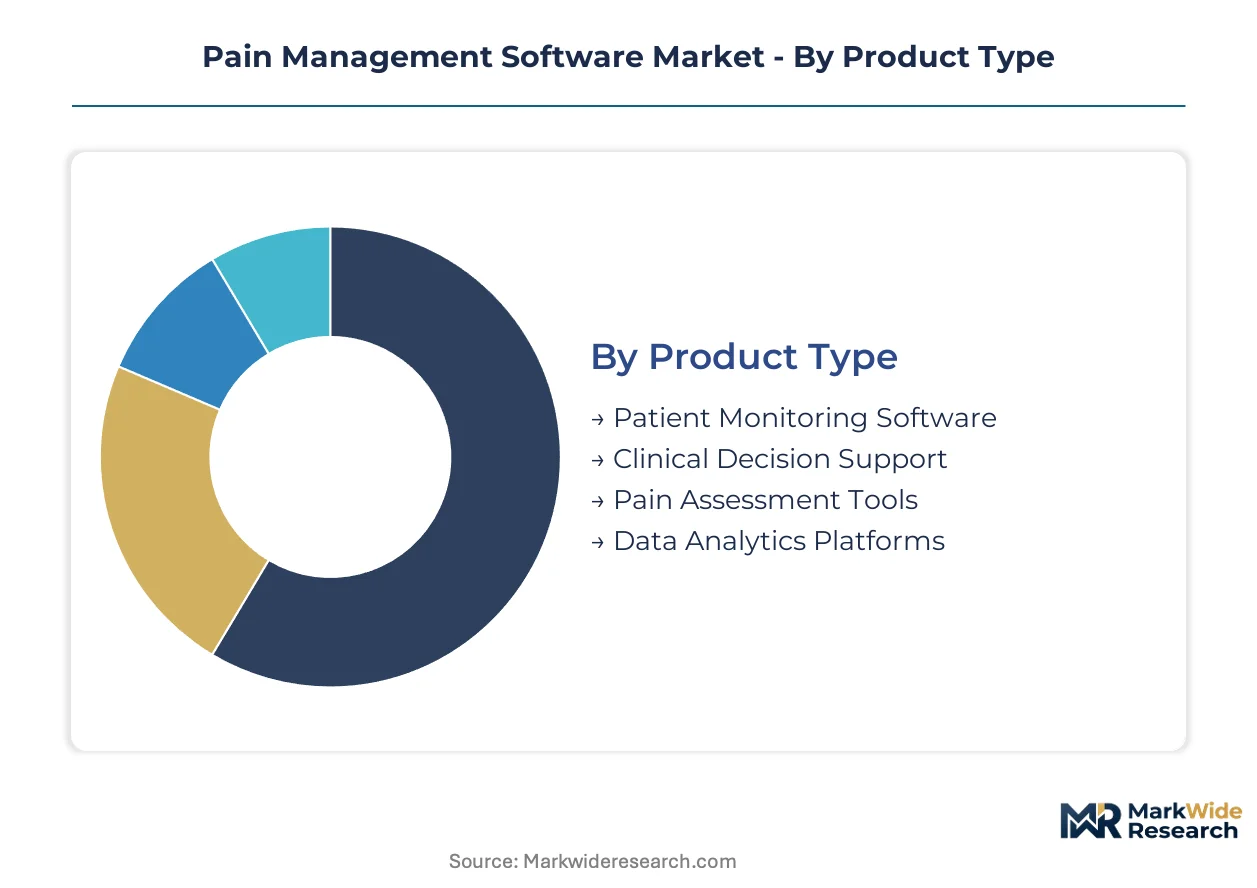
Pain management software vendors configure product architecture around distinct clinical workflows, reimbursement requirements, and infrastructure constraints. Segmentation reveals where standardization yields economies of scale versus where specialty customization commands premium positioning.
Product Type:
Customization demands peak where clinical decision support intersects with regulatory documentation, while standardization dominates patient monitoring infrastructure.
- Patient Monitoring Software:Real-time dashboards aggregate opioid stewardship metrics, respiratory indicators, and infusion pump data for surgical wards and emergency departments. Hospital systems in the United States deploy these tools most intensively where CMS quality reporting mandates require automated capture of morphine milligram equivalents and sedation scores.
- Clinical Decision Support:Rule-based and machine learning algorithms embed risk stratification directly into provider order entry workflows. Demand concentrates in academic medical centers pursuing opioid-sparing protocols under value-based contracts with Medicare Advantage plans.
- Pain Assessment Tools:Digital platforms capture patient-reported outcome measures through validated instruments like the Brief Pain Inventory.
- Data Analytics Platforms:Population health engines stratify chronic pain cohorts for ACO risk contracting and predictive intervention targeting.
Leading the category by volume: Patient Monitoring Software. Expanding most quickly: Clinical Decision Support.
Application:
Reimbursement intensity varies sharply across acute episodic versus longitudinal chronic care models.
- Chronic Pain Management:Longitudinal platforms track functional status indices, medication adherence, and interventional procedure outcomes across months or years. Ambulatory pain clinics in Texas, Florida, and Arizona generate concentrated demand as private equity rollups negotiate enterprise SaaS contracts spanning multiple sites.
- Postoperative Pain Tracking:Perioperative modules integrate with anesthesia information management systems to document multimodal analgesic protocols and discharge readiness. Surgical hospitals deploy these tools to reduce length-of-stay penalties under bundled payment programs.
- Cancer Pain Control:Oncology-integrated workflows accommodate breakthrough pain documentation and palliative care handoffs.
- Rehabilitation Therapy:Physical therapy clinics utilize functional outcome tracking for workers compensation and auto liability documentation.
Chronic Pain Management holds the largest installed base. Postoperative Pain Tracking is gaining share fastest as bundled payment penetration deepens.
End User:
Procurement sophistication scales with organizational IT resources and regulatory exposure.
- Hospitals:Integrated delivery networks demand unified platforms spanning inpatient, emergency, and ambulatory settings with enterprise-grade interoperability. These organizations command the deepest discounts through multi-year contracts while driving vendor roadmaps toward AI-enabled risk prediction.
- Ambulatory Surgery Centers:Lean IT organizations prioritize cloud-native solutions with minimal on-premise infrastructure and rapid implementation timelines.
- Physical Therapy Clinics:Smaller practices favor modular solutions with per-provider pricing and minimal customization requirements.
- Pain Management Centers:Specialty clinics require procedure documentation, fluoroscopy log integration, and interventional billing code support.
Hospitals anchor category revenue. Ambulatory Surgery Centers are climbing the fastest as site-of-service migration accelerates.
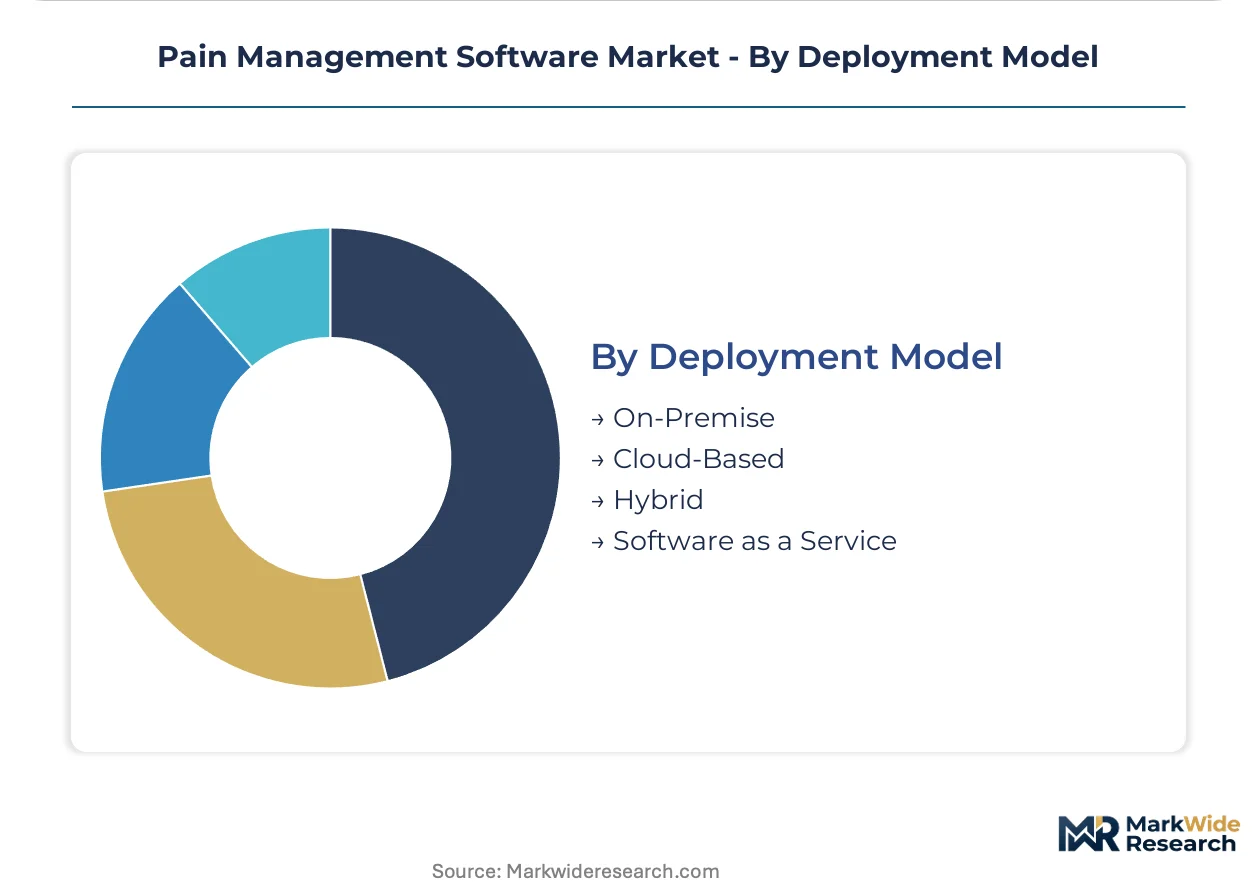
Deployment Model:
Vendor economics and customer risk tolerance shape cloud migration velocity.
- Cloud-Based:API-first architectures enable real-time data exchange between EHR systems and specialized pain modules without capital infrastructure investment. Health systems retiring legacy on-premise servers are migrating to these platforms under pressure from CMS quality reporting deadlines.
- Software as a Service:Subscription pricing aligns vendor incentives with customer success metrics and reduces upfront procurement friction for mid-size clinics.
- On-Premise:Remains entrenched in organizations with stringent data residency requirements or specialized hardware integration needs.
- Hybrid:Combines local processing for latency-sensitive applications with cloud analytics for population health reporting.
Cloud-Based deployments lead category volume. Software as a Service shows the steepest expansion trajectory as ambulatory clinic procurement concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States, while consumption spreads across health systems in Germany, Japan, and Australia seeking validated clinical decision support tools. Cloud infrastructure investments favor North American vendors serving international clients through API-first architectures.
United States
Hospital systems in Texas, Florida, and Arizona drive enterprise SaaS procurement for private equity-backed pain clinic rollups. CMS quality payment programs mandate automated pain assessment documentation under Medicare reimbursement rules. The Dallas-Fort Worth metro anchors concentrated demand from ambulatory surgery centers migrating off legacy on-premise systems.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia pursue opioid-sparing protocols under value-based contracts with statutory health insurers. EU Medical Device Regulation Class IIa certification requirements shape procurement frameworks through BfArM oversight. The Munich cluster concentrates MDR-certified platform development for export to neighboring markets.
United Kingdom
NHS Integrated Care Systems in England deploy population health analytics for chronic pain cohort stratification under NHS England commissioning guidelines. MHRA software-as-medical-device pathways create reimbursement codes for digital therapeutics previously unavailable to pure software vendors. The London-Oxford-Cambridge triangle anchors health technology assessment prioritization of predictive risk tools.
Japan
Metropolitan hospital networks in Tokyo and Osaka integrate pain monitoring modules with existing anesthesia information management systems. PMDA guidance on SaMD classification determines whether algorithm updates trigger regulatory resubmission for machine learning-enabled platforms. The Kansai region concentrates demand from surgical hospitals reducing length-of-stay under bundled payment pilots.
Australia
State health departments in New South Wales and Victoria pilot remote patient monitoring integration for wearable-derived pain scores in rural ambulatory settings. TGA software framework guidelines align with international medical device regulator harmonization initiatives. The Melbourne biomedical precinct anchors clinical validation studies for algorithmic risk prediction tools.
Pain Management Software Market Key Industry Players
Top-tier vendors anchor integrated platform economics, while mid-size specialists compete through specialty-specific workflow customization. The vendor base stratifies across cloud-native architectures serving ambulatory clinics and legacy-integrated systems dominating hospital procurement. Three archetypes dominate: EHR-embedded modules, standalone pain-specific platforms, and network-enabled interoperability layers. Consolidation pressure favors multi-year enterprise contracts, while API-first entrants compete on implementation velocity.
Within the EHR-embedded tier, RXNT and ModMed EMR exemplify cloud-native architectures designed for ambulatory pain workflows. athenaOne occupies a position emphasizing network-enabled interoperability across distributed care sites. These three vendors represent contrasting strategic bets on whether specialty-specific customization or horizontal platform scale wins procurement decisions.
| Leading Market Players |
|---|
| RXNT |
| ModMed EMR |
| NextGen Office |
| eClinicalWorks |
| CureMD |
| athenaOne |
| AdvancedMD EHR |
| Nextech |
| DrChrono |
| Others |
Cost & Logistics Intelligence
CMS quality payment program mandates for automated pain assessment documentation are compressing procurement timelines and forcing health systems toward unified cloud-native platforms, which concentrates purchasing power among integrated vendors and erodes standalone point-solution pricing.
Pricing Analysis
Margin tightening in ambulatory clinic tiers reflects private equity rollup consolidation negotiating enterprise SaaS contracts spanning multiple sites. Pricing stratifies across premium, standard, and economy tiers based on AI-enabled risk prediction capabilities and FDA 21 CFR Part 11 certification levels. Cost compression accelerates as mid-size clinics abandon perpetual licenses for subscription models. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers pursuing opioid-sparing protocols under value-based contracts show lowest.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure providers in the United States, where AWS, Microsoft Azure, and Google Cloud anchor data residency for PHI-compliant deployments. Software development draws from engineering talent pools in the United States, Germany, and India. Supply chain risk centers on HIPAA breach liability deterring smaller clinics from SaaS migration. Distribution runs through direct enterprise sales teams for hospital systems and channel partners for ambulatory clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pain management software functions as a cost-of-compliance market where FDA 21 CFR Part 11 and EU MDR Class IIa certification requirements erect barrier-to-entry moats favoring vendors with established quality management systems and clinical evidence portfolios.
For Market Incumbents: To counter API-first entrants competing on implementation velocity, deepen backward integration into cloud infrastructure and pursue MDR certification for algorithmic risk prediction tools. Lock in multi-year enterprise contracts with integrated delivery networks before CMS quality reporting deadlines consolidate purchasing decisions. For New Entrants and Emerging Players: The price-point gap between premium AI-enabled platforms and economy EHR-embedded modules creates entry space for specialty workflow customization targeting physical therapy clinics and workers compensation documentation. Pursue white-label partnerships with private equity-backed clinic rollups in Texas, Florida, and Arizona as the most penetrable channel. For Investors and Strategic Acquirers: The window for entry favors vendors with MDR-certified platforms and established hospital system partnerships over pure-play SaaS entrants. Long-term viability hinges on predictive analytics capabilities and population health contracting relationships. Watch FDA digital therapeutics pathway designations for cognitive behavioral pain apps as the inflection signal for reimbursement code expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies EHR, practice management, and pain-specific analytics under single vendor relationships. |
| FDA 21 CFR Part 11 Compliance Investment | Establishes electronic record integrity credentials required for clinical pain data capture. |
| EU MDR Class IIa Certification Pathway | Opens procurement frameworks in Germany, France, and Netherlands health technology assessments. |
| Strategic Partnership with Private Equity Rollups | Captures concentrated demand from Texas, Florida, and Arizona ambulatory clinic consolidations. |
| Remote Patient Monitoring Integration | Creates subscription revenue streams beyond traditional software licensing through wearable-derived data. |
Research Approach
Independent corroboration across pain medicine specialists, hospital procurement committees, cloud platform engineers, and regulatory affairs consultants underwrites the qualitative findings. Primary interviews with clinicians, GPO contracts managers, and biomedical engineers combined with secondary validation from CMS Medicare data, FDA 510(k) filings, and hospital procurement databases. Bottom-up and top-down triangulation cross-validates segment-level estimates against aggregate market sizing.
Rate-of-change decomposition across the analysis window isolates volume drivers from price effects. Segmentation dimensions modeled include deployment model, organization size, clinical workflow complexity, and regional regulatory cluster. CAGRs derive from trend extrapolation adjusted for policy implementation timelines and technology adoption curves. Forecast inputs incorporate CMS quality payment program penalty schedules and EU MDR certification rollout pace.
Underlying measurement precision varies by segment; patient monitoring software carries tighter precision than emerging clinical decision support categories. Forecasts reflect assumptions about interoperability standardization and cloud migration velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Migraine Management Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
Global Pain Management Market
Pain Management
Cancer Pain Market
Pain Management
Global Morphine Market
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Pain Therapeutic Solutions Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Neuralgia Treatment Market
Pain Management
Neuropathic Pain Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Painkillers Market
Pain Management
Dyspareunia Market
Pain Management
Pain Management Devices Market
Pain Management
Plantar Fasciitis Treatment Market