
 VR Stroke Rehabilitation Market | 2026-2036
VR Stroke Rehabilitation Market Size, Share, and Industry Trends Forecast 2026-2036
VR Stroke Rehabilitation Market Analytics
Real-time motion capture integration with haptic feedback hardware is reshaping how VR stroke rehabilitation systems are architected, moving platforms from visual-only immersion toward closed-loop sensorimotor retraining. MindMaze SA anchors European development through its neurotechnology specialization in brain-computer interfaces for motor recovery. Flint Rehabilitation competes in the home-based segment with upper-extremity therapy devices that extend clinical protocols into residential settings. eXRt Intelligent Healthcare leverages AI-driven adaptive difficulty algorithms to personalize rehabilitation intensity without continuous therapist oversight.
VR stroke rehabilitation encompasses immersive digital environments that combine head-mounted displays, motion tracking sensors, and software algorithms to deliver repetitive, task-specific motor and cognitive exercises for hemiparetic patients, typically operating at latency thresholds below 20 milliseconds to prevent motion sickness and preserve neuroplasticity engagement. The primary commercial purpose centers on translating evidence-based constraint-induced movement therapy and mirror therapy protocols into scalable, measurable digital interventions that reduce therapist-to-patient staffing ratios while maintaining clinical fidelity. Software platforms currently capture the deepest margin pools because subscription and per-session licensing models generate recurring revenue streams distinct from one-time hardware sales. Hospitals dominate installed base volume, though home care providers represent the fastest-growing end user category as reimbursement frameworks in Germany and the United States gradually expand remote neurorehabilitation coverage. Immersive systems integrating mixed reality overlays are gaining traction in motor skills training applications where depth perception and proprioceptive feedback prove critical for upper limb recovery protocols.
FDA digital health pre-certification and CE marking under the EU Medical Device Regulation shape product development timelines and market access requirements for VR rehabilitation platforms seeking clinical claims. HIPAA compliance obligations in the United States and GDPR data governance in Europe constrain how patient movement data and neural performance metrics are stored, transmitted, and monetized across cloud-connected therapy ecosystems. Japan's PMDA has established a distinct pathway for software as a medical device that accelerates conditional approval for VR systems demonstrating equivalence to existing neurorehabilitation modalities. Stakeholders must monitor how national reimbursement authorities classify VR stroke rehabilitation—as durable medical equipment, digital therapeutic, or telehealth service—because this determination locks in addressable market scale and pricing flexibility across each geography.
Market Dynamics
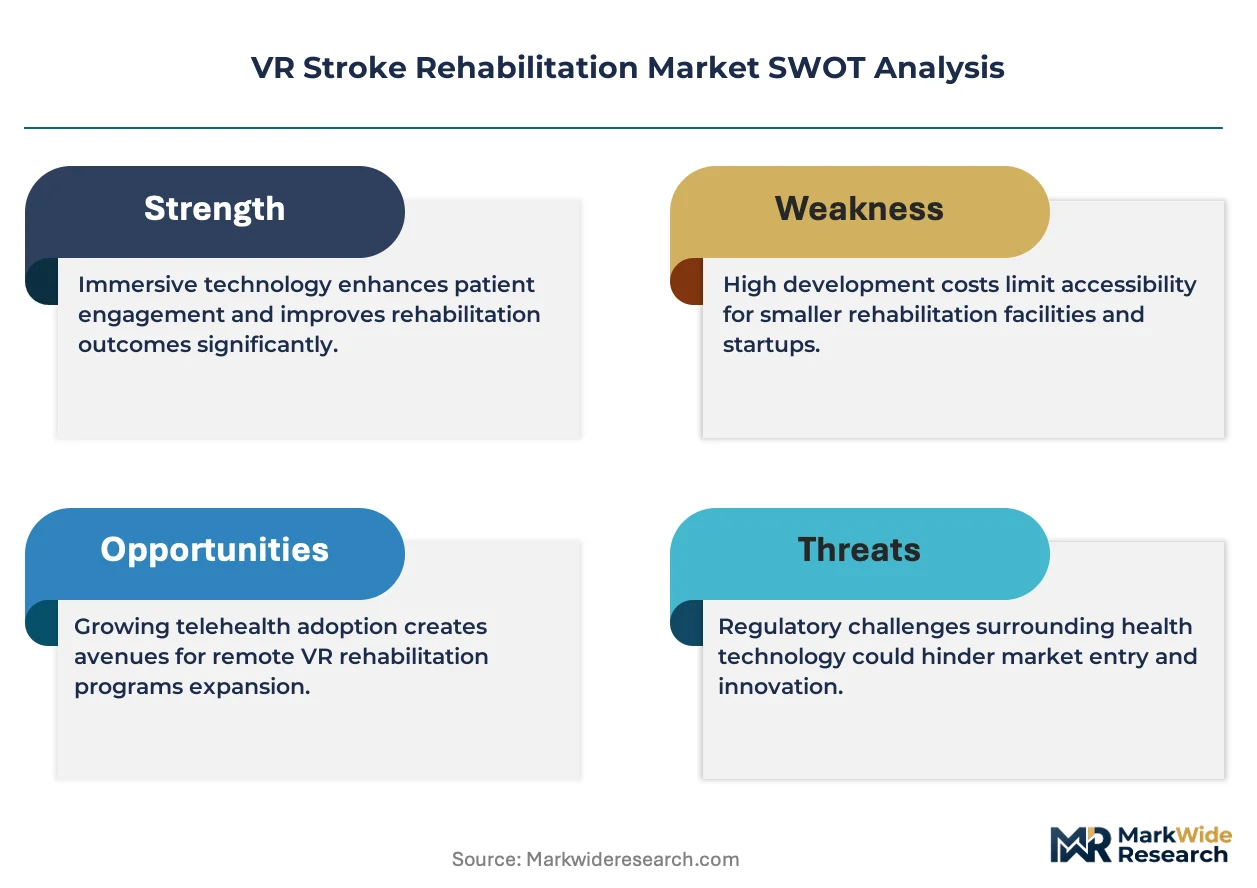
Reimbursement classification battles between durable medical equipment and digital therapeutic categories are forcing platform vendors to restructure clinical evidence packages and pricing architectures around payer acceptance rather than pure technical performance.
Growth Catalysts
- MDR CE marking maturity:Streamlined conformity assessment pathways under the EU Medical Device Regulation accelerate market access for VR neurorehabilitation systems seeking clinical claims across Germany, France, and the Netherlands.
- Home-based therapy protocols:Residential care providers deploy upper-extremity VR devices to extend hospital discharge timelines and reduce readmission penalties under value-based care frameworks.
- Aging demographic pressure:Japan's super-aged population structure generates sustained public investment in scalable motor recovery interventions through METI-sponsored healthcare robotics initiatives.
Market Restraints
- Hardware cost concentration:Haptic feedback gloves and motion capture sensors rely on precision electromechanical components sourced primarily from Taiwanese and South Korean suppliers, exposing margins to semiconductor foundry allocation constraints.
- Clinical validation timelines:FDA 510(k) clearance for novel VR therapeutic indications requires randomized controlled trials with stroke-specific functional endpoints, extending development cycles beyond typical software release cadences.
- Substitute modality persistence:Traditional constraint-induced movement therapy delivered by occupational therapists retains strong payer preference in Medicare Advantage networks due to established billing codes and liability frameworks.
Strategic Opportunities
- Remote patient monitoring convergence:Integration of VR therapy platforms with FDA-cleared digital biomarker collection creates reimbursable telehealth service lines beyond device rental models.
- German DiGA pathway expansion:Germany's Digital Health Applications fast-track approval offers conditional reimbursement for VR stroke rehabilitation software demonstrating equivalence to standard care within twelve months.
- Mixed reality overlay adoption:Depth-sensing camera arrays combined with passthrough video are enabling proprioceptive rehabilitation protocols that pure VR headsets cannot replicate.
Industry Challenges
- Neurorehabilitation specialist scarcity:Certified stroke rehabilitation therapists capable of interpreting VR-generated kinematic data and adjusting adaptive algorithms remain concentrated in academic medical centers, limiting deployment scalability.
- HIPAA-GDPR data architecture complexity:Cloud-connected therapy platforms must engineer separate data residency and consent management systems for US and European patient populations, fragmenting development resources.
- Legacy EHR integration friction:Hospital IT departments face substantial middleware costs connecting VR session outputs to Epic and Cerner electronic health record systems for longitudinal outcome tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Stroke Rehabilitation Market |
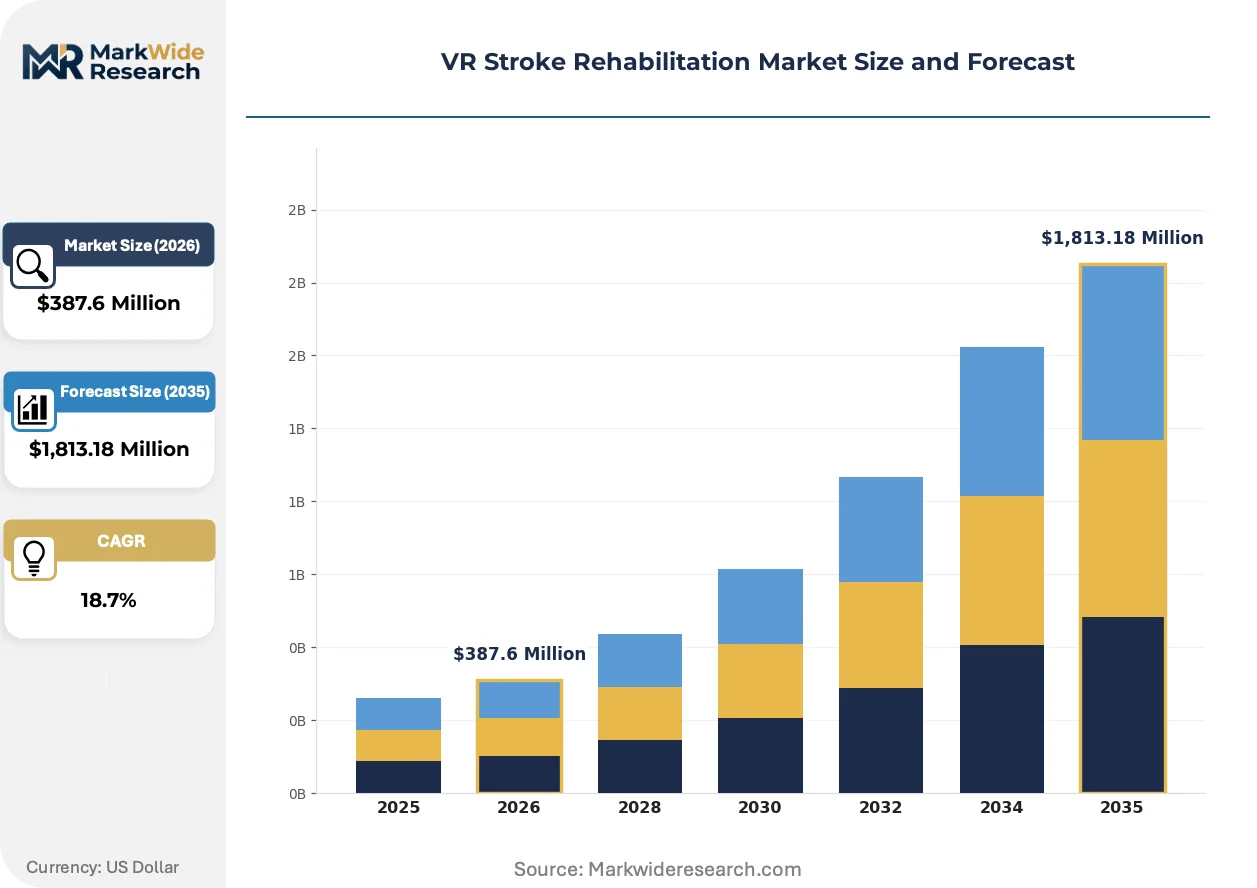
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,813.18 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Wearable Devices, Immersive Systems, Training Programs End User: Hospitals, Rehabilitation Centers, Home Care Providers, Clinics Technology: Virtual Reality, Augmented Reality, Mixed Reality, Gamification Application: Physical Therapy, Cognitive Rehabilitation, Pain Management, Motor Skills Training |
| Companies Covered | Cognimate, IRegained Inc., MindMaze SA, Bended, uMov spa, eXRt Intelligent Healthcare, Drop Digital Health, Flint Rehabilitation, Amal XR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Stroke Rehabilitation Market Evolving Landscape
Sensorimotor closed-loop architectures are displacing visual-only immersion as the dominant technical paradigm, with real-time biomechanical feedback rewiring how motor recovery protocols are designed and delivered across clinical and residential settings.
AI-driven adaptive difficulty engines are digitizing rehabilitation intensity calibration. These algorithmic systems analyze patient movement kinematics to auto-adjust task complexity without continuous therapist oversight. Hospital outpatient departments in the United States are piloting these platforms to expand patient throughput per clinical FTE. The structural compression of manual protocol adjustment is enabling same-staff volume scaling previously impossible under traditional delivery models.
Japan's PMDA software-as-a-medical-device conditional approval pathway is accelerating commercial entry for VR systems demonstrating equivalence to existing neurorehabilitation modalities. This regulatory architecture reduces pre-market clinical evidence burdens for platforms leveraging predicate device comparisons. Domestic developers and foreign entrants targeting the Japanese market are restructuring submission strategies around equivalence claims rather than novel therapeutic mechanism demonstrations.
After-sales service unbundling is fragmenting traditional device-plus-support contracts into separately billed training, maintenance, and algorithm update streams. Home care providers purchasing VR rehabilitation hardware now negotiate modular service tiers based on internal technical capabilities. This behavioral shift is most visible in German and US markets where reimbursement evolution creates incentive to minimize fixed cost commitments while preserving clinical outcome accountability.
VR Stroke Rehabilitation Market Segmentation
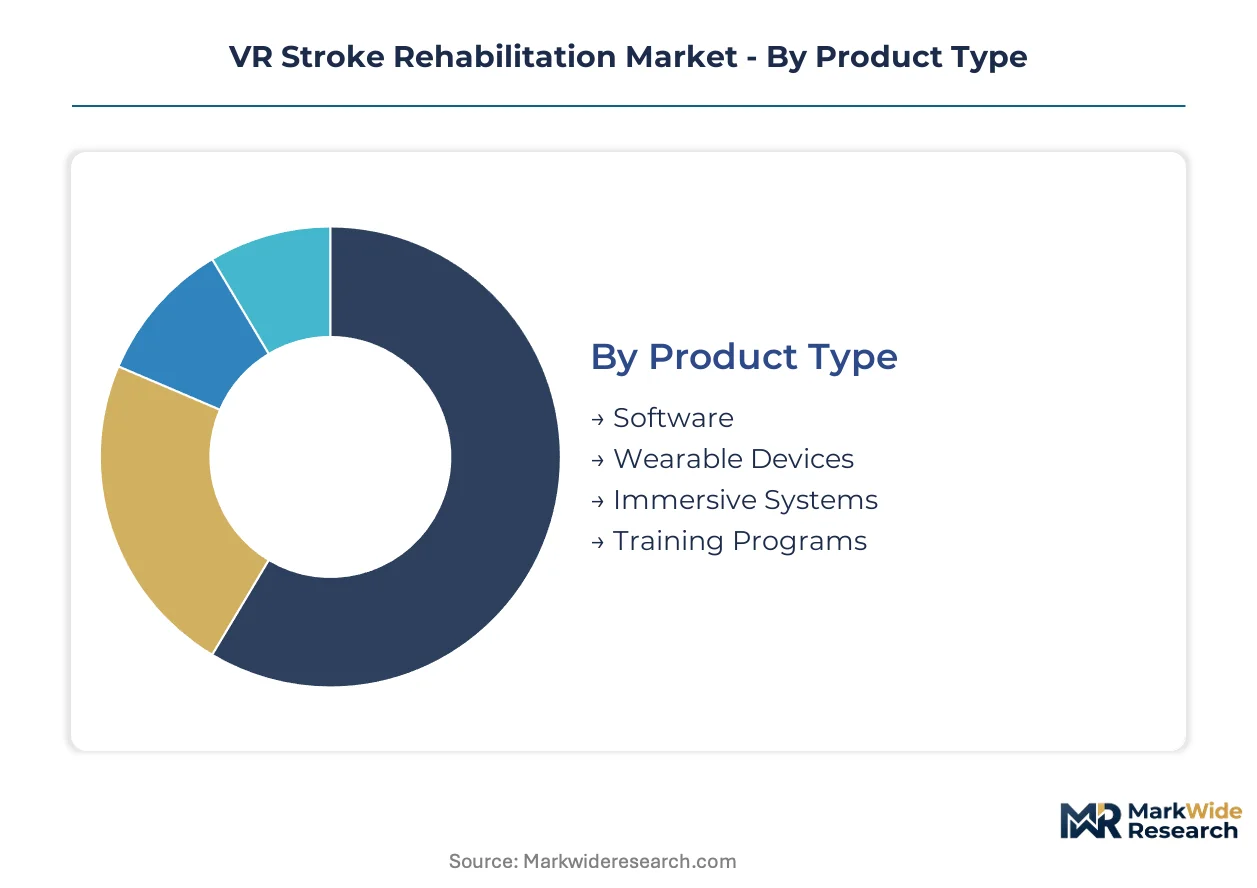
VR stroke rehabilitation platforms fragment across hardware, software, and service layers that each demand distinct commercial architectures. Understanding how these segments interact reveals where margin pools concentrate and which technology combinations unlock scalable deployment.
Product Type:
After-sales service intensity varies dramatically across product categories, with software platforms requiring continuous algorithm updates while hardware segments demand physical maintenance protocols.
- Software:Cloud-based therapy engines deliver adaptive difficulty algorithms and kinematic analytics through subscription licensing. German DiGA fast-track approvals concentrate demand here as payers seek reimbursable digital therapeutics with minimal hardware overhead.
- Wearable Devices:Haptic feedback gloves and motion capture sensors integrate with therapy platforms to provide closed-loop sensorimotor retraining. Rehabilitation centers in the United States prioritize these for upper-extremity protocols where proprioceptive feedback proves critical.
- Immersive Systems:Head-mounted displays with sub-20ms latency thresholds prevent motion sickness during neuroplasticity engagement sessions.
- Training Programs:Curated exercise libraries translate constraint-induced movement therapy into repeatable digital protocols.
Software holds the largest share; momentum sits with Wearable Devices.
End User:
Customer type determines pricing architecture flexibility, with institutional buyers negotiating enterprise licenses and residential segments driving per-session reimbursement innovation.
- Hospitals:Academic medical centers anchor installed base volume through centralized procurement of FDA-cleared platforms. These institutions generate the deepest data lakes for training adaptive algorithms.
- Rehabilitation Centers:Outpatient facilities in Japan leverage METI-sponsored robotics initiatives to scale motor recovery interventions for super-aged demographics.
- Home Care Providers:Residential deployment extends hospital discharge timelines under value-based care frameworks.
- Clinics:Private practice neurologists pilot mixed reality overlays for proprioceptive rehabilitation.
Hospitals dominate current volume; Home Care Providers are climbing the fastest.
Technology:
Technical maturity curves separate established modalities from emerging architectures that rewire competitive positioning.
- Virtual Reality:Head-mounted displays with motion tracking deliver task-specific exercises for hemiparetic patients. FDA 510(k) clearance pathways for VR therapeutic indications require stroke-specific functional endpoints.
- Augmented Reality:Overlay systems project digital guidance onto physical rehabilitation environments. These platforms reduce hardware costs while preserving spatial awareness.
- Mixed Reality:Depth-sensing camera arrays combined with passthrough video enable proprioceptive protocols that pure VR cannot replicate.
- Gamification:Behavioral incentive engines drive patient adherence through achievement mechanics and progress visualization.
Virtual Reality holds the largest share; momentum sits with Mixed Reality.
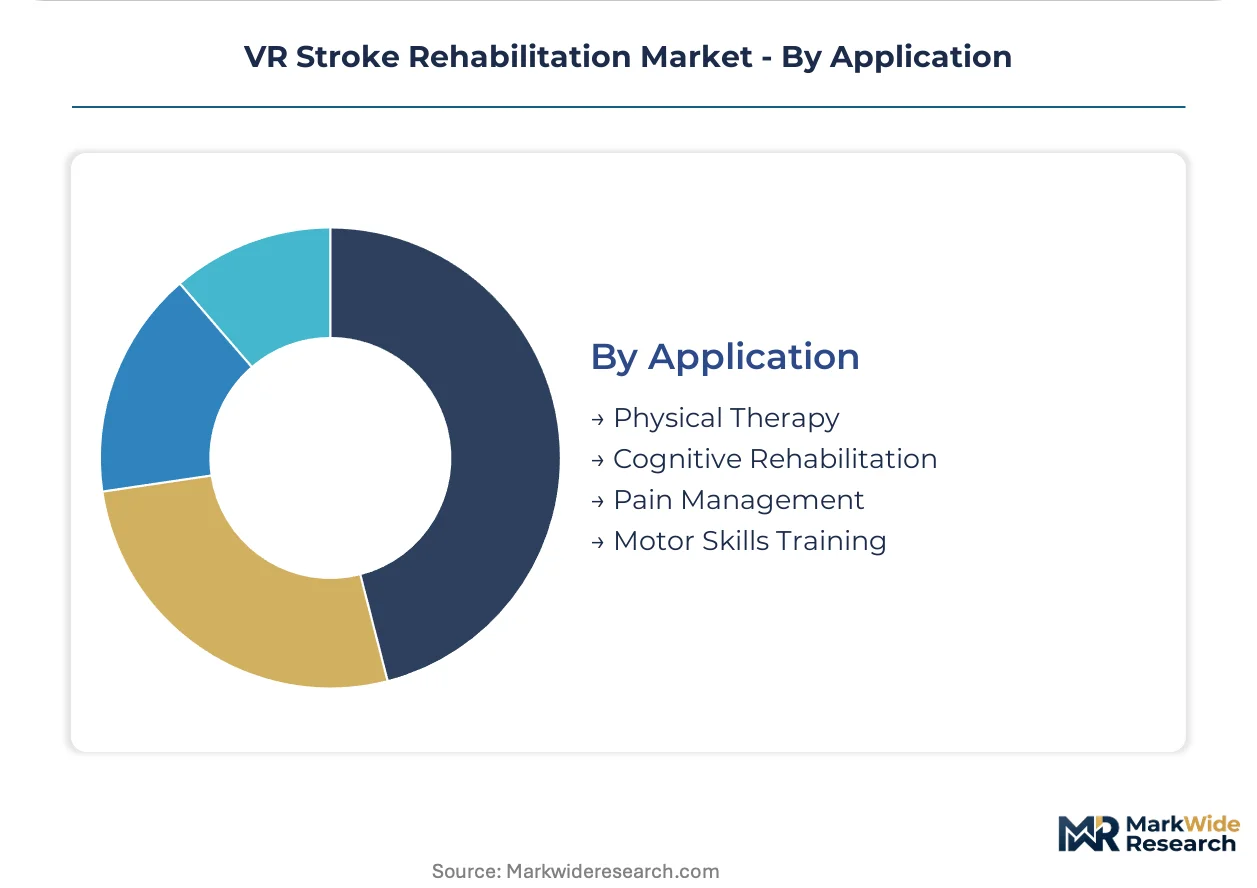
Application:
Clinical indication breadth determines addressable patient populations and reimbursement code availability across geographies.
- Physical Therapy:Repetitive task-specific exercises target upper and lower limb recovery through immersive motor retraining. Medicare Advantage networks in the United States show strong preference for established billing codes.
- Cognitive Rehabilitation:Attention, memory, and executive function protocols address post-stroke cognitive deficits. Japanese PMDA software-as-a-medical-device pathways accelerate approval for these indications.
- Pain Management:Distraction-based interventions reduce analgesic dependency during acute recovery phases.
- Motor Skills Training:Fine motor control exercises digitize mirror therapy and bilateral training protocols.
Physical Therapy holds the largest share; Cognitive Rehabilitation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and rehabilitation center administrators concentrate purchasing power in Germany, the United States, and Japan where aging demographics and evolving reimbursement frameworks drive sustained platform investment.
Germany
Rehabilitation centers in Bavaria and North Rhine-Westphalia deploy upper-extremity VR devices to extend hospital discharge timelines under value-based care contracts. The BfArM Digital Health Applications fast-track pathway grants conditional reimbursement for stroke rehabilitation software demonstrating equivalence to standard care within twelve months. Berlin-based academic medical centers generate deep kinematic data lakes for training adaptive therapy algorithms.
United States
Medicare Advantage networks and hospital outpatient departments anchor installed base volume through centralized procurement of FDA-cleared platforms. FDA digital health pre-certification pathways shape product development timelines for VR therapeutic indications requiring stroke-specific functional endpoints. The Greater Boston and San Francisco Bay Area clusters host the deepest concentration of neurotechnology startups integrating brain-computer interfaces with motor recovery protocols.
Japan
METI-sponsored healthcare robotics initiatives channel public investment toward scalable motor recovery interventions for super-aged population structures. The PMDA software-as-a-medical-device conditional approval pathway accelerates commercial entry for VR systems demonstrating equivalence to existing neurorehabilitation modalities. The Kanto region around Tokyo concentrates rehabilitation center deployment of immersive therapy platforms.
United Kingdom
NHS England integrated care boards pilot VR stroke rehabilitation within community neurorehabilitation services to reduce acute hospital bed occupancy. MHRA guidance on software medical devices aligns with EU MDR transitional provisions for CE-marked platforms. The Oxford-Cambridge-London golden triangle anchors clinical validation partnerships between academic medical centers and immersive technology developers.
Netherlands
Rehabilitation centers in the Randstad conurbation integrate mixed reality overlays for proprioceptive rehabilitation protocols. The Dutch Healthcare Authority's guidance on digital therapeutics reimbursement creates precedent for VR stroke rehabilitation classification outside durable medical equipment categories. Eindhoven's health technology cluster concentrates hardware development for haptic feedback gloves and motion capture sensors.
VR Stroke Rehabilitation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented therapeutic hardware, adaptive software engines, and bundled service architectures. The vendor base separates into three strategic archetypes: neurotechnology specialists with brain-computer interface capabilities, home-based therapy device manufacturers, and AI-driven adaptive algorithm platforms. Dominant competitive moves include regulatory pathway optimization around FDA 510(k) and CE MDR timelines, plus reimbursement classification lobbying to secure digital therapeutic rather than durable medical equipment status.
Within the neurotechnology specialist tier, MindMaze SA exemplifies European development anchored in brain-computer interfaces for motor recovery. Flint Rehabilitation occupies a position representing home-based segment specialization with upper-extremity therapy devices extending clinical protocols into residential settings. eXRt Intelligent Healthcare sits within the AI-driven adaptive difficulty category, personalizing rehabilitation intensity through algorithmic systems that analyze patient movement kinematics without continuous therapist oversight.
| Leading Market Players |
|---|
| Cognimate |
| IRegained Inc. |
| MindMaze SA |
| Bended |
| uMov spa |
| eXRt Intelligent Healthcare |
| Drop Digital Health |
| Flint Rehabilitation |
| Amal XR |
| Others |
Value Network & Pricing Analysis
Taiwanese semiconductor foundries and South Korean precision electromechanical component suppliers anchor upstream cost structures for haptic feedback gloves and motion capture sensors, concentrating margin capture in software subscription tiers where adaptive algorithm licensing escapes hardware commodity dynamics.
Pricing Analysis
Cost-plus contracts with Taiwanese foundry indexation dominate hardware procurement for VR rehabilitation platforms. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared hospital systems from CE-marked rehabilitation center bundles and unregistered home care devices. Pricing pressure stems from Medicare Advantage preference for established occupational therapy billing codes over novel digital therapeutic categories. Home care providers exhibit highest price sensitivity due to reimbursement uncertainty, while academic medical centers absorb premium tiers for algorithm training data access.
Supply Chain Analysis
Upstream feedstock for immersive displays draws from Taiwanese semiconductor foundries, South Korean OLED panel manufacturers, and Chinese rare earth processors for motion sensor magnet assemblies. Precision electromechanical components for haptic feedback rest on South Korean and Japanese supplier networks. Single-source vulnerability concentrates in sub-20ms latency display controllers sourced from Taiwanese fabless designers. Distribution runs through hospital procurement departments and rehabilitation center group purchasing organizations, with direct-to-provider channels expanding for home care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with reimbursement classification battles creating distinct vendor archetypes: neurotechnology specialists, home-based device manufacturers, and AI-driven algorithm platforms each occupy defensible niches as payer frameworks diverge across geographies.
For Market Incumbents: Harden regulatory moats through simultaneous FDA 510(k) and CE MDR submission strategies that exhaust emerging competitor resources. Deepen vertical integration into motion capture sensor design to offset Taiwanese foundry allocation constraints threatening hardware margins. Prioritize hospital system partnership lock-in via Epic and Cerner EHR integration middleware that elevates switching costs for adaptive therapy platforms. For New Entrants and Emerging Players: German DiGA fast-track approvals for stroke rehabilitation software represent the most penetrable entry point, offering conditional reimbursement without hardware infrastructure investment. Target cognitive rehabilitation applications where PMDA equivalence pathways reduce clinical evidence burdens compared to physical therapy indications. Pursue white-label algorithm licensing to established rehabilitation device manufacturers lacking in-house AI capabilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital health platforms possessing FDA pre-certification status but requiring reimbursement classification lobbying expertise. Five-to-ten year viability hinges on successful digital therapeutic designation capture in Medicare Advantage networks. Watch for German BfArM reimbursement decisions as inflection indicators for European market scaling potential.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Stroke-specific functional endpoints unlock Medicare Advantage billing code access for hospital outpatient departments. |
| CE MDR Pathway | Conformity assessment acceleration enables German DiGA fast-track entry for adaptive therapy algorithms. |
| Hospital System Partnership | Epic and Cerner EHR integration creates longitudinal outcome tracking stickiness for kinematic data platforms. |
| Software Companion Development | AI-driven adaptive difficulty engines reduce therapist-to-patient ratios under value-based care frameworks. |
| Reimbursement Strategy | Digital therapeutic classification secures pricing flexibility beyond durable medical equipment commodity tiers. |
Research Methodology
Operator-level perspectives from rehabilitation center administrators, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interview synthesis combined with secondary validation from FDA 510(k) filings, CE MDR submission databases, CMS Medicare reimbursement codes, and German BfArM Digital Health Applications registries. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across hardware, software, and service layer revenue decomposition.
Scenario-bracketing framed projections across conservative, baseline, and expansion cases throughout the forecast period. Segmentation dimensions modeled include product type, end user category, technology modality, and application indication. CAGRs derived from regression analysis of historical adoption curves adjusted for reimbursement policy inflection points. Industry-specific inputs incorporated PMDA software-as-a-medical-device approval timelines and METI healthcare robotics initiative funding allocations.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Taiwanese semiconductor foundries into haptic hardware assembly would shift outcomes. Material shifts in FDA digital therapeutic classification precedents or German DiGA equivalence demonstration requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
Veterinary Rehabilitation Services Market
Rehabilitation Services
Physiotherapy Services Market
Rehabilitation Services
Rehabilitation Therapy Services Market
Rehabilitation Services
Rehabilitation Robots Market
Rehabilitation Services
Global Home Rehabilitation Products and Services Market
Rehabilitation Services
Asia-Pacific Repair and Rehabilitation Market
Rehabilitation Services
Occupational and Physical Therapy Services Market
Rehabilitation Services
Global Outpatient Rehabilitation Centers Market
Rehabilitation Services
Wearable Neurorehabilitation Devices Market
Rehabilitation Services
US Assisted Living Facility and Neurorehabilitation Market
Rehabilitation Services
Rehabilitation Equipment Market
Rehabilitation Services
Home Rehabilitation Services Market
Rehabilitation Services
Outpatient Rehabilitation Services Market
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
Global Neurorehabilitation Devices Market