
 Thoracic Outlet Syndrome Market | 2026-2036
Thoracic Outlet Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Thoracic Outlet Syndrome Market Analytics
Specialized thoracic surgeon availability is bifurcating market access between major metropolitan corridors and secondary care markets. Pfizer Inc. leverages its established pain management portfolio to anchor pharmacological treatment channels for neurogenic TOS. Medtronic sustains technology leadership in minimally invasive decompression instrumentation, while Stryker competes through integrated operating room ecosystems that streamline surgical workflow.
Thoracic outlet syndrome encompasses compression of the brachial plexus, subclavian artery, or subclavian vein in the anatomical space between the first rib and clavicle, with diagnosis requiring dynamic ultrasound, CT angiography, or electrophysiological studies to confirm vascular or neurogenic involvement. Conservative management through physical therapy and pharmacological treatment dominates initial patient encounters, though surgical intervention captures disproportionate value in severe and chronic severity levels where first-rib resection or scalenectomy becomes indicated. Diagnostic imaging represents the fastest-growing product type as referral protocols increasingly mandate pre-interventional vascular assessment.
FDA governs device safety and clinical trial endpoints for stent-assisted venous recanalization, while HIPAA shapes how patient-reported outcome data flows across outpatient clinics and research institutions. The EU MDR extends compliance burdens for manufacturers seeking CE marking on thoracic decompression instruments. Stakeholders must monitor how CMS reimbursement determinations for catheter-directed thrombolysis versus open surgical repair reshape provider economics and patient access patterns.
Market Dynamics
Hospital consolidation into integrated delivery networks is concentrating TOS patient volumes into high-throughput surgical centers, compressing margins for independent community hospitals and forcing equipment procurement into centralized contracting frameworks.
Growth Catalysts
- EU MDR streamlining:The EU Medical Device Regulation's Article 54 pathway for well-established technologies accelerates CE marking timelines for thoracic decompression instruments, reducing regulatory friction for European market entry.
- Dynamic ultrasound protocols:Adoption of positional stress testing with Doppler imaging is expanding diagnostic sensitivity for vascular TOS, capturing previously missed cases in outpatient cardiology and vascular medicine clinics.
- Boston-Philadelphia corridor concentration:Academic medical centers along the US Northeast corridor are establishing dedicated multidisciplinary TOS clinics, creating referral gravity that pulls complex cases from secondary markets.
Market Restraints
- Titanium implant cost volatility:First-rib resection hardware and fixation plates face input cost pressure from aerospace sector competition for titanium alloy supply, squeezing device manufacturer margins.
- Specialist surgeon scarcity:Fellowship-trained thoracic outlet surgeons concentrate in approximately 40 US metropolitan areas, creating access deserts across the Mountain West and rural Southeast where general vascular surgeons lack case volume to maintain proficiency.
- Conservative management substitution:Physical therapy protocols for neurogenic TOS achieve symptom resolution in 60-70% of cases, limiting the addressable surgical population and compressing procedural volumes.
Strategic Opportunities
- Telemedicine triage networks:Virtual specialty consultation platforms connect peripheral clinics with TOS centers, capturing diagnostic referrals earlier in the patient journey and reducing geographic leakage.
- Japan's aging surgical population:Japan's PMDA has streamlined orthopedic and vascular device approvals for elderly-specific indications, creating regulatory tailwind for minimally invasive decompression tools targeting octogenarian patients.
- AI-assisted surgical planning:Machine learning algorithms analyzing CT angiography datasets are converging with 3D-printed patient-specific rib models, enabling preoperative simulation that reduces operative time and complication rates.
Industry Challenges
- Electrophysiological interpretation skill gap:EMG and nerve conduction study expertise for brachial plexus assessment resides in shrinking numbers of specialized neuromuscular neurologists, creating diagnostic bottleneck.
- Multi-year FDA PMA timelines:Novel venous stent designs for Paget-Schroetter syndrome require premarket approval pathways averaging 18-24 months, delaying revenue recognition and consuming clinical trial capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thoracic Outlet Syndrome Market |
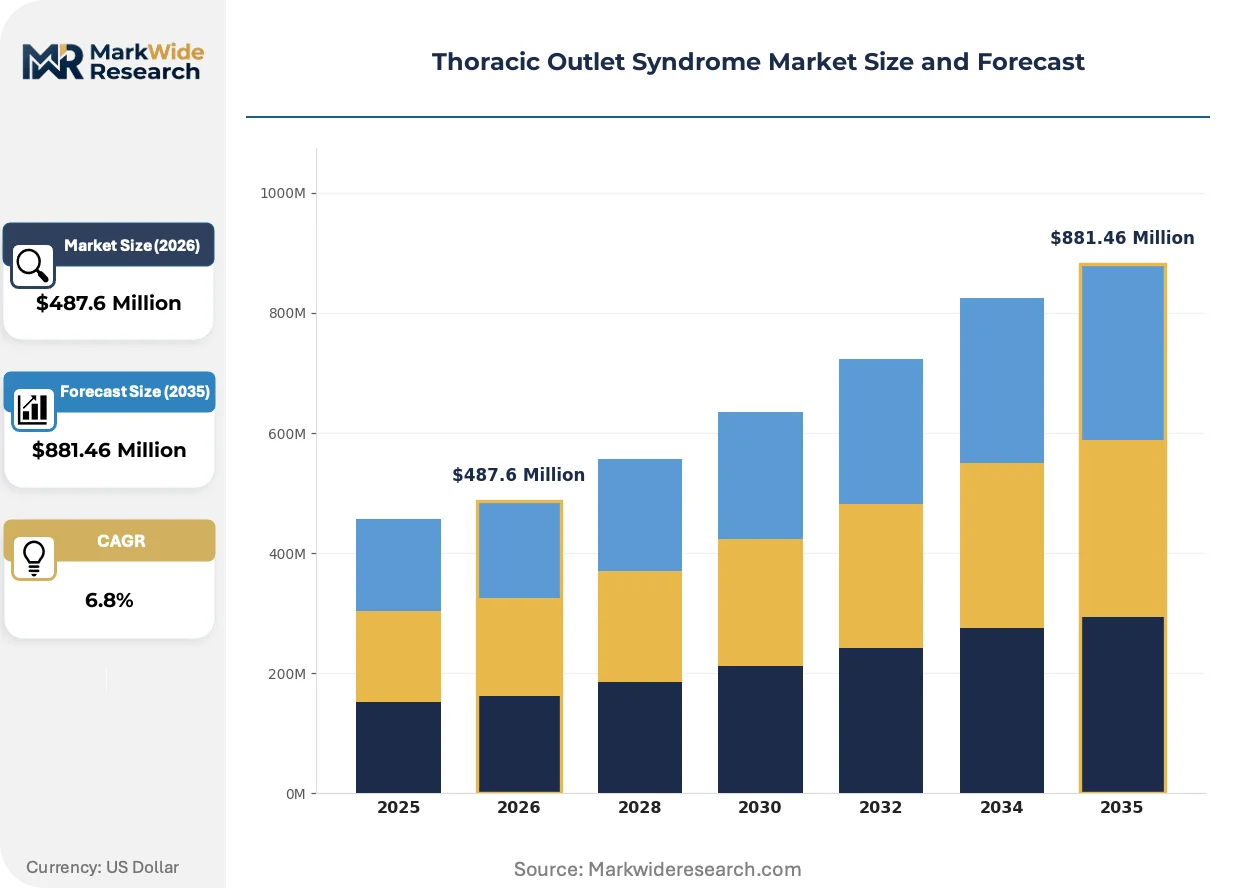
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Physical Therapy, Surgery, Diagnostic Imaging End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Research Institutions Treatment Approach: Conservative Management, Surgical Intervention, Pharmacological Treatment, Lifestyle Modification Severity Level: Mild, Moderate, Severe, Chronic |
| Companies Covered | Pfizer Inc., Bayer AG, GlaxoSmithKline plc, Novartis AG, Sanofi, Johnson & Johnson, Bristol-Myers Squibb Company, Medtronic, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thoracic Outlet Syndrome Market Evolving Landscape
Robotic-assisted surgical platforms are penetrating thoracic outlet procedures, altering capital equipment procurement patterns and redefining the skill sets required for minimally invasive first-rib resection.
Single-port robotic systems are displacing traditional thoracoscopic instrumentation in high-volume academic centers. Vascular surgery departments at Cleveland Clinic and Mayo Clinic are adopting these platforms for scalenectomy and rib resection, compressing recovery timelines from six weeks to ten days. The technology is displacing conventional video-assisted thoracoscopic surgery in the premium surgical segment, forcing instrument manufacturers to develop compatible retractor and cautery attachments.
The EU MDR's enhanced post-market surveillance requirements are reshaping device economics. Manufacturers must now maintain clinical follow-up registries for thoracic decompression implants, adding 12-15% to ongoing compliance costs. Small and mid-cap orthopedic device companies are responding by withdrawing marginal product lines from the European market, concentrating supply among firms with dedicated regulatory infrastructure.
Self-referral patterns among young athletes and manual laborers are fragmenting the traditional primary-care-to-specialist pathway. Patients with arm swelling or paresthesia increasingly initiate diagnostic workups through direct-to-consumer vascular screening services, bypassing neurology and orthopedics entirely. This channel shift is most pronounced in Texas, Florida, and California, where concierge medicine models and employer-sponsored wellness programs embed vascular ultrasound screening.
Thoracic Outlet Syndrome Market Segmentation
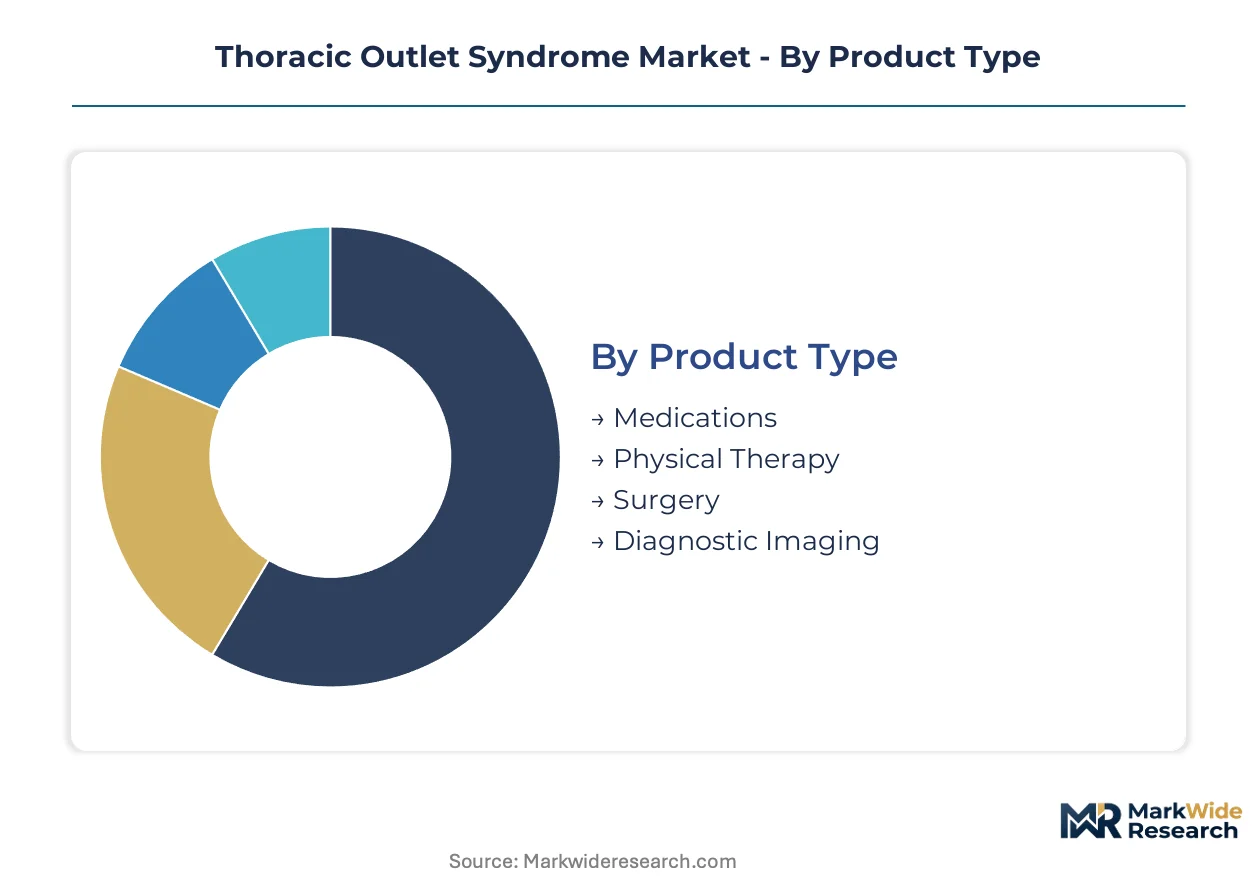
Thoracic outlet syndrome treatment pathways fragment across diagnostic, therapeutic, and care delivery dimensions. Each segmentation axis reveals distinct margin architectures and competitive dynamics that shape vendor positioning and provider economics.
Product Type:
Margin pools concentrate in procedural interventions and capital-intensive diagnostics rather than commoditized pharmacological agents.
- Surgery:First-rib resection, scalenectomy, and venous decompression procedures command premium reimbursement through bundled payment models. Academic medical centers in Boston and Philadelphia anchor high-volume surgical programs that concentrate profitability in complex cases requiring vascular reconstruction.
- Diagnostic Imaging:CT angiography protocols and dynamic ultrasound systems capture disproportionate value as referral mandates intensify pre-interventional vascular assessment. Equipment manufacturers compete through integrated workstation bundles that streamline image interpretation workflow.
- Medications:Muscle relaxants, anticoagulants, and neuropathic pain agents face generic competition and formulary pressure that compresses branded pharmaceutical margins.
- Physical Therapy:Conservative rehabilitation protocols dominate initial patient encounters but generate lower per-episode revenue compared to surgical or diagnostic alternatives.
The dominant share belongs to Surgery, while Diagnostic Imaging is closing the gap fastest.
End User:
Patient volume and reimbursement intensity diverge sharply between institutional settings.
- Hospitals:Integrated delivery networks concentrate complex decompressive procedures and catheter-directed thrombolysis in high-throughput surgical centers. Vascular surgery departments at Cleveland Clinic and Mayo Clinic exemplify the capital intensity and specialized staffing that define this tier.
- Outpatient Clinics:Community-based cardiology and vascular medicine practices capture diagnostic workups and postoperative surveillance through point-of-care ultrasound expansion.
- Rehabilitation Centers:Physical therapy protocols for neurogenic TOS achieve symptom resolution in the majority of cases, limiting downstream surgical referrals.
- Research Institutions:Academic centers generate clinical evidence and train fellowship surgeons but represent limited commercial volume.
Hospitals capture the largest revenue pool, though Outpatient Clinics are expanding share through direct-to-consumer screening channels.
Treatment Approach:
Clinical decision pathways determine addressable market boundaries for device and pharmaceutical manufacturers.
- Conservative Management:Physical therapy and activity modification protocols resolve symptoms in most neurogenic TOS presentations, constraining surgical candidacy pools.
- Surgical Intervention:First-rib resection and scalenectomy procedures concentrate in specialized centers with fellowship-trained thoracic outlet surgeons.
- Pharmacological Treatment:Anticoagulation for venous TOS and neuropathic pain management anchor pharmaceutical positioning.
- Lifestyle Modification:Ergonomic intervention and activity restriction protocols compete with formal medical therapy in occupational health settings.
Conservative Management dominates initial encounters, yet Surgical Intervention generates the highest per-patient value.
Severity Level:
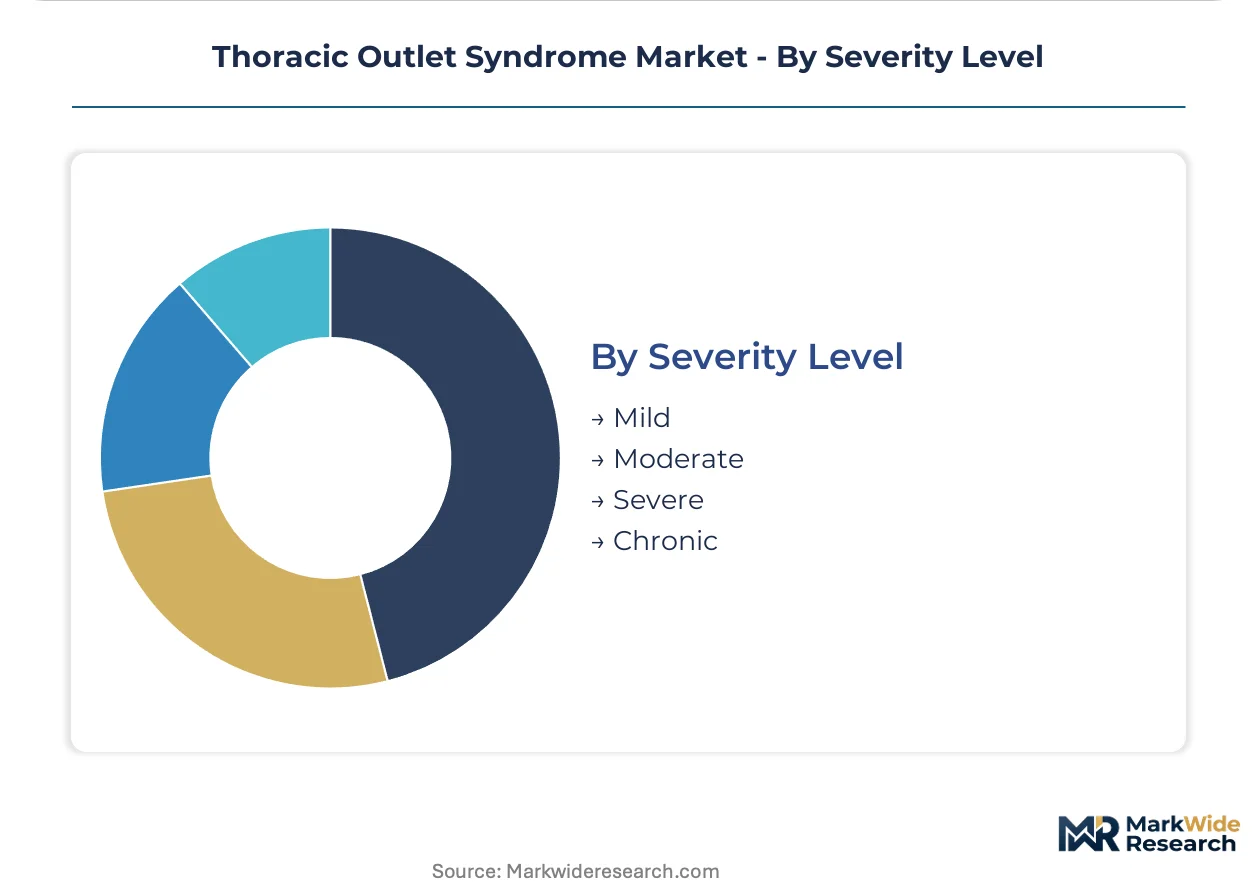
Case complexity stratifies across treatment intensity and reimbursement tiers.
- Severe:Vascular compromise and progressive neurological deficit mandate urgent surgical decompression with associated intensive care and interventional radiology support.
- Chronic:Recurrent or persistent symptoms despite prior intervention drive repeat procedures and specialized pain management referrals.
- Moderate:Intermittent symptoms with functional limitation support conservative trial before surgical consideration.
- Mild:Transient paresthesia and minimal functional impact respond to activity modification with limited medical resource utilization.
Severe presentations concentrate the highest procedural value, while Chronic cases extend longitudinal revenue through repeat intervention cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic intensity and surgical specialization diverge sharply across geographies, with the United States favoring early procedural intervention while European and Asian systems emphasize conservative management pathways before surgical escalation.
United States
Academic medical centers in Boston, New York, and Philadelphia anchor high-volume TOS referral networks that concentrate complex decompressive procedures. FDA clearance pathways for neurovascular stents have shortened time-to-market for device innovators, accelerating adoption of minimally invasive venous recanalization. Hospital consolidation into integrated delivery networks is compressing patient volumes into Cleveland Clinic and Mayo Clinic surgical centers.
Germany
Specialized thoracic surgery departments at Charité Berlin and Heidelberg University Hospital drive European clinical evidence generation for rib-sparing decompression techniques. EU MDR Article 54 pathways accelerate CE marking for well-established thoracic instruments, reducing regulatory friction for domestic manufacturers. Bavarian medical device clusters around Munich supply precision-machined titanium fixation hardware to continental surgical centers.
Japan
PMDA streamlining of orthopedic and vascular device approvals for elderly-specific indications creates regulatory tailwind for minimally invasive tools targeting octogenarian patients. METI funding for robotic surgical platforms accelerates adoption of single-port systems in Tokyo and Osaka academic hospitals. Kyushu regional health networks face specialist surgeon scarcity that limits access to fellowship-trained thoracic outlet procedures.
United Kingdom
NHS England referral protocols mandate dynamic ultrasound assessment before surgical consultation, expanding diagnostic imaging demand in cardiology and vascular medicine clinics. MHRA post-Brexit regulatory autonomy permits faster national adoption of novel venous stent designs compared to EU harmonization timelines. London teaching hospitals concentrate multidisciplinary TOS clinics that pull complex cases from Midlands and Northern England secondary markets.
Australia
TGA approval pathways for imported thoracic decompression instruments maintain rigorous clinical evidence requirements that favor established multinational suppliers over emerging device entrants. Public hospital procurement through state-based health networks concentrates surgical volumes in Sydney and Melbourne tertiary centers. Queensland and Western Australia face geographic access barriers that telemedicine triage networks are beginning to address.
Thoracic Outlet Syndrome Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical conglomerates controlling pharmacological channels and diversified medtech corporations dominating surgical instrumentation. Market structure reflects dual competitive logics: drug manufacturers compete through pain management portfolio breadth and formulary positioning, while device suppliers differentiate through operating room ecosystem integration and minimally invasive platform development. Three archetypes prevail—vertically integrated pharma-medtech hybrids, pure-play surgical instrument specialists, and diagnostic imaging workstation bundlers. Competitive moves center on strategic partnerships between device manufacturers and academic surgical centers for clinical evidence generation, plus portfolio diversification into adjacent vascular compression syndromes.
Among pharmaceutical conglomerates, Pfizer Inc. and Bayer AG exemplify the integrated pharma archetype with established pain management and anticoagulant portfolios that anchor conservative treatment channels. Medtronic plc represents the diversified medtech tier, competing through capital-intensive minimally invasive platforms and integrated surgical workflow systems. These three companies occupy positions that reflect the market's bifurcation between pharmacological management and procedural intervention, with each archetype defending distinct margin pools across the treatment pathway.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bayer AG |
| GlaxoSmithKline plc |
| Novartis AG |
| Sanofi |
| Johnson & Johnson |
| Bristol-Myers Squibb Company |
| Medtronic |
| Stryker |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between integrated delivery networks and titanium alloy suppliers lock in both surgical hardware access and cost predictability for first-rib resection programs, insulating high-volume centers from aerospace sector demand spikes that otherwise destabilize implant pricing.
Pricing Analysis
Project-based pricing dominates surgical intervention bundles, with academic medical centers negotiating case-rate contracts that consolidate facility, physician, and implant fees. Price differentiation hinges on surgeon fellowship credentials and robotic platform availability versus conventional thoracoscopic approaches. Cost compression in standard decompression hardware is intensifying because aerospace manufacturers compete for titanium feedstock. Community hospitals exhibit highest price sensitivity, while Cleveland Clinic and Mayo Clinic surgical centers command premium positioning through outcomes data and referral gravity.
Supply Chain Analysis
Inventory buffers for titanium fixation plates and robotic surgical attachments extend lead times to 16-20 weeks, forcing procurement teams into advance capacity reservations. Manufacturing concentrates in Germany, Switzerland, and the United States, with Bavarian precision-machining clusters supplying continental European surgical centers. Supply chains draw from aerospace-grade titanium alloy, specialized nitinol for venous stents, and high-density polyethylene for patient-specific 3D-printed rib models. Single-source vulnerability persists for single-port robotic cautery attachments. Distribution runs through GPO contracts and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including postoperative surveillance protocols and remote patient monitoring platforms are expanding faster than capital equipment sales, creating durable recurring revenue layers that offset hardware margin compression.
For Market Incumbents: Secure exclusive supply agreements with titanium alloy processors to defend against aerospace sector demand spikes that threaten implant cost structures. Deepen backward integration into 3D-printed patient-specific rib modeling services, capturing preoperative planning revenue that emerging AI-assisted surgical planning vendors are targeting. For New Entrants and Emerging Players: Anchor in telemedicine triage networks connecting rural and Mountain West access deserts with established TOS centers, exploiting specialist surgeon scarcity that limits local diagnosis. Target Japan's octogenarian surgical population through PMDA-streamlined minimally invasive device pathways, leveraging METI funding for robotic platform adoption in Tokyo and Osaka academic hospitals. For Investors and Strategic Acquirers: Capital is best deployed toward diagnostic imaging workstation bundlers with integrated AI-assisted CT angiography interpretation capabilities, as referral protocols increasingly mandate pre-interventional vascular assessment. Watch FDA PMA timeline compression for novel venous stent designs as the inflection signal indicating regulatory pathway maturation for Paget-Schroetter syndrome interventions.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic anchor referral networks that concentrate complex surgical volumes. |
| CE Marking Pathway | EU MDR Article 54 accelerates thoracic decompression instrument approvals for established technologies. |
| Software Companion Development | AI-assisted surgical planning algorithms analyzing CT angiography datasets reduce operative complication rates. |
| Reimbursement Strategy | CMS determinations for catheter-directed thrombolysis reshape provider economics and patient access patterns. |
| FDA Submission | Premarket approval pathways for neurovascular stents govern time-to-market for venous recanalization innovators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) and PMA filings, CMS reimbursement determinations, and hospital procurement databases. Interviews with thoracic surgeons, vascular medicine specialists, GPO contracts managers, and biomedical engineers informed demand-side dynamics. Secondary validation drew from ClinicalTrials.gov, EU MDR notified body documentation, and Japanese PMDA approval records. Bottom-up patient volume modeling and top-down spending allocation triangulation anchored market sizing.
Segmentation dimensions modeled span treatment approach, severity level, product type, and end-user setting across the projection horizon. CAGRs were derived from procedure volume trajectories and reimbursement intensity shifts. Forecast inputs incorporated specialist surgeon supply constraints, EU MDR compliance cost inflation, and robotic platform adoption curves in academic medical centers.
Decision-makers should treat outputs as directional under assumptions of stable CMS reimbursement and titanium alloy supply continuity; material deviation in aerospace sector demand or regulatory timeline compression would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Acromegaly Market
Specialty Medicine
Brugada Syndrome Market
Specialty Medicine
Global Melanoma Therapeutics Market
Specialty Medicine
Germ Cell Tumors Market
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Herpangina Treatment Market
Specialty Medicine
Neurometabolic Disorder Market
Specialty Medicine
Hemochromatosis Treatment Market
Specialty Medicine
Alport Syndrome Treatment Market
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
Hemophilia Market