
 Saudi Arabia and Egypt Healthcare 3D Printing Market | 2026-2036
Saudi Arabia and Egypt Healthcare 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia and Egypt Healthcare 3D Printing Market Intelligence
Multi-material extrusion combined with AI-driven topology optimization is tilting production economics toward patient-specific devices at scale. Stratasys Ltd. leverages its fused deposition modeling portfolio to anchor hospital workflows across the Gulf. Materialise NV sustains software-to-hardware integration that controls surgical planning and guide production. 3D Systems, Inc. specializes in biocompatible photopolymer platforms that dominate dental and maxillofacial applications.
Healthcare 3D printing in Saudi Arabia and Egypt encompasses additive fabrication of anatomical models, implants, prosthetics, and bioprinting scaffolds using polymers, metals, and living cell suspensions, with layer resolutions typically ranging from 25 to 100 microns depending on the clinical application. Its primary purpose is to reduce surgical time, improve patient outcomes, and enable distributed manufacturing of customized medical devices near the point of care. Implants and prosthetics command the deepest revenue pools due to reimbursement traction and regulatory clarity, while bioprinting materials represent the fastest-growing category as tissue engineering protocols mature in research institutions. Fused deposition modeling retains the broadest installed base across Egyptian and Saudi hospitals, though selective laser sintering in metals is gaining share in orthopedic centers requiring load-bearing titanium constructs.
SFDA in Saudi Arabia and Egypt's national pharmaceutical regulator enforce medical device registration and quality management standards that shape market access timelines for imported 3D printers and materials. Both jurisdictions are aligning with ISO 13485 and IEC 62304 frameworks to harmonize software-controlled medical device production with international safety benchmarks. Stakeholders must monitor how evolving national health insurance reimbursement policies for patient-specific implants alter procurement incentives across public and private hospital networks.
Market Dynamics
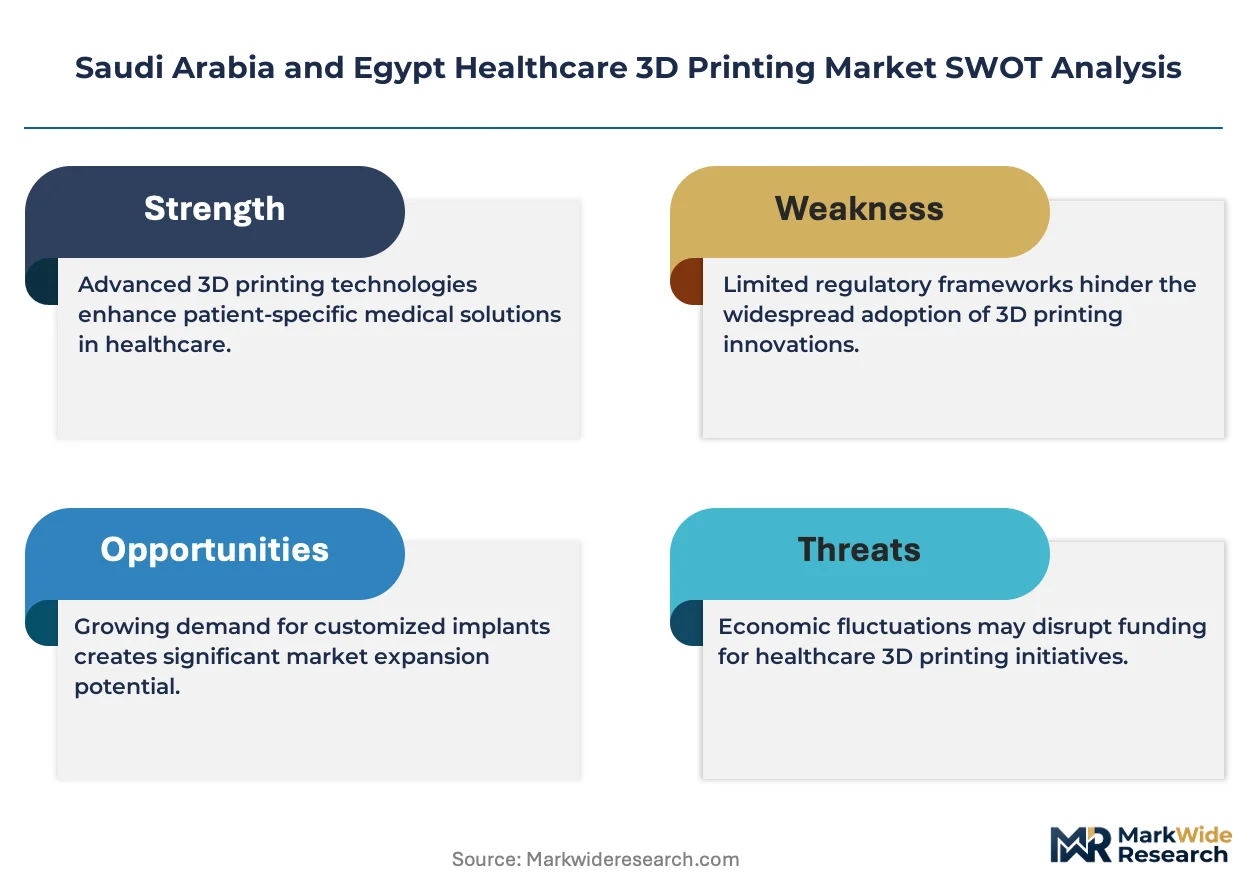
SFDA's tightening quality frameworks for patient-specific implants are compressing market access timelines and forcing manufacturers to reconfigure software-controlled production workflows around ISO 13485 and IEC 62304 benchmarks.
Growth Catalysts
- AI-driven topology optimization:Saudi Arabia's Riyadh hospital clusters deploy generative design algorithms to reduce material waste in titanium orthopedic constructs. Egyptian research institutions adopt similar protocols for maxillofacial surgical guides.
- SFDA medical device registration alignment:Harmonization with international safety benchmarks accelerates import clearance for biocompatible photopolymer platforms. Domestic distributors benefit from streamlined quality management system audits.
- Patient-specific implant procurement:Egypt's national pharmaceutical regulator validates reimbursement pathways for customized cranial plates. Private hospital networks in Jeddah expand surgical guide printing capacity.
Market Restraints
- Metal powder supply concentration:Titanium and cobalt-chrome feedstock for selective laser sintering concentrates among a limited set of certified European and East Asian suppliers. Egyptian orthopedic centers face extended lead times for load-bearing implant materials.
- Bioprinting technical limitation:Vascularization protocols for tissue-engineered scaffolds remain immature in both jurisdictions. Research institutions cannot yet fabricate clinically viable organ constructs at scale.
- Software validation friction:IEC 62304 medical device software lifecycle requirements impose documentation burdens on AI-integrated surgical planning tools. SFDA review cycles for algorithm-controlled printers extend market entry timelines.
Strategic Opportunities
- Upper Egypt hospital network penetration:Additive manufacturing service bureaus in Cairo and Alexandria lack distribution presence in Luxor and Aswan provinces. Mobile 3D printing units could capture trauma center demand for emergency splints and casts.
- Bioprinting-drug screening convergence:Saudi research universities integrate living cell suspension printing with pharmaceutical toxicity testing. This hybrid application opens procurement channels outside traditional medical device budgets.
- Point-of-care distributed production:Jeddah's private hospital clusters pilot in-house surgical guide printing to bypass import logistics. SFDA fast-track registration for hospital-based quality management systems enables this channel shift.
Industry Challenges
- Biofabrication technician scarcity:Egyptian universities graduate insufficient specialists trained in cell culture handling and bioprinter maintenance. Saudi institutions compete for the same limited talent pool.
- Multi-material printer capex intensity:Hospital procurement committees resist capital allocation for systems combining polymer extrusion with metal powder bed fusion. Financing structures for hybrid platforms remain underdeveloped.
- Post-processing certification bottlenecks:Heat treatment and surface finishing protocols for titanium implants require specialized equipment. SFDA inspection capacity for these subprocesses creates compliance backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia and Egypt Healthcare 3D Printing Market |
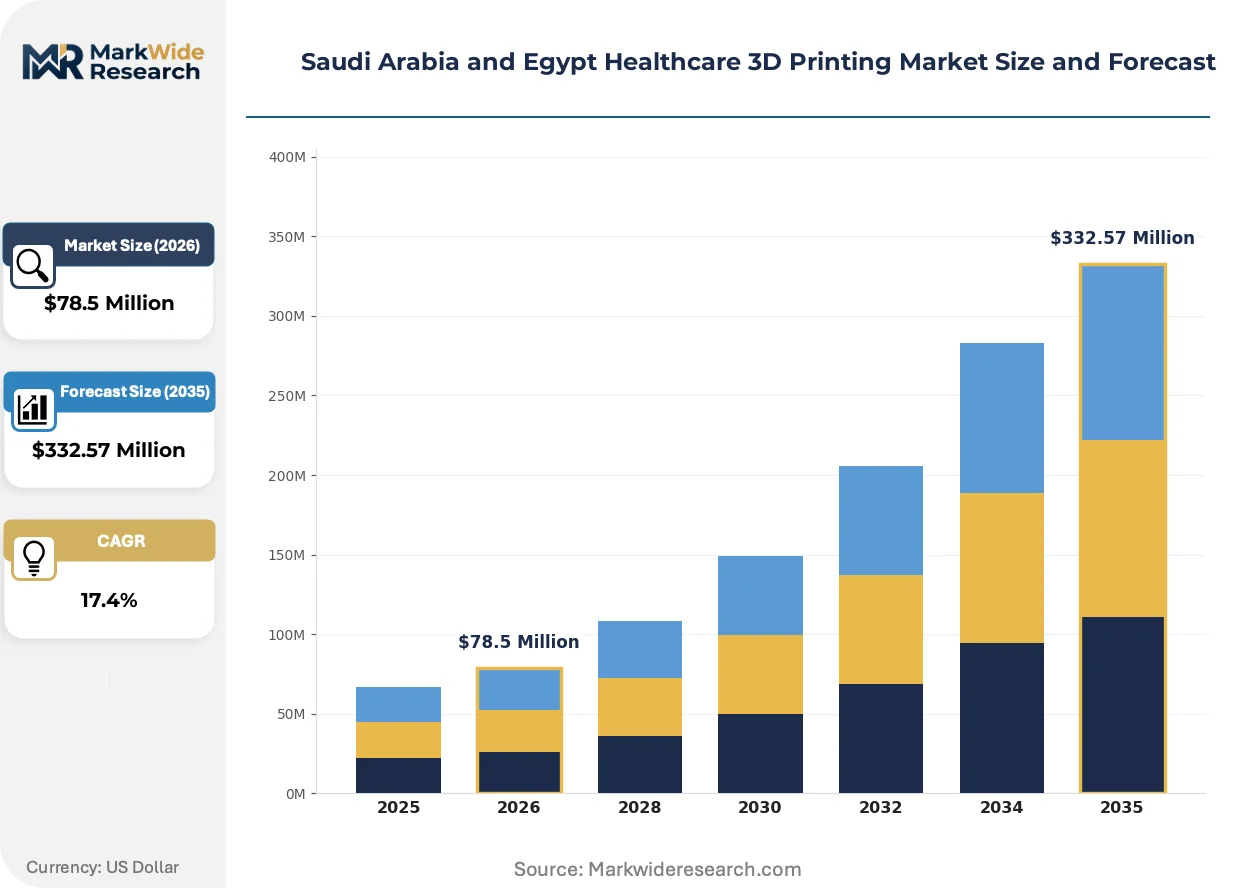
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $332.57 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Prosthetics, Bioprinting Materials, Anatomical Models Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing End User: Hospitals, Surgical Centers, Research Institutions, Educational Facilities Application: Orthopedics, Dentistry, Cardiovascular, Tissue Engineering |
| Companies Covered | Stratasys Ltd., 3D Systems, Inc., General Electric, Covestro AG, Organovo Holdings Inc., SLM Solutions, Envisiontec US LLC, Materialise NV, Cellink, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia and Egypt Healthcare 3D Printing Market Strategic Shifts & Innovations
Multi-material extrusion systems paired with real-time quality monitoring are collapsing the cost structure for patient-specific device production across Saudi and Egyptian hospital networks.
Continuous fiber-reinforced thermoplastic printing is rendering obsolete machined aluminum surgical instruments in Riyadh's orthopedic centers. Jeddah hospital clusters adopt these composite tools for sterilizable retractors and fixation plates. The technology compresses production cycles from weeks to hours while eliminating CNC machining outsourcing dependencies.
SFDA's phased implementation of software-as-a-medical-device guidelines tightens validation requirements for AI-integrated surgical planning platforms. Egyptian regulators mirror these standards through national pharmaceutical regulator directives. Medical device distributors in both countries now pre-validate algorithm updates to avoid registration suspension.
Surgeons in Cairo's university hospitals increasingly specify anatomical model fabrication as a preoperative planning prerequisite. This behavioral shift displaces traditional imaging-only review protocols. Saudi Arabia's Ministry of Health reimbursement committees are evaluating standardized payment codes for printed surgical guides to align procurement incentives with outcome metrics.
Saudi Arabia and Egypt Healthcare 3D Printing Market Segmentation
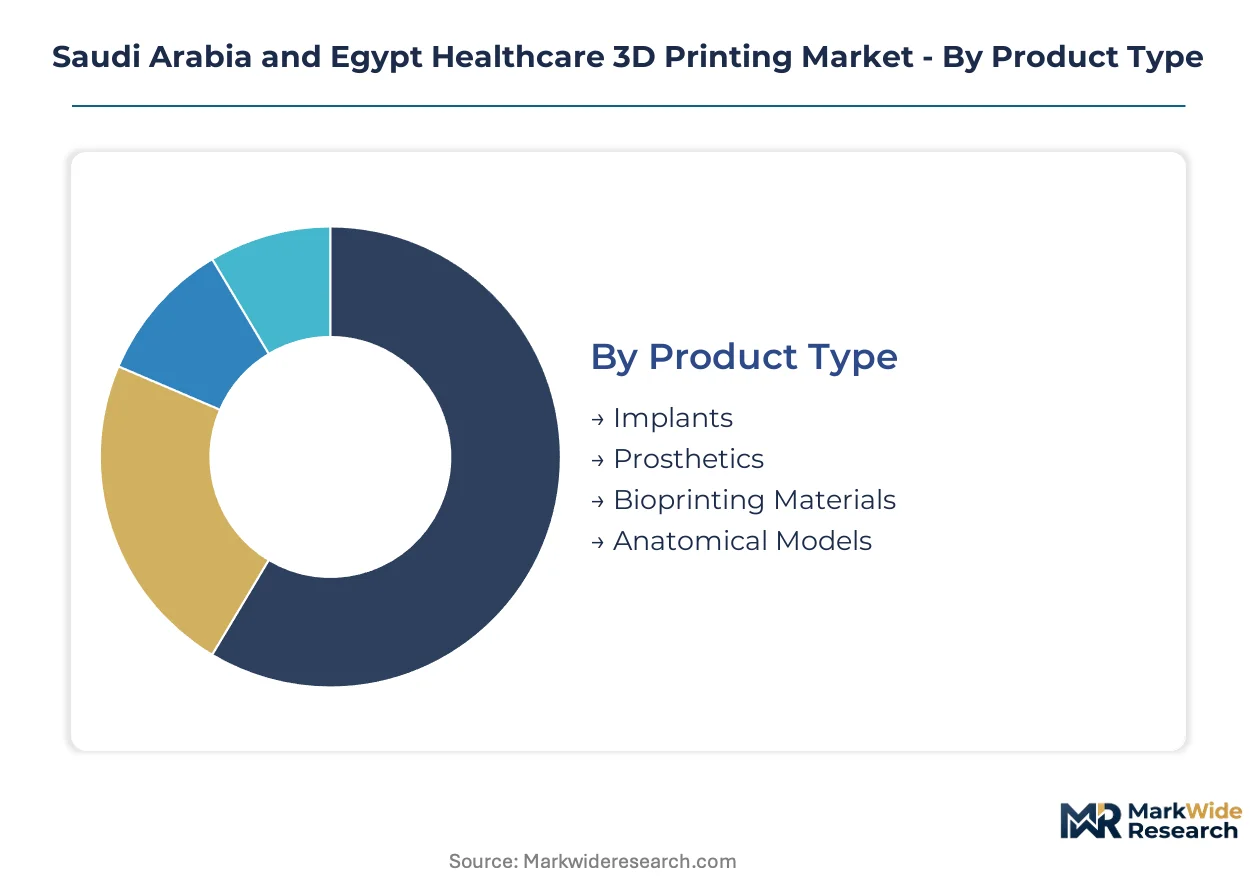
Segmentation in Saudi Arabia and Egypt Healthcare 3D Printing Market reveals distinct procurement patterns across product categories and end-use settings. Hospital procurement committees evaluate each segment through different technical validation frameworks and reimbursement pathways.
Product Type:
After-sales service intensity varies sharply across product categories, with bioprinting materials requiring specialized technician deployment and implants demanding regulatory compliance support.
- Implants:Titanium and cobalt-chrome constructs fabricated through selective laser sintering achieve load-bearing specifications for orthopedic and cranial applications. Saudi Arabia's Riyadh hospital clusters concentrate procurement for patient-specific spinal cages and hip cups, driven by SFDA reimbursement validation for customized devices.
- Bioprinting Materials:Living cell suspensions and bio-inks enable scaffold fabrication for tissue engineering protocols. Egyptian research institutions in Cairo and Alexandria drive demand, constrained by vascularization protocol immaturity that limits clinical translation.
- Prosthetics:Polymer-based limb and facial prostheses utilize fused deposition modeling for rapid customization.
- Anatomical Models:Preoperative planning replicas replicate patient-specific pathology from CT and MRI datasets.
By volume, Implants leads. By growth pace, Bioprinting Materials is ahead.
Technology:
Cost tier differentiation shapes hospital capital allocation, with entry-level extrusion systems dominating Egyptian public facilities and premium laser systems concentrating in Saudi private networks.
- Fused Deposition Modeling:Thermoplastic extrusion systems deploy acrylonitrile butadiene styrene and polylactic acid for surgical guides and anatomical models. Egyptian hospitals favor this technology for its lower capital threshold and simplified maintenance protocols.
- Selective Laser Sintering:Powder bed fusion of titanium and cobalt-chrome produces load-bearing orthopedic implants with isotropic mechanical properties. Saudi Arabia's Jeddah private hospital clusters invest in these systems to bypass import dependency for standardized implants.
- Stereolithography:Photopolymer vat polymerization achieves fine feature resolution for dental and maxillofacial applications.
- Digital Light Processing:Projector-based photopolymer curing accelerates batch production of surgical guides.
By installed base, Fused Deposition Modeling dominates. By expansion trajectory, Selective Laser Sintering is climbing the fastest.
End User:
Customer type determines procurement authority structures, with centralized Saudi Ministry of Health purchasing contrasting against fragmented Egyptian private hospital decision-making.
- Hospitals:Tertiary medical centers integrate 3D printing into surgical workflows for patient-specific device production. Riyadh's King Faisal Specialist Hospital and Cairo's Kasr Al Ainy Hospital anchor demand through dedicated additive manufacturing laboratories.
- Research Institutions:Universities and national research centers pursue bioprinting protocol development and pharmaceutical toxicity screening applications. King Abdullah University of Science and Technology and Egypt's National Research Centre drive material science innovation.
- Surgical Centers:Ambulatory facilities procure anatomical models for preoperative planning.
- Educational Facilities:Medical schools deploy printed models for anatomy instruction and surgical training.
By procurement volume, Hospitals lead. By technology advancement pace, Research Institutions is gaining share fastest.
Application:
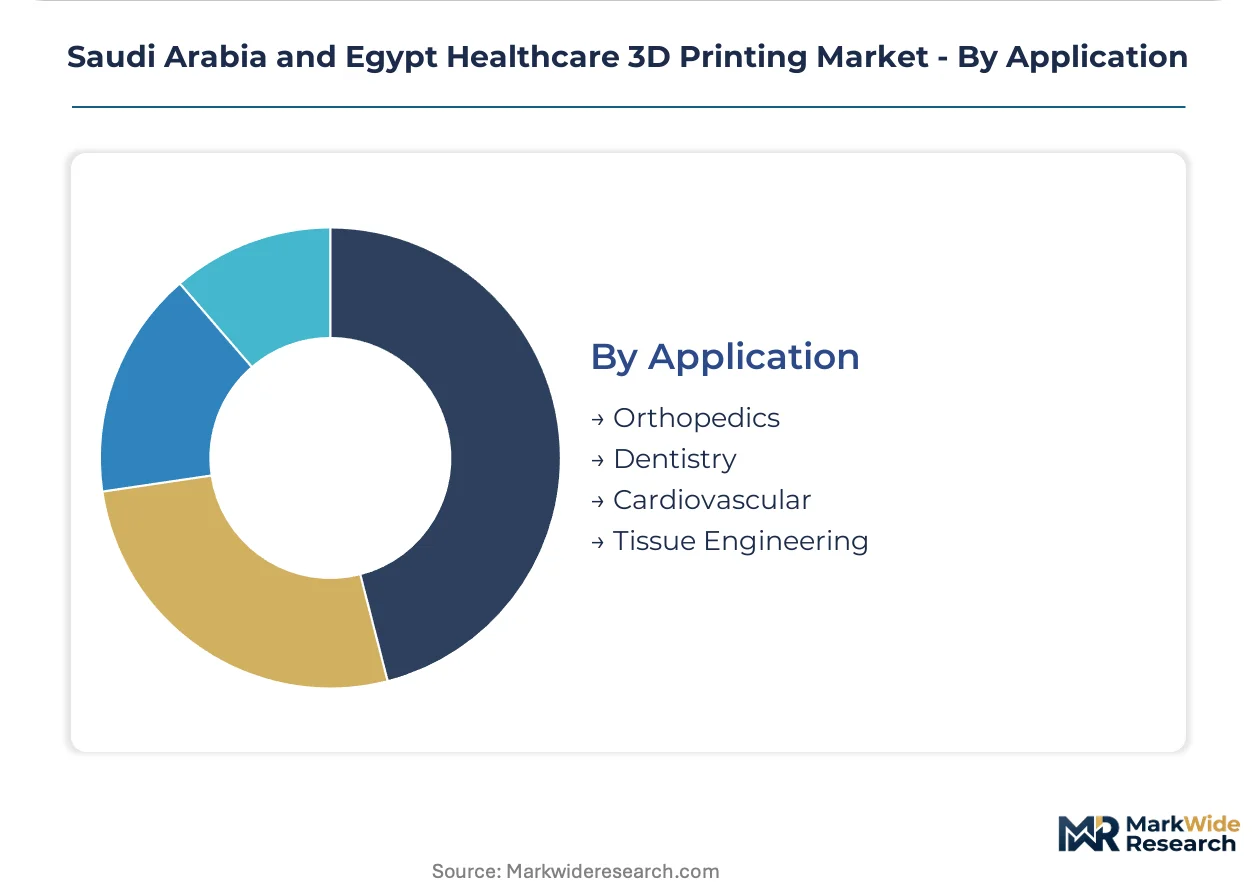
Application maturity correlates with regulatory clarity, with established orthopedic pathways contrasting against emergent cardiovascular protocols.
- Orthopedics:Patient-specific hip cups, spinal cages, and trauma plates represent the most mature reimbursement category. Saudi Arabia's SFDA has issued specific guidance documents for titanium implant registration, accelerating hospital adoption.
- Tissue Engineering:Scaffold fabrication for bone and cartilage regeneration occupies the research-commercialization boundary. Egyptian institutions concentrate on maxillofacial reconstruction applications, limited by vascularization challenges in larger constructs.
- Dentistry:Crowns, bridges, and surgical guides leverage photopolymer platforms for same-day production.
- Cardiovascular:Patient-specific valve models and vascular grafts remain preclinical in both jurisdictions.
By commercial maturity, Orthopedics leads. By protocol development pace, Tissue Engineering is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Belgian metal powder suppliers dominate feedstock flows into Saudi orthopedic centers, while Egyptian distributors channel photopolymer resins through Alexandria's port infrastructure for redistribution across North African hospital networks.
Saudi Arabia
Riyadh's King Faisal Specialist Hospital and Jeddah's private hospital clusters drive titanium implant demand through selective laser sintering procurement. SFDA enforces ISO 13485-aligned quality management audits for imported 3D printers and biocompatible materials. The Eastern Province's Dammam medical city anchors distributed manufacturing pilots for point-of-care surgical guide production.
Egypt
Cairo's Kasr Al Ainy Hospital and Alexandria's university medical centers concentrate anatomical model fabrication for preoperative planning workflows. The national pharmaceutical regulator validates reimbursement pathways for customized cranial plates and maxillofacial devices. Upper Egypt trauma centers in Luxor and Aswan remain underserved by additive manufacturing service bureaus based in the Nile Delta.
United Arab Emirates
Dubai's Dubai Health Authority and Abu Dhabi's Cleveland Clinic affiliate import patient-specific implant platforms for orthopedic and dental applications. MOHAP's medical device registration framework harmonizes with Saudi SFDA standards to accelerate cross-Gulf supply chain integration. The Dubai Science Park hosts regional distribution hubs for photopolymer and metal powder feedstock serving Saudi and Egyptian buyers.
Jordan
Amman's King Hussein Cancer Center deploys 3D-printed surgical guides for complex oncological resections. The Jordan Food and Drug Administration maintains medical device registration requirements that Egyptian manufacturers navigate for re-export positioning. Aqaba's special economic zone attracts logistics operators serving Red Sea medical supply corridors.
Turkey
Istanbul's medical device manufacturers export fused deposition modeling systems to Egyptian public hospitals seeking lower capital thresholds. The Turkish Medicines and Medical Devices Agency enforces CE marking alignment that facilitates regional trade. Ankara's METU research center collaborates with Saudi universities on bioprinting protocol development for tissue engineering applications.
Saudi Arabia and Egypt Healthcare 3D Printing Market Key Industry Players
On the supply side, the industry is bifurcated between integrated platform providers controlling hardware-software workflows and specialized material suppliers concentrating on certified feedstock production. Three strategic archetypes dominate: diversified industrial conglomerates with healthcare divisions, pure-play additive manufacturing specialists, and materials science firms extending into medical-grade polymers and metals. Competitive intensity centers on regulatory pre-certification of production workflows and exclusive distribution partnerships with hospital procurement committees.
Within the integrated platform tier, Stratasys Ltd. and 3D Systems, Inc. exemplify contrasting technology anchoring strategies, while Materialise NV occupies a position bridging software-controlled surgical planning with hardware deployment. These three entities represent the dominant competitive anchors shaping procurement patterns across Saudi and Egyptian hospital networks.
| Leading Market Players |
|---|
| Stratasys Ltd. |
| 3D Systems, Inc. |
| General Electric |
| Covestro AG |
| Organovo Holdings Inc. |
| SLM Solutions |
| Envisiontec US LLC |
| Materialise NV |
| Cellink |
| Others |
Cost & Logistics Intelligence
German and Belgian metal powder suppliers anchor upstream feedstock flows for Saudi orthopedic centers, concentrating margin capture in certified titanium and cobalt-chrome supply tiers while Egyptian distributors compete on photopolymer resin logistics through Alexandria's port infrastructure.
Pricing Analysis
Prior-generation fused deposition modeling systems trade at entry-level capital thresholds favored by Egyptian public hospitals, current-generation selective laser sintering platforms command premium positioning in Saudi private networks, and next-generation multi-material hybrid systems remain pre-commercial with project-based pilot pricing. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Cost compression in standard-tier photopolymer platforms is intensifying because Turkish manufacturers export aggressively into Egyptian procurement channels. Egyptian public hospital committees exhibit highest price sensitivity; Saudi Ministry of Health centralized purchasing demonstrates lowest sensitivity due to outcome-based reimbursement validation.
Supply Chain Analysis
Contract manufacturing for biocompatible photopolymer platforms concentrates with German specialty chemical houses and Belgian precision polymer compounders, while metal powder bed fusion feedstock sources from Austrian and Swedish additive manufacturing material specialists. Raw material dependencies center on pharmaceutical-grade titanium sponge, cobalt-chrome master alloy, and UV-curable acrylate resins. Single-source vulnerability runs through certified European metal powder suppliers subject to SFDA import inspection backlogs. Distribution runs through Dubai Science Park regional hubs serving Red Sea medical supply corridors into Jeddah and Aqaba logistics nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Upper Egypt trauma networks and Saudi point-of-care pilot programs creates niche entry positions for specialized service bureaus and hybrid platform providers.
For Market Incumbents: Pre-empt Turkish fused deposition modeling exporters from consolidating Egyptian public hospital procurement by securing exclusive distribution partnerships with Cairo-based biomedical engineering clusters. Accelerate ISO 13485 certification investments for software-controlled surgical planning workflows before SFDA tightens IEC 62304 validation requirements. Defend against emerging pure-play bioprinting specialists by anchoring hospital relationships through integrated hardware-software maintenance contracts. For New Entrants and Emerging Players: Build out mobile additive manufacturing service capacity targeting Luxor and Aswan trauma centers currently underserved by Nile Delta-based bureaus. Penetrate the bioprinting-drug screening convergence segment at Saudi research universities where procurement channels sit outside traditional medical device budgets. Deploy direct clinical liaison teams to bypass established distributor relationships in Jeddah's private hospital clusters. For Investors and Strategic Acquirers: Capital is best deployed toward software-to-hardware integration specialists controlling surgical planning and guide production workflows, given long-term viability hinges on regulatory pre-certification of algorithm-controlled production systems. Monitor SFDA fast-track registration announcements for hospital-based quality management systems as inflection signal for point-of-care distributed production channel shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures procurement committee access for patient-specific implant platforms at Riyadh's King Faisal Specialist Hospital. |
| CE Marking Pathway | Facilitates cross-Gulf trade harmonization with MOHAP standards for Dubai Health Authority import clearance. |
| Software Companion Development | Enables IEC 62304 compliance for AI-integrated surgical planning tools under SFDA review cycles. |
| Reimbursement Strategy | Aligns procurement incentives with Saudi Ministry of Health outcome metrics for customized cranial plates. |
| Backward Integration into Metal Powder | Reduces lead time exposure for Egyptian orthopedic centers dependent on European certified suppliers. |
Research Approach
The analysis maps implants, bioprinting materials, prosthetics, and anatomical models, each validated through biomedical engineers, hospital purchasing committees, GPO contracts managers, and SFDA regulatory affairs specialists. Primary interviews with clinicians and procurement directors across Riyadh, Jeddah, Cairo, and Alexandria combined with secondary validation against hospital procurement databases, GPO contracts, CMS Medicare comparable data, and SFDA medical device registration filings. Bottom-up segmentation sizing and top-down market triangulation cross-validated volume and value estimates.
Fixed assumptions across the projection horizon include sustained SFDA alignment with ISO 13485 and IEC 62304 frameworks, stable reimbursement pathways for patient-specific implants, and continued concentration of metal powder supply among certified European suppliers. Segmentation dimensions modeled encompass product type, technology platform, end-user setting, and application maturity. CAGRs derived from installed base expansion rates, replacement cycles, and procedure volume growth trajectories. Industry-specific inputs include orthopedic implant procedure forecasts and research institution bioprinting capital expenditure patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pure-play bioprinting specialists or Turkish low-cost platform exporters would shift outcomes. Quarterly review of SFDA registration queue lengths, metal powder import lead times, and hospital-based quality management system pilot announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
Global 3D Printed Electronics Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
3D Printing Market
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
North America Additive Manufacturing with Metal Powders Market
3D Printing Technology
Binder Jet Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
3D Printing Materials and Equipment Market
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
Hybrid Additive Manufacturing Machine Market
3D Printing Technology
Desktop 3D Printing Market
3D Printing Technology
3D Printing Service Bureaus Market
3D Printing Technology
3D Printing Software Market