
 3D Printing in Aviation Market | 2026-2036
3D Printing in Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing in Aviation Market Insights
Buyer concentration among defense contractors and tier-one airframers is shifting as smaller maintenance providers and aircraft modification firms gain certified additive capabilities. Boeing sustains extensive in-house printing operations for Dreamliner ducting and brackets across multiple US facilities. Lockheed Martin leverages selective laser sintering for F-35 component prototyping, reducing lead times against traditional forging. EOS GmbH anchors European supply of direct metal laser sintering systems to aviation-qualified service bureaus in Germany and Scandinavia.
3D printing in aviation encompasses layer-by-layer fabrication of flight-worthy components from metals, thermoplastics, photopolymers, and composites using precision-directed energy or extrusion processes, achieving tolerances as tight as 0.1 mm for structural airworthiness. Its primary purpose is producing geometrically complex, low-volume parts without dedicated tooling, thereby reducing material waste and accelerating design iteration cycles for prototype parts and flight-certified structural components. Metal powder applications dominate current revenue pools due to titanium and nickel superalloy demand in turbine blades and landing gear brackets, while photopolymer resin segments expand fastest in cabin interior fixtures where flame-retardancy certification cycles prove shorter. Electron beam melting technology occupies specialized margins for defense-grade titanium structures requiring vacuum-purity microstructures unobtainable through laser-based methods.
FAA airworthiness directives and EASA certification memoranda jointly govern material qualification pathways for printed aviation parts, with both agencies expanding approved feedstock lists under sustained industry petition pressure. The US EPA and OSHA maintain workplace exposure limits for metal powder handling that shape facility capital requirements and operational geography decisions for service providers. Stakeholders must monitor evolving dual-release agreements between FAA and EASA for streamlined cross-Atlantic part approval, as harmonization gaps currently fragment addressable market scope for multi-certification suppliers.
Market Dynamics
Defense procurement timelines for titanium and nickel superalloy flight hardware are compressing as FAA and EASA parallel certification pathways mature, pulling additive manufacturing from prototyping into sustained production contracts for engine brackets and structural ducting.
Growth Catalysts
- Dual-Release Harmonization:FAA-EASA streamlined approval protocols reduce recertification costs for multi-jurisdiction suppliers, accelerating cross-Atlantic parts commerce.
- Electron Beam Melting:Vacuum-purity titanium microstructures from EBM systems meet defense-grade structural requirements unobtainable through laser-based methods, expanding addressable applications.
- Scandinavian Service Bureau Cluster:EOS GmbH-equipped facilities in Sweden and Norway aggregate aviation-qualified metal printing capacity, reducing lead times for European airframers.
Market Restraints
- Titanium Powder Volatility:Sponge and alloy powder prices fluctuate with aerospace-grade titanium sponge supply from Ukrainian and Russian feedstock disruption.
- Single-Source Equipment Risk:Direct metal laser sintering system production concentrates in southern Germany, creating geographic vulnerability for service bureau capacity expansion.
- Microstructural Anisotropy:Layer-wise deposition introduces directional mechanical property variation that limits load-bearing applications in primary wing structures.
Strategic Opportunities
- India MRO Penetration:Bangalore and Hyderabad maintenance clusters lack certified additive repair capabilities for turbine blade restoration, creating first-mover openings.
- Photopolymer Cabin Interiors:Flame-retardant resin certification cycles run shorter than metal pathways, enabling rapid qualification of seat frames and galley components.
- AI-Driven Topology Optimization:Convergence of generative design software with multi-axis printing enables lattice structures that reduce bracket mass while maintaining FAA-certified safety margins.
Industry Challenges
- Non-Destructive Testing Shortage:Computed tomography technicians qualified for porosity detection in printed titanium remain scarce relative to expanding production volumes.
- Legacy ERP Integration:Additive work order management systems require custom middleware to synchronize with Boeing and Airbus incumbent manufacturing execution platforms.
- IP Fragmentation:Patent thickets around support structure generation algorithms complicate licensing for independent service bureaus entering flight-critical part production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing in Aviation Market |
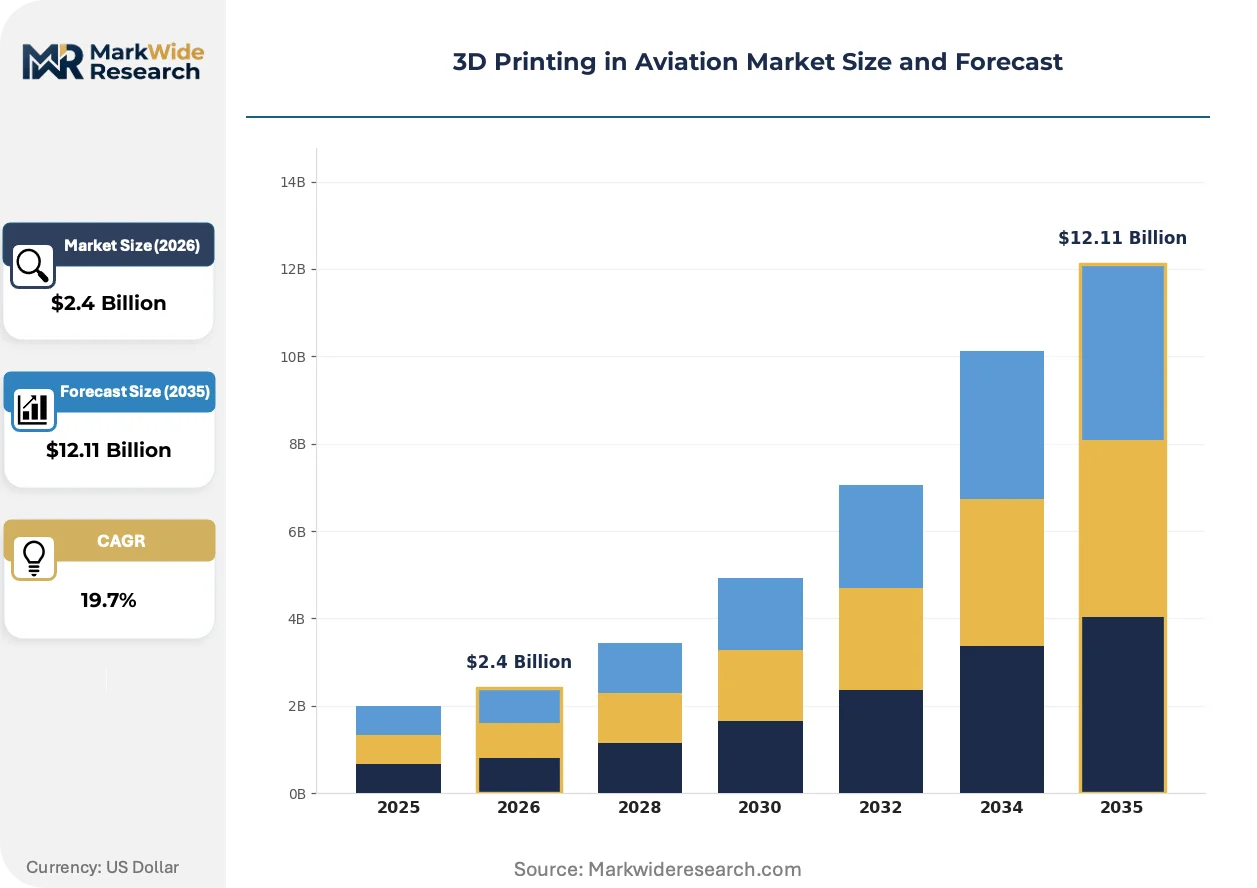
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $12.11 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Powder, Thermoplastic Filament, Photopolymer Resin, Composite Materials Technology: Fused Deposition Modeling, Selective Laser Sintering, Direct Metal Laser Sintering, Electron Beam Melting Application: Prototype Parts, Structural Components, Interior Fixtures, Tooling Equipment End User: Aircraft Manufacturers, Maintenance Providers, Defense Contractors, Aircraft Modification Firms |
| Companies Covered | Stratasys Ltd., 3D Systems Corporation, EOS GmbH, Norsk Titanium AS, Materialise NV, Aerojet Rocketdyne Holdings, Airbus, Boeing, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing in Aviation Market Trends and Innovations
Aviation additive manufacturing is pivoting from geometric capability demonstration toward production economics, with process control automation and regulatory data packages becoming the decisive competitive differentiators.
Cold spray deposition is electrifying repair applications for magnesium helicopter gearboxes and aluminum airframe sections, with US Army Aviation and Missile Command adopting mobile repair cells for forward operating base sustainment. Field units now restore worn bearing seats without removing components from aircraft, compressing turnaround from weeks to hours while bypassing traditional supply chain dependencies on forged replacement spares.
EASA's expanded Certification Memorandum for polymer additive manufacturing streamlines flame-retardancy testing protocols for cabin interior components, reducing qualification timelines from thirty-six to eighteen months for qualifying photopolymer resins. German seat manufacturers and French galley suppliers are accelerating material submissions under this pathway, shifting interior procurement toward printed thermoplastic alternatives ahead of FAA harmonization.
Airline engineering departments now contract directly with certified service bureaus for non-critical bracket and ducting production, disintermediating traditional tier-two suppliers who previously aggregated forging and machining capacity. This pattern concentrates most visibly among US low-cost carriers operating narrowbody fleets, where maintenance organizations in Dallas and Phoenix establish captive additive cells for rotable component fabrication.
3D Printing in Aviation Market Segmentation
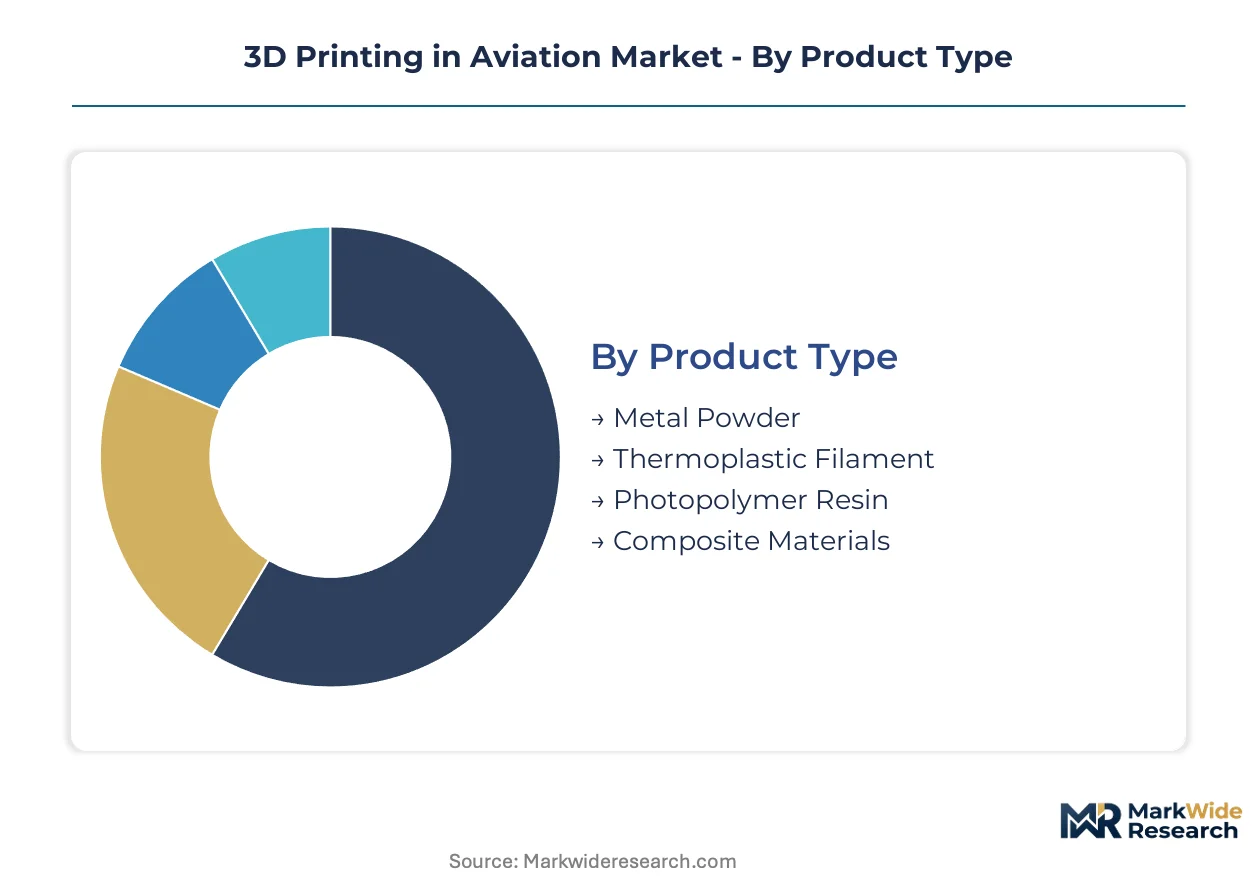
Segmentation in aviation additive manufacturing reveals how material certifications, technology maturation, and procurement authority are redistributing across the value chain. Upgrade cycles for legacy airframes and next-generation military programs are forcing distinct capability investments by segment.
Product Type:
Replacement of legacy forged and machined components with printed alternatives follows divergent material qualification timelines, with metal powders commanding longer FAA approval cycles than polymer alternatives.
- Metal Powder:Titanium and nickel superalloy powders dominate turbine blade and landing gear bracket production. Boeing and Lockheed Martin procurement in the United States absorbs the majority of aerospace-grade sponge-derived feedstock for flight-critical structural applications.
- Thermoplastic Filament:High-performance polymers such as PEKK and PEEK enable ducting and non-structural brackets with shorter EASA certification pathways. German seat manufacturers leverage this feedstock for cabin interior retrofits where flame-retardancy testing cycles compress lead times against metal alternatives.
- Photopolymer Resin:Flame-retardant formulations from French galley suppliers and Scandinavian service bureaus target non-structural interior components with eighteen-month EASA qualification timelines.
- Composite Materials:Continuous fiber-reinforced printing from NASA-funded research clusters enables hybrid structures combining polymer matrices with carbon fiber layup simulation.
Metal Powder sits at the top of the volume ranking, with Photopolymer Resin climbing the fastest.
Technology:
Capital intensity and vacuum-environment requirements create tiered entry barriers that stratify supplier capabilities between prototyping shops and production-qualified facilities.
- Fused Deposition Modeling:Extrusion-based polymer printing serves non-critical prototyping and tooling fixtures. US low-cost carrier maintenance cells in Dallas deploy FDM for rotable ducting fabrication where dimensional tolerances permit 0.2 mm deviation.
- Selective Laser Sintering:Polymer powder bed fusion enables complex geometries in cabin interior components without support structures. Lockheed Martin F-35 prototyping operations in the United States leverage SLS for rapid design iteration on bracket geometries.
- Direct Metal Laser Sintering:Laser-based metal powder fusion anchors production of titanium engine brackets and nickel superalloy turbine hardware. EOS GmbH-equipped service bureaus in Germany and Sweden concentrate European aviation-qualified capacity for DMLS production contracts.
- Electron Beam Melting:Vacuum-chamber titanium processing from US Army Aviation repair cells delivers defense-grade microstructures for forward-operating-base sustainment of helicopter gearboxes.
Direct Metal Laser Sintering commands the dominant installed base, while Electron Beam Melting gains share fastest in defense-grade applications.
Application:
Airworthiness certification requirements stratify applications by structural load-bearing responsibility, with non-critical segments offering faster entry for new suppliers.
- Prototype Parts:Design validation components accelerate iteration cycles before production tooling commitment. NASA-funded research clusters in the United States print titanium topology-optimized brackets for wind tunnel testing prior to flight qualification.
- Structural Components:Load-bearing brackets and ducting require FAA airworthiness directives and full material traceability. Boeing Dreamliner production facilities across multiple US sites sustain captive printing operations for flight-certified titanium hardware.
- Interior Fixtures:Seat frames, galley components, and trim panels face shorter flame-retardancy certification cycles. EASA's streamlined polymer memorandum enables German and French suppliers to accelerate photopolymer submissions ahead of FAA harmonization.
- Tooling Equipment:Drill guides, assembly fixtures, and masking tools bypass flight certification entirely. Maintenance providers in Phoenix establish captive additive cells for narrowbody fleet support equipment.
Structural Components absorb the largest qualification investment, with Interior Fixtures expanding most quickly through shortened certification pathways.
End User:
Procurement authority concentration varies by contract scale, with defense programs accelerating additive adoption through compressed military qualification timelines.
- Aircraft Manufacturers:Boeing sustains extensive in-house metal printing for Dreamliner production, while Airbus aggregates European supply through qualified service bureau networks in Germany and Scandinavia.
- Maintenance Providers:US low-cost carrier engineering departments in Dallas and Phoenix contract directly with certified bureaus for rotable bracket fabrication, disintermediating traditional tier-two forging suppliers.
- Defense Contractors:Lockheed Martin selective laser sintering operations for F-35 prototyping reduce lead times against traditional forging, while US Army Aviation deploys mobile cold spray cells for forward-base helicopter repair.
- Aircraft Modification Firms:Supplemental type certificate holders leverage photopolymer printing for cabin reconfiguration projects where flame-retardant resin qualification cycles enable rapid STC approval.
Defense Contractors drive the steepest capacity expansion, with Maintenance Providers gaining procurement autonomy fastest through direct service bureau relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation additive manufacturing talent clusters concentrate in aerospace engineering corridors where defense procurement and commercial airframe production overlap. FAA and EASA certification expertise anchors workforce development in specific metropolitan zones.
United States
Boeing's Dreamliner production network and Lockheed Martin's F-35 program drive titanium printing demand across Washington, California, and Texas facilities. FAA airworthiness directives for flight-critical metal parts shape qualification protocols that California and Washington-based engineering teams specialize in navigating. NASA-funded research clusters in Alabama and Ohio advance topology-optimized bracket printing for next-generation aircraft structures.
Germany
EOS GmbH anchors European direct metal laser sintering system supply from its Krailling headquarters near Munich. EASA certification memoranda for polymer additive manufacturing streamline flame-retardancy testing that Bavarian seat manufacturers exploit for cabin interior retrofits. The Eindhoven-to-Munich corridor aggregates aviation-qualified service bureau capacity for Airbus supply chain integration.
Sweden
Scandinavian aerospace suppliers leverage EOS-equipped facilities in Gothenburg and Linköping for reduced lead times on European airframer contracts. EASA's streamlined approval pathways enable Swedish bureaus to compress polymer qualification timelines against German competitors. The Nordic cluster specializes in nickel superalloy turbine hardware for Saab and Volvo Aero derivative programs.
United Kingdom
Rolls-Royce's Derby engineering center advances electron beam melting for defense-grade titanium microstructures in turbine applications. The UK Civil Aviation Authority aligns with EASA harmonization efforts for dual-release part approval that BAE Systems suppliers in Lancashire exploit. Bristol and Farnborough clusters concentrate cold spray repair expertise for helicopter gearbox sustainment contracts.
Japan
METI-funded additive manufacturing initiatives support Mitsubishi Heavy Industries and Kawasaki Heavy Industries in qualifying titanium structural brackets for regional jet programs. Japanese precision equipment manufacturers supply multi-axis deposition systems that aerospace subcontractors in Aichi Prefecture adopt for prototyping workflows. The Nagoya aerospace cluster integrates printed tooling fixtures into existing composite wing production lines.
3D Printing in Aviation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment supply, material production, and certified part fabrication. Tier-one airframers sustain captive printing operations while outsourcing non-critical components to qualified service bureaus. Three archetypes dominate: system OEMs anchoring technology platforms, metals specialists controlling titanium powder supply chains, and aviation-qualified bureaus holding EASA-FAA dual certifications. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as qualification timelines compress.
Among system OEMs, Stratasys Ltd. and 3D Systems Corporation exemplify the diversified equipment tier spanning polymer and metal platforms. EOS GmbH occupies a specialized position in direct metal laser sintering for aviation-qualified production. Norsk Titanium AS represents the metals-integrated archetype, bridging plasma deposition technology with aerospace-grade titanium supply.
| Leading Market Players |
|---|
| Stratasys Ltd. |
| 3D Systems Corporation |
| EOS GmbH |
| Norsk Titanium AS |
| Materialise NV |
| Aerojet Rocketdyne Holdings |
| Airbus |
| Boeing |
| Lockheed Martin |
| Others |
Pricing and Supply Chain Analysis
Defense procurement compression for titanium flight hardware is forcing service bureaus to absorb powder price volatility while maintaining fixed contract rates, squeezing margin structures across European and North American qualified suppliers. This demand-side pressure concentrates pricing power with EOS GmbH and Stratasys Ltd. as equipment availability gates capacity expansion.
Pricing Analysis
Capacity additions in Germany and Sweden are reshaping price floors for direct metal laser sintering services as aviation-qualified bureaus compete for Airbus supply chain slots. Three-tier pricing structure across flight-critical, flight-qualified, and prototyping tiers separates FAA-certified titanium brackets from EASA-pending polymers and non-certified tooling. Cost compression in flight-qualified metal segments is intensifying because titanium sponge supply disruptions from Eastern European feedstock sources inflate raw material costs. Maintenance providers in Dallas and Phoenix exhibit highest price sensitivity, while defense contractors at Lockheed Martin sustain lowest sensitivity due to mission-critical procurement mandates.
Supply Chain Analysis
EASA and FAA dual-certification requirements gate entry for titanium powder suppliers and service bureau equipment operators, concentrating qualified capacity in Germany, Sweden, and the United States. Aerospace-grade titanium sponge draws from Ukrainian and Russian feedstock sources, while nickel superalloy powders rest on specialty chemical supply from Germany and the United States. Single-source vulnerability concentrates in southern Germany where EOS GmbH produces direct metal laser sintering systems. Distribution runs through qualified service bureau networks rather than direct OEM supply, with Airbus aggregating European capacity and Boeing sustaining captive North American operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EASA's streamlined eighteen-month polymer certification pathway is accelerating procurement shifts toward photopolymer cabin interiors ahead of FAA harmonization.
For Market Incumbents: Hedge titanium powder exposure through backward integration into sponge supply or long-term offtake agreements with alternative feedstock sources. Incumbents must defend against cold spray repair disruption in helicopter sustainment by certifying electron beam melting capacity for defense-grade microstructures. Priority investment centers on AI-driven topology optimization software to maintain bracket mass-reduction advantages against generative design entrants.
For New Entrants and Emerging Players: Cold spray deposition technology offers a technology-first wedge into US Army Aviation forward-base repair contracts where mobile cells bypass traditional supply chain dependencies. Photopolymer cabin interiors in German and French galley retrofits present the most penetrable segment with shortened EASA qualification timelines. Go-to-market execution should target direct airline engineering department contracts in Dallas and Phoenix maintenance clusters, disintermediating tier-two forging suppliers.
For Investors and Strategic Acquirers: Asymmetric upside sits with aviation-qualified service bureaus holding dual EASA-FAA certifications for flight-critical metal parts, as qualification timelines compress and buyer concentration shifts toward direct procurement. Long-term viability over the next decade hinges on sustained defense procurement and commercial airframe production rates. Watch for FAA-EASA harmonization completion as the inflection indicator unlocking cross-Atlantic parts commerce scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | EASA-FAA qualified capacity captures Airbus and Boeing direct procurement shifts. |
| Titanium Powder Supply Agreement | Long-term sponge offtake hedges against Ukrainian and Russian feedstock disruption. |
| Cold Spray Repair Deployment | Mobile cells for US Army Aviation contracts bypass traditional forging lead times. |
| AI Topology Optimization Licensing | Generative design software enables lattice structures meeting FAA safety margins. |
| Photopolymer Resin Qualification | EASA's streamlined pathway accelerates cabin interior procurement ahead of FAA. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with additive manufacturing directors at tier-one airframers, certification engineers at EASA and FAA, service bureau operations heads, titanium powder procurement leads, and airline engineering managers with secondary validation against SEC filings from Stratasys Ltd. and 3D Systems Corporation, EASA certification memoranda, FAA airworthiness directives, and aerospace trade customs data. Bottom-up service bureau capacity estimates and top-down airframer procurement forecasts were triangulated for convergence.
Historical reference periods anchored the projection horizon through analysis of qualification timeline compression and defense procurement acceleration. Segmentation modeling spanned material type, technology platform, application airworthiness tier, and end-user procurement authority across the forecast period. CAGRs derived from fitted growth curves incorporating equipment installation rates, certification approval velocities, and titanium powder price elasticity. Industry-specific inputs included EASA-FAA harmonization progress indicators and NASA-funded research cluster output trajectories.
The model holds under sustained defense procurement and stable dual-certification harmonization progress; deviation in titanium sponge supply disruption severity or FAA-EASA approval divergence would shift capacity expansion geography and pricing power distribution. Forecasts incorporate assumptions about qualification timeline compression and cold spray repair adoption rates. A model refresh is warranted upon material change in EASA-FAA dual-release implementation or US Army Aviation cold spray deployment scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Global 4D Printing in Healthcare Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
3D Printing Enabled Augmented Manufacturing Market
3D Printing Technology
Digital 3D Printing Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
Metal 3D Printing Service Market
3D Printing Technology
Hybrid Additive Manufacturing Machine Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
PEEK Filament Market
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
Latin America Industrial 3D Printing Market