
 Powder Bonding 3D Printing Construction Market | 2026-2036
Powder Bonding 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Powder Bonding 3D Printing Construction Market Analysis
Binder jetting integration with conventional concrete batching is fragmenting traditional construction workflows into discrete digital-manufacturing stages. COBOD International leverages its gantry-based systems to dominate large-format residential printing in Northern Europe. Apis Cor sustains mobile-robotic deployment models that reduce site logistics for single-family homes. ICON anchors defense-sector contracts through its proprietary Lavacrete material formulations and rapid-shelter protocols.
Powder bonding 3D printing construction employs granular material beds fused through selective laser sintering, binder jetting, or comparable additive processes to produce structural elements with compressive strengths exceeding conventional masonry units. Layer deposition rates of 10–50 mm per hour and particle size distributions of 10–150 microns enable geometric complexity impossible with cast-in-place methods. Metal powders command premium positioning in load-bearing connection hardware where fatigue resistance justifies unit costs. Binder jetting of geopolymer composites represents the fastest-expanding technology segment as contractors seek Portland-cement alternatives with lower embodied carbon. Infrastructure applications remain nascent but attract disproportionate R&D allocation due to longer procurement cycles and higher performance thresholds.
OSHA's silica-exposure standards for powder handling and the EU Construction Products Regulation's CE marking requirements for novel building materials constrain market entry for uncertified suppliers. Dubai Municipality's 3D printing construction codes and the UAE's mandatory building-material registrations under MOHAP accelerate compliance investments among equipment vendors. Stakeholders must monitor evolving national building-code adoptions that determine whether printed structural elements qualify for insurance-backed mortgages.
Market Dynamics
UAE government mandates under Dubai's 3D Printing Strategy are forcing equipment vendors to restructure certification pipelines ahead of mortgage-qualification deadlines for printed structural elements.
Growth Catalysts
- Binder Jetting Convergence:Geopolymer composite formulations are displacing Portland cement in Northern European residential foundations. Contractors achieve embodied carbon reductions without sacrificing compressive performance.
- Defense Procurement Protocols:Rapid-shelter specifications for military contingency operations are standardizing Lavacrete-compatible equipment requirements. Deployment timelines compress from months to days.
- EU Construction Products Regulation:CE marking pathways for novel additive materials are clarifying market entry criteria. Certified suppliers gain preferential access to public infrastructure tenders.
Market Restraints
- Silica Exposure Compliance:OSHA's permissible exposure limits for respirable crystalline silica impose capital-intensive ventilation and PPE protocols on powder-handling operations.
- Metal Powder Supply Concentration:Specialty alloy feedstock production clusters in Germany and China expose equipment vendors to geopolitical disruption and freight cost volatility.
- Layer Deposition Physics:Current 10–50 mm per hour build rates constrain economically viable project scales below mid-rise commercial thresholds.
Strategic Opportunities
- MOHAP Registration Pathways:UAE's mandatory building-material registry creates first-mover advantages for vendors completing accelerated durability testing protocols.
- Load-Bearing Hardware Applications:Metal powder sintering for fatigue-resistant connection joints addresses a specification gap in seismic-zone construction codes.
- Digital Manufacturing Integration:Convergence of binder jetting with conventional concrete batching systems enables hybrid production workflows at existing precast plants.
Industry Challenges
- Geometric Complexity Talent Gap:Structural engineers proficient in topology optimization for additive manufacturing remain scarce relative to project pipeline expansion.
- Insurance-Backed Mortgage Qualification:Printed element certification timelines lag equipment deployment schedules, freezing residential sales until underwriter acceptance protocols stabilize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powder Bonding 3D Printing Construction Market |
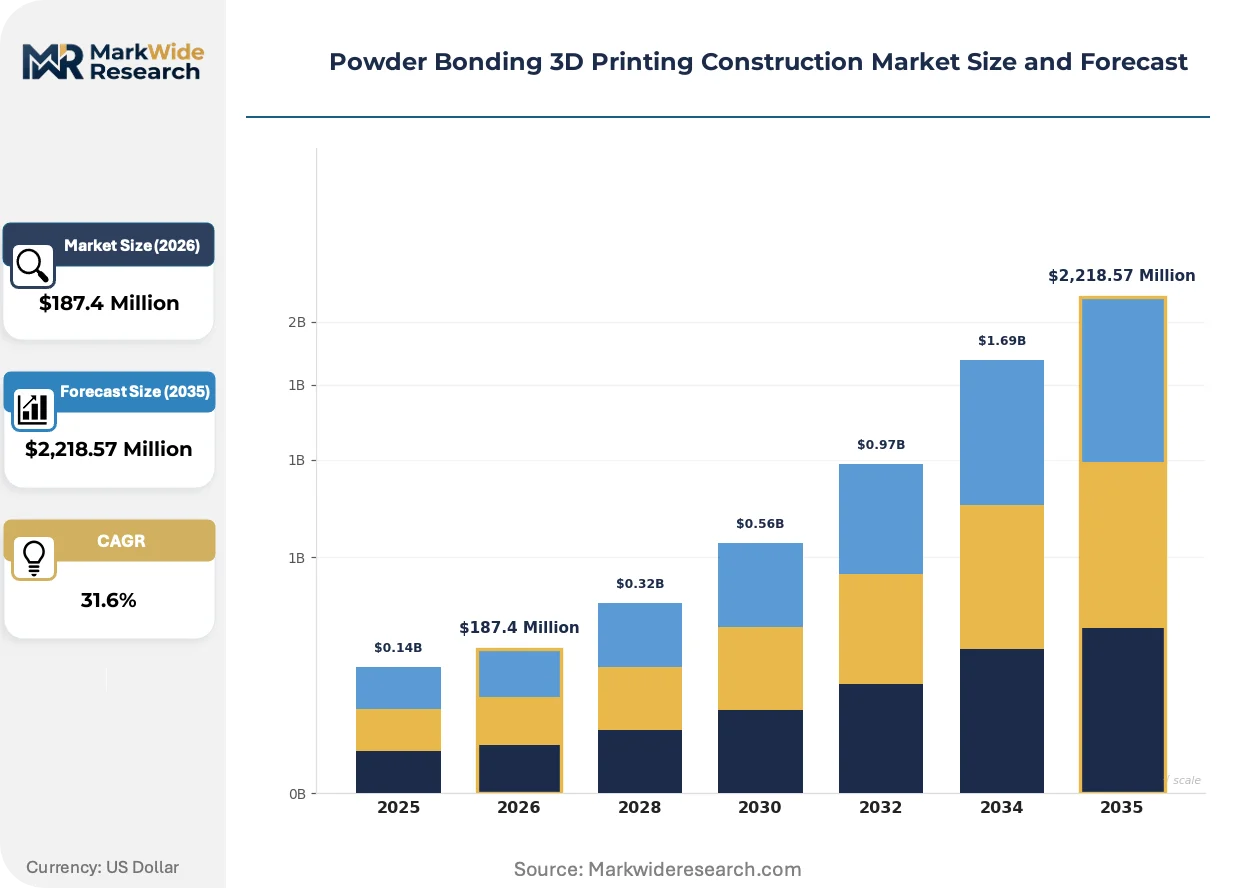
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,218.57 Million |
| CAGR (2026 – 2036) | 31.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Metal Powders, Plastic Powders, Ceramic Powders, Composite Powders Printing Technology: SLS, SLA, DLP, Binder Jetting Application Sector: Residential Buildings, Commercial Structures, Industrial Facilities, Infrastructure Projects End User: Construction Firms, Architectural Agencies, Manufacturing Companies, Research Institutions |
| Companies Covered | COBOD International, Apis Cor, ICON, CyBe Construction, XtreeE, Winsun, Constructions-3D, Contour Crafting, Sika, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powder Bonding 3D Printing Construction Market Emerging Trajectories
Construction workflows fragment into discrete digital-manufacturing stages as powder bonding systems integrate with conventional material supply chains. Three developments dominate vendor roadmaps.
Geopolymer binder jetting is digitizing concrete production by replacing wet-mix casting with dry-powder deposition and selective activation. Northern European contractors adopt these systems for foundation elements to meet carbon-reduction mandates. The technology compresses curing cycles from weeks to hours while enabling internal lattice geometries impossible with formwork.
REACH restrictions on hazardous substance emissions are tightening feedstock composition requirements for construction-grade powders. ECHA's evolving substance evaluation criteria force reformulation of legacy polymer binders. Vendors with in-house materials science capabilities are internalizing compliance testing to preserve product launch velocity.
Affordable housing agencies in the Middle East are consolidating procurement around performance-based specifications rather than prescriptive material standards. Dubai Municipality's 3D printing construction codes enable this shift by defining structural outcomes independent of manufacturing method. Single-source contracting for printed structural components displaces fragmented subcontractor networks in UAE residential developments.
Powder Bonding 3D Printing Construction Market Segmentation
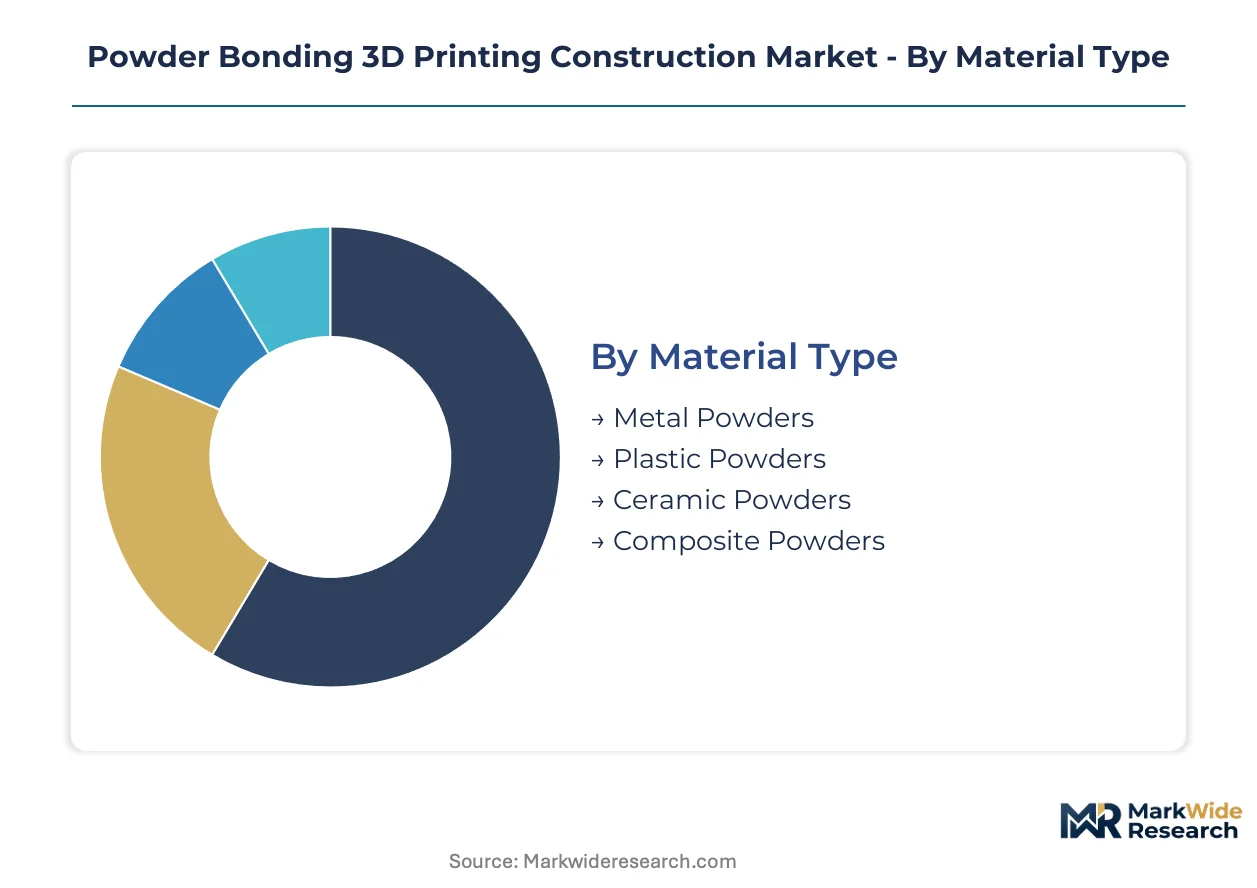
Powder bonding 3D printing construction segments diverge sharply by material cost tier and regulatory certification burden. Material type and printing technology determine equipment capex and feedstock supply chain structures, while application sector and end user shape procurement cycles and performance specifications.
Material Type:
Mature industrial feedstocks dominate current procurement volumes, though emerging formulations are capturing specification-driven niches in carbon-constrained markets.
- Metal Powders:Stainless steel and aluminum alloys with particle distributions of 10-45 microns produce fatigue-resistant connection hardware for seismic-zone structural joints. Demand concentrates in UAE commercial towers where Dubai Municipality's 3D printing codes mandate performance-based certification for load-bearing elements.
- Composite Powders:Geopolymer and fiber-reinforced formulations displace Portland cement in Northern European residential foundations, achieving embodied carbon reductions without compressive strength penalties. Contractors in Denmark and the Netherlands specify these for public housing tenders with strict environmental procurement criteria.
- Plastic Powders:Polymer binders serve non-structural architectural components and temporary formwork systems where weight reduction outweighs load-bearing requirements.
- Ceramic Powders:Alumina and zirconia-based materials enable high-temperature facade elements and specialized infrastructure coatings with superior weathering resistance.
Metal powders retain volume leadership; composite powders hold the steepest expansion curve.
Printing Technology:
Technology selection fractures along build-speed versus surface-finish tradeoffs, with cost-per-cubic-meter varying by an order of magnitude across methods.
- Binder Jetting:Dry-powder deposition with selective liquid activation achieves layer rates of 50-100 mm per hour, the fastest among construction-viable methods. UAE contractors deploy these systems for affordable housing foundations where Dubai's 3D Printing Strategy deadlines compress project schedules.
- SLS:Selective laser sintering of polymer and composite powders delivers superior tensile consistency for precision connection hardware. German equipment vendors integrate these systems with automated powder recycling to reduce feedstock waste in high-volume precast operations.
- SLA:Stereolithography's liquid-resin curing produces architectural mockups and detailed facade prototypes, though structural applications remain limited by material brittleness.
- DLP:Digital light projection offers faster layer curing than SLA for small-format decorative elements and custom hardware fittings.
Binder jetting commands the largest installed base; SLS installations are climbing fastest in European markets.
Application Sector:
Sector maturity correlates inversely with performance certification timelines, constraining revenue recognition in longer-cycle infrastructure categories.
- Residential Buildings:Single-family and low-rise multifamily structures dominate current deployment, with standardized wall and foundation elements reducing engineering overhead. UAE affordable housing agencies consolidate procurement around printed structural components to meet Dubai's mandate for additive methods in 25% of new buildings.
- Infrastructure Projects:Bridge segments, culverts, and utility housings attract disproportionate R&D investment despite nascent commercialization. Longer procurement cycles and higher performance thresholds delay revenue recognition until national building codes clarify printed element qualification.
- Commercial Structures:Mid-rise office and retail buildings face mortgage-qualification barriers until underwriters finalize insurance protocols for printed structural elements.
- Industrial Facilities:Warehousing and manufacturing plants with less stringent aesthetic requirements adopt printed elements for rapid enclosure systems.
Residential applications generate current revenue concentration; infrastructure projects carry the highest long-term contract value potential.
End User:
Customer type determines technical capability requirements and procurement sophistication, fragmenting vendor sales approaches across four distinct engagement models.
- Construction Firms:General contractors and specialized subcontractors purchase equipment and feedstock for on-site or near-site production. Large UAE developers internalize powder bonding capabilities to capture vertical integration advantages under Dubai's accelerated building mandates.
- Architectural Agencies:Design firms commission printed elements for complex geometric facades and structural optimization studies, driving specification influence without direct equipment procurement.
- Manufacturing Companies:Precast concrete producers and building component suppliers adopt hybrid workflows integrating binder jetting with conventional batching systems.
- Research Institutions:Universities and national laboratories validate material performance and develop certification protocols for emerging feedstock formulations.
Construction firms account for the majority of equipment purchases; architectural agencies are expanding fastest as design-to-fabrication workflows mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment vendors export gantry-based powder bonding systems to Northern European contractors seeking carbon-compliant foundation methods. UAE developers import metal powder sintering technology from Chinese feedstock suppliers for seismic-resistant connection hardware. Danish precast producers source geopolymer composite formulations from Netherlands-based material laboratories to meet public housing tender requirements.
United Arab Emirates
Dubai's 3D Printing Strategy mandates additive methods in 25% of new buildings, forcing equipment vendors to accelerate MOHAP registration timelines. Dubai Municipality's construction codes define performance-based structural outcomes independent of manufacturing method. Affordable housing agencies in Abu Dhabi consolidate procurement around printed foundation elements to meet federal sustainability targets.
Germany
REACH restrictions on hazardous substance emissions force reformulation of legacy polymer binders used in construction-grade powders. ECHA's substance evaluation criteria tighten feedstock composition requirements for powder bonding applications. Equipment vendors in Bavaria internalize compliance testing to preserve product launch velocity amid regulatory uncertainty.
Denmark
Public housing tenders with strict environmental procurement criteria specify geopolymer composite foundations over Portland cement alternatives. The country's building codes clarify CE marking pathways for novel additive materials in residential construction. Contractors in Copenhagen deploy binder jetting systems for low-rise multifamily projects to achieve embodied carbon reduction mandates.
United States
OSHA's permissible exposure limits for respirable crystalline silica impose capital-intensive ventilation protocols on powder-handling operations. Defense-sector rapid-shelter specifications standardize equipment requirements for military contingency operations. Equipment deployments in Texas and California concentrate on single-family residential printing where site logistics constraints favor mobile-robotic systems.
China
Specialty alloy feedstock production clusters expose equipment vendors to geopolitical disruption and freight cost volatility for metal powder supply. The country's national building material standards are evolving to address additive manufacturing certification. Precast concrete producers in the Yangtze River Delta region adopt hybrid workflows integrating binder jetting with conventional batching systems.
Powder Bonding 3D Printing Construction Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented equipment and feedstock tiers. Large-format residential printing vendors in Northern Europe face pressure from mobile-robotic deployment models reducing site logistics overhead. Three archetypes dominate: gantry-based system providers, mobile-robotic fabricators, and proprietary material formulators. Competitive moves concentrate on strategic partnerships with affordable housing agencies and accelerated certification pipeline investments ahead of mortgage-qualification deadlines.
Among large-format equipment specialists, COBOD International and CyBe Construction exemplify the gantry-based archetype serving Northern European residential foundations. Mobile-robotic deployment models find representation in Apis Cor, which occupies a position emphasizing site logistics reduction for single-family construction. ICON anchors the proprietary material tier through defense-sector positioning. These three companies collectively illustrate the technology-pathway fragmentation shaping vendor competitive positioning.
| Leading Market Players |
|---|
| COBOD International |
| Apis Cor |
| ICON |
| CyBe Construction |
| XtreeE |
| Winsun |
| Constructions-3D |
| Contour Crafting |
| Sika |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port congestion amplifies feedstock cost volatility for German equipment vendors importing Chinese specialty alloys, compressing margins on metal powder sintering systems while widening price spreads between certified and uncertified material tiers. This logistics chokepoint concentrates pricing power among integrated suppliers with captive powder production, forcing project-based buyers toward longer-term offtake contracts.
Pricing Analysis
Technology-generation pricing gaps separate legacy binder jetting systems from next-generation geopolymer composite platforms and prior-generation gantry-based installations. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking status, MOHAP registration completion, and after-sales service bundling. Pricing pressure stems from REACH-driven reformulation costs passing through to Northern European contractors. Affordable housing agencies in the UAE exhibit highest price sensitivity due to mandate-driven volume procurement, while defense-sector buyers prioritize performance over unit cost.
Supply Chain Analysis
German export-control restrictions on dual-use laser sintering technology limit equipment flows to Chinese precast producers, fragmenting supply chain access. Specialty alloy feedstock production clusters in Germany, China, and South Korea, with geopolymer composite formulations concentrated in Netherlands-based material laboratories. Raw material dependencies span nickel-chromium powders, metakaolin feedstock, and proprietary activator chemicals. Single-source vulnerability concentrates in Chinese rare-earth processing for high-performance laser optics. Distribution runs through equipment vendor-direct sales for large-format systems and regional distributor networks for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated affordable housing agencies in the UAE and Denmark as procurement scales fragment traditional subcontractor networks into single-source printed component contracts.
For Market Incumbents: Pre-empt margin erosion from geopolymer composite disruptors by accelerating in-house materials science capabilities and securing MOHAP registration ahead of Dubai's mortgage-qualification deadlines. Vertical integration into metakaolin feedstock sourcing reduces exposure to Netherlands-based supplier concentration. Lock in multi-year equipment leases with UAE developers to defend against mobile-robotic deployment models. For New Entrants and Emerging Players: Establish a beachhead in seismic-zone load-bearing hardware applications where metal powder sintering specifications remain undersupplied relative to structural engineering demand. Target infrastructure project R&D allocations with fatigue-resistant connection joint prototypes. Lead with topology optimization software bundling to differentiate from gantry-based incumbents lacking geometric complexity talent. For Investors and Strategic Acquirers: Carve-out targets emerge from precast concrete producers with stranded conventional batching assets seeking hybrid workflow transitions. Five-to-ten year viability hinges on national building code adoptions clarifying printed element insurance protocols. Monitor Dubai Municipality certification timeline acceleration as the inflection signal for mortgage-market liquidity unlocking.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Registration Acceleration | First-mover vendors capture UAE affordable housing procurement mandates ahead of competitor compliance timelines. |
| Geopolymer Composite Backward Integration | Captive metakaolin sourcing insulates margins from Netherlands feedstock supply concentration. |
| Defense-Sector Rapid-Shelter Partnership | Lavacrete-compatible equipment standardization locks in military contingency deployment specifications. |
| Topology Optimization Talent Acquisition | Scarce structural engineering capabilities enable premium pricing for complex lattice geometries. |
| Hybrid Batching System Joint Venture | Precast plant integration accelerates binder jetting adoption without greenfield capex requirements. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with equipment vendor sales directors, geopolymer materials scientists, UAE affordable housing procurement officers, and Danish public housing tender administrators; and secondary validation against Dubai Municipality construction codes, ECHA substance evaluation databases, OSHA silica exposure rulings, and EU Construction Products Regulation CE marking pathways. Bottom-up triangulation across equipment shipment records and top-down validation through national building material registries anchored volume estimates.
Forecast inputs considered technology adoption curves across binder jetting, selective laser sintering, and stereolithography platforms; material type segmentation spanning metal powders, geopolymer composites, and ceramic formulations; application sector differentiation between residential foundations, commercial structures, and infrastructure projects; and end-user archetypes from construction firms to research institutions. CAGRs derived from regression analysis of procurement cycle compression and regulatory deadline acceleration. Industry-specific inputs incorporated MOHAP registration velocity and REACH reformulation cost pass-through rates.
Sensitivities concentrate around Dubai mortgage-qualification timeline delays, ECHA substance restriction expansions, and Chinese export license disruptions for laser sintering equipment. Forecasts reflect documented assumptions on national building code adoption rates and defense procurement standardization. Material shifts in UAE federal sustainability target enforcement or German export-control scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
Conventional and Rapid Prototyping Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
North America Additive Manufacturing with Metal Powders Market
3D Printing Technology
3D Printing Enabled Augmented Manufacturing Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
Europe Industrial 3D Printing Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
Online 3D Printing Service Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
3D Printing Service Bureaus Market
3D Printing Technology
4D Printing Market
3D Printing Technology
Latin America Industrial 3D Printing Market