
 Global 3D Metal Printing Machines Market | 2026-2036
Global 3D Metal Printing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Metal Printing Machines Market Foresight
Buyer concentration among aerospace OEMs and tier-one automotive suppliers is recalibrating procurement patterns across the installed base. EOS GmbH leverages its deep integration with German automotive qualification workflows to sustain long-term service contracts. Nikon SLM Solutions anchors its position through precision optics expertise that controls beam quality in multi-laser systems. Farsoon Technologies competes aggressively on open-material architecture, extending customer flexibility for proprietary alloy development.
3D metal printing machines fuse metallic powders or wires using laser, electron beam, or thermal energy sources to produce dense, near-net-shape components with typical layer thicknesses of 20–100 microns and build envelopes ranging from 250 mm to over 1.5 meters. These systems serve industrial applications requiring complex geometries, internal cooling channels, or material efficiency impossible with conventional subtractive methods. Powder Bed Fusion technology dominates current installed value due to its mature qualification pathways in medical implants and aerospace structural parts, while Binder Jetting represents the fastest-expanding process category as throughput economics improve for stainless steel and tool steel production at scale. Industrial Systems command the largest product-type revenue pool, though Hybrid Systems that combine deposition with CNC finishing are capturing margin-rich niches in mold repair and legacy part remanufacturing.
FDA device regulations and FAA airworthiness certification standards shape machine specification requirements in the United States, mandating extensive process validation documentation and traceable parameter logging. EMA medical device frameworks and REACH substance restrictions in Europe impose additional material compliance burdens that filter down to equipment design and software architecture. ISO/ASTM additive manufacturing standards provide the cross-border interoperability baseline that reduces market fragmentation for multinational buyers. Stakeholders must monitor evolving certification reciprocity agreements between national aviation authorities, as these directly determine which machine platforms qualify for cross-regional production contracts.
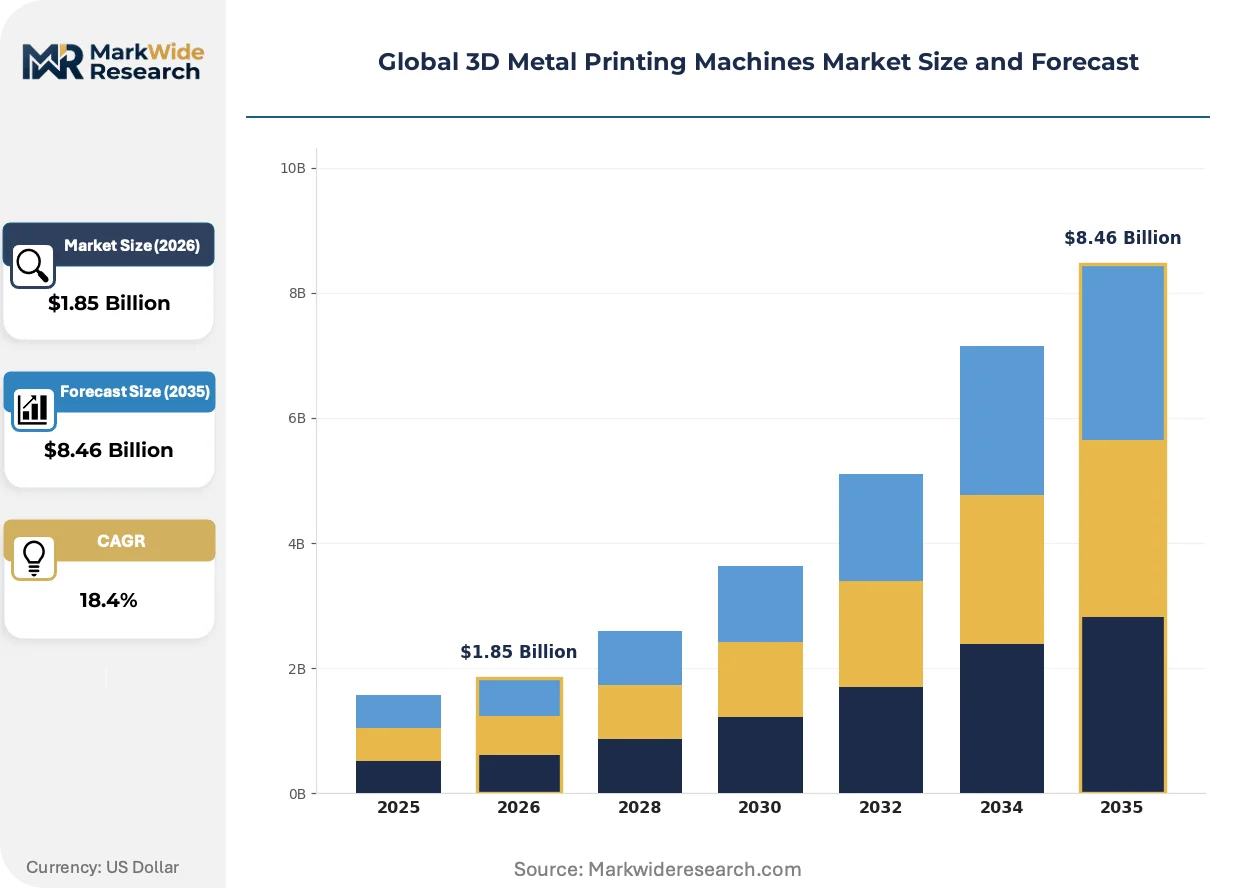
Market Dynamics
Aerospace OEMs are consolidating machine procurement around flight-critical titanium components, forcing equipment suppliers to restructure qualification support and long-term service architectures around FAA certification timelines.
Growth Catalysts
- FAA Airworthiness Mandates:Flight-critical component sourcing rules are compelling aerospace tier-ones to qualify dedicated additive manufacturing cells for titanium structural parts, locking in multi-year equipment commitments.
- REACH Substance Traceability:ECHA compliance requirements in Europe are mandating certifiable build parameter logging, pushing machine architecture toward closed-loop sensor integration and blockchain-ready data layers.
- Binder Jetting Throughput Economics:Stainless steel and tool steel production at scale is accelerating adoption among automotive tooling suppliers seeking net-shape geometries without laser-based cycle times.
Market Restraints
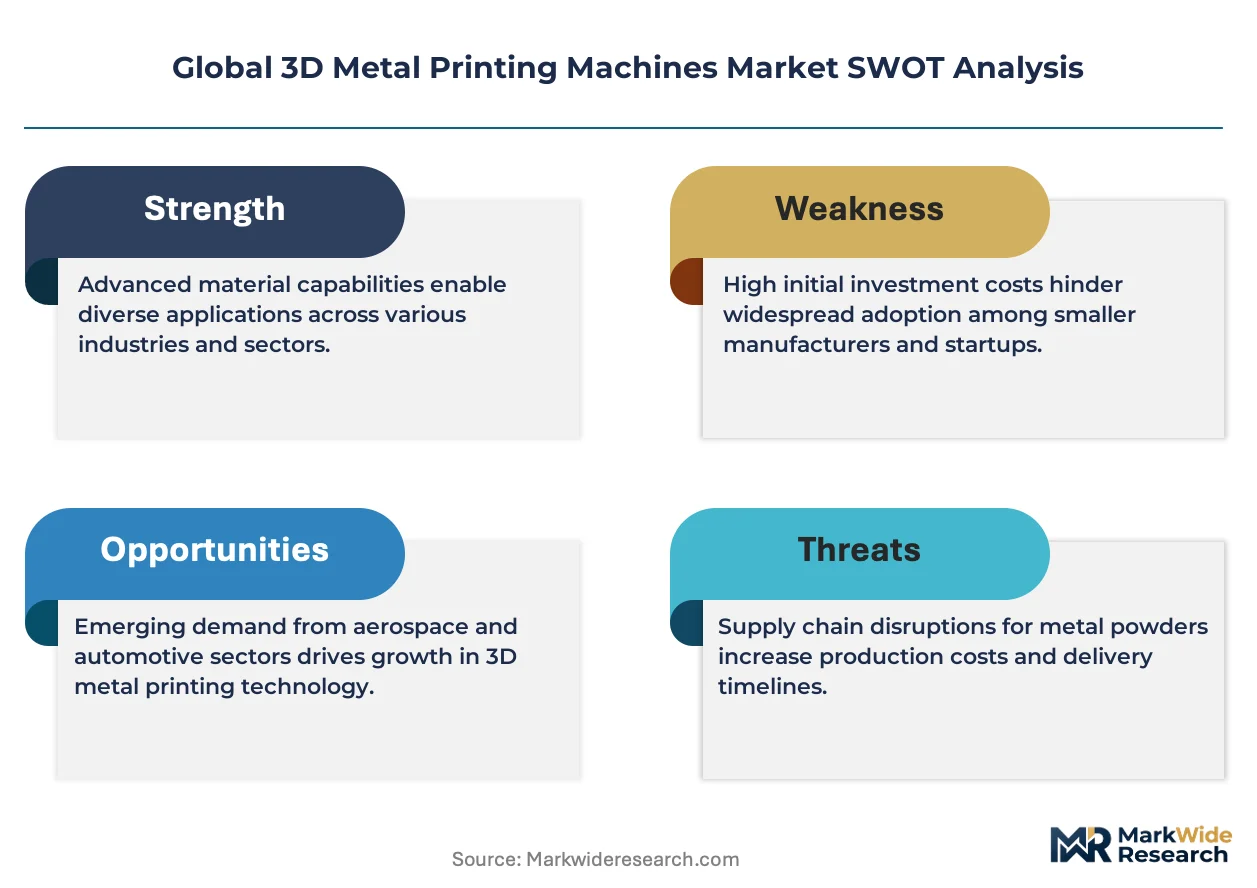
- Powder Supply Concentration:Spherical titanium and nickel superalloy feedstock production clusters in Germany and the United States, creating single-source vulnerability for Asian machine operators.
- Multi-Laser System Capex:Industrial PBF platforms with four or more beam sources require capital commitments exceeding conventional five-axis machining centers, excluding mid-tier job shops.
- ISO/ASTM Certification Gaps:Incomplete harmonization between national aviation authorities delays cross-regional production contract eligibility for otherwise qualified machine installations.
Strategic Opportunities
- India Tooling Sector:Die and mold manufacturers in Pune and Chennai clusters show minimal AM penetration despite complex cooling channel requirements, presenting first-mover equipment positioning.
- EU AI Act Compliance Services:Machine builders can capture recurring revenue by embedding automated defect detection and predictive maintenance modules that satisfy algorithmic transparency mandates for medical device production.
- Hybrid System Remanufacturing:Deposition-plus-CNC platforms enable legacy part restoration for defense and energy sectors, opening margin-rich niches outside greenfield component markets.
Industry Challenges
- Process Engineer Scarcity:Qualified technicians capable of parameter development for new alloys command compensation premiums that erode job shop margins during qualification phases.
- Multi-Year Certification Timelines:FAA and EMA validation documentation requirements stretch eighteen to thirty-six months, freezing capital deployment and compressing equipment ROI windows.
- Legacy MES Integration:Shop floor data architectures from established CNC vendors resist seamless additive manufacturing parameter ingestion, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Metal Printing Machines Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Powder Bed Fusion, Directed Energy Deposition, Binder Jetting, Material Extrusion, Sheet Lamination Application: Aerospace Parts, Medical Implants, Automotive Components, Industrial Tooling, Jewelry Product Type: Desktop Machines, Mid-Size Printers, Industrial Systems, Hybrid Systems, Portable Printers End User: OEMs, Aftermarket Providers, Custom Manufacturers, Research Institutions, Contract Manufacturers |
| Companies Covered | EOS GmbH, BLT, Nikon SLM Solutions, 3D Systems, Colibrium Additive, DMG Mori, Farsoon Technologies, Desktop Metal, EPlus3D, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Metal Printing Machines Market Shifts & Advancements
Equipment architectures are fragmenting between high-throughput commodity production and precision-qualified aerospace cells, with software-defined process control emerging as the primary differentiation axis.
Multi-laser Powder Bed Fusion is decentralizing build job allocation across distributed beam sources, enabling parallel processing of smaller components within single large-format machines. Medical implant manufacturers in Switzerland and orthopedic suppliers in the United States are adopting these architectures to compress lot turnaround times. This topology is decentralizing production planning authority from central manufacturing engineering to cell-level operators.
EMA's Medical Device Regulation and the EU AI Act are converging to mandate algorithmic explainability in automated quality assurance modules. Machine builders must now document decision pathways for defect classification models. European orthopedic and dental implant producers are responding by demanding open-architecture software stacks that permit customer-side algorithm auditing.
After-sales service unbundling is accelerating as aerospace OEMs negotiate separate contracts for hardware, software maintenance, and process qualification support. Tier-one automotive suppliers in Germany are following this pattern, treating machine acquisition as capital expenditure and ongoing parameter optimization as operational expenditure. This bifurcation is most pronounced in Bavaria's automotive supply cluster and Michigan's aerospace corridor.
Global 3D Metal Printing Machines Market Segmentation
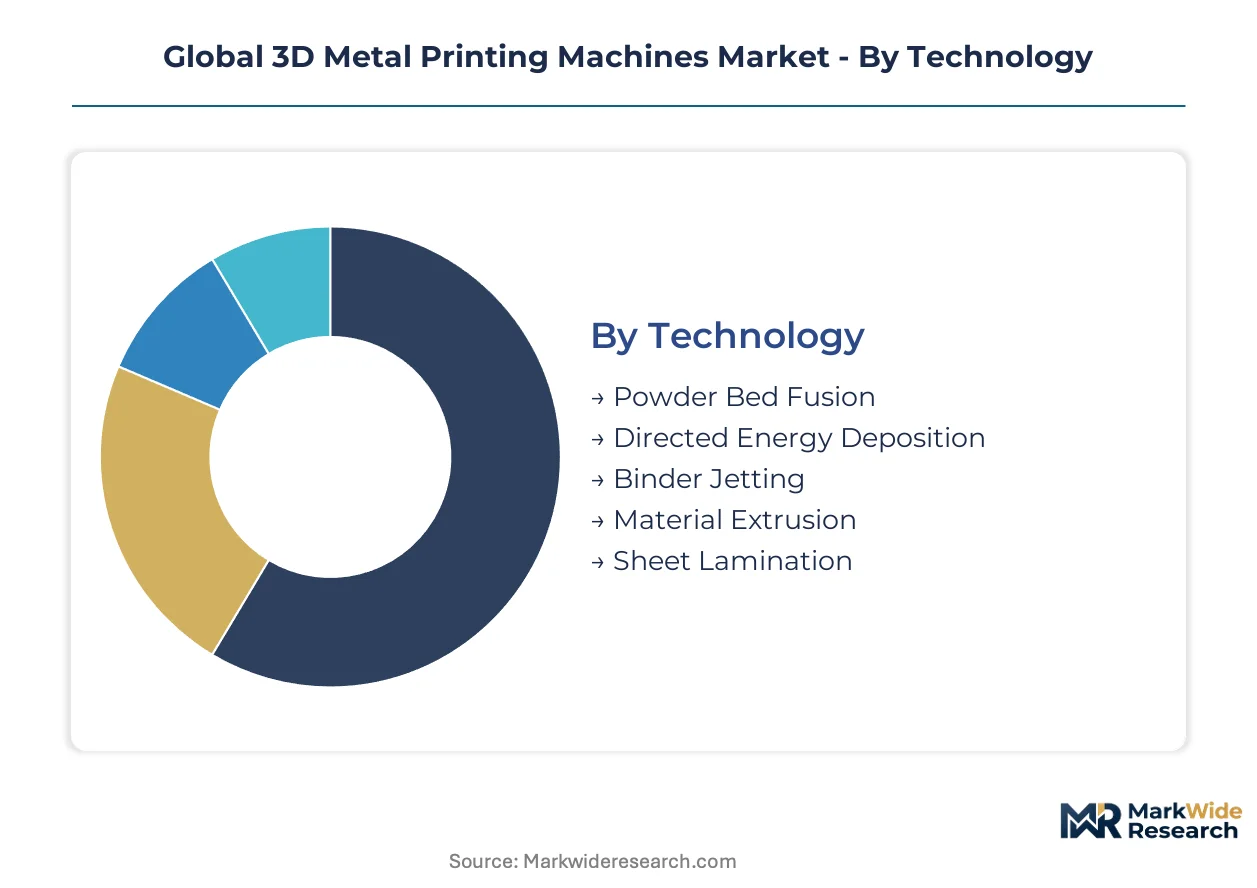
Technology choice dictates certification pathways and capital intensity in metal additive manufacturing. Equipment buyers align machine specifications with end-use regulatory requirements and production economics.
Technology:
FAA airworthiness mandates and EMA medical device frameworks impose distinct validation burdens across process categories, with laser-based systems facing the most stringent documentation requirements.
- Powder Bed Fusion:Laser or electron beam systems fuse metallic powder layers with typical resolutions of 20–50 microns. Aerospace OEMs in Germany and the United States concentrate procurement here for titanium structural components requiring FAA traceability documentation.
- Binder Jetting:Liquid binding agents join metal powder layers before thermal sintering, enabling stainless steel throughput economics without laser cycle times. Automotive tooling suppliers in Bavaria and Michigan are expanding installations for net-shape production at scale.
- Directed Energy Deposition:Wire or powder-fed systems deposit molten material for repair applications and large-format builds.
- Material Extrusion:Metal-loaded filament extrusion followed by debinding and sintering suits prototyping and low-volume production.
- Sheet Lamination:Ultrasonic bonding of metal sheets with CNC contouring serves hybrid manufacturing and multimaterial structures.
Powder Bed Fusion sits at the top of the volume ranking, with Binder Jetting climbing the fastest.
Application:
End-use sectors separate into flight-critical qualification tiers and commercial production tiers, with certification timelines stretching eighteen to thirty-six months for aerospace and medical segments.
- Aerospace Parts:Flight-critical titanium and nickel superalloy components demand closed-loop parameter logging and blockchain-ready traceability layers. Tier-one suppliers in Toulouse, Hamburg, and Seattle anchor procurement concentration.
- Medical Implants:Orthopedic and dental devices require EMA MDR compliance and FDA 510(k) pathways with algorithmic explainability for automated quality assurance. Swiss and U.S. manufacturers lead adoption of multi-laser architectures.
- Automotive Components:Structural and powertrain parts prioritize throughput over geometric complexity.
- Industrial Tooling:Mold inserts with conformal cooling channels drive demand from die manufacturers in Pune and Chennai.
- Jewelry:Precious metal processing favors small-format systems with high resolution.
Aerospace Parts commands the highest equipment margins, while Medical Implants expands most quickly on regulatory tailwinds.
Product Type:
Capital deployment patterns bifurcate between job shop affordability and OEM production cell integration, with hybrid architectures capturing remanufacturing niches.
- Industrial Systems:Large-format platforms with multi-laser configurations and build envelopes exceeding 400 mm dominate qualified production for aerospace and medical markets. German automotive suppliers treat these as dedicated capital expenditure with separate operational budgets for parameter optimization.
- Hybrid Systems:Deposition heads integrated with five-axis CNC finishing enable legacy part restoration and mold repair. Defense and energy sectors in the United States and United Kingdom are expanding adoption for remanufacturing applications.
- Desktop Machines:Compact systems suit research and prototyping with limited build volumes.
- Mid-Size Printers:Intermediate platforms bridge qualification workflows and production scaling.
- Portable Printers:Field-deployable systems serve maintenance and repair operations.
Industrial Systems leads revenue concentration, with Hybrid Systems gaining share fastest in margin-rich restoration markets.
End User:
Customer procurement authority shapes service contract structures, with OEMs unbundling hardware, software, and qualification support into separate expenditure categories.
- OEMs:Aerospace and automotive original equipment manufacturers consolidate machine procurement around dedicated additive manufacturing cells with multi-year service architectures. Boeing, Airbus, and BMW Group negotiate separate contracts for hardware ownership and ongoing process validation.
- Contract Manufacturers:Job shops and production service providers face compressed ROI windows from certification timelines and process engineer scarcity. Mid-tier operators in the U.S. Midwest and German industrial clusters struggle with multi-laser system capex thresholds.
- Aftermarket Providers:Maintenance and spare part producers leverage AM for legacy system support.
- Custom Manufacturers:Bespoke production houses serve low-volume, high-complexity orders.
- Research Institutions:Universities and national laboratories drive alloy development and parameter innovation.
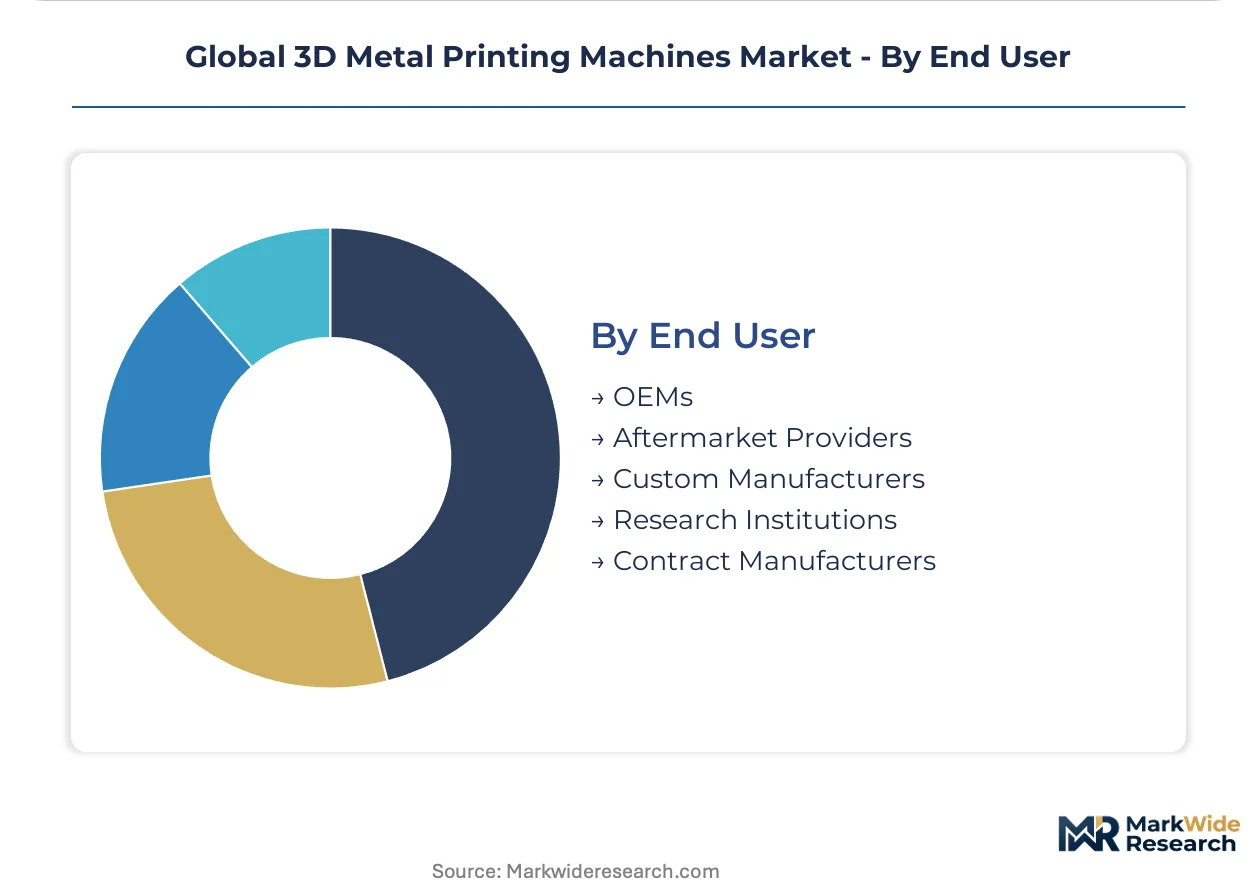
OEMs dominate installed value, with Contract Manufacturers showing the steepest expansion trajectory as qualification timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands denser precision engineering supplier networks than the United States, yet American aerospace OEMs drive larger procurement volumes for flight-critical titanium platforms.
United States
FAA airworthiness mandates compel Boeing and Lockheed Martin to qualify dedicated additive manufacturing cells for titanium structural components. FDA device regulations impose extensive process validation documentation on medical implant producers. Seattle and Los Angeles aerospace clusters anchor the highest concentration of multi-laser system installations.
Germany
BMW Group and Airbus consolidate machine procurement around dedicated production cells with separate operational budgets for parameter optimization. REACH substance traceability requirements push equipment architecture toward closed-loop sensor integration. Bavaria's automotive supply cluster treats hardware acquisition as capital expenditure distinct from ongoing qualification support.
China
Domestic aerospace programs accelerate titanium component sourcing from qualified additive manufacturing suppliers. MIIT industrial standards shape equipment specification requirements for defense and civil aviation applications. Shenzhen and Beijing research institutions drive parameter innovation for proprietary alloy development.
Japan
METI advanced manufacturing initiatives support precision metal printing adoption for orthopedic and dental implant production. PMDA medical device frameworks mandate algorithmic explainability for automated quality assurance modules. Nagoya industrial machinery suppliers integrate deposition heads with five-axis CNC finishing for mold repair applications.
India
Die and mold manufacturers in Pune and Chennai clusters show minimal AM penetration despite complex cooling channel requirements. BIS industrial standards and PLI scheme incentives encourage first-mover equipment positioning. Contract manufacturers in the Delhi-Mumbai industrial corridor face compressed ROI windows from certification timelines.
Global 3D Metal Printing Machines Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale-driven industrial platforms coexist with agile open-architecture challengers. Market concentration remains moderate, with no single vendor commanding dominant share across all process categories. Three strategic archetypes define competitive positioning: precision-integrated German engineering houses, Chinese open-material platform builders, and diversified Japanese machine tool conglomerates. Dominant competitive moves include strategic partnerships for powder supply security and technology licensing for regional market access.
Within the precision-integrated tier, EOS GmbH and Nikon SLM Solutions exemplify equipment suppliers that anchor positions through deep qualification workflow integration and optical beam control expertise respectively. Farsoon Technologies occupies a position among open-architecture specialists competing aggressively on material flexibility. DMG Mori represents diversified machine tool conglomerates leveraging hybrid system portfolios to capture remanufacturing niches in defense and energy sectors.
| Leading Market Players |
|---|
| EOS GmbH |
| BLT |
| Nikon SLM Solutions |
| 3D Systems |
| Colibrium Additive |
| DMG Mori |
| Farsoon Technologies |
| Desktop Metal |
| EPlus3D |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in China and family-owned precision engineering houses in Germany anchor divergent pricing disciplines, with state-supported capacity expansion compressing mid-tier equipment margins while European specialists defend premiums through qualification-integrated service architectures. This bifurcation concentrates pricing power among vendors with captive powder supply or deep aerospace certification workflows, leaving independent machine builders exposed to feedstock cost volatility.
Pricing Analysis
Capacity additions in China are reshaping price floors for industrial Powder Bed Fusion platforms, with domestic vendors undercutting European equivalents by fifteen to twenty percent on hardware-only transactions. Pricing stratifies across aerospace-qualified, medical-certified, and industrial-grade tiers, with FAA traceability documentation and EMA MDR compliance commanding substantial premiums. Cost compression in the mid-tier intensifies because Chinese producers are bundling basic training and domestic powder supply. Contract manufacturers in the U.S. Midwest and German industrial clusters exhibit the sharpest price sensitivity, while aerospace OEMs in Seattle and Toulouse prioritize qualification support over unit economics.
Supply Chain Analysis
Remanufacturing flows for legacy aerospace components and mold repair applications are creating secondary supply channels that compete with virgin powder procurement, particularly for titanium and nickel superalloy feedstock. Spherical titanium powder production concentrates in Germany, the United States, and China, with gas atomization capacity expanding fastest among Chinese state-affiliated producers. Machine builders draw from specialized optical component suppliers in Japan, high-power laser manufacturers in Germany, and motion control specialists in Switzerland. Single-source vulnerability for electron beam source assemblies creates structural risk for vendors without dual-qualified sub-tier relationships. Distribution runs through direct OEM sales teams for aerospace and medical accounts, with regional distributors serving job shops and contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on software-defined process control modules that convert capital equipment sales into recurring revenue streams, while binder jetting throughput economics open volume-tier pricing previously inaccessible to laser-based platforms.
For Market Incumbents: Anchor defensive positions through backward integration into spherical powder production, particularly for titanium and nickel superalloy grades where German and Chinese supply concentration creates vulnerability. Lock in long-term service contracts with aerospace OEMs by embedding predictive maintenance algorithms that satisfy EU AI Act transparency mandates, neutralizing emerging Chinese vendors on qualification timelines rather than hardware cost. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for algorithmic explainability specialists to capture medical device production contracts from incumbent machine builders with legacy software architectures. Target India's die and mold manufacturers in Pune and Chennai clusters with compact binder jetting systems priced below multi-laser Powder Bed Fusion thresholds. Lead with open-material platforms that permit customer-side alloy development, mirroring Farsoon Technologies' positioning in Chinese and Asian markets. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid system specialists with deposition-plus-CNC portfolios serving defense remanufacturing contracts, where margin profiles exceed greenfield component production. Five-to-ten year viability favors vendors with software recurring revenue exceeding thirty percent of total sales, insulating against hardware commoditization. Monitor FAA-EASA certification reciprocity negotiations as the critical inflection signal—accelerated harmonization would unlock cross-regional production contracts for qualified machine platforms, re-rating vendors with dual-jurisdiction validation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Supply | Captive spherical titanium production insulates EOS GmbH and Nikon SLM Solutions from feedstock cost volatility. |
| Software-Defined Process Control Modules | Automated defect detection algorithms satisfy EU AI Act mandates for medical implant manufacturers in Switzerland. |
| Binder Jetting Capacity Expansion | Stainless steel throughput economics capture automotive tooling demand from Bavarian die manufacturers. |
| Hybrid System Portfolio Development | Deposition-plus-CNC platforms access margin-rich defense remanufacturing contracts in the United States. |
| Regulatory Compliance Service Unbundling | Separate qualification support contracts convert capital expenditure into recurring operational revenue from BMW Group. |
Research Methodology
Direct dialogue with additive manufacturing cell managers at aerospace tier-ones, process engineering directors at orthopedic implant producers, procurement leads at German automotive suppliers, and powder metallurgy specialists at gas atomization facilities grounded qualitative findings. Secondary validation drew from FAA airworthiness directives, EMA Medical Device Regulation guidance documents, ISO/ASTM additive manufacturing standards, and SEC filings from diversified machine tool conglomerates. Bottom-up equipment shipment tallies triangulated against top-down end-use demand estimates across aerospace, medical, and automotive segments.
Installed base projections and revenue forecasts across the modeling period reflect segment-level CAGRs derived from technology adoption curves, regulatory timeline assumptions, and capital expenditure patterns at named OEMs. Segmentation dimensions include process technology, application sector, product type, and end-user procurement authority, with additional granularity on laser source configuration and build envelope size. Forecast inputs incorporated powder supply capacity expansion timelines, certification reciprocity negotiation status between national aviation authorities, and software recurring revenue penetration rates at leading vendors.
Revisions become necessary when FAA-EASA harmonization agreements stall, when Chinese powder export restrictions materialize, or when binder jetting sintering furnace capacity fails to match machine installation growth. Practitioners should monitor ECHA REACH substance restriction proposals, MIIT industrial standard updates from China, and algorithmic transparency enforcement patterns under the EU AI Act for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
Global 3D Printed Electronics Market
3D Printing Technology
Binder Jet Market
3D Printing Technology
3D Printing Robots Market
3D Printing Technology
4D Printing Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
3D Printer Market
3D Printing Technology
Asia-Pacific Industrial 3D Printing Market