
 Binder Jet Market | 2026-2036
Binder Jet Market Size, Share, and Industry Trends Forecast 2026-2036
Binder Jet Market Outlook
Production-grade specification tiers for density and surface finish is collapsing the gap between binder jetting and conventional powder metallurgy. Desktop Metal Inc leverages its in-house furnace network to control post-processing economics across stainless steel and tool steel workflows. ExOne anchors the sand-casting tooling segment with large-format machines serving foundries in the American Midwest. GE Additive dominates aerospace qualification pathways through its direct ties to jet engine OEMs.
Binder jetting deposits liquid binding agents onto powdered material beds to form green parts, which are then sintered to achieve final densities exceeding ninety-five percent for ferrous alloys. Metal binders command the largest revenue pool due to automotive and aerospace qualification cycles, while polymer binders serve rapid prototyping where thermal post-processing requirements are minimal. Tooling applications generate premium margins because printed sand molds and cores eliminate pattern fabrication lead times in foundry supply chains. Healthcare end users represent the fastest-growing demand channel as dental and orthopedic segments pursue patient-specific geometries.
FAA airworthiness standards and FDA quality system regulation shape certification timelines for flight-critical and implantable binder-jetted components. EPA powder handling guidelines and OSHA respirable metal dust limits raise facility capital requirements for North American producers. Stakeholders must monitor evolving sintering furnace throughput benchmarks and qualification data packages as OEMs shift from prototyping to serial production contracts.
Market Dynamics
The transition from prototyping to serial production contracts is compressing qualification timelines and forcing furnace throughput investments across automotive and aerospace supply chains. OEMs now demand density parity with wrought alloys while slashing pattern-to-part lead times.
Growth Catalysts
- FAA Airworthiness Pathways:Streamlined certification frameworks for flight-critical turbine components accelerate aerospace adoption timelines. Jet engine manufacturers leverage these pathways to validate printed blade geometries.
- Automotive Tooling Clusters:Dedicated additive manufacturing centers in Germany consolidate demand for stainless steel and tool steel workflows. Foundries eliminate pattern fabrication through printed sand molds and cores.
- Patient-Specific Orthopedics:FDA quality system regulation evolution enables dental and implantable device geometries previously machined from bar stock. Hospitals pursue surgical guide customization.
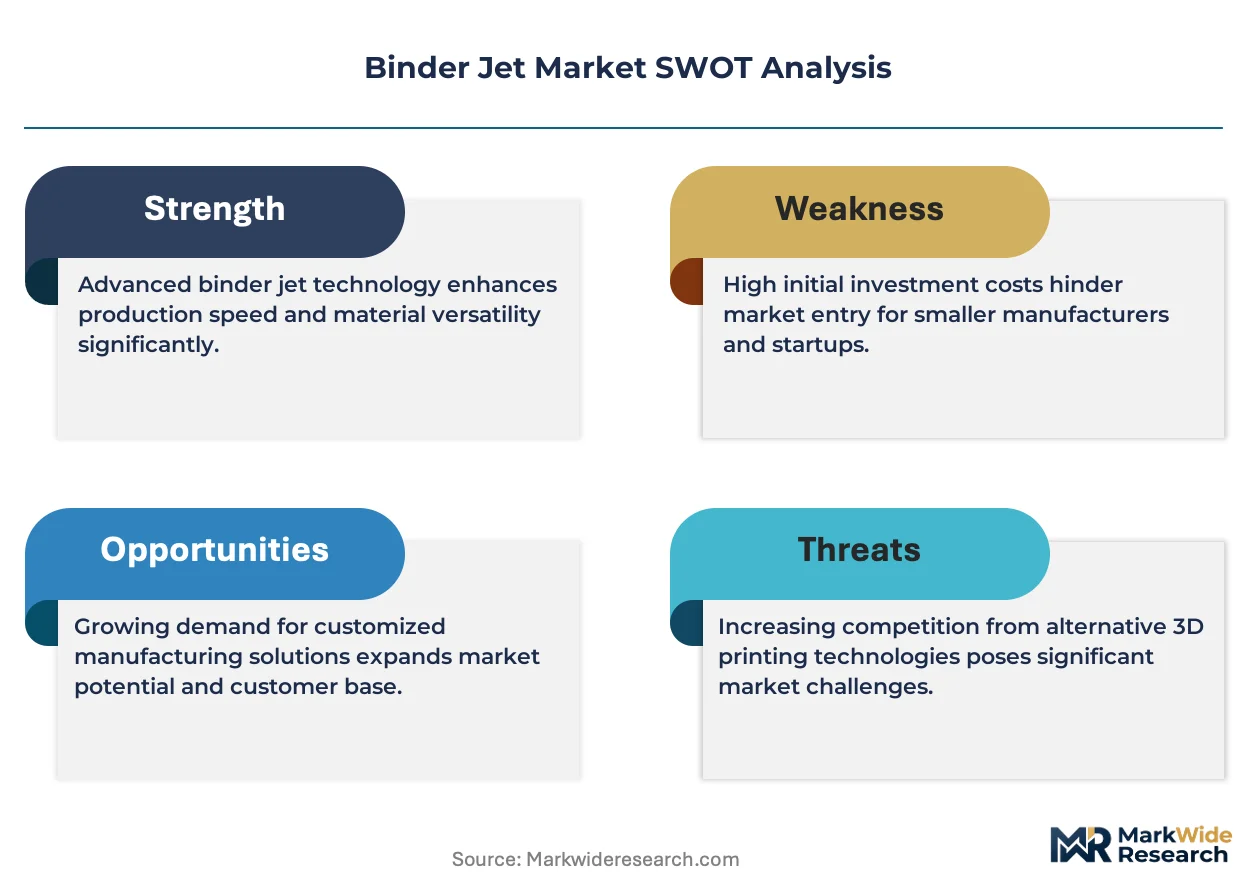
Market Restraints
- Respirable Metal Dust Compliance:OSHA exposure limits mandate capital-intensive powder handling infrastructure. North American producers face facility retrofit costs exceeding sintering equipment investments.
- Graphite Electrode Volatility:Furnace consumable price swings destabilize post-processing economics for ferrous alloy workflows. Sintering operations absorb margin compression.
- Substitution by Laser Powder Bed Fusion:Aerospace suppliers default to LPBF for titanium and nickel superalloys where density requirements exceed ninety-eight percent. Binder jetting cedes high-value flight segments.
Strategic Opportunities
- Indian Automotive Supplier Base:PLI scheme incentives for advanced manufacturing attract tooling investments from global OEMs seeking cost-competitive sand-casting alternatives. Domestic foundries lack large-format machine penetration.
- Copper Thermal Management:Convergence of binder jetting with pure copper sintering protocols opens heat sink applications for electric vehicle inverters and data center cooling. Thermal conductivity specifications favor printed geometries.
- EMA Medical Device Harmonization:Streamlined implant qualification across EU member states reduces redundant testing burdens. Orthopedic manufacturers consolidate European distribution through centralized certification.
Industry Challenges
- Process Engineer Scarcity:Green part handling and sintering shrinkage compensation require specialized expertise absent from conventional powder metallurgy training pipelines. Universities lack dedicated additive manufacturing curricula.
- ISO/ASTM Standardization Delays:Missing consensus on density measurement protocols and surface finish benchmarks prolongs customer qualification cycles. Suppliers await unified testing methodologies.
- Legacy ERP Integration:Foundries struggle to embed binder jetting workflows into MRP systems designed for pattern-based casting lead times. Production scheduling algorithms require fundamental restructuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Binder Jet Market |
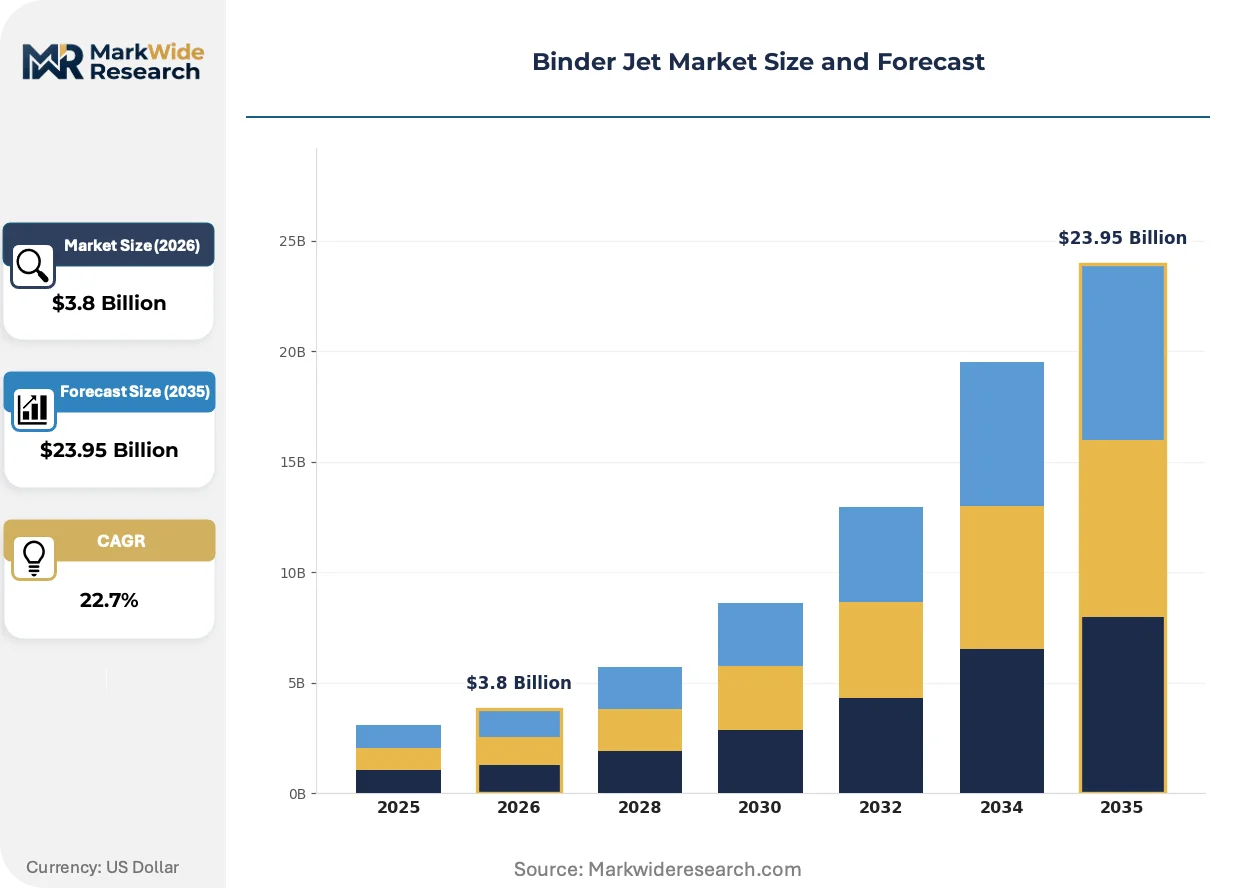
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Binders, Polymer Binders, Ceramic Binders, Others End User: Aerospace, Automotive, Healthcare, Consumer Goods Application: Prototyping, Production, Tooling, Customization Technology: 3D Printing, Additive Manufacturing, Direct Metal Deposition, Others |
| Companies Covered | Desktop Metal Inc, ExOne, GE Additive, Voxeljet AG, HP Inc, 3D Systems, Inc., Proto Labs Inc, Renishaw plc, Stratasys, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Binder Jet Market Strategic Shifts
Multi-material deposition capabilities and AI-driven shrinkage prediction are collapsing the iteration cycles between green part printing and final sintered dimensions. Equipment suppliers now bundle simulation software with furnace acquisitions.
Reactive metal binder formulations are decomposing the thermal barrier between printed green parts and full-density sintering. Automotive drivetrain suppliers adopt these chemistries for gear and shaft production at volumes exceeding ten thousand units annually. The technology is decomposing the cost floor that previously restricted metal additive manufacturing to aerospace price tolerance.
REACH substance restrictions on formaldehyde-based binders force European equipment suppliers to validate water-based and bio-derived alternatives. Foundries in the American Midwest face parallel EPA air emission scrutiny for thermal debinding stages. Sand-casting tooling producers accelerate furnace ventilation upgrades to maintain production permits.
Consolidated procurement by tier-one automotive suppliers compresses vendor qualification from twelve-month cycles to ninety-day pilot programs. Foundries abandon equipment-agnostic purchasing in favor of captive furnace networks with single-source binder supply agreements. Germany's automotive OEMs drive this behavioral shift through mandated supplier consolidation programs.
Binder Jet Market Segmentation
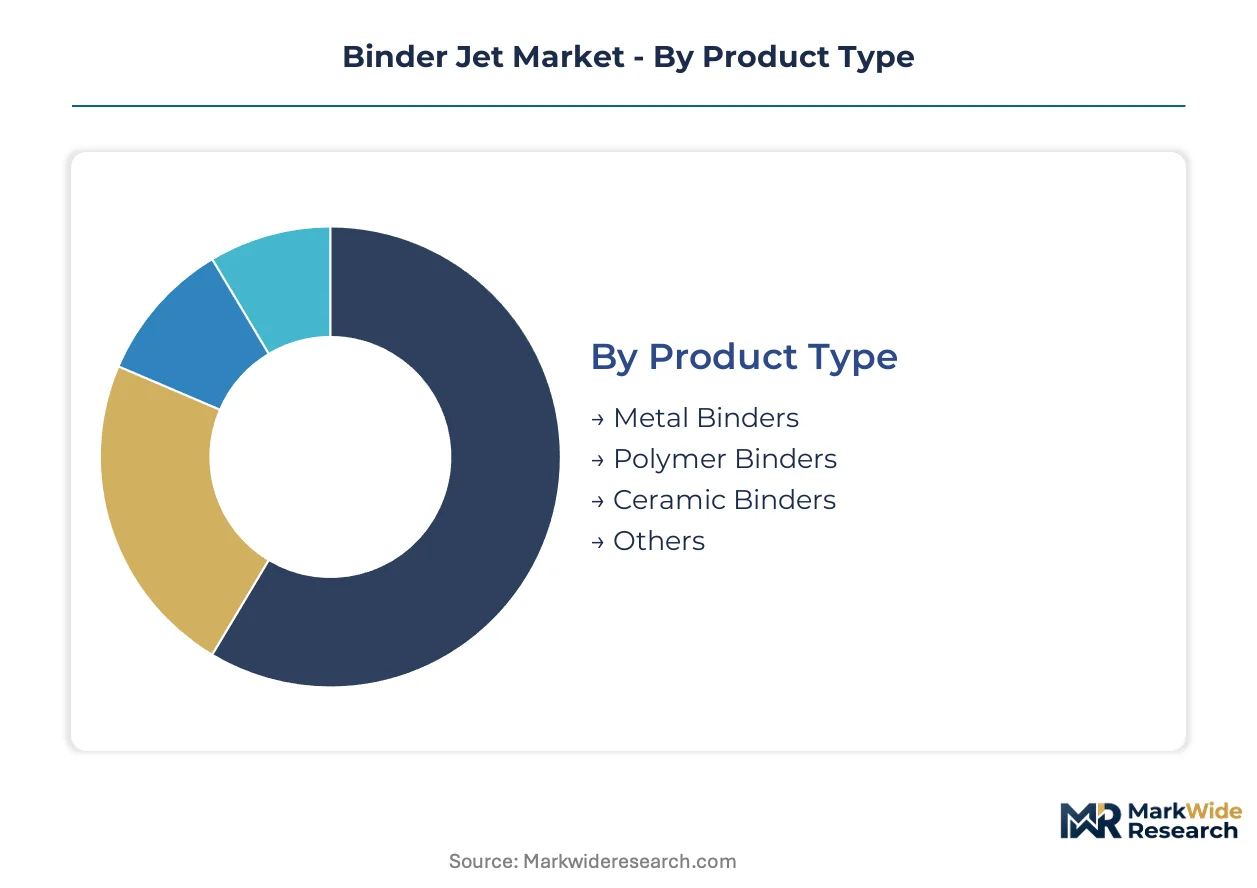
Binder jet market segmentation reveals distinct procurement channels where metal binders flow through aerospace qualification pathways, polymer binders serve rapid prototyping demand, and tooling applications consolidate around automotive supply chains. Understanding these channel dynamics exposes margin concentration and technology substitution risks.
Product Type:
Metal binders dominate direct sales channels to qualified aerospace and automotive OEMs, while polymer binders distribute through prototyping service bureaus and polymer binders reach foundries through equipment-integrated supply agreements.
- Metal Binders:Ferrous and non-ferrous powder formulations achieve final densities exceeding ninety-five percent through controlled atmosphere sintering. Demand concentrates in Germany where automotive OEMs operate dedicated additive manufacturing centers for stainless steel and tool steel drivetrain components. FAA airworthiness pathways compress qualification timelines for flight-critical turbine blade production.
- Polymer Binders:Thermoset and thermoplastic resin systems deposit without thermal post-processing requirements. Prototyping service bureaus in the United States absorb volume for rapid iteration cycles where surface finish specifications remain below production-grade thresholds. Minimal furnace infrastructure lowers barrier to entry for distributed manufacturing nodes.
- Ceramic Binders:Alumina and silica-based systems serve investment casting foundries requiring refractory mold geometries.
- Others:Composite and specialty formulations address niche applications in dental and jewelry segments.
By volume, metal binders lead. By growth pace, polymer binders for healthcare customization are expanding most quickly.
End User:
Cost tier segmentation separates flight-critical aerospace components commanding premium qualification overhead from automotive tooling applications where furnace throughput economics determine contract viability.
- Aerospace:Jet engine OEMs validate printed turbine blade geometries through direct ties to equipment suppliers. FAA streamlined certification frameworks accelerate adoption timelines for nickel superalloy components previously machined from wrought bar stock. Density parity requirements with conventional metallurgy sustain extended qualification cycles.
- Automotive:Drivetrain suppliers adopt reactive metal binder formulations for gear and shaft production at serial volumes. Germany's automotive OEMs consolidate supplier bases through mandated programs that compress vendor qualification from twelve-month cycles to ninety-day pilots. Foundries eliminate pattern fabrication lead times through printed sand molds and cores.
- Healthcare:FDA quality system regulation evolution enables patient-specific orthopedic implants and dental geometries.
- Consumer Goods:Jewelry and electronics accessories leverage design freedom without structural load requirements.
Aerospace commands the highest margin tier. Healthcare patient-specific applications are gaining share fastest.
Application:
Volume concentration separates prototyping workflows requiring minimal post-processing from production applications where sintering furnace throughput investments dominate capital allocation decisions.
- Tooling:Printed sand molds and cores eliminate pattern fabrication lead times in foundry supply chains. The American Midwest hosts concentrated demand from sand-casting tooling producers serving automotive supplier networks. EPA air emission scrutiny for thermal debinding stages accelerates furnace ventilation upgrades to maintain production permits.
- Production:Serial manufacturing contracts for ferrous alloy components demand density parity with wrought alloys. Automotive drivetrain suppliers achieve volumes exceeding ten thousand units annually through reactive metal binder chemistries. REACH substance restrictions on formaldehyde-based binders force validation of water-based alternatives in European operations.
- Prototyping:Rapid iteration cycles prioritize speed over final density specifications.
- Customization:Patient-specific geometries in dental and orthopedic segments pursue geometries impossible through conventional machining.
Tooling generates the steepest margin expansion. Production applications show the steepest trajectory toward volume scale.
Technology:
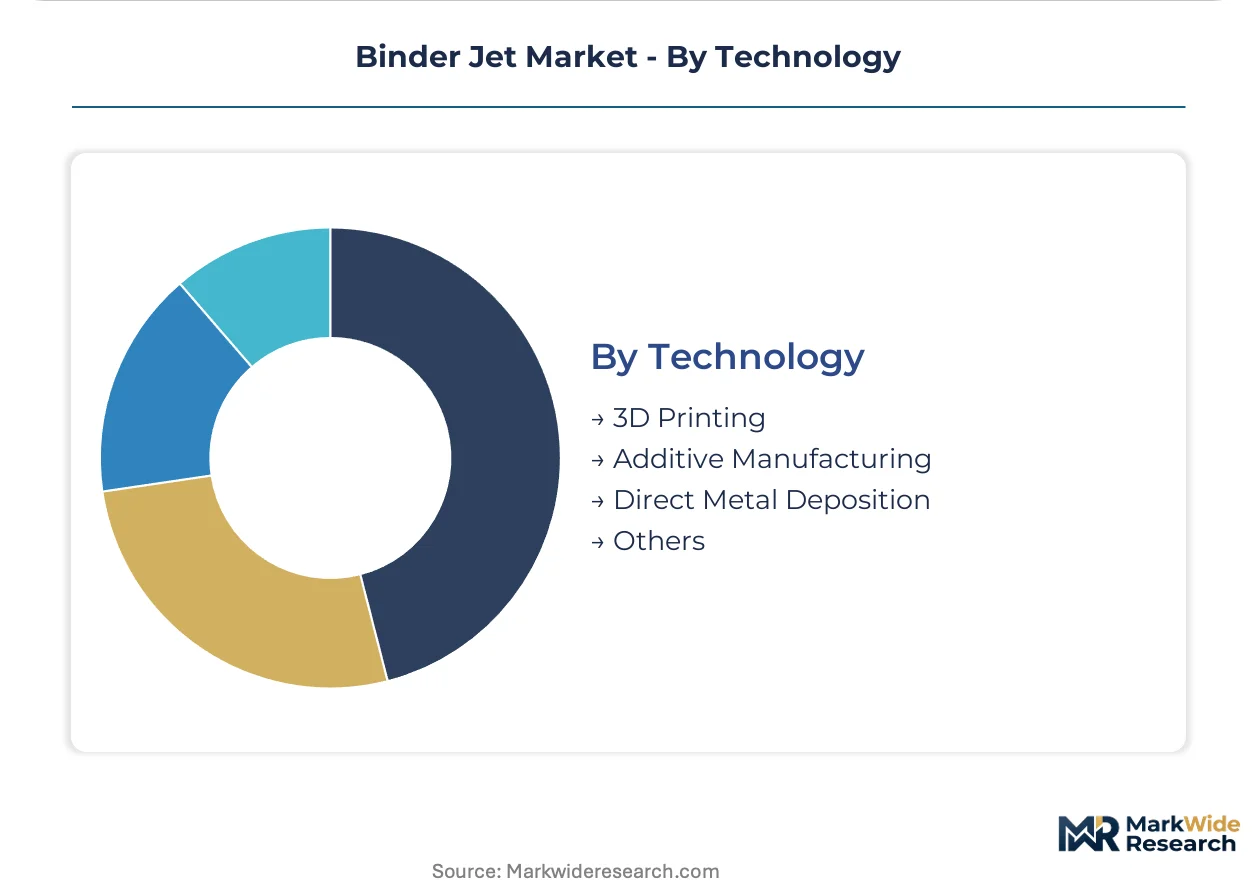
Supply concentration clusters around equipment suppliers bundling simulation software with furnace acquisitions, while deposition modality determines compatibility with multi-material and reactive binder protocols.
- 3D Printing:Layer-wise binder deposition onto powder beds forms green parts for subsequent sintering. Desktop Metal Inc leverages in-house furnace networks to control post-processing economics across stainless steel and tool steel workflows. Multi-material deposition capabilities collapse iteration cycles between green part printing and final dimensions.
- Additive Manufacturing:Production-grade specification tiers for density and surface finish collapse the gap with conventional powder metallurgy. GE Additive dominates aerospace qualification pathways through direct ties to jet engine OEMs. AI-driven shrinkage prediction software now bundles with furnace acquisitions.
- Direct Metal Deposition:Alternative powder delivery mechanisms address repair and cladding applications.
- Others:Emerging modalities including continuous printing and hybrid subtractive-additive systems.
Additive manufacturing leads by installed base. 3D printing with bundled simulation software is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment suppliers and furnace networks cluster in Germany and the United States where automotive and aerospace OEMs operate captive additive manufacturing centers. Foundry demand for printed sand molds concentrates in the American Midwest while medical device qualification pathways tighten across European and North American regulatory jurisdictions.
United States
FAA streamlined certification frameworks accelerate jet engine OEM validation of printed turbine blade geometries. OSHA respirable metal dust exposure limits mandate capital-intensive powder handling infrastructure retrofits. The American Midwest hosts concentrated foundry demand for large-format sand-casting tooling machines.
Germany
Automotive OEMs operate dedicated additive manufacturing centers consolidating stainless steel and tool steel drivetrain workflows. REACH substance restrictions on formaldehyde-based binders force equipment suppliers to validate water-based alternatives. Foundries in Baden-Württemberg and Bavaria eliminate pattern fabrication lead times through printed sand molds.
China
Domestic automotive suppliers pursue cost-competitive sand-casting alternatives for drivetrain components. MIIT advanced manufacturing initiatives support industrialization of metal additive production protocols. Yangtze River Delta manufacturing clusters absorb furnace equipment for ferrous alloy sintering operations.
India
PLI scheme incentives for advanced manufacturing attract tooling investments from global OEMs seeking sand-casting alternatives. The country's national automotive regulator aligns with international vehicle component qualification standards. Domestic foundries in Maharashtra and Gujarat lack large-format machine penetration.
Japan
Precision equipment manufacturers integrate binder jetting workflows for small-batch automotive and electronics tooling. METI industrial technology roadmaps prioritize additive manufacturing standardization. Nagoya-area automotive supplier networks evaluate reactive metal binder chemistries for gear production.
Binder Jet Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the binder jet market. Equipment suppliers bundling simulation software with furnace acquisitions occupy distinct competitive positions from foundry-integrated service providers. Three archetypes dominate: aerospace-qualification specialists, automotive tooling consolidators, and prototyping service bureaus. Strategic moves concentrate on captive furnace network expansion and single-source binder supply agreements.
Among US-based equipment suppliers, Desktop Metal Inc and GE Additive occupy positions representing divergent strategic vectors. Desktop Metal Inc exemplifies the automotive tooling consolidator archetype through in-house furnace network control. GE Additive anchors the aerospace-qualification specialist tier through direct ties to jet engine OEMs. ExOne represents the foundry-integrated service model with large-format machine deployment.
| Leading Market Players |
|---|
| Desktop Metal Inc |
| ExOne |
| GE Additive |
| Voxeljet AG |
| HP Inc |
| 3D Systems, Inc. |
| Proto Labs Inc |
| Renishaw plc |
| Stratasys, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term furnace capacity reservation contracts lock in both sintering throughput access and predictable unit economics for automotive drivetrain suppliers qualifying serial production programs. These structures bind OEMs to dedicated post-processing networks while insulating qualified vendors from spot-market graphite electrode volatility.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European operations, forcing premium validation costs for water-based binder alternatives against legacy formaldehyde formulations. Three-tier pricing structure across aerospace-qualified, automotive-production, and prototyping-service levels separates FAA-certified turbine components from foundry sand-casting tooling. Pricing pressure stems from graphite electrode cost swings destabilizing ferrous alloy sintering economics. Prototyping service bureaus exhibit highest price sensitivity due to minimal furnace infrastructure requirements.
Supply Chain Analysis
Germany and the United States anchor equipment manufacturing and captive furnace network deployment for automotive and aerospace OEMs. Raw material flows draw from specialty graphite electrode producers in China and Japan alongside ferrous powder suppliers in Sweden and North America. Single-source vulnerability concentrates in furnace consumables subject to export licensing. Distribution runs through equipment-integrated binder supply agreements rather than spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket furnace maintenance contracts and sintering process consulting services expand faster than hardware sales as OEMs shift from prototyping to serial production qualification. Recurring revenue from shrinkage compensation software subscriptions and thermal cycle optimization outpaces machine placement growth.
For Market Incumbents: Shield aerospace qualification pathways from laser powder bed fusion substitution by accelerating FAA certification data package completion. Deepen backward integration into reactive metal binder chemistry development to capture margin from automotive drivetrain volume scale. Prioritize captive furnace network expansion in Germany's automotive supplier clusters.
For New Entrants and Emerging Players: Foundry-integrated service gaps in India's domestic supplier base offer white-space entry where PLI scheme incentives attract tooling investments but local machine penetration remains thin. Target Maharashtra and Gujarat sand-casting operations with equipment-leasing bundled to process engineering training. Lead with thermal debinding emission compliance as regulatory pressure intensifies.
For Investors and Strategic Acquirers: Equipment suppliers bundling AI-driven shrinkage prediction software with furnace acquisitions represent the most defensible acquisition archetype as simulation capabilities consolidate procurement decisions. Long-term viability hinges on recurring revenue attachment rates exceeding hardware replacement cycles. Monitor EMA medical device harmonization progress as signal for orthopedic implant qualification volume inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Furnace Network Expansion | Desktop Metal Inc controls post-processing economics across stainless steel workflows through in-house thermal infrastructure. |
| Reactive Metal Binder Chemistry Development | Automotive drivetrain suppliers achieve ten-thousand-unit annual volumes through advanced sintering protocols. |
| AI-Driven Shrinkage Prediction Software Bundling | Equipment vendors collapse iteration cycles between green part printing and final sintered dimensions. |
| Water-Based Binder Validation | European suppliers respond to REACH formaldehyde restrictions with bio-derived alternative qualification. |
| Foundry ERP Integration Restructuring | Pattern-based casting lead time algorithms require fundamental rebuilding for binder jetting workflow scheduling. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foundry operations managers, aerospace qualification engineers, automotive Tier 1 procurement leads, and thermal processing specialists. Secondary validation drew from FAA airworthiness directives, EPA powder handling guidelines, OSHA respirable dust exposure databases, and ISO/ASTM standardization committee proceedings. Bottom-up equipment shipment tracking and top-down OEM capital expenditure analysis were triangulated against sintering furnace installation records.
Across the analysis window, volume and value projections were modeled by binder type, end-use industry, application workflow, and technology modality. CAGRs were derived from regression analysis of qualification timeline compression and furnace throughput scaling. Forecast inputs incorporated graphite electrode price volatility indices and automotive supplier consolidation program mandates.
Underlying assumptions cover sustained FAA pathway streamlining and REACH substance restriction enforcement, with deviation risk concentrated in laser powder bed fusion technology substitution for titanium and nickel superalloy segments. Recalibration cycles align with material shifts in OEM serial production contract awards and EMA medical device harmonization implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Additive Manufacturing Software Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
Additive Manufacturing Platform Market
3D Printing Technology
Global 3D Pens Market
3D Printing Technology
3D Printing Vacuum Furnaces Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
3D Printing Enabled Augmented Manufacturing Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
Selective Laser Sintering Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
Military 3D and 4D Printing Market