
 North America Additive Manufacturing with Metal Powders Market | 2026-2036
North America Additive Manufacturing with Metal Powders Market Size, Share, and Industry Trends Forecast 2026-2036
North America Additive Manufacturing with Metal Powders Market Analysis
Buyer concentration among defense prime contractors is pivoting toward direct metal printing qualification programs. GE Additive leverages its aviation heritage to anchor powder bed fusion supply chains for turbine blades. EOS GmbH sustains technology leadership through tightly controlled process parameter packages. SLM Solutions differentiates via large-format build envelope systems targeting rocket propulsion fabricators.
Additive manufacturing with metal powders encompasses layer-by-layer consolidation of metallic feedstocks using directed energy or binder-based processes, typically achieving near-full density above 99.5% with particle size distributions of 15-45 microns for laser-based systems. Stainless steel dominates current powder shipments due to mature qualification pathways and lower cost per kilogram, while titanium alloys command premium positioning in orthopedic implant and airframe applications where strength-to-weight ratios justify extended certification timelines. Electron beam melting occupies a specialized niche for reactive alloys requiring vacuum environments, whereas selective laser melting captures the broadest end-user footprint across functional prototyping and production tooling.
FAA airworthiness directives and FDA 21 CFR Part 820 quality system regulations govern powder lot traceability and mechanical property validation for flight-critical and implantable components. NIST measurement science programs and ASTM F42 committee standards shape powder characterization protocols that determine supplier market access. Stakeholders must monitor evolving DoD additive manufacturing directives and state-level workforce development investments as determinants of regional production capacity allocation.
Market Dynamics
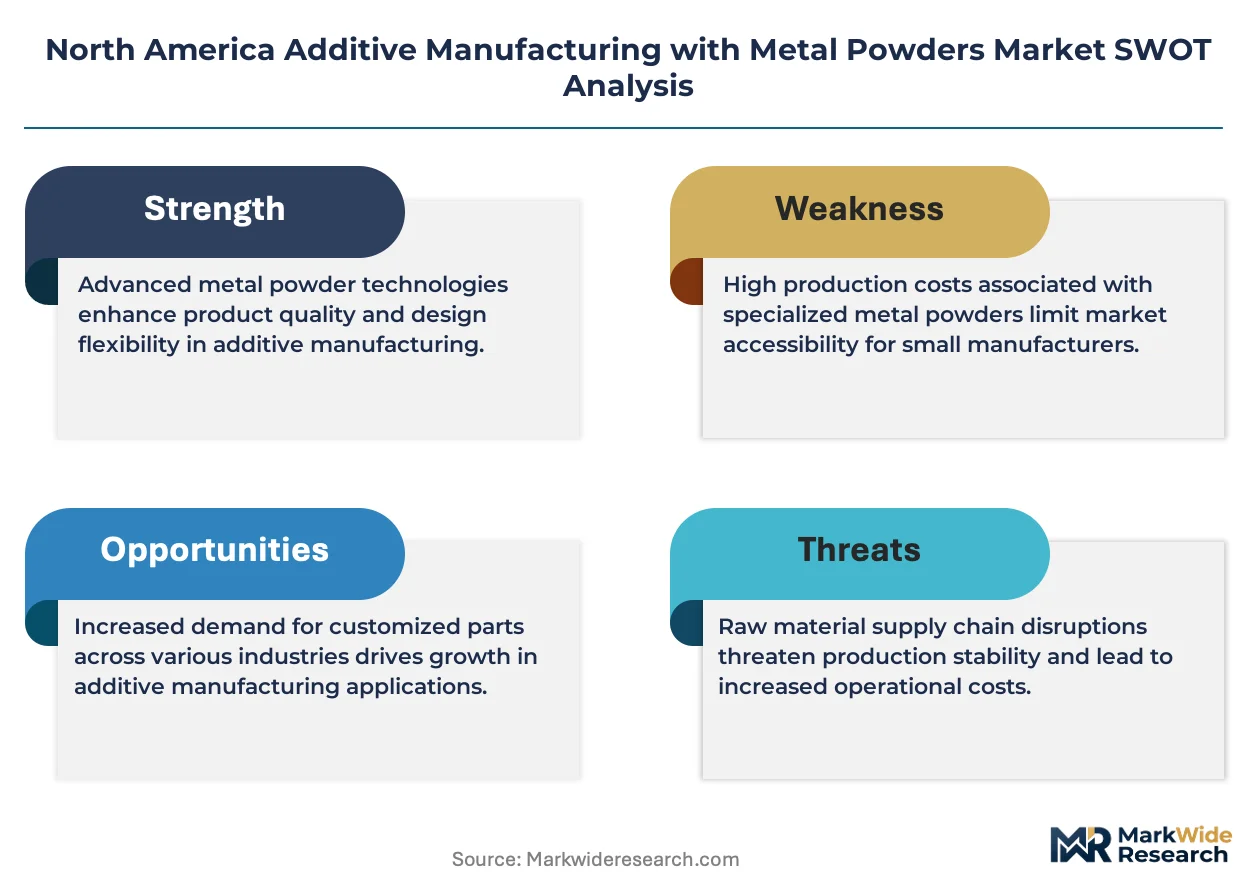
Defense prime contractors are consolidating powder bed fusion qualification programs, forcing tier-two suppliers to absorb extended certification timelines and capital-heavy process validation costs.
Growth Catalysts
- FAA Airworthiness Directives:Mandated powder lot traceability for flight-critical components is accelerating supplier qualification investments across the US Great Lakes corridor.
- Titanium Alloy Adoption:Orthopedic implant manufacturers are expanding laser-based powder bed fusion capacity for patient-specific acetabular cups and spinal cages.
- Directed Energy Deposition:Repair applications for turbine blade tips are displacing conventional welding in US-based MRO facilities.
Market Restraints
- Argon Gas Supply Concentration:Inert gas costs represent 12-18% of total build cost, with regional supply bottlenecks constraining production scaling in the Ohio-Illinois manufacturing belt.
- ASTM F42 Standard Gaps:Incomplete powder recyclability protocols create qualification uncertainty, extending FDA 510(k) review cycles for implantable devices.
- Electron Beam System Costs:Vacuum chamber infrastructure and electron gun maintenance requirements limit adoption to defense-aerospace primes with captive capital pools.
Strategic Opportunities
- Mexico Nearshoring:Querétaro and Baja California aerospace clusters present untapped demand for qualified titanium powder distributors serving tier-one suppliers.
- Multi-Laser Architectures:Convergence of beam steering controls with real-time melt pool monitoring is compressing build times for rocket engine chambers.
- DoD Additive Manufacturing Directives:Pentagon supply chain reshoring mandates are creating dedicated qualification pathways for small-to-mid format system vendors.
Industry Challenges
- Non-Destructive Testing Bottlenecks:Computed tomography inspection capacity lags behind build throughput, creating work-in-process accumulation at US-based job shops.
- Post-Processing Skill Scarcity:Hot isostatic pressing and CNC finishing expertise remains concentrated among legacy forging technicians approaching retirement.
- ERP Integration Friction:Powder traceability requirements conflict with existing aerospace supplier MRP systems, demanding custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Additive Manufacturing with Metal Powders Market |
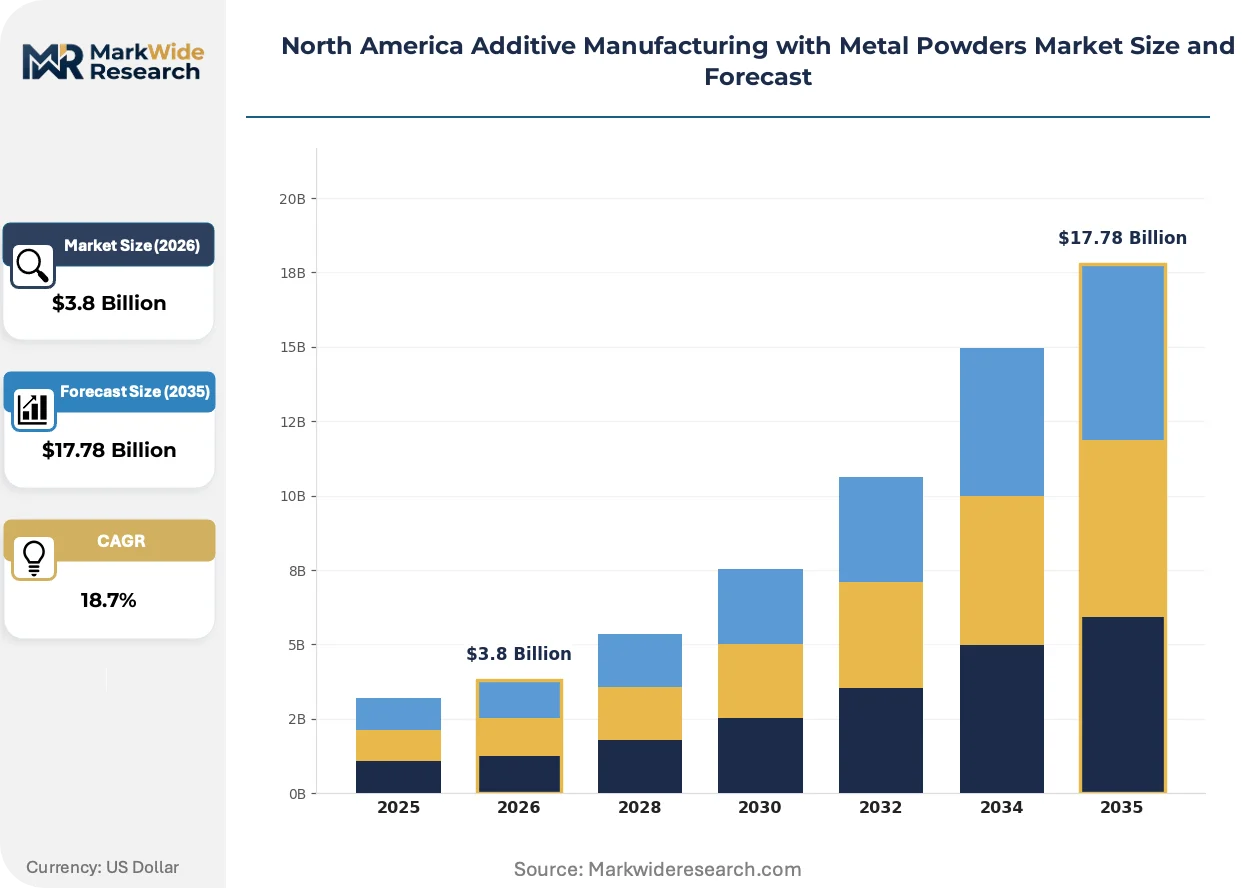
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Titanium Alloys, Aluminum Alloys, Tool Steel Technology: Selective Laser Melting, Electron Beam Melting, Binder Jetting, Hybrid Manufacturing End User: Aerospace, Automotive, Defense, Medical Devices Application: Prototype Development, Tooling, High-Performance Parts, Custom Components |
| Companies Covered | 3D Systems Corporation, EOS GmbH, SLM Solutions, GE Additive, ExOne, Renishaw, Aerojet Rocketdyne, Trumpf, Optomec, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Additive Manufacturing with Metal Powders Market Emerging Trajectories
Process automation and in-situ quality assurance are compressing the gap between prototype validation and production qualification across North American metal powder additive operations.
Artificial intelligence-driven defect detection is automating real-time melt pool classification in multi-laser powder bed fusion systems. Aerospace OEMs in the US Great Lakes region are deploying these architectures for turbine blade production, eliminating post-build radiographic inspection for geometrically simple features. The technology is automating labor-intensive quality gates that previously consumed 30-40% of total production cycle time.
FDA 21 CFR Part 820 quality system regulations are tightening device master record requirements for powder-based implants. The agency's Center for Devices and Radiological Health is demanding particle morphology certificates of analysis tied to specific atomization batches. Orthopedic manufacturers in Indiana and Pennsylvania are responding by backward-integrating into plasma atomization partnerships or captive powder screening operations.
Consignment inventory models are displacing spot purchasing for qualified titanium and nickel superalloy powders. Tier-one rocket propulsion fabricators in Texas and California are forcing distributors to hold 90-120 day safety stocks at regional warehouses, transferring working capital burdens downstream. This pattern is most visible in Space Coast adjacent suppliers serving reusable launch vehicle programs.
North America Additive Manufacturing with Metal Powders Market Segmentation
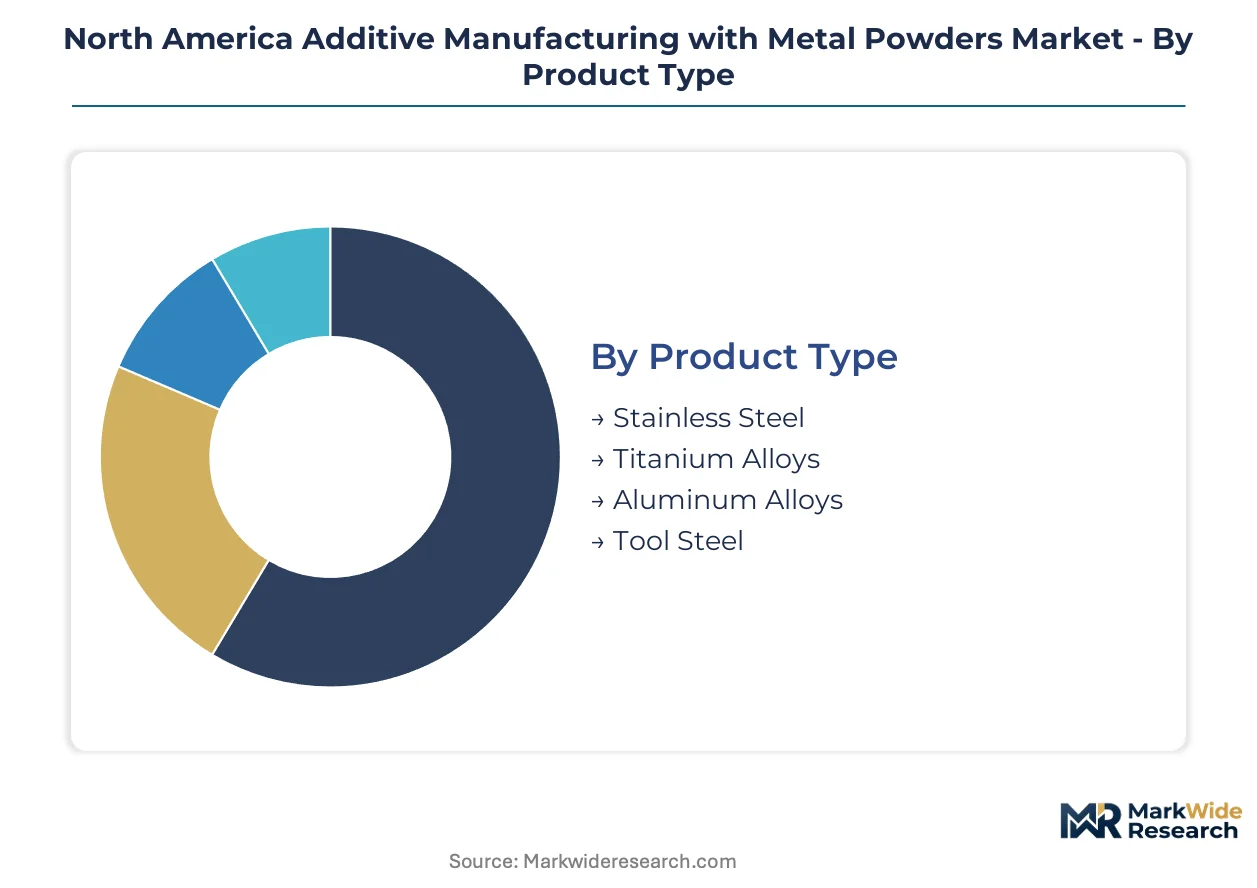
Metal powder additive manufacturing segments diverge sharply between high-volume commodity grades and premium-certified alloys. Each dimension—material chemistry, consolidation mechanism, end-use qualification, and functional application—carries distinct margin structures and certification barriers that reshape supplier positioning across the US Great Lakes and Southwest industrial corridors.
Product Type:
Volume shipments concentrate in cost-optimized grades serving industrial tooling and general fabrication, while premium alloys command extended qualification timelines for flight-critical and implantable applications.
- Stainless Steel:Austenitic grades dominate current powder tonnage due to mature atomization supply chains and established FDA 510(k) qualification pathways for surgical instruments. Ohio and Illinois job shops consume bulk shipments for production tooling and functional prototypes where corrosion resistance requirements align with cost-sensitive procurement.
- Titanium Alloys:Ti-6Al-4V and Ti-6Al-4V ELI grades anchor orthopedic implant and airframe component production, with plasma atomization batches requiring particle morphology certificates tied to specific melt lots. Michigan and Indiana manufacturers are backward-integrating into captive powder screening to satisfy FDA device center master record requirements.
- Aluminum Alloys:AlSi10Mg serves automotive lightweighting programs in the Detroit metro corridor, though powder handling challenges limit adoption outside controlled atmosphere facilities.
- Tool Steel:H13 and M2 grades target injection mold inserts and die casting tooling, with demand clustering among Chicago-area contract manufacturers serving tier-two automotive suppliers.
Today's leader: Stainless Steel. Tomorrow's challenger: Titanium Alloys.
Technology:
Process selection tracks capital availability and atmospheric requirements, with laser-based systems capturing broad adoption while electron beam and hybrid architectures occupy specialized niches.
- Selective Laser Melting:Multi-laser architectures with real-time melt pool monitoring now dominate functional prototyping and production tooling across the US Great Lakes region. Aerospace OEMs in Ohio deploy these systems for turbine blade fabrication, compressing build times through automated defect detection that eliminates post-process radiographic inspection for geometrically simple features.
- Electron Beam Melting:Vacuum chamber processing of reactive titanium and nickel superalloys serves defense-aerospace primes with captive capital pools, limiting adoption to Texas and California rocket propulsion fabricators.
- Binder Jetting:Green part sintering enables stainless steel production without inert gas consumption, attracting cost-focused job shops in Pennsylvania facing argon supply bottlenecks.
- Hybrid Manufacturing:Directed energy deposition integrated with CNC finishing addresses turbine blade tip repair applications, displacing conventional welding at US-based MRO facilities.
Selective Laser Melting anchors current capacity expansion. Binder Jetting gains share fastest among price-sensitive tooling segments.
End User:
Customer concentration varies from fragmented medical device procurement to consolidated defense prime contracting, with qualification requirements determining supplier market access.
- Aerospace:FAA airworthiness directives mandate powder lot traceability for flight-critical components, accelerating supplier qualification investments across Ohio, Michigan, and Illinois. GE Additive anchors regional supply chains for turbine blade production.
- Automotive:Detroit-area OEMs leverage aluminum alloy printing for powertrain prototyping, though production volumes remain constrained by build speed economics versus conventional casting.
- Defense:Pentagon supply chain reshoring mandates under DoD additive manufacturing directives create dedicated qualification pathways for small-to-mid format system vendors serving prime contractors.
- Medical Devices:FDA 21 CFR Part 820 quality system regulations tighten device master record requirements, with orthopedic manufacturers in Indiana and Pennsylvania demanding particle morphology certificates of analysis tied to specific atomization batches.
Aerospace commands premium positioning. Medical Devices climbs fastest as patient-specific implant adoption accelerates.
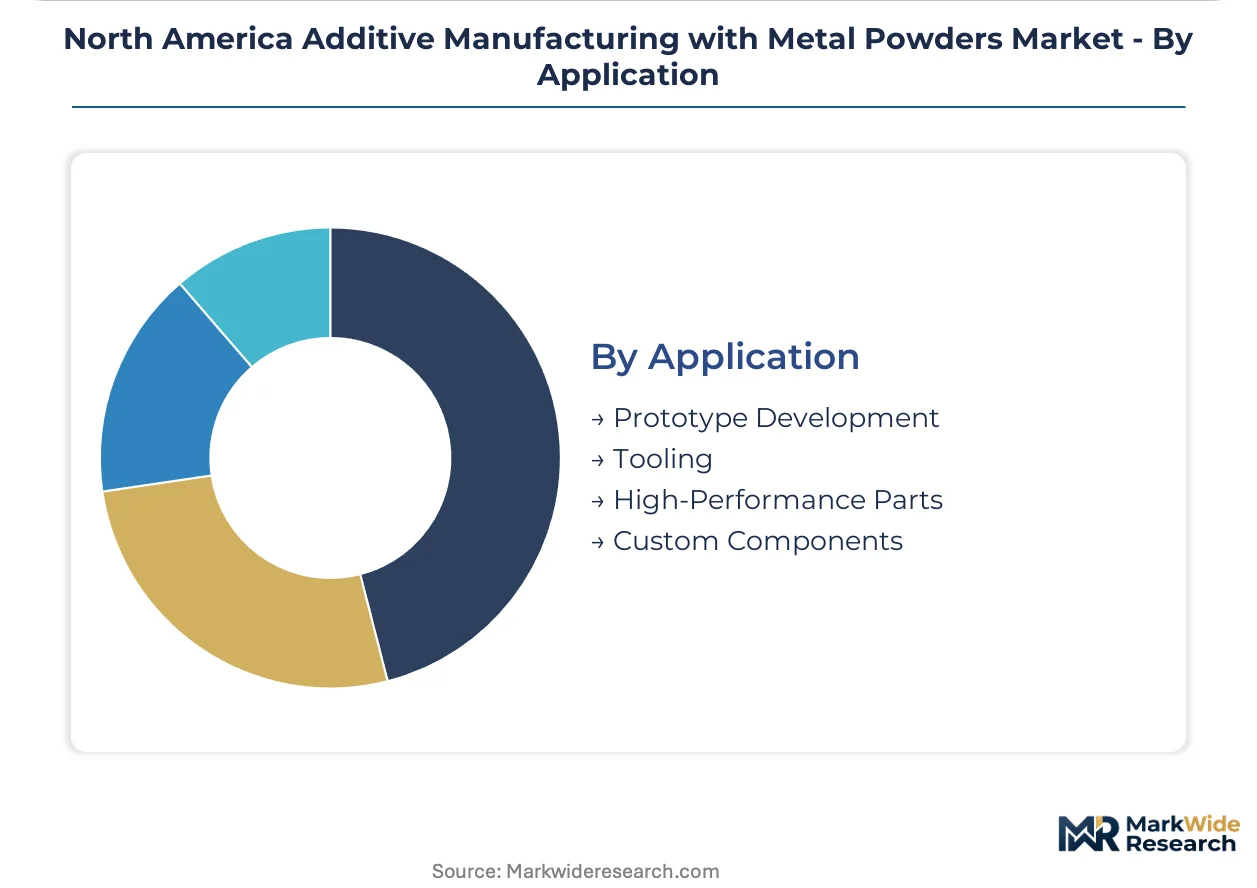
Application:
Functional use cases span the qualification spectrum from disposable prototypes to flight-critical production hardware, with margin profiles inversely correlated to certification burden.
- Prototype Development:Rapid design iteration for automotive and consumer electronics housings dominates early-stage adoption, with Chicago and Detroit service bureaus competing on turnaround speed rather than material certification depth.
- Tooling:Conformal cooling channels in injection mold inserts deliver cycle time reductions that justify stainless steel and tool steel powder costs for Ohio plastics processors.
- High-Performance Parts:Rocket engine chambers and turbine blades require titanium and nickel superalloy processing under FAA or DoD qualification protocols, with Texas and California fabricators forcing 90-120 day consignment inventory terms onto distributors.
- Custom Components:Patient-specific acetabular cups and spinal cages drive titanium alloy demand among Indiana and Pennsylvania orthopedic manufacturers responding to surgeon-specific implant requests.
Tooling generates current volume. High-Performance Parts exhibits the steepest expansion trajectory as reusable launch vehicle programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled technician concentrations in the US Great Lakes industrial corridor anchor North American metal powder additive manufacturing capacity, with specialized welding and CNC finishing expertise migrating toward laser-based powder bed fusion operations.
United States
Defense prime contractors and orthopedic implant manufacturers drive titanium alloy powder demand across Ohio, Michigan, and Illinois. FAA airworthiness directives mandate powder lot traceability for flight-critical turbine blades, accelerating supplier qualification investments. Cleveland and Cincinnati aerospace clusters host GE Additive operations anchoring regional supply chains for aviation components.
Canada
Ontario-based job shops leverage stainless steel powder bed fusion for automotive tooling and general fabrication applications. Health Canada device regulations align with FDA quality system frameworks, easing cross-border qualification for implantable component suppliers. Toronto-Waterloo corridor additive manufacturing centers concentrate on medical device prototyping and small-batch production.
Mexico
Querétaro and Baja California aerospace clusters generate untapped demand for qualified titanium powder distributors serving tier-one suppliers. Mexican federal manufacturing incentives under the IMMEX program reduce import friction for US-sourced atomized powders. Monterrey industrial parks attract captive powder screening operations from Indiana-based orthopedic manufacturers seeking tariff-advantaged production.
North America Additive Manufacturing with Metal Powders Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across North American metal powder additive manufacturing, creating a tiered structure where aviation heritage and captive capital pools determine market access. The vendor landscape concentrates around three strategic archetypes: diversified industrial conglomerates with vertical aerospace supply chains, German-engineered precision equipment specialists, and venture-backed rocket propulsion fabricators. Dominant competitive moves include backward integration into plasma atomization partnerships and multi-laser architecture capacity expansions targeting rocket engine chamber production.
Within the aviation-heritage tier, GE Additive exemplifies conglomerate leverage of turbine blade production expertise into powder bed fusion supply chain anchoring. EOS GmbH and SLM Solutions occupy positions as German-engineered equipment specialists, with the former representing tightly controlled process parameter packaging and the latter exemplifying large-format build envelope differentiation for rocket propulsion applications.
| Leading Market Players |
|---|
| 3D Systems Corporation |
| EOS GmbH |
| SLM Solutions |
| GE Additive |
| ExOne |
| Renishaw |
| Aerojet Rocketdyne |
| Trumpf |
| Optomec |
| Others |
Supply Flow & Price Mechanics
Multi-laser powder bed fusion adoption across Ohio and Michigan job shops is compressing build economics while concentrating qualified powder demand among fewer distributors with captive screening capabilities. This technology shift simultaneously raises equipment capital barriers for tier-two suppliers and transfers working capital burdens downstream through consignment inventory mandates.
Pricing Analysis
Equipment-plus-consumables bundling dominates procurement for aerospace and medical device OEMs, while spot powder purchasing persists among general fabrication shops. Price differentiation rests on FDA 510(k) certification tier and lot-specific particle morphology documentation. Cost compression in stainless steel tooling grades is intensifying as binder jetting alternatives eliminate inert gas requirements. General fabrication shops exhibit highest price sensitivity; orthopedic implant manufacturers accept premium positioning for ELI-grade titanium with full traceability.
Supply Chain Analysis
Skilled technician scarcity in the US Great Lakes corridor constrains post-processing capacity expansion despite build throughput gains. Plasma atomization feedstock concentrates in the United States, Canada, and select European suppliers with NIST-traceable characterization protocols. Argon gas supply draws from regional industrial gas distributors with single-source vulnerability during peak aerospace production cycles. Distribution runs through qualified distributor networks holding consignment inventory at regional warehouses adjacent to Ohio, Texas, and California manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FAA airworthiness directives and FDA quality system mandates continuously elevate qualification barriers that protect incumbent positions while creating dedicated entry pathways for certified specialists.
For Market Incumbents: Cement powder bed fusion supply chain anchoring through captive plasma atomization partnerships or backward integration into screening operations. Expand multi-laser capacity in the US Great Lakes corridor to capture rocket propulsion fabrication demand. Defend against binder jetting displacement in tooling segments by emphasizing as-built density guarantees and fatigue performance documentation. For New Entrants and Emerging Players: Binder jetting system architectures for stainless steel production tooling offer the most penetrable wedge against laser-based incumbent dominance. Target Pennsylvania and Ohio job shops facing argon supply bottlenecks and cost pressure. Pursue equipment-leasing models with powder consignment arrangements to bypass capital barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional powder distributors with captive screening capabilities and established FDA master file access. Long-term viability favors specialists with dual aerospace-medical certification rather than undifferentiated job shop operators. Monitor DoD additive manufacturing directive implementation pace as inflection indicator for defense-qualified small-format system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Atomization Partnership | Secures particle morphology control for FDA device center compliance. |
| Multi-Laser Capacity Expansion | Compresses build times for GE Additive turbine blade supply contracts. |
| Consignment Inventory Program | Transfers working capital burden to distributors serving Space Coast fabricators. |
| Post-Processing Skill Acquisition | Addresses hot isostatic pressing technician retirement waves in Michigan. |
| ERP Middleware Development | Resolves powder traceability conflicts with legacy aerospace MRP systems. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with powder metallurgy engineers, aerospace procurement managers, orthopedic device regulatory affairs leads, and job shop operations directors with secondary validation against FAA airworthiness directives, FDA 510(k) clearance databases, ASTM F42 committee standards, and NIST measurement science program publications. Bottom-up build volume estimates triangulated against top-down powder shipment tonnage reported by plasma atomization suppliers.
Segment-weighting applied material chemistry, consolidation technology, end-use qualification tier, and functional application as core dimensions across the projection horizon. CAGRs derived from curve-fitting historical qualification timeline compression and forward-projecting DoD supply chain reshoring mandate implementation. Industry-specific inputs incorporated electron beam system maintenance cost trajectories and real-time melt pool monitoring adoption rates among US Great Lakes aerospace OEMs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ASTM F42 standard completion timelines and argon supply infrastructure investments. Forecasts reflect documented assumptions regarding FAA rulemaking pace and FDA device center inspection prioritization. Practitioners should monitor Pentagon additive manufacturing directive funding allocations and Ohio-Illinois workforce development program enrollment for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
US Additive Manufacturing Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
Global 4D Printing in Healthcare Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
3D Printing Robots Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
Metal 3D Printing Service Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Additive Manufacturing Platform Market