
 3D Printing Pellet Extruder Market | 2026-2036
3D Printing Pellet Extruder Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Pellet Extruder Market Insights
Aftermarket service revenue is reshaping competitive economics in the 3D Printing Pellet Extruder Market as hardware margins compress and vendors chase recurring income. CEAD leverages its large-format installed base to anchor service contracts across European industrial sites. Titan Robotics competes on open-platform architectures that reduce customer lock-in. Dyze Design specializes in compact pellet feeding systems for retrofitting existing gantry printers.
A 3D printing pellet extruder is a material delivery device that melts thermoplastic granules—typically ABS, PLA, PETG, or reinforced composites—and deposits them through a heated nozzle at controlled flow rates, enabling additive manufacturing without filament conversion. The system operates at throughput rates measured in kilograms per hour, far exceeding conventional filament extruders, and serves industrial applications requiring large-scale or cost-efficient part production. Twin screw extruder configurations command the strongest margin pools due to superior mixing capability for fiber-reinforced and multi-material compounds. Industrial Production applications lead volume uptake as manufacturers replace CNC machining for low-volume tooling and fixtures. Fused Deposition Modeling technology dominates the pellet extrusion landscape because its open-source motion control architecture readily accommodates granular feedstock adaptations.
FDA device manufacturing guidelines and EU REACH chemical registration requirements jointly elevate material certification burdens for pellet extruder vendors serving medical and aerospace end users. ISO 9001 quality management and AS9100 aerospace standards further gate market access for suppliers targeting regulated industries. Stakeholders must monitor evolving EPA emissions rules for polymer processing equipment and assess whether in-house compounding capabilities justify the capital intensity of multi-screw systems versus outsourced pellet supply.
Market Dynamics
Pellet extrusion systems are compressing the cost structure of large-format additive manufacturing, forcing incumbent filament suppliers to defend position through material certification rather than feedstock economics alone.
Growth Catalysts
- REACH material traceability mandates:European chemical registration requirements are accelerating pellet extruder adoption as manufacturers seek direct polymer sourcing with documented supply chains.
- Aerospace tooling replacement cycles:Boeing and Airbus tier suppliers are qualifying pellet-fed systems for flight-certified jigs and fixtures, bypassing filament inventory costs.
- Stuttgart-Munich industrial cluster concentration:Germany's automotive belt is piloting pellet extrusion for injection mold tooling, creating demonstration effects for machinery OEMs across Central Europe.
Market Restraints
- Polymer feedstock price volatility:ABS and glass-filled nylon pellet costs fluctuate with crude oil derivatives, compressing margin predictability for job shops operating on fixed-price contracts.
- Single-screw mixing limitations:Conventional extruder geometries cannot achieve fiber dispersion uniformity above 30% loading, restricting high-performance composite applications.
- Capital intensity barriers:Twin-screw industrial systems require facility upgrades for three-phase power and fume extraction that small-to-mid manufacturers cannot absorb.
Strategic Opportunities
- India PLI scheme alignment:Domestic medical device manufacturing incentives are creating entry points for pellet extruder vendors serving orthopedic implant tooling.
- Marine salvage and repair:Shipyards in Greece and Norway are exploring on-demand pellet printing for propeller blade repair, eliminating casting lead times.
- Closed-loop recycling integration:Convergence of shredder-extruder hybrid systems with post-industrial waste streams is enabling circular production models for automotive interior components.
Industry Challenges
- AS9100 certification timelines:Aerospace suppliers face 18-24 month qualification periods for pellet-printed flight hardware, delaying revenue recognition.
- Thermal process control expertise gaps:Operators trained on filament systems lack competency in melt rheology tuning for variable pellet geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Pellet Extruder Market |
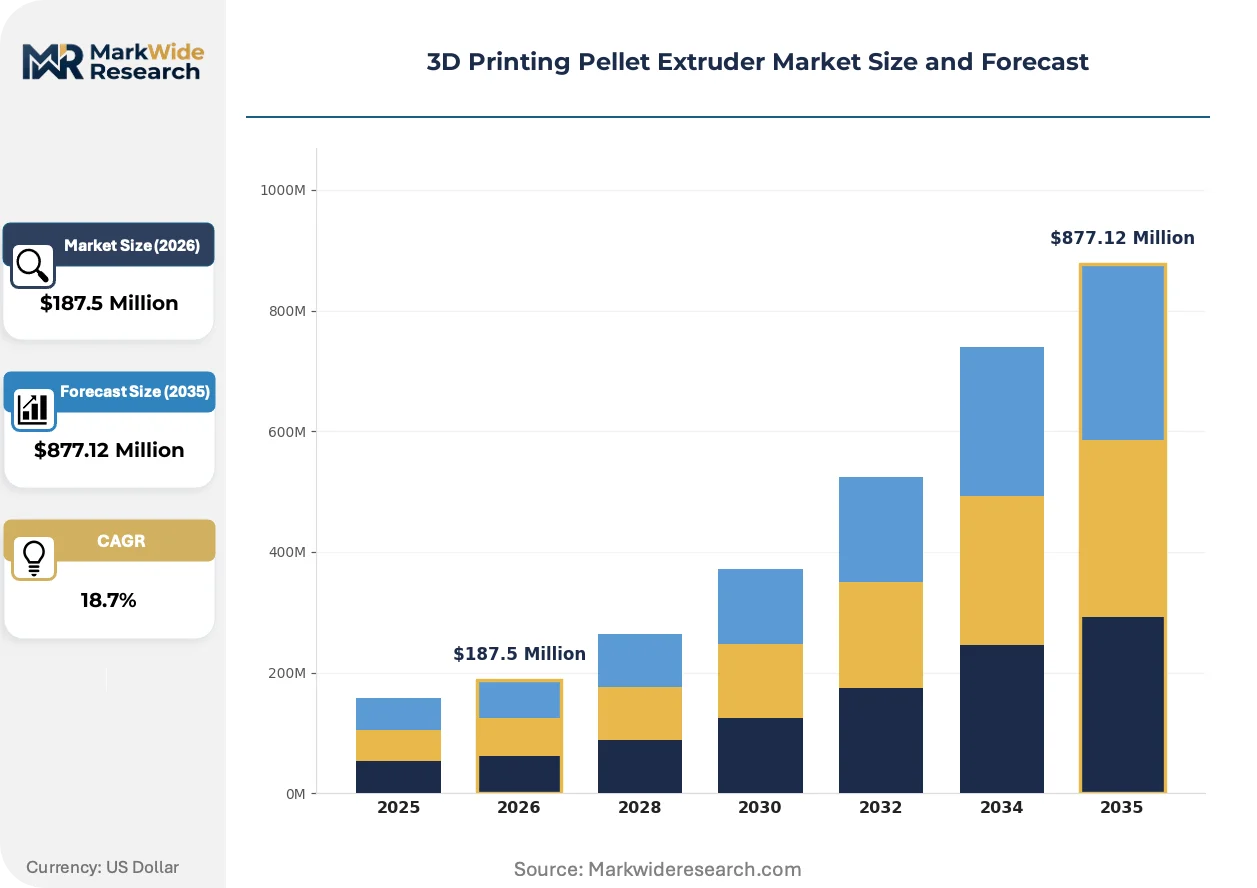
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $877.12 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Screw, Twin Screw, Multi-Screw, Specialty Extruder Application: Prototyping, Industrial Production, Educational Use, Medical Devices End User: Aerospace, Automotive, Consumer Goods, Medical Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Powder Bed Fusion |
| Companies Covered | Dyze Design, Pollen AM, Direct3D, CEAD, Titan Robotics, Shenzhen KINGS 3D Printing, Re3D, Arburg, Imai Intelligent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Pellet Extruder Market Trends and Innovations
Hardware commoditization is redirecting vendor investment toward software-defined process control and predictive maintenance platforms that lock in recurring revenue.
Continuous pellet feeding mechanisms with gravimetric loss-in-weight control are rendering obsolete batch hopper systems that require manual refill cycles. Medical device contract manufacturers in Ireland and Switzerland are adopting these systems for overnight unmanned production runs. The shift is compressing equipment utilization metrics and forcing smaller vendors to license control algorithms rather than develop proprietary firmware.
EU MDR medical device regulation is tightening biocompatibility documentation requirements for patient-contacting printed components. Pellet extruder operators must now maintain lot-level resin certificates that filament distributors previously consolidated. German and French orthopedic implant suppliers are responding by qualifying single-source polymer compounders with dedicated medical grades.
Service contract unbundling is fragmenting the traditional hardware-plus-support bundle. Automotive tooling buyers in Michigan and Bavaria now procure extruder maintenance through third-party industrial service networks rather than OEM channels. The disintermediation is most pronounced among mid-volume manufacturers operating 3-5 year equipment refresh cycles who prioritize local technician response times over brand loyalty.
3D Printing Pellet Extruder Market Segmentation
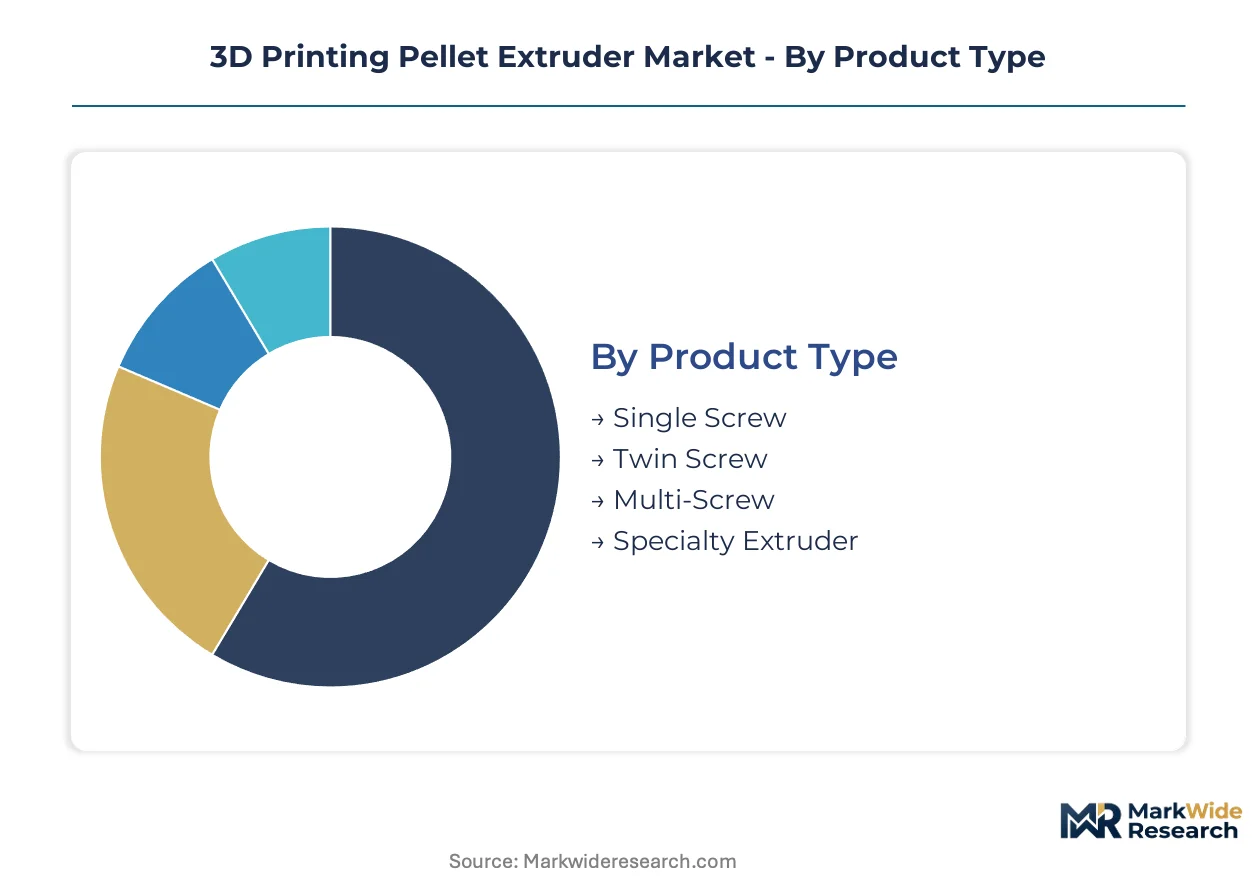
Pellet extruder segmentation reveals how hardware architecture, application intensity, and end-user compliance requirements create divergent margin profiles across the additive manufacturing value chain. Understanding these fault lines exposes where capital deployment concentrates and where technology gaps persist.
Product Type:
Cost tier differentiation separates entry-level single-screw units from precision twin-screw systems commanding premium pricing for fiber-reinforced compounding.
- Single Screw:Simple auger-driven designs with fixed compression ratios suit commodity thermoplastics like ABS and PLA. Automotive job shops in Michigan and Bavaria deploy these for non-critical tooling where throughput outweighs mixing precision.
- Twin Screw:Intermeshing co-rotating screws achieve distributive and dispersive mixing for glass-filled nylon and carbon fiber compounds. Aerospace tier suppliers around Toulouse and Hamburg qualify these systems for flight-certified jigs requiring batch-to-batch consistency.
- Multi-Screw:Triple and quadruple configurations enable continuous compounding of multi-material gradients for functional prototyping.
- Specialty Extruder:Custom geometries address ceramic-loaded and metal-polymer hybrid feedstocks for dental and orthopedic applications.
Twin Screw commands the established base. The steepest expansion runs through Specialty Extruder configurations serving medical device contract manufacturers.
Application:
Volume intensity and part qualification requirements create four distinct demand profiles with divergent equipment specifications and service contract structures.
- Industrial Production:Continuous operation modes with automated pellet feeding and fume extraction integration dominate automotive and aerospace tooling replacement. Tier suppliers in Stuttgart's industrial cluster run these systems at utilization rates exceeding filament-based alternatives.
- Medical Devices:ISO 13485-compliant installations with lot-level resin traceability serve orthopedic implant tooling and surgical guide fabrication. Swiss and Irish contract manufacturers drive specification intensity here.
- Prototyping:Lower-duty-cycle systems prioritize material flexibility over throughput for design validation workflows.
- Educational Use:Universities and technical institutes deploy simplified units for workforce training in polymer processing fundamentals.
Industrial Production anchors revenue concentration. Medical Devices is climbing the fastest as EU MDR documentation requirements tighten.
End User:
Customer type determines certification burden, procurement cycle length, and whether equipment purchases flow through capital expenditure or operating lease structures.
- Aerospace:AS9100 quality mandates and 18-24 month qualification timelines for flight hardware create vendor stickiness. Tier suppliers to Boeing and Airbus prioritize twin-screw systems with documented process parameter libraries.
- Automotive:Tooling refresh cycles and closed-loop recycling initiatives drive demand in Germany's automotive belt and Michigan's manufacturing corridor.
- Medical:FDA 510(k) and EU MDR pathways elevate material biocompatibility documentation requirements.
- Consumer Goods:Packaging and appliance manufacturers pursue pellet extrusion for mold tooling cost reduction.
Automotive holds the largest installed base. Aerospace is gaining share fastest as flight-certified additive manufacturing expands.
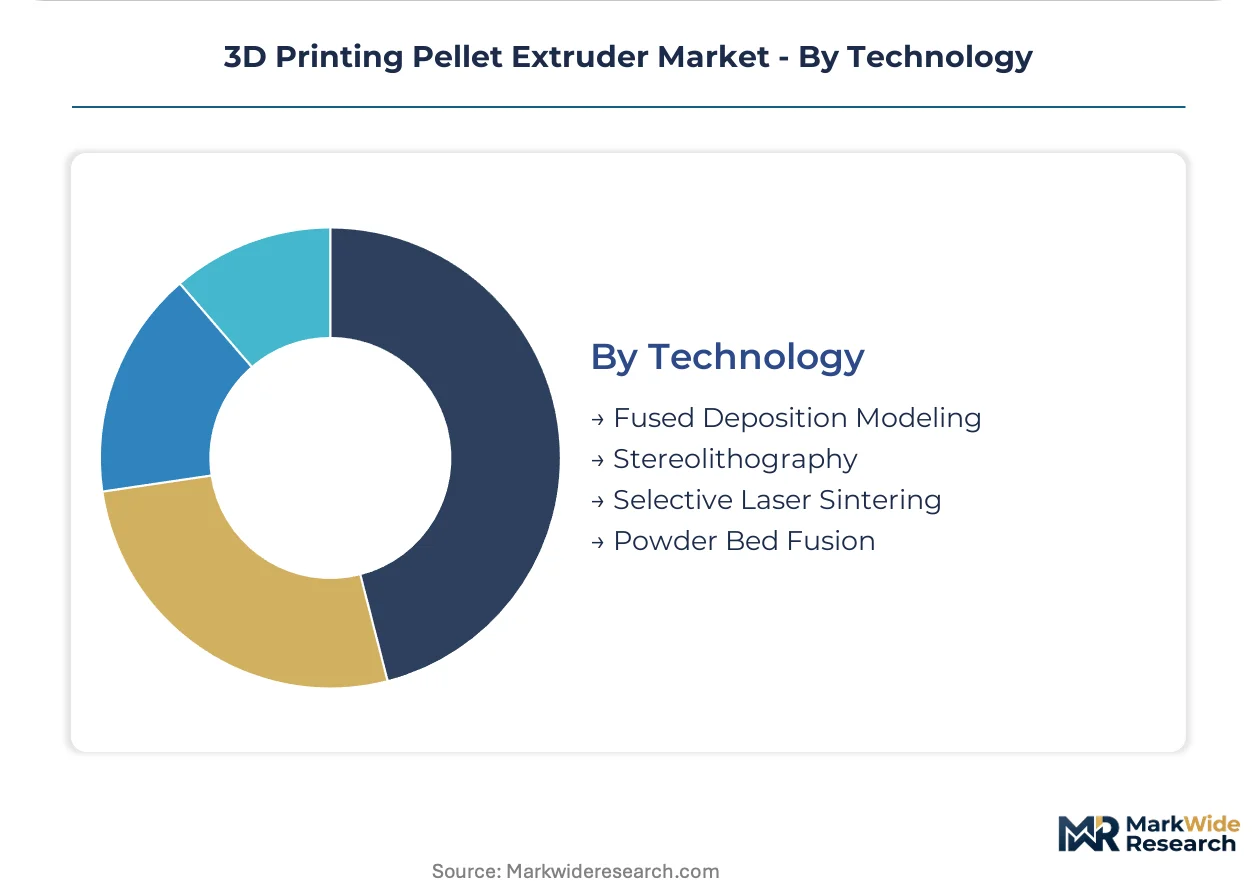
Technology:
Maturity and open-source accessibility determine how readily pellet feedstock adaptations integrate with existing motion control architectures.
- Fused Deposition Modeling:Open-source G-code compatibility and proven gantry systems enable straightforward pellet extruder retrofit. This technology dominates current installations across industrial, educational, and prototyping environments.
- Stereolithography:Photopolymer resin systems have limited pellet analogs, constraining adoption to experimental ceramic-loaded suspensions.
- Selective Laser Sintering:Powder bed processes operate on fundamentally different material delivery mechanisms with no direct pellet pathway.
- Powder Bed Fusion:Metal and polymer powder systems remain incompatible with thermoplastic pellet feedstocks.
Fused Deposition Modeling represents the dominant trajectory. The remaining technologies show minimal pellet adaptation potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Job shops in North America absorb capital intensity more readily than European mid-tier manufacturers facing REACH compliance costs. Asian markets prioritize retrofit economics over greenfield installations.
United States
Michigan's automotive tooling corridor and Greater Boston's medical device cluster drive twin-screw system demand. FDA 510(k) pathways for 3D-printed surgical guides elevate material traceability requirements. Boeing tier suppliers in Washington State qualify pellet-fed jigs for flight hardware production.
Germany
Stuttgart-Munich industrial belt pilots closed-loop recycling for automotive interior components. EU REACH chemical registration mandates direct polymer sourcing with documented supply chains. Arburg and other machinery OEMs anchor equipment supply from Baden-Württemberg.
China
Shenzhen and Dongguan electronics manufacturers adopt pellet extrusion for mold tooling cost reduction. MIIT industrial upgrade subsidies accelerate large-format additive manufacturing adoption. Yangtze River Delta job shops prioritize retrofit systems over greenfield capacity.
India
PLI scheme incentives for domestic medical device manufacturing create entry points for orthopedic implant tooling suppliers. CDSCO regulatory alignment with FDA streamlines qualification timelines. Maharashtra and Gujarat pharmaceutical clusters pilot pellet-fed surgical guide production.
Switzerland
Swissmedic oversight tightens biocompatibility documentation for patient-contacting printed components. Zurich and Geneva orthopedic contract manufacturers drive specification intensity for medical-grade systems. Precision engineering heritage favors gravimetric loss-in-weight feeding mechanisms.
3D Printing Pellet Extruder Market Competitive Landscape
Large-format system builders and compact retrofit specialists split the market into divergent margin pools. Hardware commoditization compresses upfront equipment pricing while service contracts and software subscriptions capture recurring revenue. Three archetypes dominate: European industrial machinery incumbents with aerospace certification libraries, North American open-platform challengers reducing customer lock-in, and Asian cost-optimized fabricators serving price-sensitive job shops. Competitive moves concentrate on strategic partnerships for polymer compounder qualification and geographic expansion through third-party service networks.
Within the European industrial tier, CEAD and Arburg occupy positions anchored by large-format installed bases and documented process parameter libraries. Titan Robotics exemplifies the North American open-platform approach. Dyze Design represents the compact retrofit specialization serving gantry printer conversions.
| Leading Market Players |
|---|
| Dyze Design |
| Pollen AM |
| Direct3D |
| CEAD |
| Titan Robotics |
| Shenzhen KINGS 3D Printing |
| Re3D |
| Arburg |
| Imai Intelligent |
| Others |
Pricing and Supply Chain Analysis
German machinery OEMs around Stuttgart anchor twin-screw extruder supply, concentrating margin capture in precision compounding tiers while single-screw commoditization erodes pricing power at the entry level. Polymer feedstock volatility and REACH compliance costs reshape how buyers evaluate total cost of ownership across equipment lifecycles.
Pricing Analysis
Service contract revenue now drives lifetime value as hardware margins compress across all tiers. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified aerospace systems from automotive job shop units and educational retrofit kits. Price differentiation rests on certification grade and after-sales bundling intensity. Cost compression in the single-screw tier is intensifying because Asian fabricators flood job shop segments with unbundled equipment. Automotive tooling buyers in Michigan and Bavaria exhibit highest price sensitivity, while Swiss orthopedic contract manufacturers prioritize specification compliance over upfront cost.
Supply Chain Analysis
Thermoplastic pellet feedstock draws from petrochemical complexes in Germany, China, and the US Gulf Coast. Precision screw elements and heated nozzle assemblies source from Swiss machining houses and Japanese ceramic suppliers. Single-source vulnerability concentrates in medical-grade polymer compounders qualified under EU MDR. Distribution runs through machinery OEM direct sales for large-format systems and third-party industrial distributors for retrofit components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers, geographic clusters, and application intensity creates niche entry points for specialists. The shift toward closed-loop recycling and on-demand marine repair fragments demand into discrete capability requirements that favor targeted positioning over broad coverage.
For Market Incumbents: Entrench position through captive control over medical-grade polymer compounder partnerships and AS9100 process parameter libraries. CEAD and Arburg must deepen firmware-based service lock-in before open-platform challengers erode maintenance contract attachment rates. Priority levers include backward integration into gravimetric feeding mechanism production and qualification support services for aerospace tier suppliers. For New Entrants and Emerging Players: Establish a beachhead in marine salvage applications around Greek and Norwegian shipyards where casting lead time elimination commands premium pricing. Target India's PLI-backed orthopedic implant tooling corridor before domestic compounders achieve FDA alignment. Position through shredder-extruder hybrid systems that enable circular production models for automotive interior waste streams. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with documented medical certification pathways and installed bases in Switzerland's orthopedic contract manufacturing cluster. Long-term viability hinges on software-defined process control differentiation rather than hardware scale. Watch for inflection when EU MDR lot-level documentation requirements trigger consolidation among undercapitalized filament distributors attempting pellet conversion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | CEAD and Arburg secure supply chain control over REACH-compliant medical grades. |
| Software-Defined Process Control Licensing | Titan Robotics reduces customer lock-in while capturing recurring firmware revenue. |
| Medical Device Certification Pathway Investment | Dyze Design targets Swiss orthopedic contract manufacturers with ISO 13485-aligned retrofits. |
| Closed-Loop Recycling System Development | Stuttgart-Munich automotive belt pilots shredder-extruder hybrids for interior component waste. |
| Third-Party Service Network Expansion | Mid-volume manufacturers in Michigan and Bavaria disintermediate OEM maintenance channels. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with pellet extruder OEM product managers, aerospace tier supplier manufacturing engineers, medical device contract manufacturing quality directors, and automotive tooling procurement leads; and secondary validation against ECHA REACH registration databases, FDA 510(k) device filings, SEC 10-K machinery disclosures, and German customs trade statistics for polymer processing equipment. Bottom-up equipment shipment triangulation against top-down addressable market sizing anchored volume estimates.
Forecast inputs considered screw configuration tier, end-use industry certification burden, regional regulatory cluster stringency, and technology adaptation maturity across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro manufacturing investment cycles. Industry-specific inputs included aerospace tooling replacement cycle timing and EU MDR implementation phase impacts on medical-grade system demand.
Macroeconomic conditions sit as an overlay; deviation in crude oil derivative pricing and central European manufacturing investment sentiment would shift the trajectory. Forecasts assume stable REACH enforcement intensity and continued FDA alignment with EU MDR documentation standards. Cross-checking against VDMA plastics machinery order intake data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
Global 4D Printing in Healthcare Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
Digital 3D Printing Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
Desktop 3D Printing Market
3D Printing Technology
Military 3D and 4D Printing Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
3D Printing Enabled Augmented Manufacturing Market
3D Printing Technology
Conventional and Rapid Prototyping Market