
 Global 3D Printed Electronics Market | 2026-2036
Global 3D Printed Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Printed Electronics Market Analysis
Asset-light contract manufacturing and equipment-leasing programs is reconfiguring competitive entry barriers for mid-scale electronics producers. Nano Dimension Ltd. leverages direct-write deposition systems to anchor premium circuit board production for defense and satellite clients. Optomec Inc. sustains technology leadership in aerosol jet systems, while nScrypt Inc. specializes in multi-material dispensing platforms that extend fabrication freedom for biomedical electrode arrays.
3D printed electronics fabricates functional circuitry and electromechanical components through layer-by-layer additive processes, typically employing conductive nanoparticle inks, dielectric polymers, and laser-sintered metal traces with trace widths below 50 micrometers. The primary industrial purpose is to eliminate subtractive etching waste and enable conformal integration onto curved or flexible substrates. Inkjet printing dominates volume production of IoT device interconnects where resolution requirements remain moderate, while laser sintering occupies the high-reliability tier for aerospace sensor modules demanding thermal durability. Additive manufacturing competes across wearable devices by enabling stretchable conductor geometries that conventional printed circuit boards cannot achieve.
FDA reviews printed biomedical applications under evolving combination product frameworks, while REACH restricts certain silver nanoparticle formulations in European consumer electronics. The FCC governs electromagnetic emission standards for antennas produced through additive methods in United States commercial deployments. Stakeholders must monitor how material qualification databases from ISO and IEC evolve to certify conductive inks for automotive underhood temperatures.
Market Dynamics
Material qualification databases from ISO and IEC are compressing time-to-market for automotive and aerospace suppliers, forcing parallel-track certification investments alongside R&D cycles.
Growth Catalysts
- Aerospace sensor miniaturization:Germany and the United States defense primes are qualifying laser-sintered antenna arrays for satellite constellations, bypassing traditional PCB etching constraints.
- REACH material exemptions:ECHA guidance on silver nanoparticle formulations is creating compliant ink pathways for European consumer electronics OEMs.
- Wearable stretchable conductors:South Korean electronics manufacturers are integrating inkjet-printed circuitry into curved device housings for health-monitoring applications.
Market Restraints
- Silver nanoparticle cost volatility:Conductive ink feedstock prices fluctuate with precious metals markets, squeezing gross margins for mid-scale producers.
- Equipment supplier concentration:Aerosol jet system manufacturing concentrates among specialized vendors in the United States, creating procurement bottlenecks.
- Thermal durability ceilings:Polymer substrates degrade above 150°C, excluding printed electronics from automotive underhood zones.
Strategic Opportunities
- Japan biomedical electrodes:PMDA combination product frameworks are opening printed biosensor pathways for continuous glucose monitoring patches.
- India domestic electronics:PLI scheme incentives for semiconductor packaging are pulling additive manufacturing equipment into Bengaluru and Hyderabad contract facilities.
- AI-driven print optimization:Machine vision convergence with multi-material dispensing is reducing defect rates in high-mix, low-volume production runs.
Industry Challenges
- Multi-physics simulation talent scarcity:Electromechanical co-design requires rare cross-training in fluid dynamics, materials science, and RF engineering.
- FDA pre-submission timelines:Printed biomedical device reviews average 18-24 months, consuming working capital before revenue recognition.
- Legacy MES integration friction:Additive workflows lack standardized data exchange with ERP systems deployed by tier-one electronics contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Printed Electronics Market |
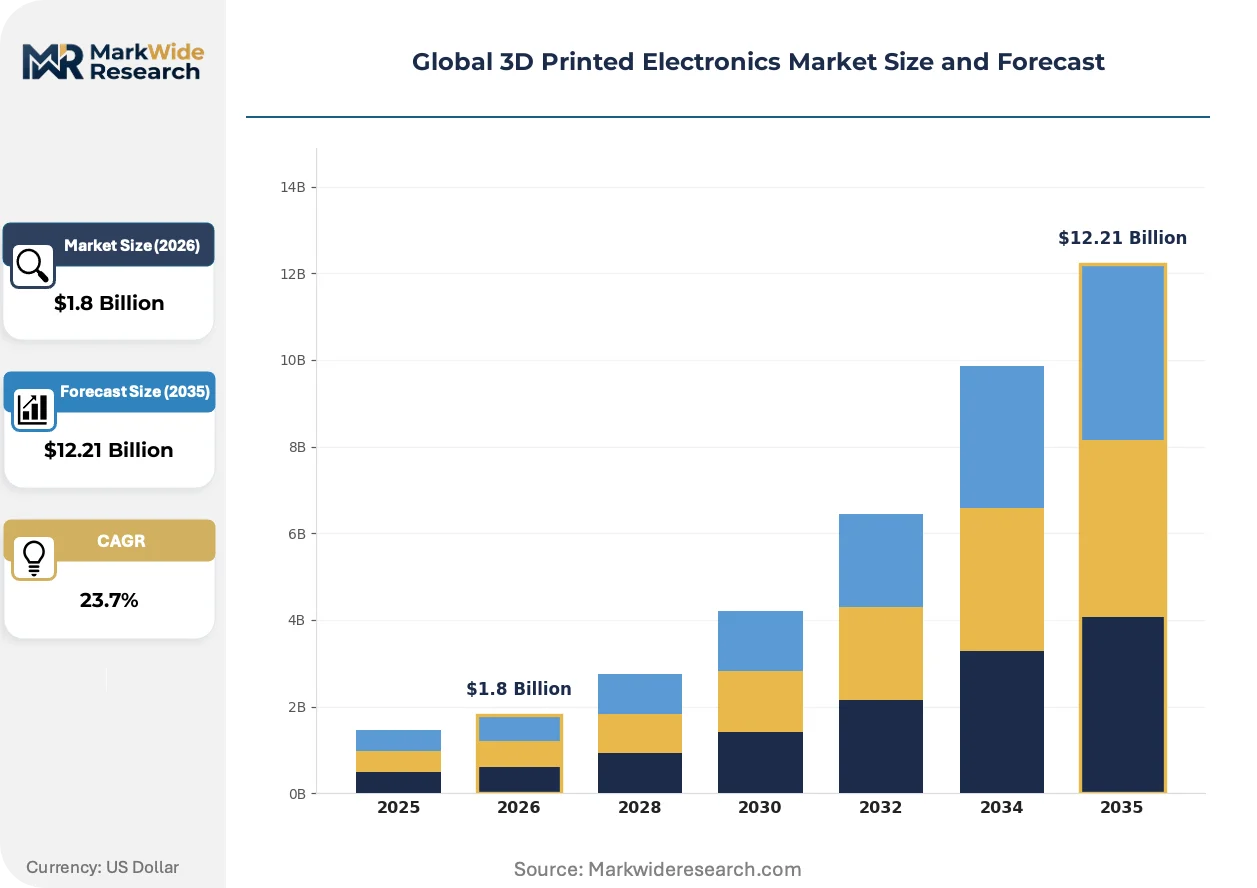
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.21 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Boards, Sensors, Antennas, Connectors Technology: Additive Manufacturing, Inkjet Printing, Laser Sintering, Extrusion End User: Consumer Electronics, Automotive, Aerospace, Healthcare Application: Wearable Devices, IoT Devices, Smart Packaging, Biomedical |
| Companies Covered | Nano Dimension Ltd., Optomec Inc., nScrypt Inc., Molex LLC, Novacentrix, DuPont de Nemours, Inc., Agfa-Gevaert Group, Nissha Co., Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Printed Electronics Market Emerging Trajectories
Conformal integration requirements are dissolving the boundary between structural housing and functional circuitry, compressing traditional electronics assembly into single-process fabrication.
Multi-material dispensing platforms are hybridizing dielectric and conductive deposition within single print sequences. Medical device manufacturers in Massachusetts and Minnesota are piloting these systems for neural interface arrays. The structural consequence is collapsing subcontractor tiers, as finished electrode assemblies emerge from one machine rather than three separate suppliers.
REACH authorization requirements for certain silver salt formulations are tightening material substitution timelines. European electronics OEMs are accelerating copper-nickel alloy ink qualification to maintain market access. South Korean chemical suppliers are capturing qualification data ahead of 2027 sunset dates, positioning as compliant feedstock alternatives.
Defense procurement offices are compressing supplier qualification cycles through digital thread documentation. Satellite prime contractors in California and Colorado now require additive process digital twins for antenna array submissions. This behavioral shift is most visible in smallsat constellations, where rapid iteration demands match compressed launch schedules.
Global 3D Printed Electronics Market Segmentation
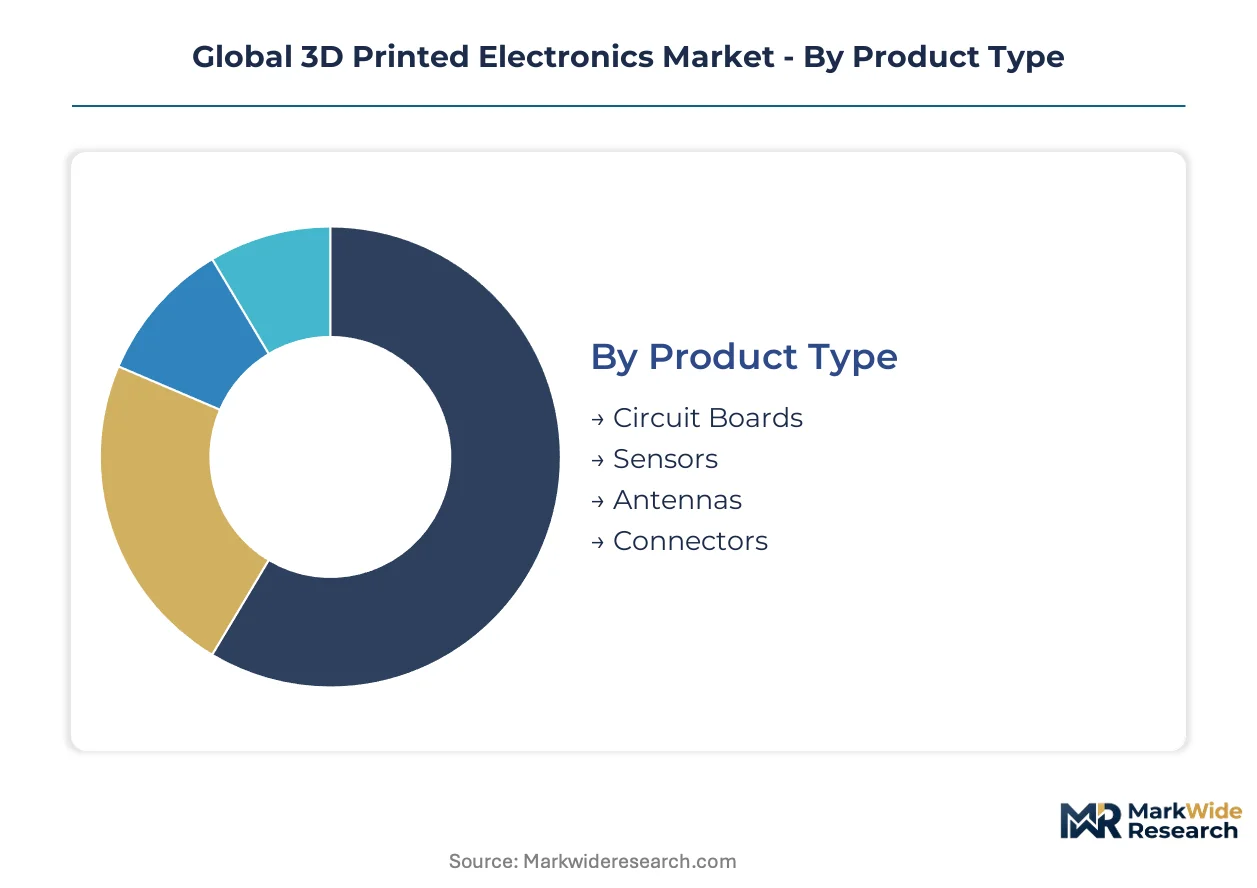
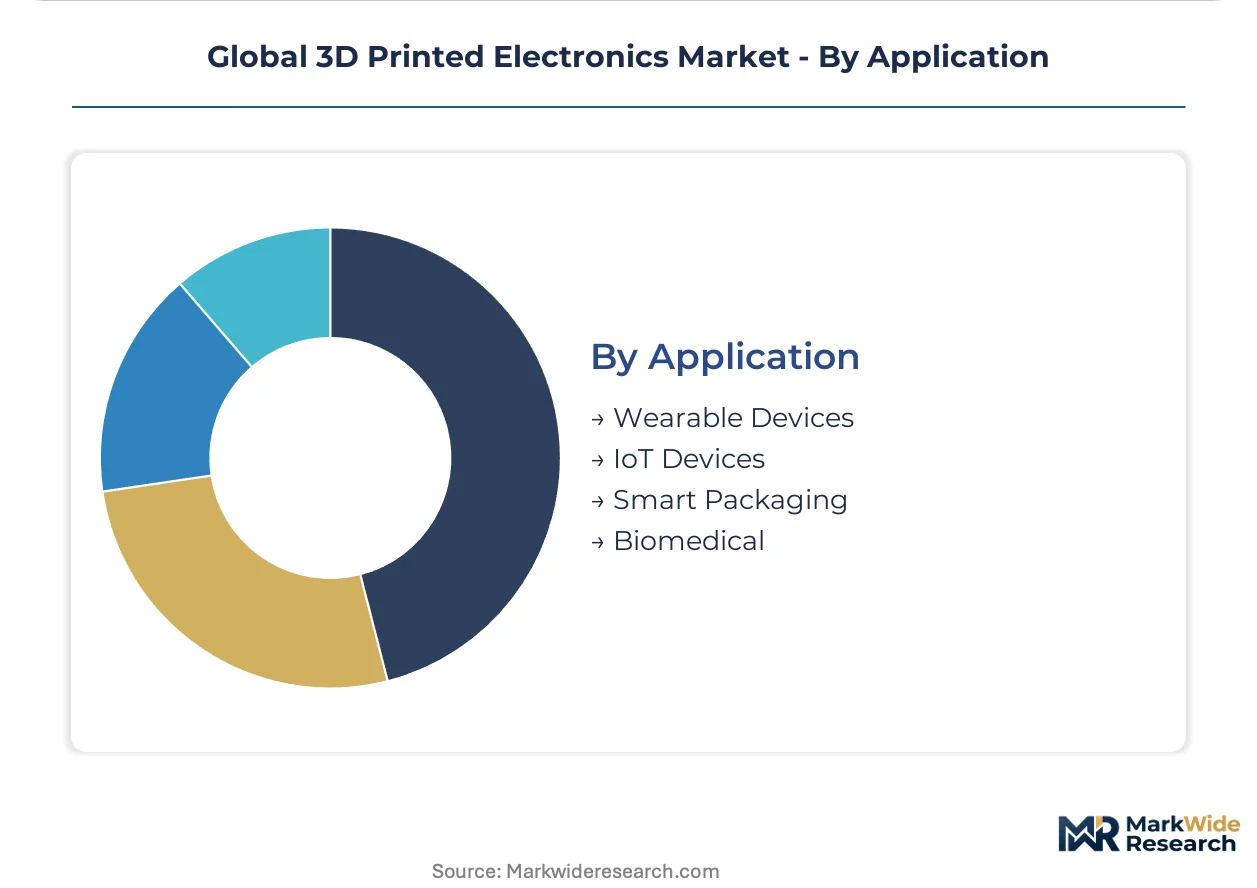
3D printed electronics defy conventional component classification because structural and functional layers merge. Segmentation reveals how fabrication methods dictate viable end-uses and which customer types absorb premium process costs.
Product Type:
Cost tier separates commodity interconnects from mission-critical RF components requiring trace width precision below 50 micrometers.
- Circuit Boards:Multi-layer dielectric-conductor stacks replace subtractive etching for IoT device backplanes. Consumer electronics OEMs in South Korea are qualifying inkjet-printed flexible PCBs for curved smartphone housings, though silver nanoparticle feedstock costs compress margins at volume.
- Sensors:Printed strain gauges and temperature transducers integrate directly onto structural aircraft skins. Germany's defense primes are laser-sintering antenna-integrated sensor modules for satellite constellations, bypassing traditional PCB assembly constraints.
- Antennas:Conformal RF arrays on polymer substrates serve wearable and aerospace applications.
- Connectors:Custom interconnect geometries bridge rigid-flex transitions in miniaturized devices.
Circuit boards hold installed capacity. Sensors are rotating up the share rankings.
Technology:
Volume throughput and resolution precision create distinct competitive tiers with different capital intensity barriers.
- Additive Manufacturing:Direct-write deposition systems build 3D circuitry with arbitrary geometry freedom. Nano Dimension anchors defense and satellite production with multi-material platforms capable of simultaneous conductive and dielectric deposition.
- Inkjet Printing:Drop-on-demand nanoparticle dispensing dominates consumer electronics volume. Massachusetts medical device manufacturers pilot hybrid systems for neural interface arrays, collapsing three supplier tiers into single-machine output.
- Laser Sintering:Thermal consolidation of metal traces achieves aerospace-grade reliability.
- Extrusion:Paste-based deposition suits prototyping and low-mix production environments.
Inkjet printing commands volume share. Laser sintering is climbing the fastest as satellite qualification cycles compress.
End User:
Customer type determines material qualification burden and acceptable price premiums for printed versus conventional electronics.
- Consumer Electronics:Wearable and smartphone OEMs drive inkjet volume for curved device integration. South Korean manufacturers embed health-monitoring circuitry directly into watch housings, though REACH silver nanoparticle restrictions accelerate copper-nickel ink substitution timelines.
- Aerospace:Satellite prime contractors in California and Colorado now require additive process digital twins for antenna submissions. Small satellite constellations demand rapid iteration matching compressed launch schedules.
- Automotive:Underhood thermal durability ceilings exclude most polymer substrates from engine bay applications.
- Healthcare:FDA combination product reviews average 18-24 months for printed biomedical devices.
Consumer electronics holds volume leadership. Aerospace is gaining share fastest as defense procurement digitalizes qualification.
Application:
Maturity stage separates established IoT interconnects from emerging biomedical formats facing regulatory navigation.
- Wearable Devices:Stretchable conductor geometries enable skin-conforming health monitors impossible with rigid PCBs. South Korean electronics OEMs integrate inkjet-printed circuitry into curved housings for continuous biometric tracking.
- IoT Devices:Volume production of sensor node interconnects leverages moderate-resolution inkjet where thermal cycling demands remain modest.
- Smart Packaging:Printed RFID and environmental sensors track cold chain integrity.
- Biomedical:Japan's PMDA combination product frameworks are opening printed biosensor pathways for continuous glucose monitoring patches. Minnesota neural interface manufacturers pilot multi-material dispensing for electrode arrays.
IoT devices hold mature volume share. Biomedical applications are expanding most quickly as regulatory pathways clarify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for 3D printed electronics equipment and conductive inks tilt toward net importers in emerging manufacturing hubs while established producers in Germany, the United States, and Japan maintain technology trade surpluses. Capital equipment flows concentrate where defense procurement and biomedical regulatory pathways create captive demand clusters.
United States
Defense prime contractors in California and Colorado drive demand for laser-sintered antenna arrays in small satellite constellations. The FCC governs electromagnetic emission standards for additively manufactured RF components in commercial deployments. Massachusetts and Minnesota medical device clusters pilot multi-material dispensing systems for neural interface arrays under FDA combination product frameworks.
Germany
Aerospace manufacturers in Bavaria and Baden-Württemberg expand procurement of conformal sensor modules for satellite applications. REACH compliance through ECHA tightens material qualification pathways for silver nanoparticle formulations in consumer-facing electronics. The Stuttgart and Munich industrial corridors anchor precision equipment manufacturing for aerosol jet deposition systems.
South Korea
Electronics OEMs in Seoul and Suwon integrate inkjet-printed circuitry into curved wearable housings for health-monitoring applications. The MFDS regulates printed biomedical devices under evolving combination product standards. The Gyeonggi-do cluster concentrates flexible PCB prototyping capacity serving smartphone and smartwatch supply chains.
Japan
Medical device manufacturers in Tokyo and Osaka pursue PMDA approval pathways for continuous glucose monitoring patches using printed biosensor electrodes. METI industrial policy supports domestic additive manufacturing equipment development for electronics applications. The Nagoya aerospace corridor qualifies printed RF components for satellite and defense platforms.
India
Contract manufacturers in Bengaluru and Hyderabad import additive manufacturing equipment under PLI scheme incentives for semiconductor packaging localization. The BIS develops standards for conductive ink formulations in domestic electronics production. The Karnataka electronics manufacturing cluster absorbs imported deposition systems for IoT device interconnect prototyping.
Global 3D Printed Electronics Market Vendor Landscape
On the supply side, the industry is consolidating around specialized equipment vendors with differentiated deposition technologies and material science capabilities. Three strategic archetypes dominate: direct-write deposition specialists, aerosol jet system providers, and multi-material dispensing platform developers. Competitive moves center on technology licensing agreements and strategic partnerships with defense and biomedical end-users to compress qualification cycles.
Within the direct-write deposition tier, Nano Dimension Ltd. exemplifies premium circuit board production positioning for defense and satellite clients. Optomec Inc. anchors aerosol jet technology leadership, while nScrypt Inc. occupies the multi-material dispensing segment for biomedical electrode applications. These three companies represent distinct technology vectors rather than overlapping market positions.
| Leading Market Players |
|---|
| Nano Dimension Ltd. |
| Optomec Inc. |
| nScrypt Inc. |
| Molex LLC |
| Novacentrix |
| DuPont de Nemours, Inc. |
| Agfa-Gevaert Group |
| Nissha Co., Ltd. |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Underutilized aerosol jet system capacity in the United States Midwest is pressuring equipment vendors to extend lease financing terms while compressing upfront pricing for South Korean and German contract manufacturers evaluating multi-material platform adoption.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures spanning 36-60 month equipment leasing with embedded service tiers. Pricing stratifies across aerospace-grade laser sintering, mid-tier inkjet production, and prototyping extrusion systems based on trace width precision and thermal durability certification. Cost compression in consumer electronics inkjet feedstock is intensifying because silver nanoparticle spot prices fluctuate with precious metals markets. Tier-one defense primes exhibit lowest price sensitivity due to mission-critical qualification requirements, while mid-scale biomedical contract manufacturers face acute margin pressure from FDA pre-submission capital lockup.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize equipment procurement contracts as vendors compete for limited capital expenditure budgets in the post-expansion phase. Manufacturing concentrates in the United States for aerosol jet systems, Germany for precision deposition optics, and Japan for high-resolution printhead assemblies. Conductive ink formulation draws from silver nanoparticle suppliers in South Korea, copper-nickel alloy developers in Germany, and dielectric polymer compounders in the United States. Single-source vulnerability persists around specialized piezoelectric printhead components sourced from Japanese precision ceramics manufacturers. Distribution runs through direct vendor-to-OEM relationships for defense and satellite applications, with regional equipment distributors serving prototyping and academic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D printed electronics market is entering a cyclical recovery phase as defense procurement offices accelerate small satellite constellation deployment schedules and FDA combination product pathways mature for printed biomedical devices.
For Market Incumbents: Build regulatory qualification moats by pre-positioning material databases with ECHA ahead of 2027 REACH sunset dates for silver salt formulations. Incumbents should anchor capacity additions in the Gyeonggi-do cluster to capture South Korean wearable OEM volume, while defending against copper-nickel ink substitution threats through backward integration into compliant feedstock production. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized semiconductor packaging corridor, where Bengaluru and Hyderabad contract facilities lack indigenous additive manufacturing equipment expertise. New entrants should target biomedical electrode arrays for continuous glucose monitoring patches as the most penetrable application, leveraging AI-driven print optimization partnerships with Massachusetts and Minnesota medical device clusters to compress defect rates. For Investors and Strategic Acquirers: Long-term, this sits as a defense-biomedical dual-use technology play because satellite prime contractor digital thread requirements and FDA combination product frameworks create durable captive demand with high switching costs. Acquisition targets should display multi-material dispensing platform capabilities with existing PMDA or FDA engagement. The signal to watch is ECHA authorization timeline acceleration for alternative conductive ink chemistries, which would unlock European consumer electronics volume and validate copper-nickel substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Platform Integration | Collapses three-tier subcontractor structures into single-machine electrode assembly output for neural interface manufacturers. |
| REACH-Compliant Ink Qualification | Positions European OEMs to maintain market access as ECHA tightens silver nanoparticle authorization pathways. |
| Defense Digital Thread Certification | Satisfies California and Colorado satellite prime contractor requirements for additive process documentation in antenna submissions. |
| AI-Driven Print Optimization | Reduces defect rates in high-mix, low-volume biomedical production runs through machine vision convergence with dispensing systems. |
| Biomedical Regulatory Pre-Submission | Compresses FDA combination product review timelines from 24-month averages through early-stage agency engagement protocols. |
Methodological Framework
Initial hypotheses were tested against primary input from equipment R&D directors at deposition system manufacturers, procurement leads at aerospace prime contractors, regulatory affairs specialists at biomedical device firms, and conductive ink formulation chemists, then refined through secondary validation against SEC 10-K equipment vendor disclosures, ECHA REACH authorization databases, FDA combination product submission records, and ISO/IEC material qualification standards. Bottom-up demand modeling across end-use segments was triangulated with top-down equipment shipment aggregation.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeled by fabrication technology, product type, end-user industry, and application maturity stage. CAGRs were derived from equipment capacity expansion announcements correlated with end-user procurement pipeline visibility. Industry-specific forecast inputs included defense satellite constellation launch schedules and PMDA biomedical device approval pathway evolution.
Sensitivities concentrate around precious metals price volatility for conductive feedstock, REACH authorization timeline shifts, and FDA pre-submission backlog fluctuations. Forecasts incorporate documented assumptions regarding equipment utilization rates and qualification cycle compression. Macroeconomic contraction affecting defense discretionary spending, regulatory restriction expansion beyond current silver nanoparticle scopes, or breakthrough substitution technologies for conformal antenna fabrication would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
Asia-Pacific Industrial 3D Printing Market
3D Printing Technology
3D Printing Service Bureaus Market
3D Printing Technology
3D Printing Market
3D Printing Technology
Additive Manufacturing Software Market
3D Printing Technology
3D Printing Robots Market
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
3D Printer Market
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
Online 3D Printing Service Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
Digital 3D Printing Market
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
North America Industrial 3D Printing Market