
 3D Printing Market | 2026-2036
3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Market Intelligence
A shift from outsourced prototyping to in-house production is realigning how manufacturers source additive components. Stratasys leverages its polymer expertise to anchor service bureau networks across North America. EOS GmbH dominates industrial metal powder bed fusion with installed base concentration in automotive and medical tooling. General Electric Company sustains vertical control over turbomachinery supply chains through captive additive manufacturing at its Auburn facility.
3D printing constructs objects by depositing, curing, or sintering material layer-by-layer from digital models, typically achieving tolerances of 50-200 microns depending on process modality. Fused Deposition Modeling occupies the broadest installed base due to low equipment cost and thermoplastic versatility in jigs and fixtures. Metal Powders command the highest value per kilogram and attract aerospace fabricators seeking topology-optimized structural components. Selective Laser Sintering leads polymer production for functional prototypes where surface finish and isotropic strength matter.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape market access for dental implants and patient-specific surgical guides, forcing manufacturers to maintain validated process parameters. ISO/ASTM 52900 standards define terminology and test methods that reduce qualification friction between buyers and suppliers. Stakeholders must monitor evolving FAA airworthiness criteria for printed flight hardware as certifying authorities weigh statistical process control against traditional destructive testing protocols.
Market Dynamics
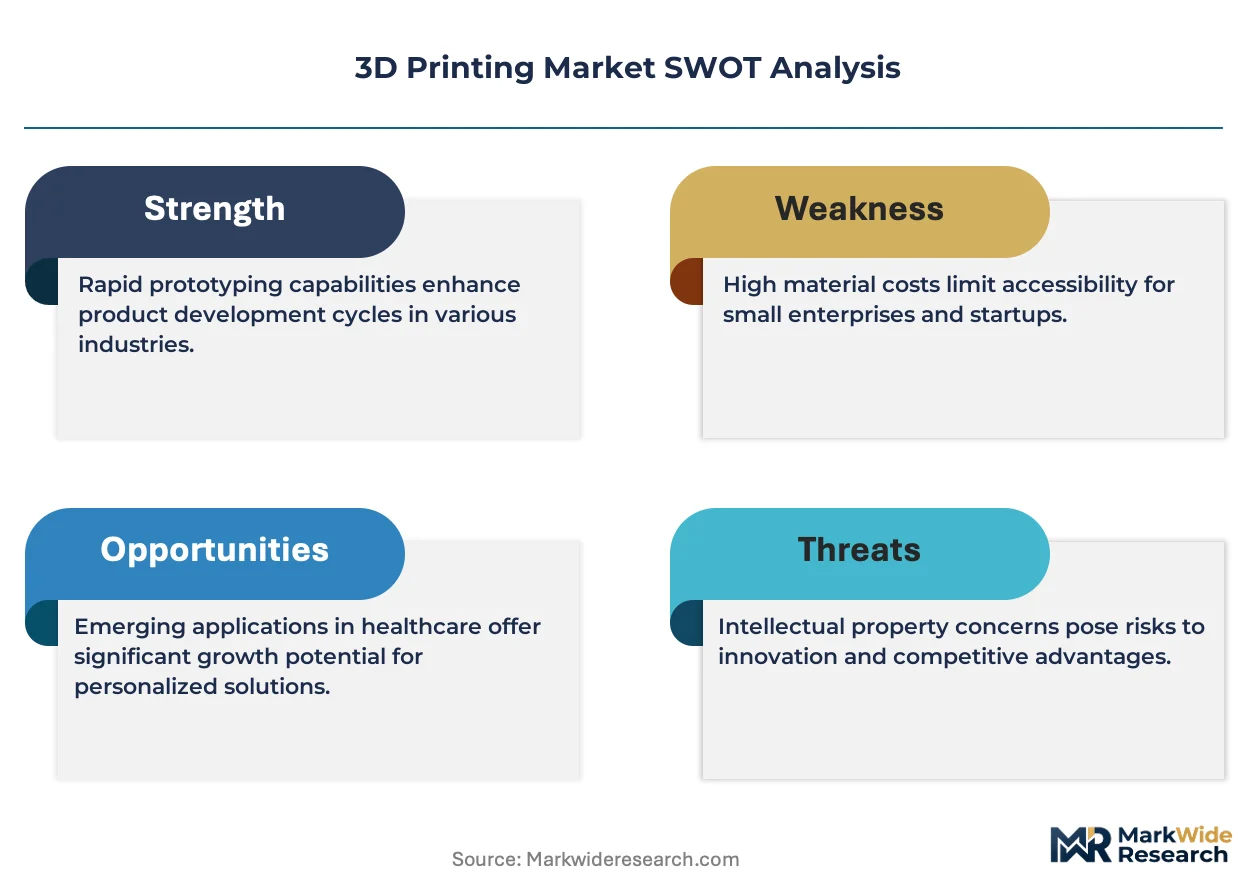
Flight-certification pathways for titanium lattice structures are compressing development timelines while tightening quality documentation requirements across aerospace supply chains. This regulatory acceleration is forcing fabricators to choose between captive additive capacity and qualified external service bureaus.
Growth Catalysts
- EU Medical Device Regulation:MDR quality benchmarks for patient-contact devices are elevating entry barriers that favor validated additive manufacturers with established quality management systems.
- Topology optimization software:Generative design tools integrated with powder bed fusion are enabling weight reductions in structural aerospace components previously machined from solid billet.
- German industrial clusters:Concentrated metal printing ecosystems around Munich and Aachen provide qualified workforce pipelines and shared metrology infrastructure.
Market Restraints
- Noble metal powder costs:Titanium and nickel superalloy feedstock prices fluctuate with aerospace commodity cycles, compressing margins for contract manufacturers without long-term supply agreements.
- Beam source concentration:High-power laser and electron beam systems rely on a limited supplier base in Germany and the United States, creating single-source vulnerability for production scaling.
- Build-rate limitations:Powder bed fusion throughput remains two orders of magnitude below conventional casting for high-volume automotive components.
Strategic Opportunities
- India medical device manufacturing:CDSCO regulatory harmonization with ISO/ASTM 52900 standards creates first-mover advantage for implant-qualified additive facilities serving domestic and export markets.
- Multi-material deposition:Combining polymer and metal extrusion in single builds opens functional integration opportunities in surgical instrumentation and electronic housings.
- US Inflation Reduction Act:Domestic content incentives for clean energy hardware accelerate qualification of printed copper windings and heat exchangers for grid infrastructure.
Industry Challenges
- Non-destructive inspection talent:Industrial computed tomography interpretation for internal defect detection requires specialized radiographers in short supply across certified labs.
- FAA airworthiness certification:Statistical process control acceptance criteria for flight-critical hardware remain undefined, extending qualification timelines beyond program schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Market |
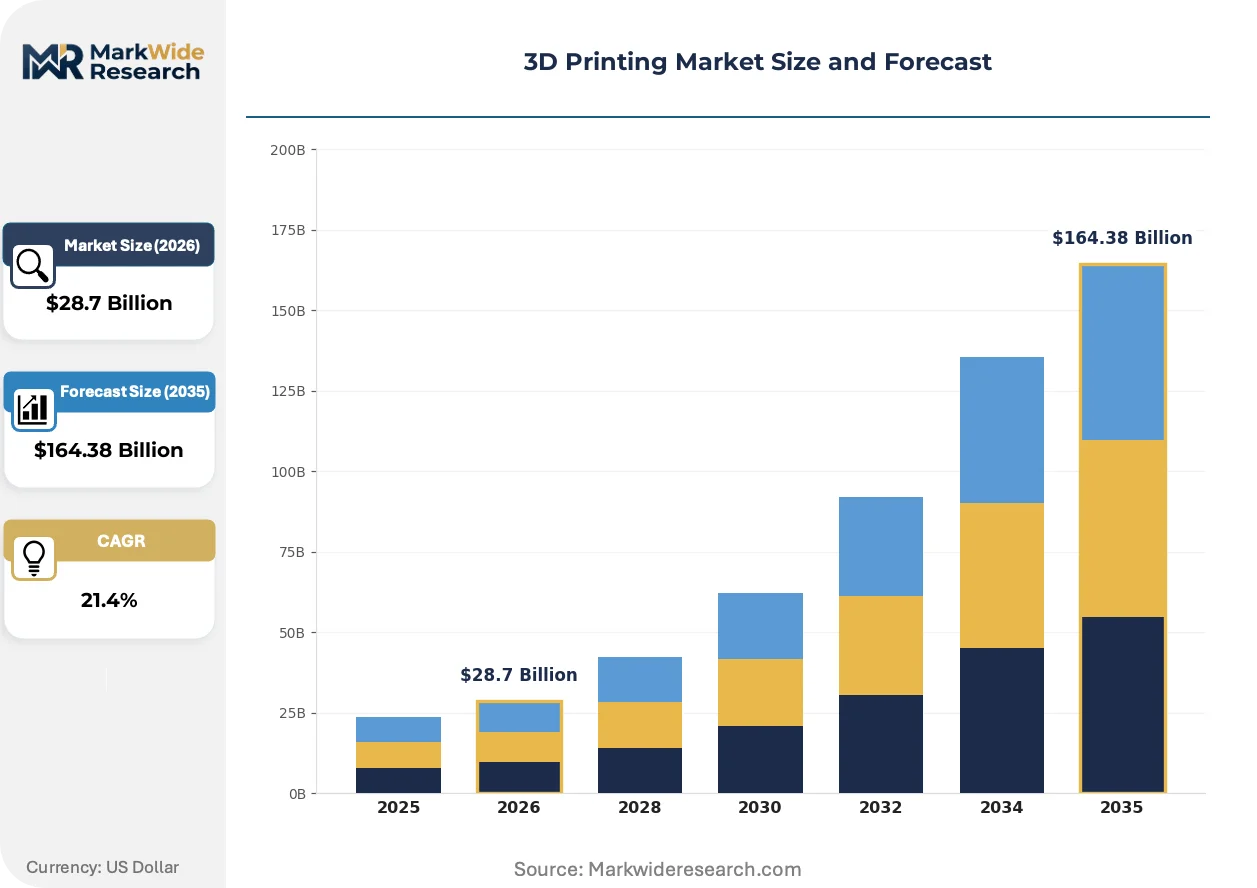
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $164.38 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing, Binder Jetting Application: Prototyping, Mold Making, Customized Jewelry, Aerospace Components, Dental Implants End User: Consumer Goods Manufacturers, Aerospace Fabricators, Dental Laboratories, Architectural Firms, Educational Institutions Material Type: Thermoplastics, Photopolymer Resins, Metal Powders, Ceramics, Composite Filaments |
| Companies Covered | Stratasys, 3D Systems, Inc., HP Development Company, EOS GmbH, Materialise, General Electric Company, Protolabs, Desktop Metal, Renishaw plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Market Strategic Shifts & Innovations
Process monitoring systems are shifting quality assurance from post-build inspection to in-situ detection, compressing rework cycles and redefining supplier qualification protocols across regulated industries.
Continuous fiber-reinforced thermoplastic printing is rewriting structural performance expectations for jigs, fixtures, and non-flight aerospace interiors. Automotive tooling departments are adopting these systems at pilot scale to replace machined aluminum patterns. The technology is compressing lead times from weeks to days while eliminating CNC programming bottlenecks.
FDA 510(k) clearance pathways for patient-matched surgical guides are tightening predicate device requirements and demanding material-specific biocompatibility data. Device sponsors must now submit complete process parameter documentation rather than referencing third-party material master files. Dental implant manufacturers with validated titanium workflows are expanding into craniomaxillofacial plates to leverage existing quality infrastructure.
Spare parts procurement for legacy industrial equipment is migrating from original equipment manufacturer catalogs to distributed additive networks. Power generation operators in the United States and Germany are qualifying printed burner tips and valve components to circumvent long-tail inventory carrying costs. This pattern is most visible in sectors with aging installed bases and fragmented OEM aftermarket support.
3D Printing Market Segmentation
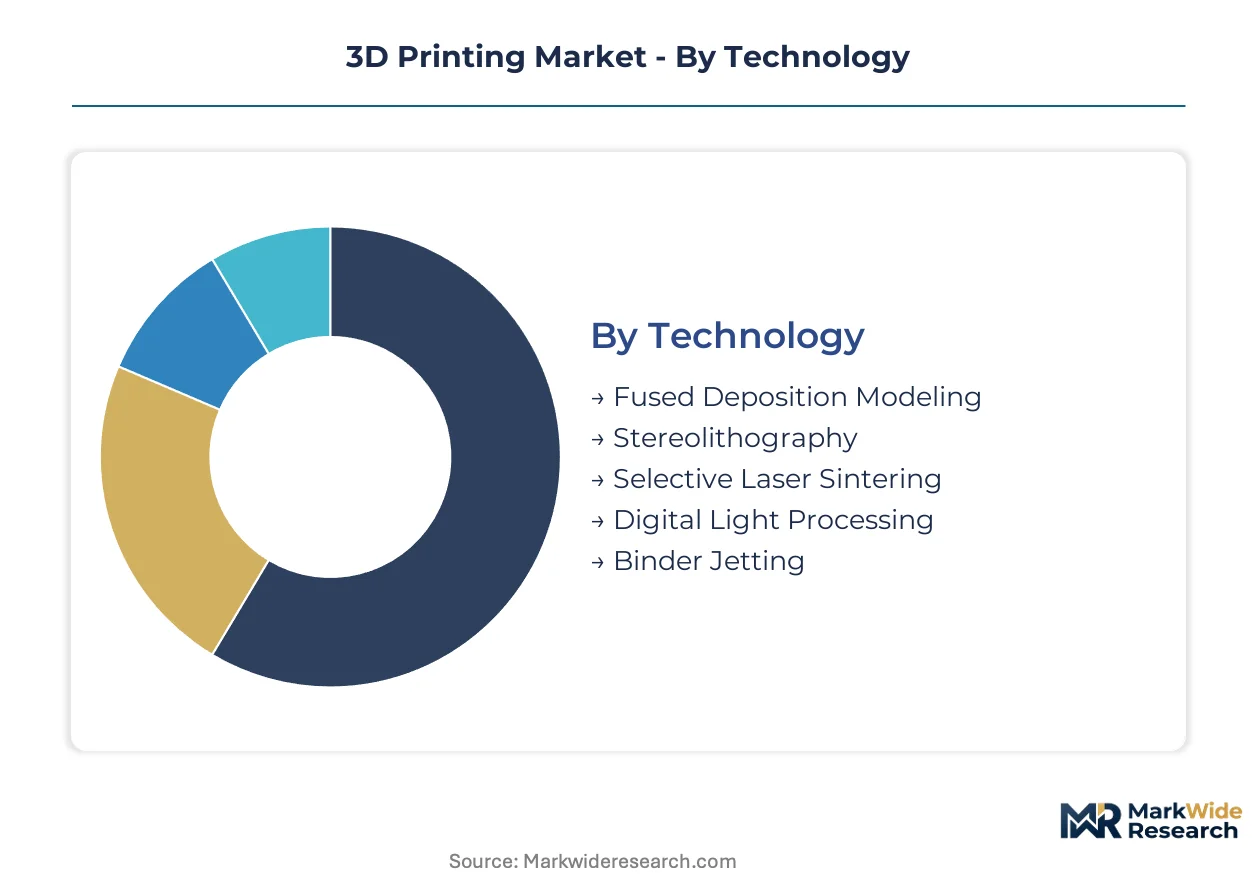
Segmentation in additive manufacturing reveals how certification burdens and material costs stratify competitive position across technologies and end-use verticals. Each dimension carries distinct qualification requirements that determine which suppliers can access regulated applications.
Technology:
FDA 510(k) clearance and FAA airworthiness certification apply unevenly across process modalities, with metal-capable systems facing the heaviest documentation loads while polymer extrusion operates under lighter regulatory scrutiny.
- Selective Laser Sintering:Powder bed fusion using CO₂ or fiber lasers to sinter polymer or metal powders into dense, isotropic parts. Aerospace fabricators in Germany concentrate demand here for flight-certified titanium lattice structures requiring full process parameter traceability.
- Fused Deposition Modeling:Thermoplastic filament extrusion through heated nozzles building parts layer-by-layer. Consumer goods manufacturers and educational institutions drive volume in North America and Asia-Pacific where equipment costs sit lowest and regulatory barriers remain minimal.
- Stereolithography:UV laser curing of photopolymer resins achieves the finest surface finish among polymer processes. Dental laboratories leverage this precision for surgical guide production under FDA and EU MDR quality benchmarks.
- Digital Light Processing:Projector-based photopolymer curing delivers faster throughput than point-source stereolithography. Jewelry and dental applications dominate with biocompatible resin formulations cleared for patient contact.
- Binder Jetting:Liquid binder deposition onto powder beds enables metal and sand casting pattern production without thermal distortion risks. Foundry integration in the United States and China drives adoption for legacy equipment spare parts.
Fused Deposition Modeling sits at the top of the volume ranking, with Binder Jetting climbing the fastest as metal production scales beyond prototyping.
Application:
Application segments diverge sharply by margin structure, with patient-contact medical devices commanding premium pricing validated through ISO 13485 quality systems while prototyping services compete on speed and labor arbitrage.
- Dental Implants:Patient-specific titanium fixtures and surgical guides requiring FDA 510(k) clearance or EU MDR conformity assessment. Manufacturers with validated powder bed fusion workflows in Germany and the United States leverage existing quality infrastructure to expand into craniomaxillofacial plates.
- Aerospace Components:Topology-optimized structural elements in titanium and nickel superalloys subject to FAA airworthiness certification. Flight-critical hardware demands statistical process control documentation that only captive additive facilities or qualified service bureaus can provide.
- Prototyping:Functional form-and-fit validation across all material classes with fastest turnaround requirements. Mold makers and consumer goods manufacturers source this capability through service bureau networks to avoid capital deployment.
- Mold Making:Conformally cooled injection mold inserts printed in tool steel or copper alloys. Automotive suppliers in Germany adopt these to compress cooling cycle times in high-volume production.
- Customized Jewelry:Precious metal casting patterns and direct precious metal printing for bespoke design. Low regulatory burden attracts artisanal producers and luxury brands seeking mass customization.
Prototyping holds the largest revenue base, though Dental Implants gains share fastest as regulatory harmonization opens export markets.
End User:
Customer type determines procurement sophistication, with aerospace and medical verticals demanding full supply chain traceability while educational buyers prioritize equipment reliability and curriculum support over process validation.
- Aerospace Fabricators:Tier-1 and Tier-2 suppliers qualifying printed flight hardware through FAA-approved quality systems. GE Aviation's Auburn facility exemplifies captive additive capacity for turbomachinery supply chain control.
- Dental Laboratories:Small-to-mid-size facilities adopting chairside and centralized printing for crowns, bridges, and surgical guides. EU MDR implementation is consolidating demand toward validated manufacturers with established technical documentation.
- Consumer Goods Manufacturers:Footwear, electronics, and packaging companies using additive for tooling and limited production parts. Speed-to-market pressures favor polymer processes with minimal post-processing requirements.
- Architectural Firms:Scale models and facade prototypes printed in gypsum, resin, or thermoplastic. Project-based demand cycles create irregular equipment utilization patterns.
- Educational Institutions:Universities and technical colleges training workforce pipelines while supporting research programs. Equipment purchases concentrate in Germany, the United States, and China where government funding supports advanced manufacturing curricula.
Consumer Goods Manufacturers represent the broadest installed base, with Dental Laboratories expanding most quickly as digital dentistry penetrates emerging markets.
Material Type:
Feedstock economics and supply security vary dramatically, with noble metal powders subject to aerospace commodity price swings while thermoplastic pellets benefit from established petrochemical distribution infrastructure.
- Metal Powders:Titanium, nickel superalloy, aluminum, and steel feedstock produced through plasma atomization or gas atomization. Aerospace fabricators face margin pressure from titanium price volatility and limited qualified powder suppliers concentrated in Germany and the United States.
- Thermoplastics:ABS, PLA, PETG, and engineering-grade filaments and pellets for extrusion-based processes. Lowest cost per kilogram enables high-volume prototyping and end-use part production across consumer and industrial applications.
- Photopolymer Resins:Acrylate and epoxy formulations cured by UV light for dental, jewelry, and precision prototyping. Biocompatible grades cleared by FDA and EU regulators command substantial premiums over standard formulations.
- Ceramics:Alumina, zirconia, and technical ceramic pastes for high-temperature and biomedical applications. Sintering shrinkage management limits adoption to specialized medical and industrial component producers.
- Composite Filaments:Continuous fiber-reinforced thermoplastics combining nylon or ABS with carbon or glass fiber. Automotive tooling departments pilot these systems to replace machined aluminum patterns with compression-molded structural fixtures.
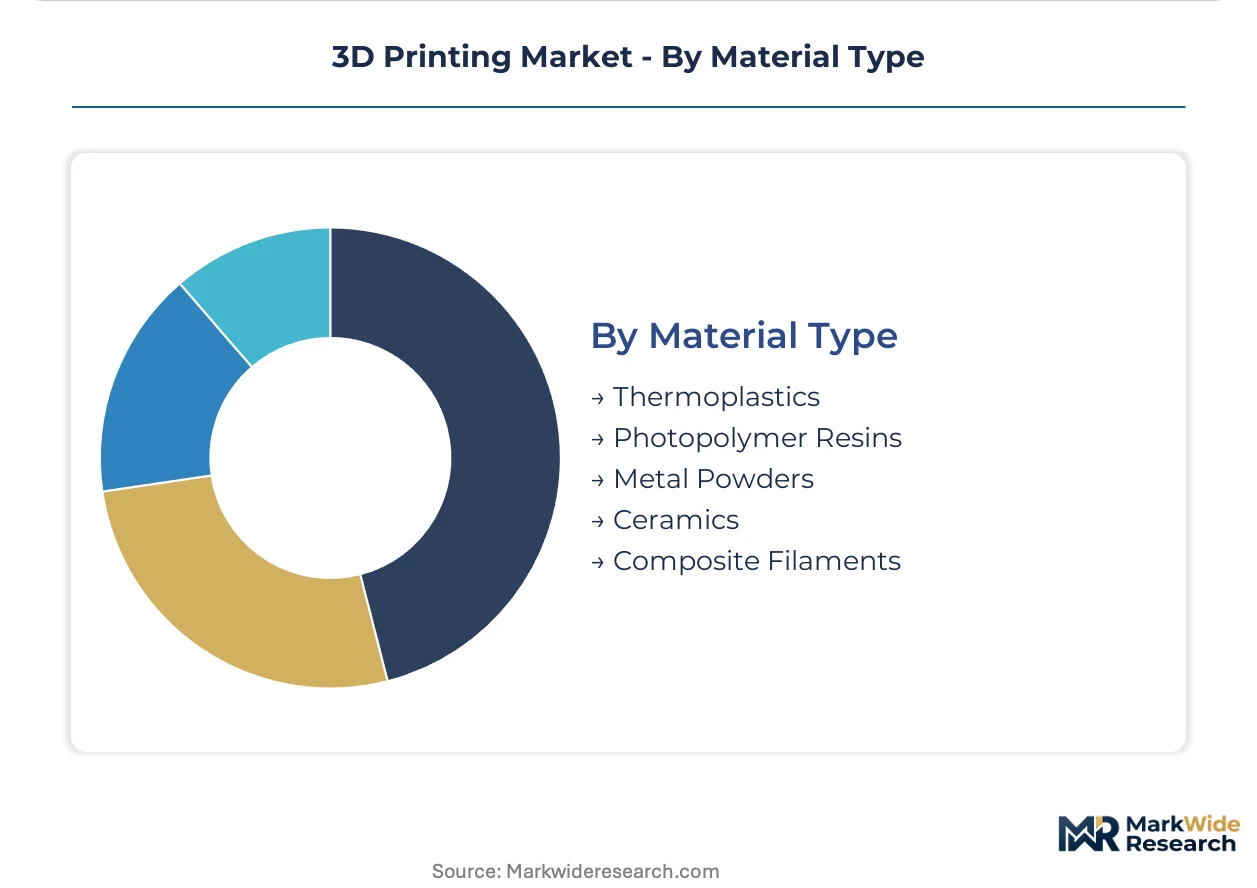
Thermoplastics dominate by volume, with Metal Powders showing the steepest expansion trajectory as flight-certified applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting additive manufacturing investment toward jurisdictions with harmonized quality standards and concentrated technical infrastructure. Fabricators migrate production to exploit cost-of-compliance gaps between established certification regimes and emerging regulatory pathways.
Germany
Aerospace demand for flight-certified titanium components drives metal powder bed fusion adoption. The EU Medical Device Regulation elevates entry barriers for patient-contact devices, favoring validated manufacturers with ISO 13485 systems. Munich and Aachen anchor industrial clusters where EOS GmbH and Materialise maintain shared metrology infrastructure and qualified workforce pipelines.
United States
Domestic content incentives under the Inflation Reduction Act accelerate qualification of printed copper windings for grid infrastructure. FAA airworthiness criteria for flight-critical hardware remain under development, extending qualification timelines for turbomachinery suppliers. GE Aviation's Auburn facility exemplifies captive additive capacity for vertical supply chain control.
India
CDSCO regulatory harmonization with ISO/ASTM 52900 standards creates first-mover positioning for implant-qualified facilities serving export markets. The PLI scheme for medical device manufacturing attracts additive infrastructure investment. Maharashtra and Gujarat concentrate dental laboratory demand as digital dentistry penetrates tier-2 cities.
China
Dual carbon goals and MIIT advanced manufacturing directives accelerate binder jetting adoption for metal production scaling beyond prototyping. NMPA medical device regulations tighten predicate device requirements for patient-matched surgical guides. Yangtze River Delta foundries integrate printed sand casting patterns to circumvent long-tail inventory costs for legacy industrial equipment.
Japan
METI industrial competitiveness programs fund continuous fiber-reinforced thermoplastic printing for automotive tooling replacement. PMDA quality benchmarks for dental implants force manufacturers to submit complete process parameter documentation. Nagoya-area automotive suppliers pilot these systems to compress aluminum pattern lead times from weeks to days.
3D Printing Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue multi-material deposition and in-situ process monitoring capabilities. Market structure reflects moderate consolidation around metal powder bed fusion specialists with validated regulatory pathways. Three archetypes dominate: aerospace-integrated captive facilities, medical-qualified contract manufacturers, and polymer-focused service bureau networks. Competitive moves concentrate on strategic partnerships for beam source security and portfolio diversification into dental and jewelry applications.
Among Germany-based fabricators, EOS GmbH and Materialise occupy positions within the industrial metal printing cluster, exemplifying the medical-qualified contract manufacturer archetype through their concentration around Munich and Aachen infrastructure. Stratasys represents the polymer-focused service bureau network model, anchoring North American capacity deployment. General Electric Company sits within the aerospace-integrated captive facility tier, demonstrating vertical supply chain control through dedicated turbomachinery production capacity.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems, Inc. |
| HP Development Company |
| EOS GmbH |
| Materialise |
| General Electric Company |
| Protolabs |
| Desktop Metal |
| Renishaw plc |
| Others |
Cost & Logistics Intelligence
Titanium powder feedstock costs cascade through aerospace supply chains into three-tier pricing structures across premium flight-certified, standard industrial, and economy prototyping tiers. Buyers in Germany and the United States absorb volatility through long-term offtake agreements while dental laboratories in India face spot-market exposure.
Pricing Analysis
Input-cost pass-through from noble metal powders dominates pricing dynamics for flight-certified components, with titanium and nickel superalloy fluctuations compressing contract manufacturer margins. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical workflows from uncertified prototyping services. Pricing pressure stems from beam source supplier concentration in Germany and the United States, forcing equipment purchasers into single-source vulnerability. Dental laboratories exhibit highest price sensitivity due to fragmented demand, while aerospace fabricators prioritize qualification over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for flight-critical hardware mandate qualified powder suppliers in both Germany and the United States, with aerospace fabricators maintaining redundant qualification pathways. Raw material dependencies center on plasma-atomized titanium feedstock, high-power laser systems, and biocompatible photopolymer resins. Single-source vulnerability concentrates in electron beam and fiber laser component supply. Distribution runs through captive additive facilities for turbomachinery, qualified service bureau networks for medical devices, and direct equipment sales for prototyping applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in additive manufacturing rests on topology-optimized design software adoption that reduces material intensity for flight-certified components. Premium-tier shift toward patient-matched surgical guides under EU MDR elevates pricing power for validated manufacturers.
For Market Incumbents: Deploy captive powder atomization capacity to secure titanium feedstock supply against aerospace commodity cycles. Anchor position through backward integration into plasma atomization equipment, defending against emerging Chinese binder jetting entrants. Fortify FDA 510(k) predicate device libraries to extend clearance pathways into craniomaxillofacial plates.
For New Entrants and Emerging Players: Begin with CDSCO-harmonized implant manufacturing in Maharashtra and Gujarat, where dental laboratory consolidation creates first-mover positioning for export-qualified facilities. Target multi-material deposition systems combining polymer and metal extrusion for surgical instrumentation white space. Pursue hospital system partnerships rather than equipment sales to bypass incumbent service bureau networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where FAA airworthiness certification timelines exceed program schedules, stranding non-captive fabricators without qualified capacity. Long-term viability favors medical-qualified contract manufacturers with ISO 13485 infrastructure over polymer-focused prototyping networks. Watch FAA statistical process control acceptance criteria publication as inflection signal for flight-hardware qualification velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Beam Source Supply Agreement | Secures high-power laser and electron beam component access against German and US supplier concentration. |
| FDA 510(k) Predicate Expansion | Extends validated titanium workflows from dental implants into craniomaxillofacial plate applications. |
| India CDSCO Qualification | Captures first-mover positioning in harmonized implant manufacturing for domestic and export markets. |
| Multi-Material Deposition Launch | Combines polymer and metal extrusion for functional integration in surgical instrumentation. |
| In-Situ Process Monitoring Integration | Shifts quality assurance from post-build inspection to real-time defect detection under ISO/ASTM 52900. |
Research Approach
Bottom-up dental and aerospace demand modeling reconciled against top-down powder bed fusion equipment tracking forms the analytical core of this study. Primary interviews with biomedical engineers at German dental laboratories, FAA certification specialists, EOS GmbH service technicians, and hospital GPO contracts managers combined with secondary validation from FDA 510(k) filings, EASA airworthiness directives, CDSCO implant registration databases, and MIIT advanced manufacturing disclosures. Triangulation across stakeholder inputs and regulatory documentation ensures segmentation integrity.
Input-output matrix framing connects titanium powder consumption to flight-certified component output across technology, application, end-user, and material-type dimensions. CAGRs derive from equipment installed base expansion rates, qualified facility counts, and regulatory pathway velocity throughout the forecast period. Industry-specific forecast inputs include FAA statistical process control acceptance criteria development timeline and EU MDR technical documentation burden estimates for patient-contact devices.
Several conditions sit outside the modeled scope, including potential FAA airworthiness criteria revisions, titanium commodity price shocks, and geopolitical restrictions on beam source component trade. Forecasts reflect documented assumptions about certification pathway harmonization and qualified workforce pipeline expansion. Deviation in FAA statistical process control acceptance criteria publication timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
Europe 3D Printing Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Europe Industrial 3D Printing Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
Asia-Pacific Industrial 3D Printing Market
3D Printing Technology
Saudi Arabia and Egypt Healthcare 3D Printing Market
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
3D Printing Materials and Equipment Market