
 North America Trace Detection Screening Market | 2026-2036
North America Trace Detection Screening Market Size, Share, and Industry Trends Forecast 2026-2036
North America Trace Detection Screening Market Insights
SAE International's AMS-STD-2175 qualification cycle is rotating vendor eligibility for trace detection equipment deployed at critical infrastructure checkpoints. Bruker Corporation leverages its mass spectrometry R&D intensity to anchor premium positioning in laboratory-grade screening platforms. Smiths Detection Group Ltd. competes through geographic dominance at major Canadian transit hubs, while L3Harris Technologies Inc. sustains channel control across U.S. federal security contracts.
Trace detection screening encompasses technologies that identify microscopic quantities of explosives, narcotics, chemical warfare agents, or biological threats through sample collection and analytical separation, typically achieving detection thresholds in the picogram to nanogram range depending on ionization method and detector architecture. Ion mobility spectrometry occupies the largest installed base due to its portability and sub-ten-second alarm resolution, while mass spectrometry segments command higher margins from forensic laboratories requiring molecular specificity. Gas chromatography systems serve mature demand in fixed-site reference laboratories, whereas surface acoustic wave sensors are gaining traction in compact handheld formats for event security deployments.
The U.S. Transportation Security Administration and Canada's Canadian Air Transport Security Authority jointly shape procurement specifications for aviation checkpoint equipment, with both agencies mandating false-alarm-rate thresholds that filter vendor participation. U.S. Department of Homeland Security grant programs and FDA oversight of biological threat detection assays add compliance layers that extend product development cycles. Stakeholders must monitor evolving explosive precursor regulations from Health Canada and the U.S. Drug Enforcement Administration, as scheduled substance list updates directly expand the analyte libraries that detection platforms must recognize without hardware retrofit.
Market Dynamics
The North America trace detection screening market is undergoing a fundamental restructuring as TSA's next-generation checkpoint protocols force wholesale replacement of aging ion mobility spectrometry fleets at major U.S. airports, compressing procurement cycles and redrawing vendor competitive boundaries.
Growth Catalysts
- Explosive precursor monitoring mandates:The U.S. Drug Enforcement Administration's scheduled substance list updates expand analyte libraries that detection platforms must recognize, compelling hardware refresh cycles across federal security installations.
- Canada's critical infrastructure hardening:Health Canada's evolving chemical threat regulations drive procurement of multi-threat detection systems at Toronto Pearson, Vancouver International, and Montreal-Trudeau airports.
- Mass spectrometry miniaturization:Shrinking form factors for laboratory-grade molecular specificity enable deployment at field checkpoints previously limited to ion mobility spectrometry portability.
Market Restraints
- Helium-3 supply concentration:neutron detection subsystems depend on scarce helium-3 reserves concentrated in U.S. federal stockpiles, creating input cost volatility and supply security concerns.
- Extended FDA biological assay validation:biological threat detection platforms face multi-year approval timelines for new pathogen signatures, freezing product roadmaps and delaying revenue recognition.
- False-alarm-rate technical floors:ion mobility spectrometry architectures hit sensitivity-specificity trade-offs that TSA mandates now exceed, forcing premature obsolescence of installed base.
Strategic Opportunities
- Surface acoustic wave sensor convergence:compact handheld formats combining acoustic wave physics with microfluidic sample prep open event security and stadium deployment channels beyond aviation.
- U.S. Department of Homeland Security grant programs:non-aviation critical infrastructure—ports, rail terminals, federal buildings—access dedicated funding streams for threat detection modernization.
- Mexico's emerging aviation security framework:underpenetrated airport infrastructure presents first-mover positioning as regulatory harmonization with U.S. standards advances.
Industry Challenges
- Spectroscopy data scientist scarcity:chemometric algorithm development for multi-anyte classification requires specialized expertise concentrated in defense contractors and national laboratories.
- SAE AMS-STD-2175 recertification timelines:vendor eligibility rotation demands sustained engineering investment without guaranteed procurement awards, straining R&D budgets.
- Legacy checkpoint integration complexity:new detection platforms must interface with existing baggage handling and passenger flow systems at LAX, JFK, and Chicago O'Hare without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Trace Detection Screening Market |
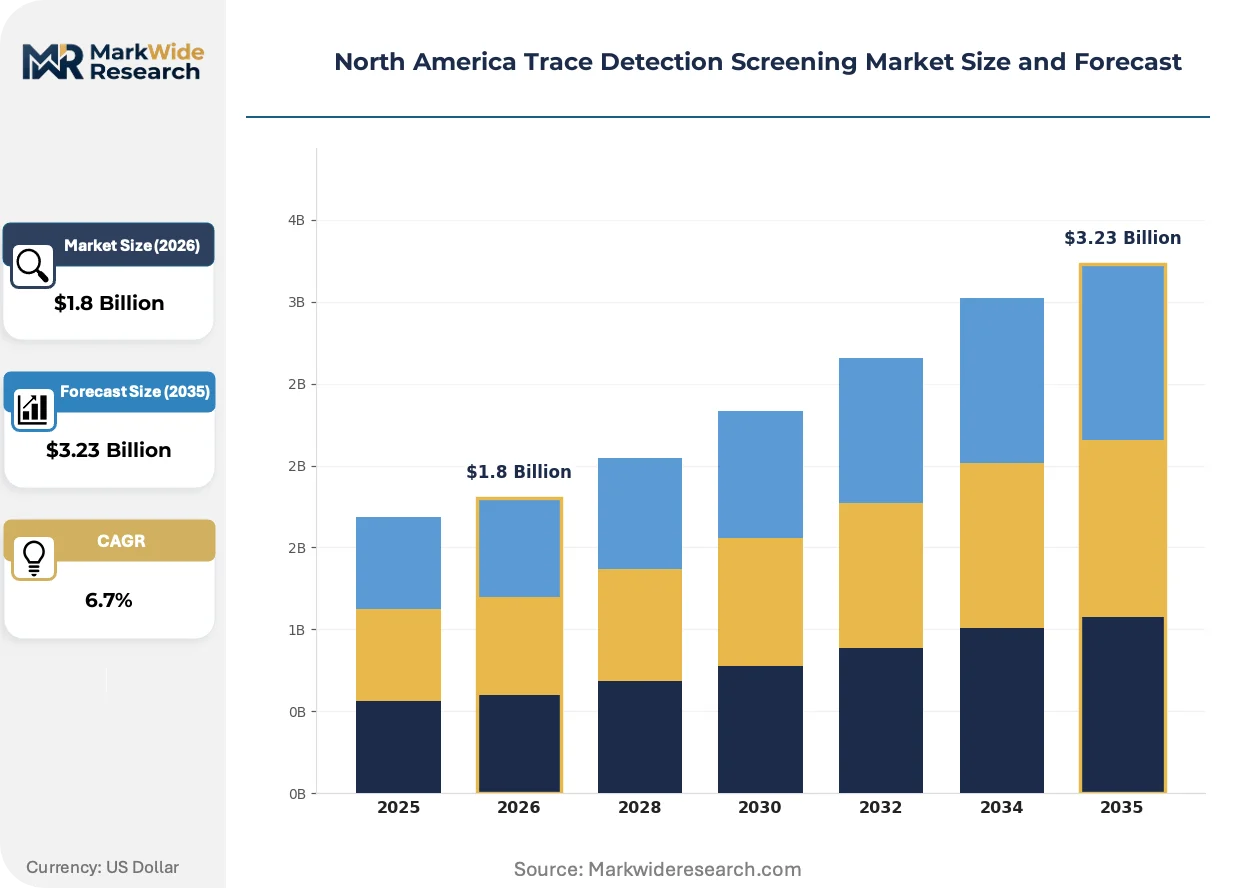
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ion Mobility Spectrometry, Gas Chromatography, Mass Spectrometry, Surface Acoustic Wave End User: Defense, Transportation, Homeland Security, Law Enforcement Technology: Optical, Chemical, Biological, Electronic Application: Airport Security, Border Control, Event Security, Facility Screening |
| Companies Covered | Bruker Corporation, Rapiscan Systems Inc., Smiths Detection Group Ltd., Chemring Group PLC, Leidos Holdings Inc., L3Harris Technologies Inc., Thermo Fisher Scientific Inc., Autoclear, LLC., Teledyne FLIR LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Trace Detection Screening Market Trends and Innovations
Detection modality selection is splitting along performance-versus-portability lines as end-users confront diverging operational requirements. Three forces are compressing traditional technology boundaries.
Mass spectrometry is bifurcating the premium segment from portable workhorse deployments. Forensic laboratories at FBI regional facilities and RCMP technical centers demand molecular specificity for court-admissible evidence, accepting benchtop form factors. Field security managers at border crossings and event perimeters prioritize ten-second alarm resolution over structural identification, locking in ion mobility spectrometry for volume applications. The technology split is compressing vendor R&D allocation between irreconcilable performance targets.
TSA's Checkpoint Property Screening System (CPSS) procurement specifications and CATSA's harmonized Canadian requirements are mandating open-architecture software interfaces. Equipment vendors must decouple detection hardware from threat library updates, enabling over-the-air signature expansion without hardware retrofit. This regulatory pressure is fragmenting traditional integrated-system margins and forcing modular design investments.
Service contract unbundling is disrupting long-term vendor lock-in at U.S. federal installations. TSA's Total Lifecycle Cost evaluation criteria separate hardware acquisition from maintenance, calibration, and threat library subscriptions. Prime contractors now compete against third-party service specialists for post-warranty revenue streams. The purchasing pattern shift is most visible at Category X airports where procurement autonomy has expanded under recent federal delegation pilots.
North America Trace Detection Screening Market Segmentation
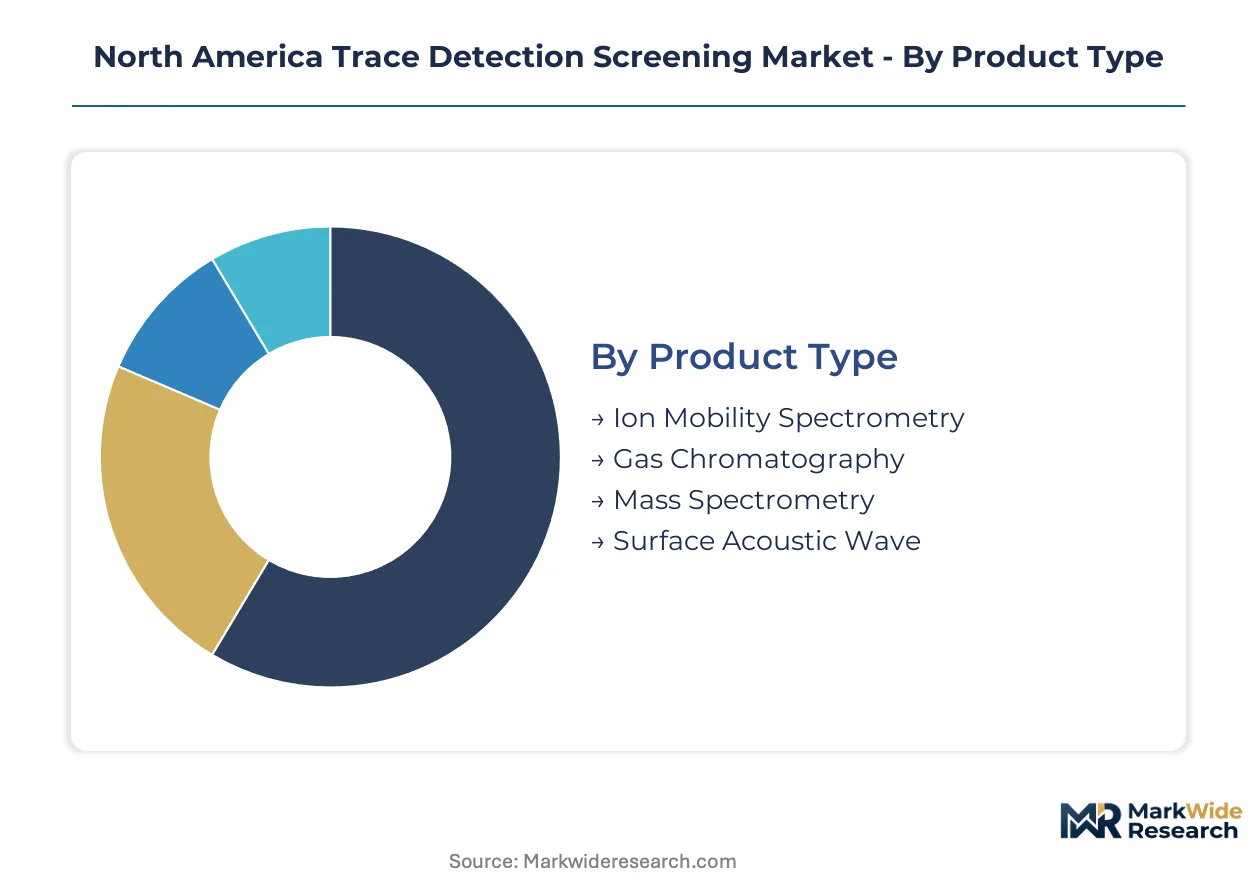
Technology selection in trace detection screening splits procurement channels between high-throughput aviation checkpoints and precision-oriented forensic laboratories. End-use concentration varies sharply by threat vector, with explosive detection dominating federal contracts while narcotics screening drives municipal law enforcement refresh cycles.
Product Type:
Channel mix splits sharply: ion mobility spectrometry and surface acoustic wave systems flow through TSA's consolidated procurement vehicles, while mass spectrometry and gas chromatography platforms sell direct to forensic laboratories and reference facilities.
- Ion Mobility Spectrometry:Portable analyzers separate ionized molecules through drift tubes under electric fields, achieving sub-ten-second alarm resolution. Demand concentrates at Los Angeles International Airport, Chicago O'Hare, and Toronto Pearson where TSA and CATSA mandate high-throughput passenger screening without throughput degradation.
- Mass Spectrometry:Laboratory-grade platforms deliver molecular specificity through mass-to-charge ratio measurement, enabling court-admissible forensic evidence. FBI regional facilities and RCMP technical centers in Ottawa drive procurement as false-alarm-rate mandates from SAE AMS-STD-2175 exceed ion mobility capabilities.
- Gas Chromatography:Fixed-site reference systems separate volatile compounds through chromatographic columns for definitive compound identification. Mature demand centers on U.S. Department of Homeland Security forensic laboratories requiring validated protocols for precursor chemical analysis.
- Surface Acoustic Wave:Compact sensors detect mass loading on piezoelectric substrates through frequency shifts, enabling handheld form factors. Event security deployments at stadiums and convention centers in Dallas, Atlanta, and Vancouver represent emerging demand channels beyond aviation infrastructure.
Ion mobility spectrometry dominates installed base across North American aviation checkpoints. Mass spectrometry is where expansion concentrates as forensic admissibility requirements harden.
End User:
Cost tier stratification separates federally funded defense installations from municipally budgeted law enforcement agencies, with homeland security grants bridging procurement capability gaps.
- Defense:Military installations require multi-threat detection spanning explosives, chemical warfare agents, and biological pathogens. U.S. Department of Defense procurement through Defense Logistics Agency channels specifies MIL-STD environmental ruggedization for forward deployment scenarios.
- Transportation:Aviation security mandates from TSA and CATSA drive the largest volume procurement, with checkpoint modernization programs at Category X airports consuming ion mobility spectrometry fleets in thousand-unit quantities.
- Homeland Security:Federal building protection and port security operations access dedicated grant funding streams, with Customs and Border Protection border crossings representing high-priority deployment zones for trace detection modernization.
- Law Enforcement:Municipal police departments and state trooper units deploy handheld narcotics trace detectors for field interdiction, with DEA scheduled substance list updates forcing analyte library refresh cycles across county and state budgets.
Transportation commands procurement volume leadership. Law enforcement represents the steepest expansion trajectory as fentanyl precursor monitoring mandates cascade to municipal agencies.
Technology:
Application context determines modality selection, with optical and chemical detection saturating checkpoint environments while biological platforms face extended FDA validation timelines.
- Optical:Spectroscopic methods including Raman and infrared absorption enable non-contact threat identification. Border control checkpoints along the U.S.-Mexico corridor deploy portable optical analyzers for cargo screening without sample destruction.
- Chemical:Ion mobility and mass spectrometry platforms anchor explosive and narcotics detection across all major end-use segments. SAE AMS-STD-2175 qualification cycles rotate vendor eligibility based on chemical detection performance benchmarks.
- Biological:PCR and immunoassay-based platforms identify pathogen signatures through nucleic acid or antigen detection. FDA oversight of biological threat detection assays imposes multi-year approval timelines that freeze product roadmaps for anthrax and ricin screening applications.
- Electronic:Surface acoustic wave and electrochemical sensors provide compact, low-power alternatives for event security and facility screening where laboratory infrastructure is unavailable.
Chemical detection dominates current deployment. Biological platforms face revenue recognition delays from regulatory validation requirements.
Application:
Maturity gradients separate established aviation security protocols from emerging event security channels, with facility screening representing mid-cycle adoption between these poles.
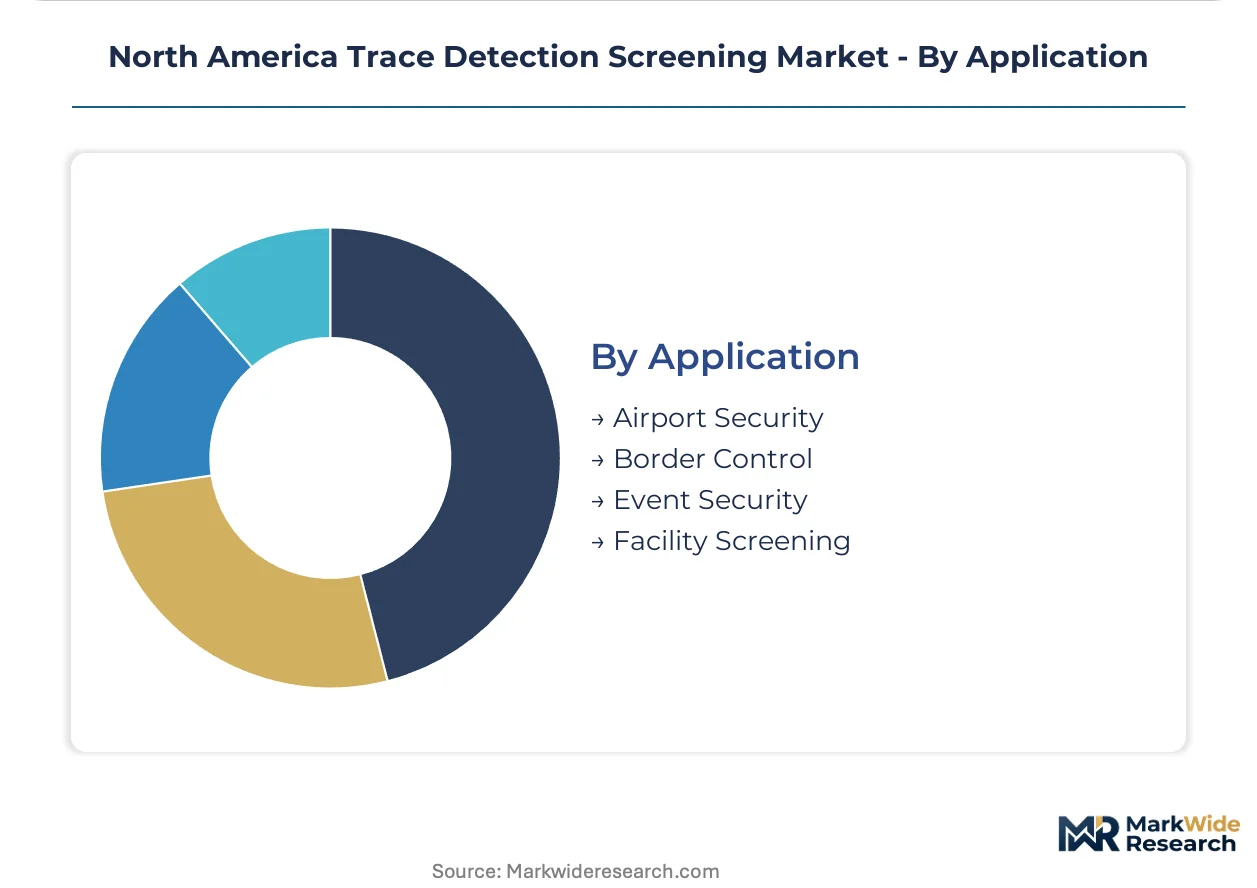
- Airport Security:TSA's next-generation checkpoint protocols and CATSA's harmonized Canadian requirements mandate wholesale replacement of aging detection fleets. Los Angeles International Airport, John F. Kennedy International Airport, and Toronto Pearson anchor regional procurement concentration.
- Border Control:U.S. Customs and Border Protection land ports of entry and Canada Border Services Agency checkpoints deploy vehicle and cargo screening systems. Regulatory harmonization between U.S. and Canadian standards drives cross-border procurement specification alignment.
- Event Security:Stadium and convention center operators deploy handheld and portal trace detectors for temporary threat screening. Surface acoustic wave miniaturization opens deployment channels for Super Bowl, Olympics, and political convention security operations.
- Facility Screening:Federal buildings, courthouses, and critical infrastructure sites implement trace detection for visitor and mail screening. U.S. Department of Homeland Security grant programs fund non-aviation critical infrastructure modernization at ports and rail terminals.
Airport security commands technology investment scale. Event security is gaining share fastest as surface acoustic wave form factors enable temporary deployment economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TSA's next-generation checkpoint protocols and CATSA's harmonized Canadian requirements are compressing procurement cycles across North American aviation infrastructure. Federal grant programs and precursor chemical monitoring mandates are cascading threat detection modernization to municipal agencies and border installations.
United States
Category X airports anchor the largest volume procurement, with Los Angeles International Airport and Chicago O'Hare consuming ion mobility spectrometry fleets in thousand-unit quantities. The U.S. Drug Enforcement Administration's scheduled substance list updates force analyte library expansions across federal security installations. FBI regional facilities and Customs and Border Protection land ports of entry drive demand for molecular specificity in forensic and cargo screening applications.
Canada
Toronto Pearson, Vancouver International, and Montreal-Trudeau airports are deploying multi-threat detection systems under Health Canada's evolving chemical threat regulations. The Canadian Air Transport Security Authority mandates false-alarm-rate thresholds that filter vendor participation in checkpoint modernization. RCMP technical centers in Ottawa anchor laboratory-grade mass spectrometry procurement for court-admissible forensic evidence.
Mexico
Underpenetrated airport infrastructure presents positioning opportunities as regulatory harmonization with U.S. standards advances through bilateral security cooperation frameworks. The Mexico City Metro and Nuevo León industrial corridor represent initial deployment zones for trace detection modernization. Border control checkpoints along the U.S.-Mexico corridor are expanding cargo screening capabilities to align with U.S. Customs and Border Protection specifications.
North America Trace Detection Screening Market Competitive Landscape
Player mix skews toward defense-integrated conglomerates and analytical instrumentation specialists with established SAE AMS-STD-2175 qualification cycles. Market structure concentrates around vendors with sustained engineering investment capacity for federal recertification timelines. Two strategic archetypes dominate: mass spectrometry R&D-intensive platforms commanding laboratory-grade margins, and ion mobility spectrometry providers optimized for high-throughput checkpoint volume. Competitive moves center on modular open-architecture design investments and service contract unbundling to capture post-warranty revenue streams.
Within the defense-integrated tier, L3Harris Technologies Inc. and Leidos Holdings Inc. occupy positions shaped by channel control across U.S. federal security contracts. Among analytical instrumentation specialists, Bruker Corporation exemplifies premium-tier positioning anchored to mass spectrometry R&D intensity. Smiths Detection Group Ltd. represents geographic concentration at major Canadian transit hubs, illustrating how vendor eligibility rotates through qualification cycles without guaranteed procurement awards.
| Leading Market Players |
|---|
| Bruker Corporation |
| Rapiscan Systems Inc. |
| Smiths Detection Group Ltd. |
| Chemring Group PLC |
| Leidos Holdings Inc. |
| L3Harris Technologies Inc. |
| Thermo Fisher Scientific Inc. |
| Autoclear, LLC. |
| Teledyne FLIR LLC |
| Others |
Pricing and Supply Chain Analysis
Twelve-to-eighteen-month qualification cycles for SAE AMS-STD-2175 certification compress vendor margins while concentrating pricing power among incumbents with sustained engineering investment capacity. TSA's consolidated procurement vehicles and CATSA's harmonized specifications amplify buyer leverage at the top of the supply chain, forcing tiered cost absorption through the vendor base.
Pricing Analysis
Certification level (SAE AMS-STD-2175 qualified versus non-qualified) creates the primary spread between premium laboratory-grade platforms and volume checkpoint equipment. Three-tier pricing structure across forensic-grade, aviation-certified, and municipal law enforcement tiers reflects performance thresholds and false-alarm-rate mandates. Cost compression in ion mobility spectrometry segments intensifies as TSA's next-generation protocols force premature obsolescence of installed base. Municipal law enforcement agencies exhibit highest price sensitivity due to county budget constraints, while FBI regional facilities and RCMP technical centers prioritize molecular specificity over unit cost.
Supply Chain Analysis
Helium-3 reserve concentration in U.S. federal stockpiles creates critical input chokepoint for neutron detection subsystems, amplifying cost volatility across multi-threat detection platforms. Manufacturing concentration in the United States, Germany, and the United Kingdom feeds specialized detector components and precision ionization sources. Supply chain risk centers on single-source vulnerability for helium-3 extraction from nuclear weapons stockpile decay and rare earth magnet sourcing for drift tube assemblies. Distribution runs through defense logistics channels for federal contracts, direct OEM relationships for forensic laboratories, and regional integrators for municipal law enforcement deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TSA's next-generation checkpoint protocols and mass spectrometry miniaturization represent dual technological inflections reshaping competitive boundaries. The market's 6.70% CAGR trajectory rewards positioning ahead of regulatory mandate cascades.
For Market Incumbents: Compound channel control advantages at Category X airports by securing open-architecture software interface certifications ahead of CATSA harmonization deadlines. Deepen backward integration into ionization source manufacturing to offset helium-3 supply volatility. Lock in multi-year threat library subscription contracts before TSA's Total Lifecycle Cost evaluation criteria fully separate hardware from service revenue streams. For New Entrants and Emerging Players: Anchor in Mexico's underpenetrated airport infrastructure and Nuevo León industrial corridor where regulatory harmonization with U.S. standards advances through bilateral security frameworks. Target surface acoustic wave handheld formats for event security deployments at stadiums and convention centers beyond aviation's consolidated procurement concentration. Pursue direct municipal law enforcement channel relationships bypassing federal procurement vehicle barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from defense conglomerates seeking to divest non-core analytical instrumentation divisions amid portfolio rationalization pressures. Five-to-ten-year viability hinges on modular platform architectures enabling threat library expansion without hardware retrofit. Monitor SAE AMS-STD-2175 recertification timelines as inflection signal for vendor eligibility rotation and consolidation opportunity windows.| Strategic Initiative | Industry Significance |
|---|---|
| Open-Architecture Certification | Decoupling detection hardware from threat library updates enables recurring revenue streams at TSA-mandated checkpoints. |
| Helium-3 Alternative Sourcing | Boron-10 or lithium-6 neutron detection substitutes reduce supply security exposure from federal reserve concentration. |
| Surface Acoustic Wave Miniaturization | Handheld form factors unlock stadium and convention center deployments beyond aviation procurement concentration. |
| Mexico Regulatory Harmonization | Bilateral security cooperation frameworks position first-mover advantage in underpenetrated airport infrastructure. |
| Service Contract Unbundling | Third-party calibration and maintenance specialists capture post-warranty revenue as TSA separates hardware from lifecycle costs. |
Research Methodology
Initial hypotheses were tested against primary input from TSA procurement officers, CATSA specification engineers, FBI forensic laboratory directors, and municipal police equipment coordinators and refined through secondary validation. Primary research drew from customs and trade data, SAE qualification registry filings, DHS grant award databases, and SEC 10-K disclosures from analytical instrumentation specialists. Bottom-up segment sizing triangulated against top-down federal budget allocation analysis across the analysis window.
Variance decomposition across technology modality, end-use sector, and geographic regulatory cluster shaped the analytical framework. CAGRs were derived from installed base replacement cycles, precursor chemical monitoring mandate cascades, and mass spectrometry miniaturization adoption curves. Modeled inputs included TSA checkpoint modernization program schedules, Health Canada explosive precursor regulatory updates, and DEA scheduled substance list expansion timelines.
Decision-makers should treat outputs as directional under sustained federal security funding and helium-3 reserve release assumptions; material deviation would warrant model refresh. Forecasts embed assumptions regarding regulatory harmonization velocity and certification cycle stability. Practitioners should keep alternative scenarios live as SAE AMS-STD-2175 specification revisions and Mexico bilateral framework implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Technology
Global Weather Forecasting Systems Market
Analytical Technology
Digital Smell Technology Market
Analytical Technology
United States Computational Fluid Dynamics Market
Analytical Technology
AI-Powered Video Analytics Market
Analytical Technology
Motion Simulation Market
Analytical Technology
Incubator Analyzer Market
Analytical Technology
Brain Fingerprinting Technology Market
Analytical Technology
Emission Monitoring Software Market
Analytical Technology
Global Advanced Visualization Market
Analytical Technology
Process Analyzer Market
Analytical Technology
Global Optical Character Recognition Market
Analytical Technology
Computational Fluid Dynamics (CFD) Market
Analytical Technology
Europe Computational Fluid Dynamics Market
Analytical Technology
Asia-Pacific Digital Scent Technology Market