
 3D Printing Software Market | 2026-2036
3D Printing Software Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Software Market Analysis
Enterprise-grade simulation fidelity is reorganizing competitive dynamics across the 3D printing software landscape. Autodesk Inc. leverages cloud-native architecture to extend its presence in design-to-print workflows. Materialise NV anchors its position through deep specialization in medical segmentation and build preparation. Siemens dominates industrial digital thread integration by connecting additive manufacturing execution with broader factory automation systems.
3D printing software encompasses the digital toolchain that translates geometric models into machine-executable instructions, incorporating mesh repair algorithms, support generation logic, thermal simulation kernels, and G-code optimization routines to enable layer-by-layer fabrication across polymer, metal, and ceramic substrates. Slicing software captures the largest margin pool due to its direct coupling with hardware throughput and material efficiency, while cloud-based deployment models are expanding fastest as distributed engineering teams demand real-time collaboration across prototyping and production scenarios. Design software retains structural importance for upstream model integrity, though its growth rate trails simulation-integrated platforms that reduce print failure rates before physical commitment.
FDA 21 CFR Part 820 quality system requirements and EMA MDR software validation protocols are elevating compliance costs for medical applications while creating barrier-to-entry advantages for vendors with established audit trails. China's GB standards for additive manufacturing equipment, administered by SAMR, are mandating interoperability testing that favors domestic software-hardware pairings in state-backed industrial zones. Stakeholders must monitor how evolving cybersecurity frameworks for connected manufacturing systems reshape liability allocation between software publishers and end-users operating distributed print fleets.
Market Dynamics
Simulation-integrated slicing platforms are compressing design-to-print cycles across aerospace and medical verticals, forcing software vendors to embed thermal modeling and failure prediction directly into build preparation workflows or cede position to specialized competitors.
Growth Catalysts
- FDA 21 CFR Part 820 traceability mandates:Medical device manufacturers in the United States must document software validation chains, creating durable demand for audit-ready build preparation suites.
- Industrial cluster concentration in Shenzhen:China's additive manufacturing equipment makers are bundling proprietary slicing tools with hardware exports, expanding the addressable base for localized software licensing.
- Titanium lattice thermal simulation:Aerospace engineers now require predictive distortion modeling for thin-wall geometries, pulling advanced solver capabilities into standard pre-print workflows.
Market Restraints
- GPU compute cost volatility:Cloud-based simulation kernels depend on NVIDIA data center capacity, with spot pricing swings directly squeezing SaaS gross margins.
- Legacy CAD format lock-in:Proprietary mesh formats from Dassault Systèmes and PTC create interoperability friction that slows multi-vendor toolchain adoption.
- Open-source slicer substitution:Cura and PrusaSlicer community editions capture hobbyist and education segments, capping pricing power at the entry tier.
Strategic Opportunities
- EMA MDR software validation protocols:European medical device regulation creates compliance service revenue streams for vendors with established notified body relationships.
- Copper and ceramic multi-material workflows:Electronics cooling and dental implant applications require new support generation algorithms that incumbent platforms have not yet optimized.
- India's PLI scheme for additive manufacturing:Domestic equipment production incentives are creating localized software customization demand in Bengaluru and Pune industrial corridors.
Industry Challenges
- Computational geometry specialist scarcity:Mesh repair algorithm development requires rare cross-training in topology optimization and GPU kernel programming.
- Cross-platform certification timelines:Validating identical build outcomes across Stratasys, EOS, and HP hardware fleets extends qualification cycles for regulated medical production.
- Cloud-native security architecture:Distributed engineering teams expose IP-sensitive CAD files to breach risks that on-premise legacy installations did not face.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Software Market |
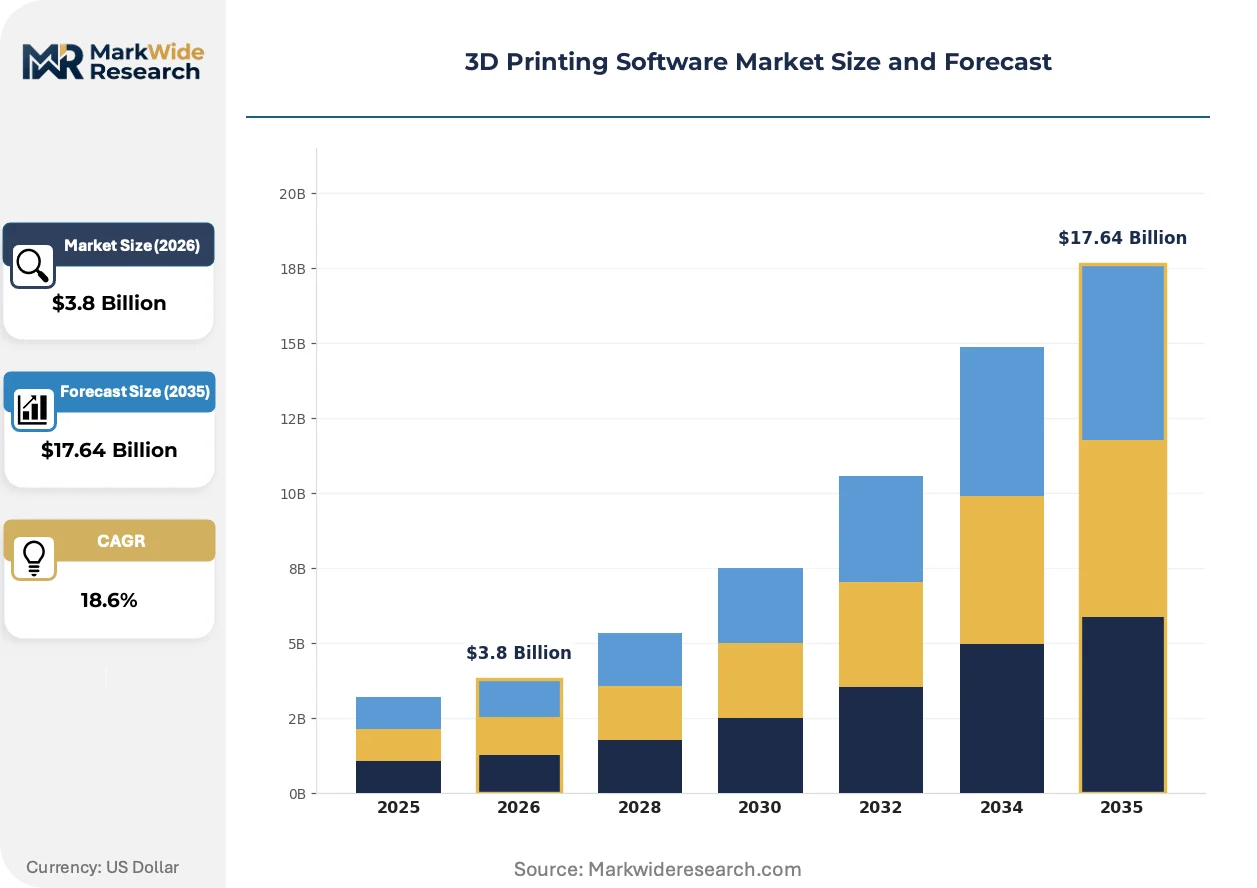
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Slicing Software, Modeling Software, Design Software, Printing Management Software Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Aerospace, Automotive, Healthcare, Education Usage Scenario: Prototyping, Production, Customization, Tooling |
| Companies Covered | Autodesk Inc., 3D Systems Inc., Materialise NV, Dassault Systèmes, PTC Inc., Ansys Inc., Stratasys Ltd., Siemens, Altair Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Software Market Emerging Trajectories
Real-time collaborative workflows are collapsing the sequential handoffs between design, simulation, and machine programming that previously stretched project timelines across weeks.
Physics-informed neural networks are supplanting finite element solvers for first-pass thermal distortion estimates. Tier-one aerospace suppliers in Germany now run generative pre-simulations in under thirty seconds that previously required overnight cluster jobs. This compression is enabling same-day design iteration cycles that reshape competitive bidding dynamics for urgent tooling contracts.
REACH substance restrictions on photopolymer resin constituents are forcing formulation transparency disclosures from European material suppliers. Software platforms must now embed chemical composition tracking to maintain build traceability for medical and aerospace auditors. Vendors without material database integration face exclusion from qualified supplier lists at Safran and Airbus Hamburg operations.
Subscription pricing for simulation modules is displacing perpetual licenses among mid-market job shops. North American contract manufacturers prefer monthly cloud access that scales with project volume rather than capitalizing enterprise seats. This preference shift favors vendors with granular usage metering over those locked into traditional enterprise sales motions.
3D Printing Software Market Segmentation
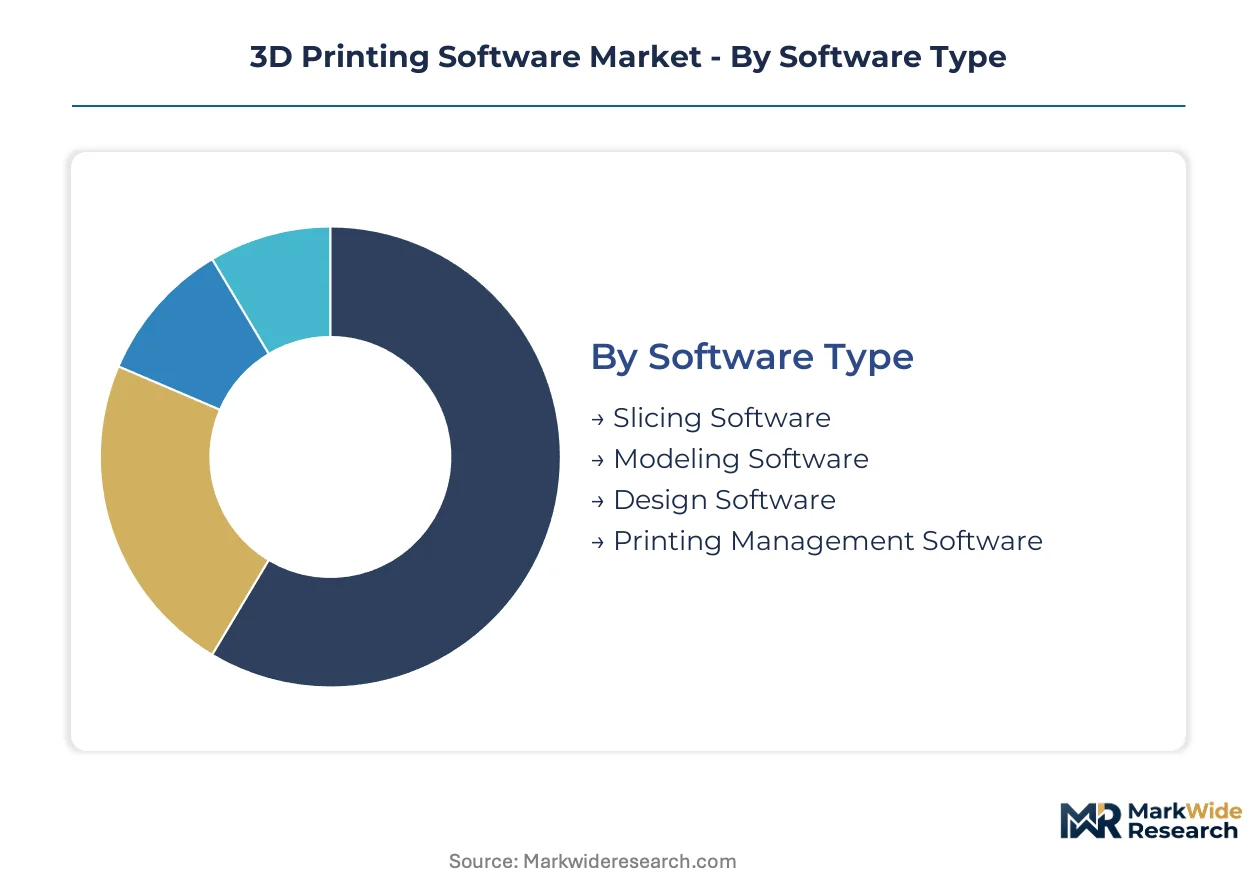
Segmentation in 3D printing software reveals how procurement patterns diverge between regulated industrial users and agile prototyping teams. Channel strategy must align with deployment complexity, as aerospace manufacturers demand on-premise validation chains while distributed design shops favor consumption-based cloud access.
Software Type:
Slicing software flows through hardware OEM bundling channels and direct enterprise licensing. Modeling and design tools distribute via CAD platform marketplaces and value-added reseller networks serving vertical specialists.
- Slicing Software:Translates solid models into machine-executable G-code through adaptive layer height algorithms and infill pattern optimization. Demand concentrates in Germany's aerospace supplier network, where EOS and Stratasys users require build preparation suites that interface directly with metal powder bed systems. Thermal simulation integration is becoming mandatory for titanium lattice structures.
- Modeling Software:Parametric and mesh-based geometry engines enable topology optimization and generative design workflows. Medical device manufacturers in the United States drive specialized demand through FDA 21 CFR Part 820 validation requirements for patient-specific implant modeling.
- Design Software:Upstream CAD tools ensuring watertight manifold geometry before downstream processing.
- Printing Management Software:Fleet orchestration platforms monitoring distributed printer networks and material inventory.
Slicing software dominates installed base. Printing management software is where expansion concentrates.
Deployment Model:
Cost tier segmentation separates capital-intensive perpetual licenses from operational expenditure models favored by mid-market job shops. Security architecture and compliance overhead determine channel viability across regulated versus non-regulated end uses.
- Cloud-Based:Browser-accessible platforms enabling real-time collaboration across distributed engineering teams. North American contract manufacturers prefer monthly metering that scales with project volume rather than capitalizing enterprise seats.
- SaaS:Subscription modules for simulation kernels where GPU compute costs pass through to end users. Pricing volatility in NVIDIA data center spot markets directly squeezes vendor gross margins.
- On-Premises:Air-gapped installations mandatory for ITAR-controlled defense work and pharmaceutical IP protection.
- Hybrid:Split architectures keeping sensitive CAD files local while outsourcing compute-intensive thermal simulations.
On-premises retains share in regulated verticals. Cloud-based deployment is climbing the fastest.
End User:
Application-driven segmentation maps software capability requirements to industry-specific validation protocols. Aerospace and healthcare impose the steepest compliance burdens, while education and automotive prototyping prioritize accessibility and iteration speed.
- Healthcare:Patient-specific surgical guides and implant workflows requiring DICOM segmentation and biocompatible material traceability. EMA MDR software validation protocols in Europe create compliance service revenue for vendors with notified body relationships.
- Aerospace:Structural qualification for flight-critical components demands distortion prediction and process parameter locking. Airbus Hamburg and Safran operations exclude vendors without integrated material database transparency.
- Automotive:Rapid tooling and j fixture production for assembly line customization.
- Education:Curriculum integration and hobbyist accessibility through open-source slicer derivatives.
Healthcare commands premium pricing tiers. Aerospace represents the deepest vertical integration opportunity.
Usage Scenario:
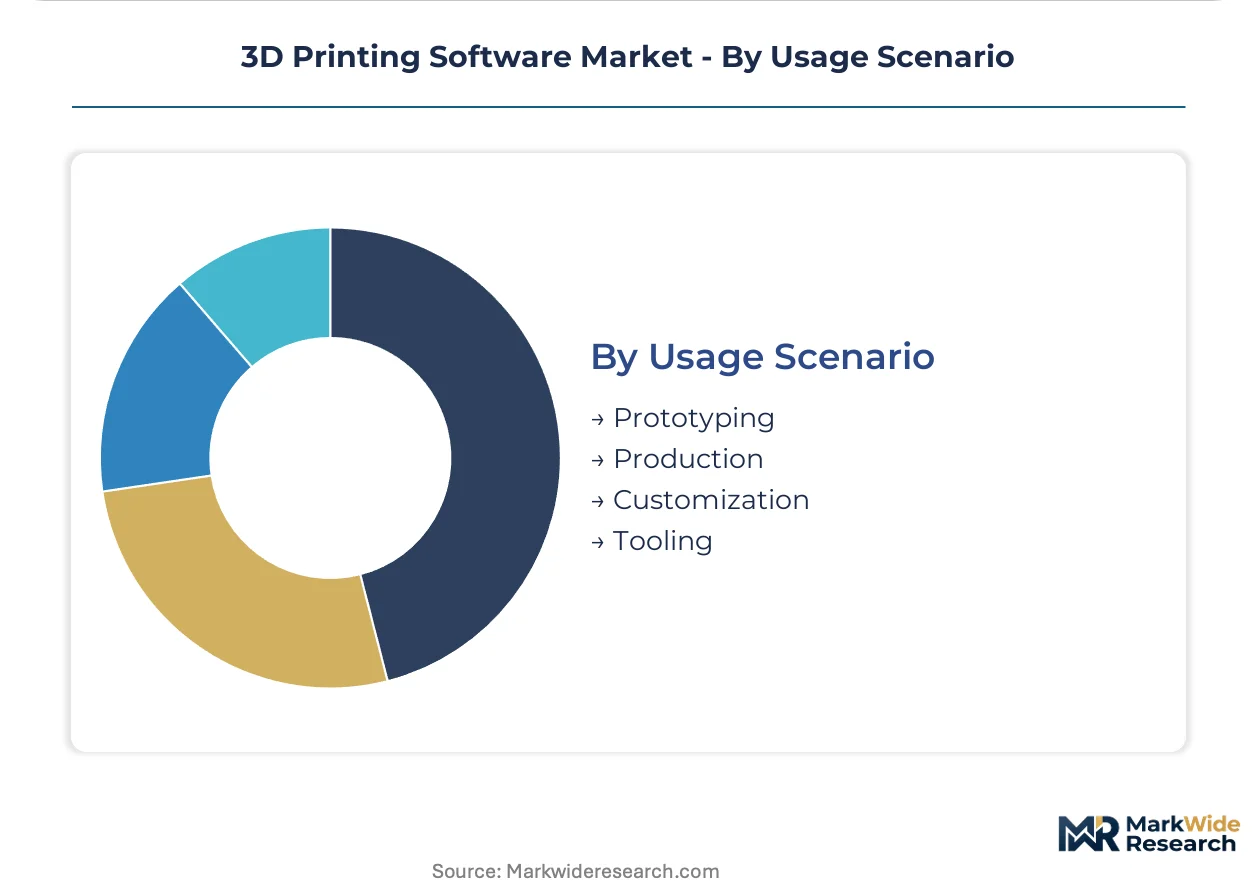
Volume and maturity segmentation separates experimental prototyping from qualified production workflows. Customer type determines whether software procurement centers on per-seat design tools or enterprise-wide manufacturing execution integration.
- Production:Validated process parameters locked for regulatory submission and lot traceability. Shenzhen industrial clusters bundle proprietary slicing with hardware exports, expanding localized licensing bases.
- Tooling:Direct manufacturing of injection mold inserts and assembly fixtures compressing lead times from weeks to days. India's PLI scheme for additive manufacturing drives customization demand in Bengaluru and Pune corridors.
- Prototyping:Iterative design validation without formal process qualification requirements.
- Customization:Mass personalization workflows for dental aligners and consumer products.
Prototyping retains volume leadership. Production workflows are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. North American aerospace buyers absorb premium pricing for validated compliance chains. Asian contract manufacturers prioritize per-seat cost efficiency over simulation depth.
United States
FDA 21 CFR Part 820 traceability mandates drive durable demand for audit-ready build preparation suites among medical device manufacturers. The agency's software validation requirements elevate compliance costs while creating barrier-to-entry advantages for established vendors. Aerospace suppliers in California and Texas concentrate procurement around simulation-integrated slicing platforms for titanium lattice structures.
Germany
Airbus Hamburg and Safran operations exclude vendors without integrated material database transparency for REACH compliance. The country's aerospace supplier network demands thermal simulation integration as mandatory capability for metal powder bed systems. Industrial clusters around Munich and Hamburg anchor procurement of distortion prediction software for flight-critical components.
China
GB standards administered by SAMR mandate interoperability testing that favors domestic software-hardware pairings. The country's dual carbon goals accelerate adoption of material-efficient slicing algorithms in state-backed industrial zones. Equipment makers in Shenzhen bundle proprietary slicing tools with hardware exports, expanding localized licensing bases.
India
The PLI scheme for additive manufacturing creates localized software customization demand among domestic equipment producers. CDSCO's emerging software validation frameworks for medical devices are tightening documentation requirements for patient-specific implant workflows. Bengaluru and Pune industrial corridors concentrate procurement of fleet orchestration platforms for distributed print networks.
Japan
METI's industrial digitalization initiatives subsidize cloud-native design-to-print workflow adoption among precision manufacturers. JIS standards for additive manufacturing equipment create certification pathways that favor vendors with established domestic partnerships. Industrial concentrations in Nagoya and Osaka prioritize build preparation suites with direct machine control integration.
3D Printing Software Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the 3D printing software landscape. The market structure separates consolidated upstream design platforms from fragmented downstream build preparation specialists. Three archetypes dominate: cloud-native CAD-integrated suites, medical-specialized segmentation platforms, and industrial automation-anchored digital thread providers. Strategic moves center on M&A for solver capability acquisition and geographic expansion through hardware OEM bundling partnerships.
Among established software houses, Autodesk Inc. and Dassault Systèmes occupy positions representing design-to-print workflow integration. Materialise NV exemplifies the medical-specialized archetype through deep segmentation and build preparation focus. Siemens anchors the industrial digital thread tier, connecting additive manufacturing execution with broader factory automation systems. These three represent distinct competitive vectors rather than direct substitutes.
| Leading Market Players |
|---|
| Autodesk Inc. |
| 3D Systems Inc. |
| Materialise NV |
| Dassault Systèmes |
| PTC Inc. |
| Ansys Inc. |
| Stratasys Ltd. |
| Siemens |
| Altair Engineering |
| Others |
Supply Flow & Price Mechanics
FDA 21 CFR Part 820 and EMA MDR validation protocols gate both supplier qualification and price differentiation in medical-grade 3D printing software, compressing margins for uncertified vendors while enabling premium capture by audit-ready incumbents. Aerospace OEMs in Germany and the United States absorb elevated pricing for simulation-integrated platforms, whereas Asian contract manufacturers prioritize per-seat cost efficiency over solver depth.
Pricing Analysis
After-sales revenue from validation support contracts and regulatory documentation services drives lifetime value for enterprise vendors. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical suites from mid-market SaaS subscriptions and open-source community editions. Cost compression in cloud-based simulation tiers is intensifying because NVIDIA GPU spot pricing volatility squeezes vendor gross margins. Medical device manufacturers show lowest price sensitivity due to compliance lock-in, while education and hobbyist segments capture open-source substitution.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes disrupt hardware-software bundling shipments from Shenzhen and Shanghai industrial clusters. Software development concentrates in the United States, Germany, and China, with cloud infrastructure resting on hyperscaler data centers in Virginia, Frankfurt, and Singapore. Single-source vulnerability characterizes GPU accelerator supply from NVIDIA. Distribution runs through hardware OEM bundling channels, direct enterprise licensing, and CAD platform marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among aerospace OEMs and medical device consolidators, compressing vendor margins and favoring scale players with compliance infrastructure. Procurement committees at tier-one manufacturers now demand end-to-end digital thread integration.
For Market Incumbents: Shield installed base erosion by embedding thermal simulation kernels directly into build preparation workflows before specialized competitors capture aerospace procurement. Deepen backward integration into GPU cloud capacity to buffer margin pressure from spot pricing volatility. Prioritize FDA 510(k) companion documentation services to lock medical device accounts against emerging SaaS entrants. For New Entrants and Emerging Players: EMA notified body fast-track partnerships open white-space penetration in European medical device compliance services. India's PLI scheme for additive manufacturing equipment creates localized customization demand in Bengaluru and Pune corridors underserved by incumbent medical specialists. Target copper and ceramic multi-material workflow algorithms as unoptimized capability gaps in current platforms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as distributed engineering teams displace on-premise validation chains. Long-term viability favors acquisition targets with physics-informed neural network solver IP and established aerospace notified body relationships. Watch for inflection when tier-one OEMs consolidate qualified supplier lists below five vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Physics-informed neural network solver capabilities compress simulation runtime from overnight clusters to sub-minute pre-validation at Airbus Hamburg. |
| Platform Integration | Direct machine control APIs for EOS and Stratasys hardware lock aerospace procurement through validated build parameter chains. |
| Geographic Expansion | Shenzhen equipment bundling partnerships expand localized licensing bases under SAMR GB standards interoperability mandates. |
| Strategic Partnership | EMA notified body relationships create recurring compliance service revenue streams for MDR software validation protocols. |
| Product Launch | Copper thermal management algorithms address electronics cooling applications excluded from incumbent platform roadmaps. |
Methodological Framework
Cross-validation between primary interviews with additive manufacturing software executives and secondary validation through FDA 510(k) filings, EMA MDR submissions, and hyperscaler capex disclosures anchors the qualitative findings. Stakeholder roles span CTOs at industrial software houses, biomedical engineers at medical device OEMs, procurement leads at aerospace tier-one suppliers, and integration specialists at CAD platform vendors. Bottom-up sizing of slicing software deployments triangulates against top-down estimates of hardware installed base and attach rates.
Sensitivity analysis across deployment model adoption curves, GPU compute cost scenarios, and regulatory timeline variations shapes the analytical framework. Segmentation dimensions modeled include software type, deployment architecture, end-use vertical, and geographic adoption pattern. CAGRs derive from regression against hardware shipment trajectories and simulation module attach rate elasticities. Forecast inputs incorporate REACH substance restriction compliance costs and India's PLI scheme localization incentives.
The analysis sits within stated boundaries; outcomes outside sustained cloud infrastructure investment and stable regulatory validation timelines would require recalibration. Forecasts reflect assumptions regarding aerospace qualification cycle durations and medical device software documentation burdens. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Europe Industrial 3D Printing Market
3D Printing Technology
Food 3D Printing Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
Metal 3D Printing Service Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
PEEK Filament Market
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
US Additive Manufacturing Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
Online 3D Printing Service Market