
 Desktop 3D Printing Market | 2026-2036
Desktop 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Desktop 3D Printing Market Intelligence
Modular filament-and-printer bundling is rebalancing how small businesses evaluate total cost of ownership against standalone hardware procurement. Stratasys leverages its materials ecosystem to lock in recurring consumables revenue across installed bases. HP Inc. competes through multi-jet fusion architectures that extend from industrial platforms into compact workshop formats. EOS GmbH anchors its position in polymer powder-bed systems, sustaining premium positioning through open-material strategies that attract engineering-centric buyers.
Desktop 3D printing comprises compact additive manufacturing systems with build volumes typically under 300 mm per axis, employing extrusion, photopolymerization, or powder-bed fusion to produce functional prototypes and end-use components from thermoplastics, photopolymers, or composite feedstocks. These systems serve design iteration, custom manufacturing, and distributed production workflows where low part count and geometric complexity outweigh economies of scale from conventional tooling. FDM systems dominate unit shipments due to mechanical simplicity and material accessibility, while SLA segments capture margin pools in dental and jewelry applications where surface resolution determines value. SLS hardware occupies a narrower but defensible niche in functional nylon prototyping, with powder refresh economics and chamber temperature control representing the primary barriers to desktop price-point entry.
FDA clearance pathways for 510(k) medical devices and EU MDR material traceability requirements shape product development timelines and regional market access for dental and surgical guide applications. ISO 10993 biocompatibility testing and REACH chemical compliance add certification overhead that favors established suppliers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving EPA emissions standards for ultrafine particles in enclosed workspaces, as local occupational safety interpretations could trigger retrofit demand for filtration subsystems or shift procurement toward closed-chamber architectures.
Market Dynamics
Photopolymer formulation certification under EU MDR is restructuring supplier hierarchies, forcing dental laboratories to consolidate procurement around vendors with dedicated regulatory affairs capacity and ISO 10993 testing infrastructure.
Growth Catalysts
- EU MDR material traceability mandates:Dental aligner production in Germany and France now requires certified biocompatible resins, locking laboratories into recurring consumables relationships with compliant suppliers.
- Orthodontic aligner volume:European dental laboratories are scaling resin-based system deployments to capture demand from direct-to-consumer orthodontic brands.
- Technical university clusters:Prototyping demand from RWTH Aachen and TU Munich sustains hardware refresh cycles and filament volume in Germany's industrial corridor.
Market Restraints
- Powder refresh economics:SLS desktop systems require 30-50% virgin powder replenishment per build, compressing margins for nylon prototyping services.
- Ultrafine particle emissions:EPA occupational safety interpretations for enclosed workspaces threaten retrofit costs for open-chamber FDM installations in US workshops.
- Photopolymer supply concentration:Certified resin formulation expertise concentrates among three European chemical suppliers, creating procurement bottlenecks for MDR-compliant dental workflows.
Strategic Opportunities
- Closed-chamber architecture migration:US workshops facing EPA emissions scrutiny present replacement demand for filtered, enclosed systems with integrated ultrafine particle capture.
- Multi-jet fusion format extension:Compact workshop-scale powder-bed systems are expanding into job shop environments previously served by outsourced industrial platforms.
- India PLI scheme leverage:Domestic medical device manufacturing incentives create entry pathways for biocompatible photopolymer systems targeting surgical guide production.
Industry Challenges
- ISO 10993 certification timelines:Biocompatibility testing for new resin formulations extends product development cycles by 18-24 months, delaying revenue recognition.
- Thermoplastic extrusion expertise scarcity:Design-for-additive-manufacturing skills remain concentrated among senior engineers in German and US technical universities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desktop 3D Printing Market |
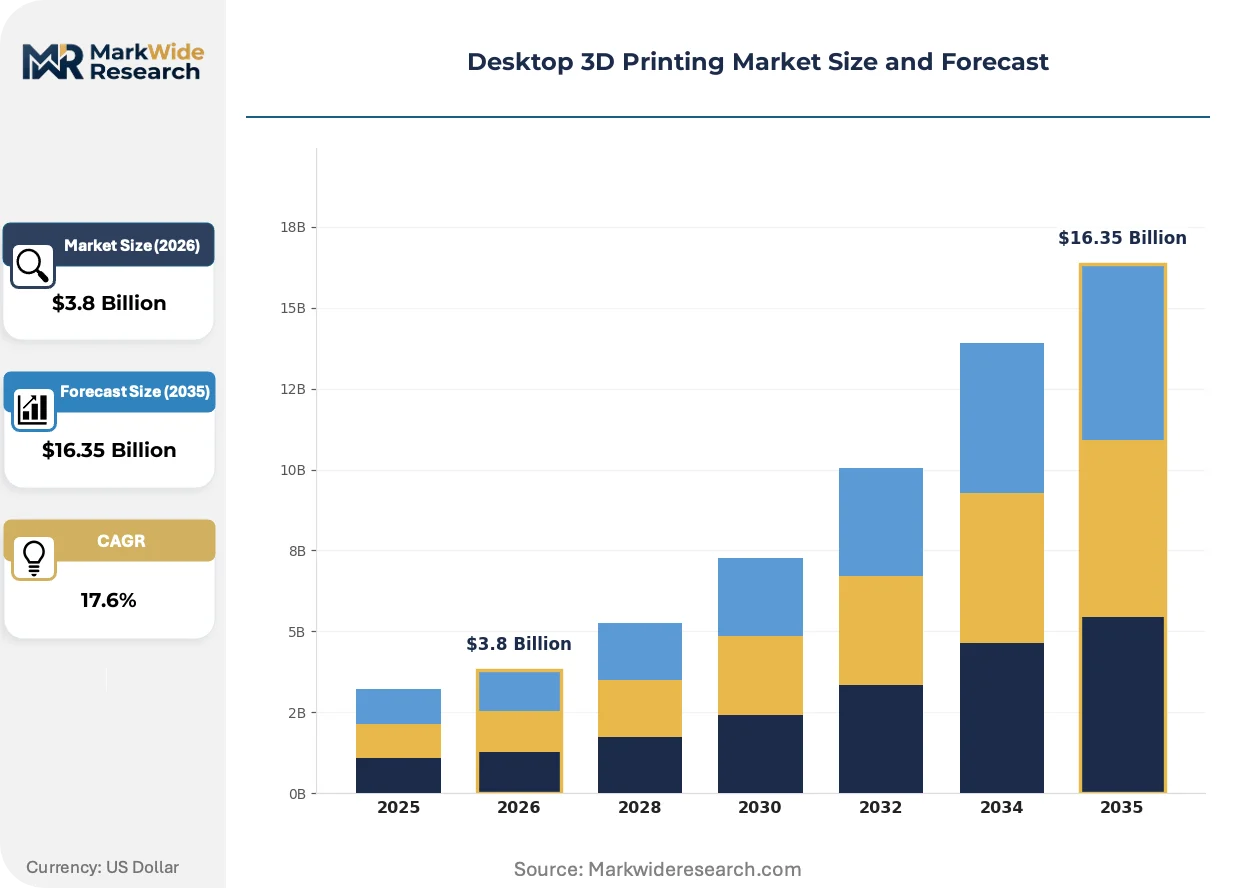
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FDM, SLA, SLS, DLP End User: Education, Prototyping, Dental, Manufacturing Material: PLA, ABS, Nylon, Resin Application: Consumer Products, Engineering Parts, Education Models, Artifacts |
| Companies Covered | Stratasys, 3D Systems, EOS GmbH, HP Inc., Materialise, Desktop Metal, SLM Solutions, Markforged, Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desktop 3D Printing Market Strategic Shifts & Innovations
Hardware architectures are fragmenting along workflow specialization lines, with resin systems optimizing for surface resolution and extrusion platforms competing on material diversity rather than build speed alone.
Continuous liquid interface production is expanding into jewelry and dental applications where layerless surface quality commands premium pricing. Artisan manufacturers in Antwerp and Valenza are adopting these systems to compress finishing labor and reduce stone-setting rework. The technology is expanding into mid-market dental laboratories previously constrained by technician bench time per aligner mold.
REACH chemical compliance expansions are forcing reformulation of photoinitiator packages in European-sold resins. Suppliers with in-house toxicology testing capacity are capturing share from import-dependent distributors. Dental device manufacturers in Italy and Spain are consolidating procurement around REACH-registered suppliers to preempt supply interruption.
Consumables bundling is displacing standalone hardware procurement among small US job shops. Stratasys and Formlabs now structure three-year total cost of ownership contracts that embed filament or resin minimums. Midwest manufacturing clusters show highest uptake, where shop owners prioritize predictable monthly outlays over capital expenditure spikes.
Desktop 3D Printing Market Segmentation
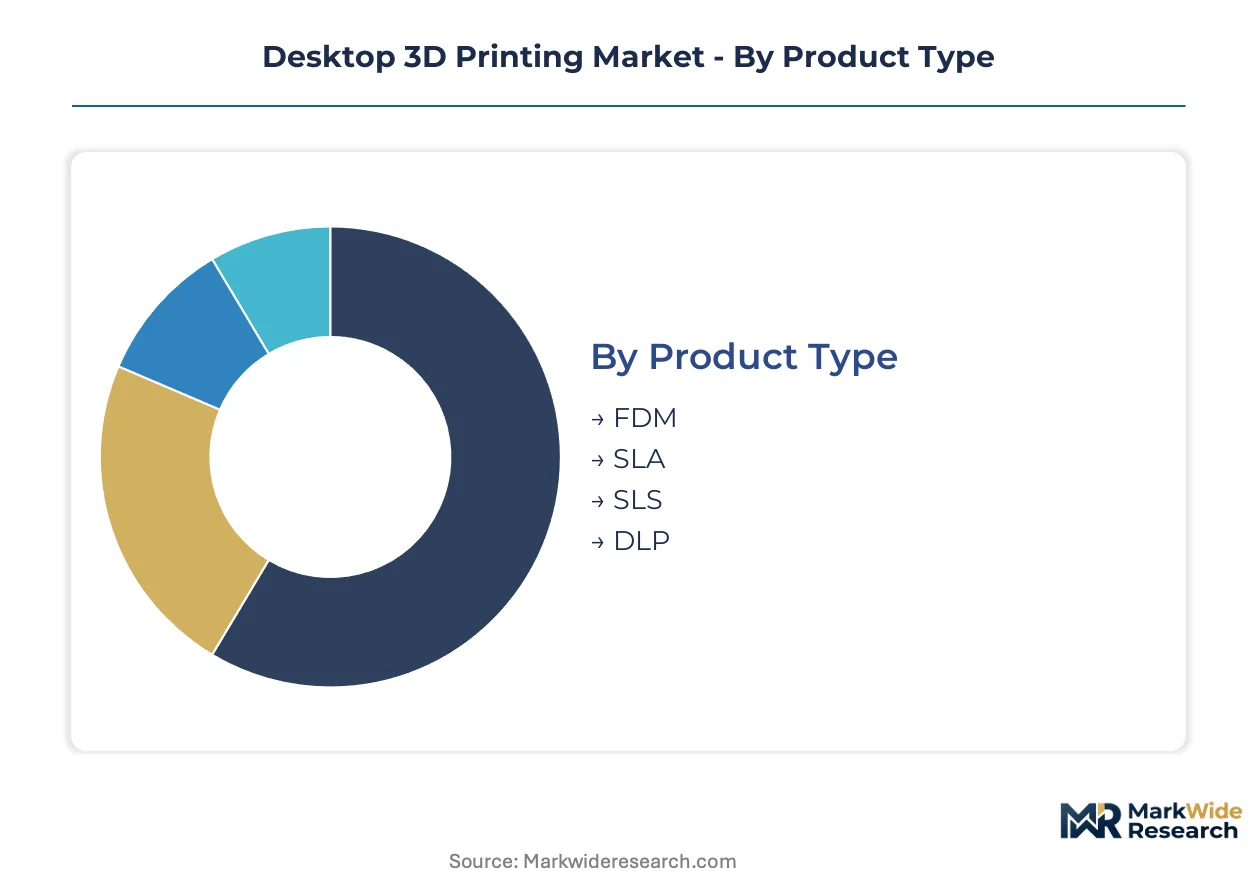
Segmentation in desktop 3D printing reveals how certification requirements, material costs, and workflow specialization fragment procurement patterns across user categories. Each dimension carries distinct regulatory burdens and margin profiles that reshape competitive positioning.
Product Type:
ISO 10993 biocompatibility testing and EU MDR material traceability impose divergent compliance costs across hardware architectures, with resin-based systems facing the heaviest regulatory overhead.
- FDM:Fused deposition modeling extrudes thermoplastic filaments through heated nozzles, building parts layer by layer with mechanical simplicity that minimizes maintenance. Demand concentrates in German technical universities and Midwest US job shops where PLA and ABS accessibility supports iterative prototyping cycles. EPA ultrafine particle emissions scrutiny threatens open-chamber installations with retrofit costs.
- SLA:Stereolithography cures liquid photopolymer with UV lasers, delivering surface resolution below 25 microns that commands premium pricing in dental aligner production. European laboratories in Germany and France now require REACH-registered, MDR-certified resins, locking procurement around compliant chemical suppliers with dedicated toxicology testing infrastructure.
- SLS:Selective laser sintering fuses nylon powder beds with infrared lasers, producing functional parts without support structures. Powder refresh economics requiring 30-50% virgin material replenishment compress margins for job shop operators.
- DLP:Digital light processing projects entire layer images with LED arrays, accelerating build speeds for jewelry manufacturers in Antwerp and Valenza seeking to reduce stone-setting rework.
FDM sits at the top of the volume ranking, with SLA climbing the fastest on dental aligner demand.
End User:
Customer type determines whether procurement prioritizes capital expenditure minimization or total cost of ownership predictability through consumables bundling.
- Education:Universities and technical institutes deploy FDM systems for curriculum integration, with RWTH Aachen and TU Munich sustaining hardware refresh cycles through research grant funding.
- Prototyping:Engineering departments and design studios iterate geometric concepts before tooling commitment, favoring material diversity over build speed.
- Dental:Laboratories across Italy and Spain consolidate procurement around REACH-registered resin suppliers to preempt EU MDR supply interruption, with three-year consumables contracts displacing standalone hardware purchases.
- Manufacturing:Job shops and production floors adopt compact powder-bed systems for low-volume end-use components, extending multi-jet fusion architectures from industrial platforms into workshop formats.
Dental end users are expanding most quickly on aligner volume, with Education retaining the largest installed base.
Material:
Feedstock chemistry dictates whether users face REACH compliance, biocompatibility certification, or simple thermal processing requirements.
- PLA:Polylactic acid derived from corn starch offers low-temperature extrusion and biodegradability, dominating education and consumer entry-level deployments.
- ABS:Acrylonitrile butadiene styrene delivers higher heat resistance and mechanical toughness for functional prototyping in automotive and appliance design workflows.
- Nylon:Polyamide powders in SLS systems produce durable, chemically resistant parts for engineering applications, though powder refresh ratios constrain job shop profitability.
- Resin:Photopolymer formulations for SLA and DLP systems now require ISO 10993 testing and EU MDR traceability, with certified expertise concentrating among three European chemical suppliers.
PLA holds the volume lead, with Resin gaining share fastest on dental certification mandates.
Application:
Output purpose determines whether surface quality, mechanical performance, or geometric complexity drives hardware selection and post-processing investment.
- Consumer Products:Custom jewelry, home accessories, and personalized goods leverage resin systems for surface finish that reduces finishing labor.
- Engineering Parts:Functional prototypes and end-use components in aerospace and automotive supply chains demand SLS nylon or high-temperature FDM filaments with documented mechanical properties.
- Education Models:Teaching aids and anatomical replicas prioritize low-cost, safe materials accessible to undergraduate users without specialized ventilation.
- Artifacts:Museums and cultural institutions reproduce delicate objects with continuous liquid interface production systems that eliminate layer lines.
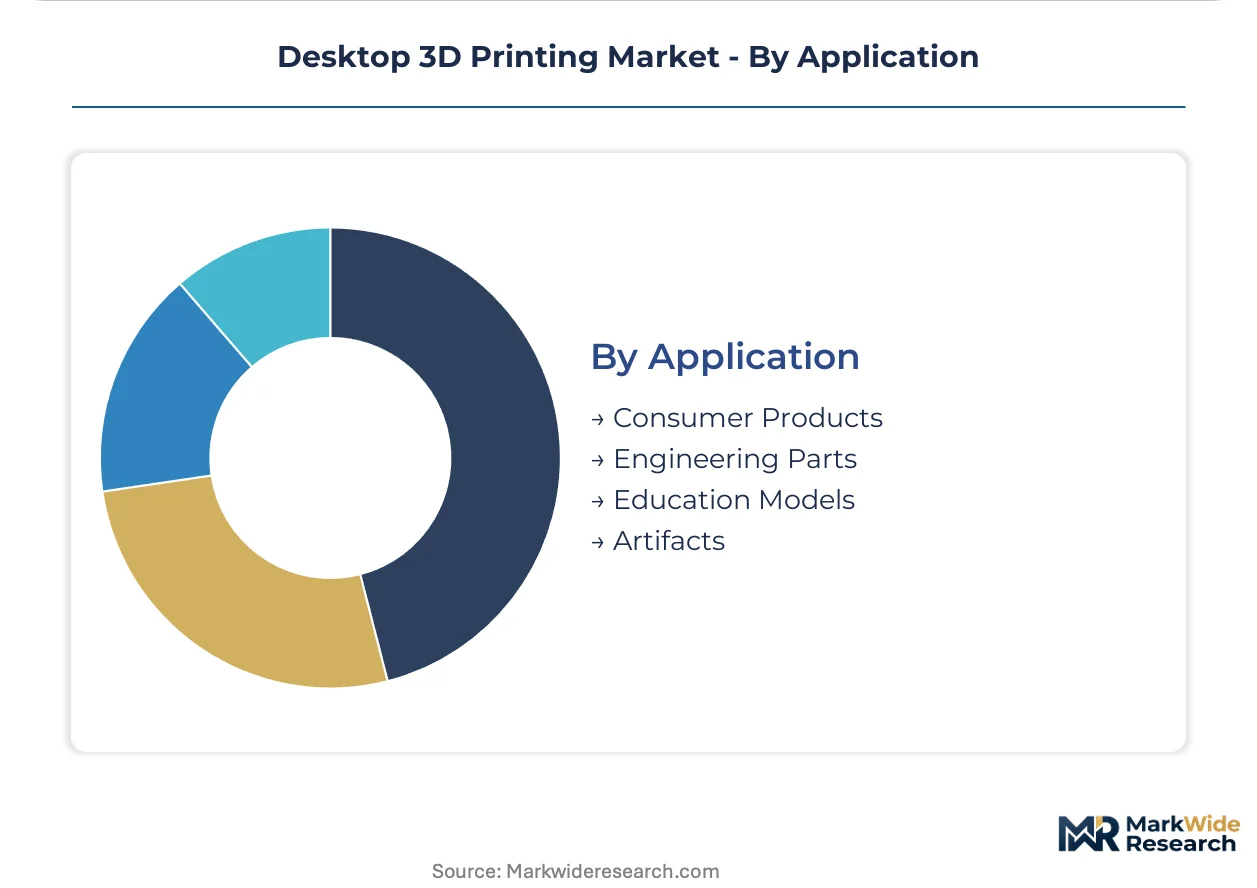
Engineering Parts commands the highest hardware investment per unit, with Artifacts showing the steepest expansion trajectory on cultural heritage digitization initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Desktop 3D printing traces its industrial roots to Minnesota, where early stereolithography patents spawned the first commercial systems. German engineering clusters later refined powder-bed and extrusion architectures, establishing dual geographic poles that persist today. Market demand now distributes across manufacturing corridors shaped by regulatory frameworks, university research networks, and dental laboratory density.
United States
Midwest job shops drive FDM hardware refresh cycles, with Ohio and Michigan manufacturing clusters prioritizing predictable consumables spend over capital spikes. EPA occupational safety scrutiny of ultrafine particle emissions threatens open-chamber installations with retrofit costs. Greater Boston anchors resin system development for dental workflows, with Massachusetts-based laboratories scaling aligner production for direct-to-consumer orthodontic brands.
Germany
RWTH Aachen and TU Munich sustain filament volume through research grant funding and iterative prototyping demand from automotive supply chains. EU MDR material traceability mandates lock dental laboratories into certified resin relationships, compressing procurement flexibility. Bavaria's industrial corridor hosts polymer powder-bed system development, with Munich-area engineering firms advancing compact workshop-scale architectures.
China
Domestic manufacturers dominate entry-level FDM unit shipments, leveraging Shenzhen electronics supply chains for motion control components. MIIT industrial additive manufacturing policies channel subsidies toward metal and polymer systems for aerospace prototyping. Yangtze River Delta clusters concentrate photopolymer formulation capacity, though ISO 10993 testing infrastructure remains concentrated among European suppliers.
India
CDSCO medical device registration pathways and PLI scheme incentives attract biocompatible photopolymer system deployments for surgical guide production. Maharashtra and Gujarat dental laboratories expand resin-based aligner manufacturing to serve domestic orthodontic demand. Karnataka's Bangalore-Tumkur corridor hosts technical university prototyping clusters that sustain hardware import volume.
Japan
PMDA medical device clearance timelines shape product development cycles for dental applications, favoring established suppliers with regulatory affairs capacity. METI additive manufacturing roadmaps prioritize high-temperature thermoplastic systems for aerospace component qualification. Nagoya-area automotive engineering clusters drive functional prototyping demand for nylon and composite feedstocks.
Desktop 3D Printing Market Key Industry Players
Premium-margin players sit above commodity-margin players across materials certification and regulatory compliance capabilities. The market structures into three tiers: integrated materials-hardware ecosystems commanding recurring consumables revenue, standalone hardware vendors competing on acquisition cost, and specialized resin formulators capturing margin from biocompatibility certification bottlenecks. Consolidation pressure concentrates among mid-scale hardware vendors lacking captive materials supply, while geographic expansion and technology licensing represent the dominant competitive moves.
Within the integrated ecosystem tier, Stratasys and HP Inc. exemplify contrasting approaches to consumables lock-in. EOS GmbH anchors the premium powder-bed segment through open-material strategies that attract engineering-centric buyers. These three players occupy positions that reflect divergent bets on whether hardware margins or recurring materials revenue will dominate value capture in workshop-scale additive manufacturing.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems |
| EOS GmbH |
| HP Inc. |
| Materialise |
| Desktop Metal |
| SLM Solutions |
| Markforged |
| Carbon |
| Others |
Cost & Logistics Intelligence
REACH chemical compliance expansions are gating qualified photopolymer supply and premium-tier pricing access for dental laboratories across Italy and Spain, forcing consolidation around REACH-registered suppliers with in-house toxicology testing capacity.
Pricing Analysis
Three-year total cost of ownership contracts that embed filament or resin minimums are displacing standalone hardware procurement among Midwest US job shops. Price differentiation hinges on ISO 10993 biocompatibility certification tier and consumables bundling depth. Cost compression in entry-level FDM hardware is intensifying because Shenzhen manufacturers leverage electronics supply chain scale. Education buyers show highest price sensitivity; dental laboratories demonstrate lowest sensitivity due to MDR compliance lock-in.
Supply Chain Analysis
Dual-sourcing requirements from EU MDR-compliant dental laboratories mandate multi-supplier qualification for certified resin formulations. Photopolymer feedstock draws from Germany, France, and China, with motion control components anchored in Shenzhen electronics clusters. Single-source vulnerability concentrates among three European chemical suppliers holding ISO 10993 testing infrastructure. Distribution runs through authorized dental equipment distributors and direct university procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU MDR material traceability mandates driving recurring consumables revenue and supplier consolidation across European dental workflows.
For Market Incumbents: Lock in recurring resin revenue through multi-year consumables contracts that preempt MDR-driven supplier switching. Deepen captive photopolymer formulation capacity to defend margin position against REACH-registered European chemical suppliers. Prioritize ISO 10993 testing infrastructure investment to compress certification timelines for new resin launches.
For New Entrants and Emerging Players: Dental equipment distributors represent the most accessible channel partner type for bypassing incumbent consumables lock-in. Target India's PLI scheme corridors for surgical guide production workflows where CDSCO registration pathways remain navigable. Pursue white-label resin formulation partnerships with Yangtze River Delta chemical clusters to circumvent European supply bottlenecks.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale resin formulators because ISO 10993 certification timelines create insurmountable barriers to organic entry. Platform consolidation across REACH-registered European suppliers offers five-to-ten year viability as MDR compliance requirements tighten. Monitor EPA occupational safety interpretations for ultrafine particle emissions as the inflection signal triggering replacement demand for closed-chamber architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Consumables Bundling Contracts | Three-year TCO agreements with dental laboratories in Germany and France lock in recurring resin revenue streams. |
| ISO 10993 Testing Infrastructure Buildout | In-house biocompatibility capacity compresses product development cycles by 18-24 months for new photopolymer formulations. |
| Closed-Chamber Architecture Migration | Filtered FDM systems capture replacement demand from US workshops facing EPA ultrafine particle emissions scrutiny. |
| India PLI Scheme Leverage | Domestic medical device manufacturing incentives create entry pathways for surgical guide production in Maharashtra and Gujarat. |
| REACH-Registered Supplier Consolidation | Preemptive procurement consolidation by Italian and Spanish dental laboratories prevents MDR-driven supply interruption. |
Research Approach
Multiple input streams — primary interviews with dental laboratory managers, university prototyping coordinators, and resin formulation chemists; secondary validation through EU MDR regulatory filings, EPA emissions guidance documents, and customs trade data for photopolymer imports — were reconciled through bottom-up hardware shipment analysis and top-down consumables revenue triangulation.
Data-stream reconciliation across product type, end user category, material chemistry, and geographic regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base growth rates and consumables attach rates by segment. Forecast inputs incorporated REACH chemical compliance expansion timelines and CDSCO medical device registration pathway developments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA occupational safety rulemaking and EU MDR enforcement consistency. Deviation in ISO 10993 certification timeline acceleration or photopolymer supply concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
Global 3D Pens Market
3D Printing Technology
Saudi Arabia and Egypt Healthcare 3D Printing Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
Food 3D Printing Market
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
Global 3D Printing in Medical Applications Market
3D Printing Technology
3D Printer Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
North America Additive Manufacturing Market
3D Printing Technology
3D Printing Market