
 Hybrid Additive Manufacturing Machine Market | 2026-2036
Hybrid Additive Manufacturing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Additive Manufacturing Machine Market Analysis
The direct sales channel for industrial machine tools is narrowing as OEMs build captive service networks and regional technical centers. DMG MORI Co., Ltd. leverages its global dealership footprint to control aftermarket revenue streams. Mazak Corporation anchors North American demand through its Kentucky manufacturing campus and localized application engineering. SLM Solutions Group AG competes by specializing in metal powder-bed systems for aerospace qualification pathways.
Hybrid additive manufacturing machines combine directed energy deposition or powder-bed fusion with subtractive milling, turning, or grinding in a single work envelope, typically achieving surface finishes of 2-4 micrometers Ra without secondary operations. Their primary purpose is to produce near-net-shape metal components with internal cooling channels, graded material transitions, or repair features impossible in conventional machining alone. Direct Energy Deposition technology leads installed capacity for repair and large-format part production, while Selective Laser Sintering dominates polymer prototyping and medical device tooling. Aerospace end users command the highest average system values, though Automotive buyers are expanding fastest as electric vehicle platforms require lighter, topology-optimized structural nodes.
FAA airworthiness directives and EASA certification memoranda shape hybrid system validation timelines for flight-critical components, while EPA emissions standards and OSHA metalworking fluid regulations influence coolant system design and shop-floor integration requirements. The EU Green Deal carbon border adjustments are redirecting European supplier investment toward in-house hybrid production to preserve margin against imported finished goods. Stakeholders must monitor evolving ISO/ASTM standards for hybrid process qualification and determine whether to pursue machine-tool OEM partnerships or develop proprietary process-parameter libraries.
Market Dynamics
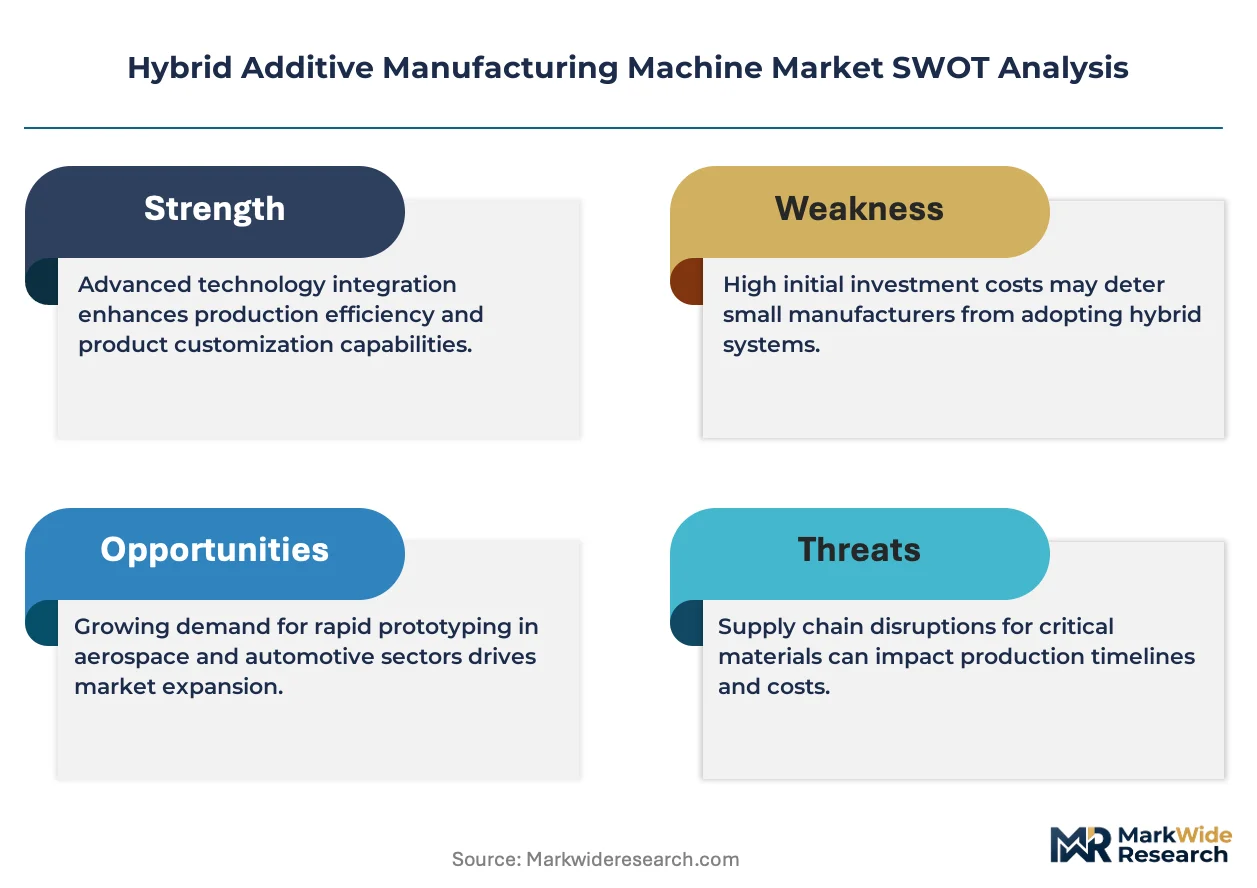
EU Green Deal carbon border adjustments and FAA airworthiness directives are compressing qualification timelines while forcing suppliers to consolidate subtractive and additive capabilities under single work envelopes.
Growth Catalysts
- EU Green Deal carbon border adjustments:European automotive and aviation suppliers face margin erosion on imported finished goods, redirecting capital toward in-house hybrid production to preserve profitability.
- Directed Energy Deposition repair protocols:Aerospace maintenance facilities adopt DED systems for turbine blade restoration, cutting lead times versus conventional weld-and-machine workflows.
- Stuttgart precision engineering cluster:Germany's machine tool development ecosystem anchors end-user testing and accelerates OEM-to-customer feedback loops for hybrid system refinement.
Market Restraints
- Metal powder supply concentration:Specialty alloy powder production clusters in a limited supplier base, exposing buyers to input cost volatility and qualification delays.
- FAA-EASA dual certification friction:Divergent validation timelines for flight-critical components force aerospace suppliers to maintain parallel documentation systems.
- Conventional five-axis machining substitution:Mature subtractive systems retain cost advantages for simple geometries without internal cooling channels.
Strategic Opportunities
- Topology-optimized EV structural nodes:Electric vehicle platforms demand lighter chassis components, opening hybrid production lines for automotive tier-one suppliers.
- ISO/ASTM hybrid process qualification standards:Early alignment with evolving certification frameworks positions equipment vendors as preferred partners for aerospace qualification pathways.
- Captive service network expansion:OEM technical centers in regional manufacturing hubs capture aftermarket revenue streams previously lost to independent distributors.
Industry Challenges
- Multi-physics process-parameter optimization:Engineers must simultaneously control thermal gradients, deposition rates, and machining forces—skill sets rarely combined in traditional manufacturing training.
- Legacy ERP integration complexity:Shop-floor data from hybrid systems requires middleware development to connect with existing production planning software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Additive Manufacturing Machine Market |
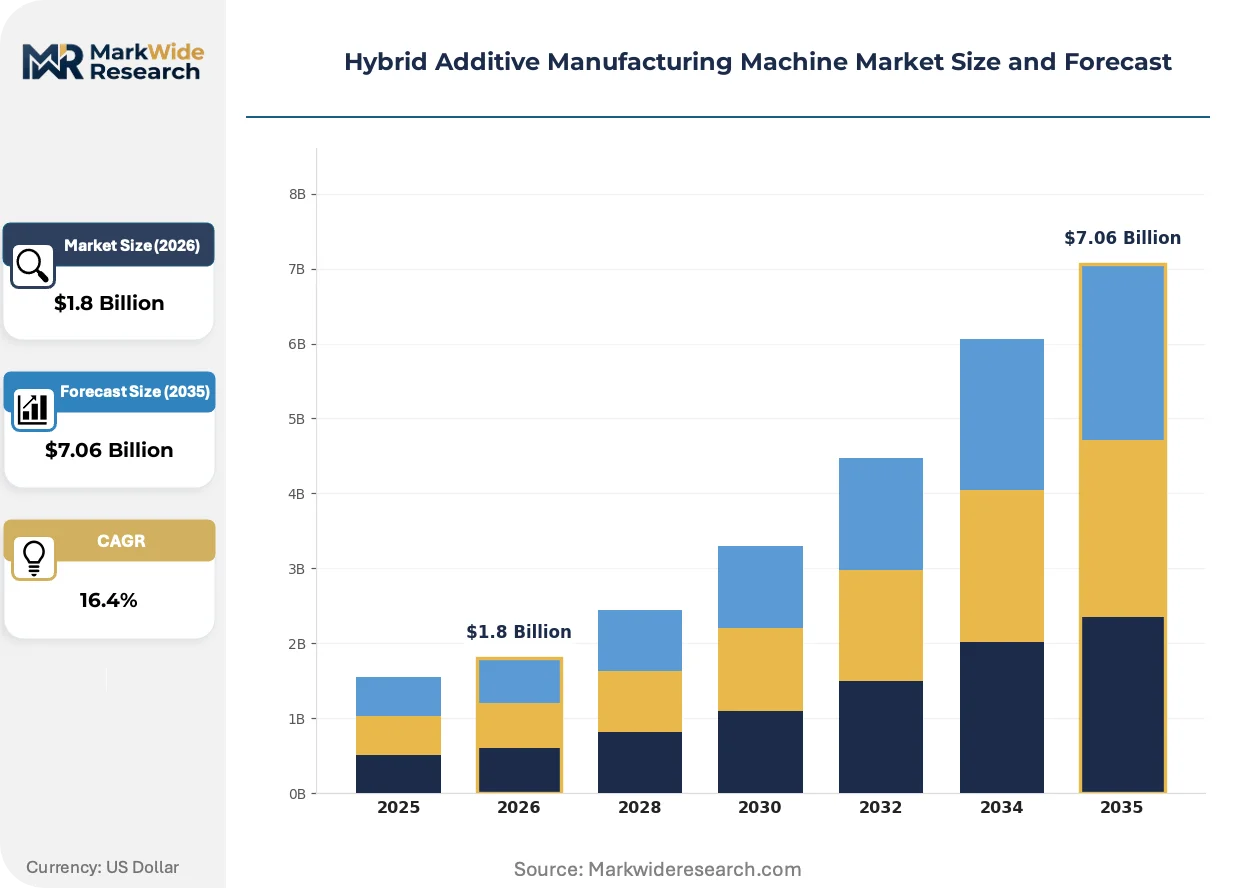
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fused Deposition Modeling, Selective Laser Sintering, Electron Beam Melting, Direct Energy Deposition End User: Aerospace, Automotive, Healthcare, Consumer Goods Material: Metals, Polymers, Ceramics, Composites Component: Print Head, Build Platform, Control System, Cooling System |
| Companies Covered | Optomec, Inc., voxeljet AG, DMG MORI Co., Ltd., Maschinenfabrik Berthold Hermle AG, SLM Solutions Group AG, Mazak Corporation, Stratasys Ltd, GE Additive, Matsuura Machinery Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Additive Manufacturing Machine Market Emerging Trajectories
Process convergence and regulatory compression are redefining competitive positioning. Equipment vendors now compete on integrated workflow validation rather than standalone machine specifications.
Hybrid systems combining directed energy deposition with in-situ milling is rendering obsolete the traditional sequence of separate additive build and subtractive finishing operations. Aerospace maintenance divisions adopt these platforms for depot-level repair, collapsing part turnaround from weeks to days. The structural consequence is compressed supplier qualification timelines as single-envelope traceability replaces multi-vendor process documentation.
REACH substance restrictions on metalworking fluids are forcing coolant system redesigns across European installations. Equipment manufacturers respond with minimum-quantity lubrication and closed-loop filtration to maintain CE marking compliance. Medical device tooling segments face the steepest adaptation costs due to biocompatibility validation requirements.
Buyer concentration among aerospace primes is consolidating procurement leverage. Tier-one suppliers now demand outcome-based machine performance guarantees rather than equipment-only transactions. This shift concentrates most visibly in Germany, where DMG MORI and Mazak field application engineers co-develop process-parameter libraries with captive customer engineering teams.
Hybrid Additive Manufacturing Machine Market Segmentation
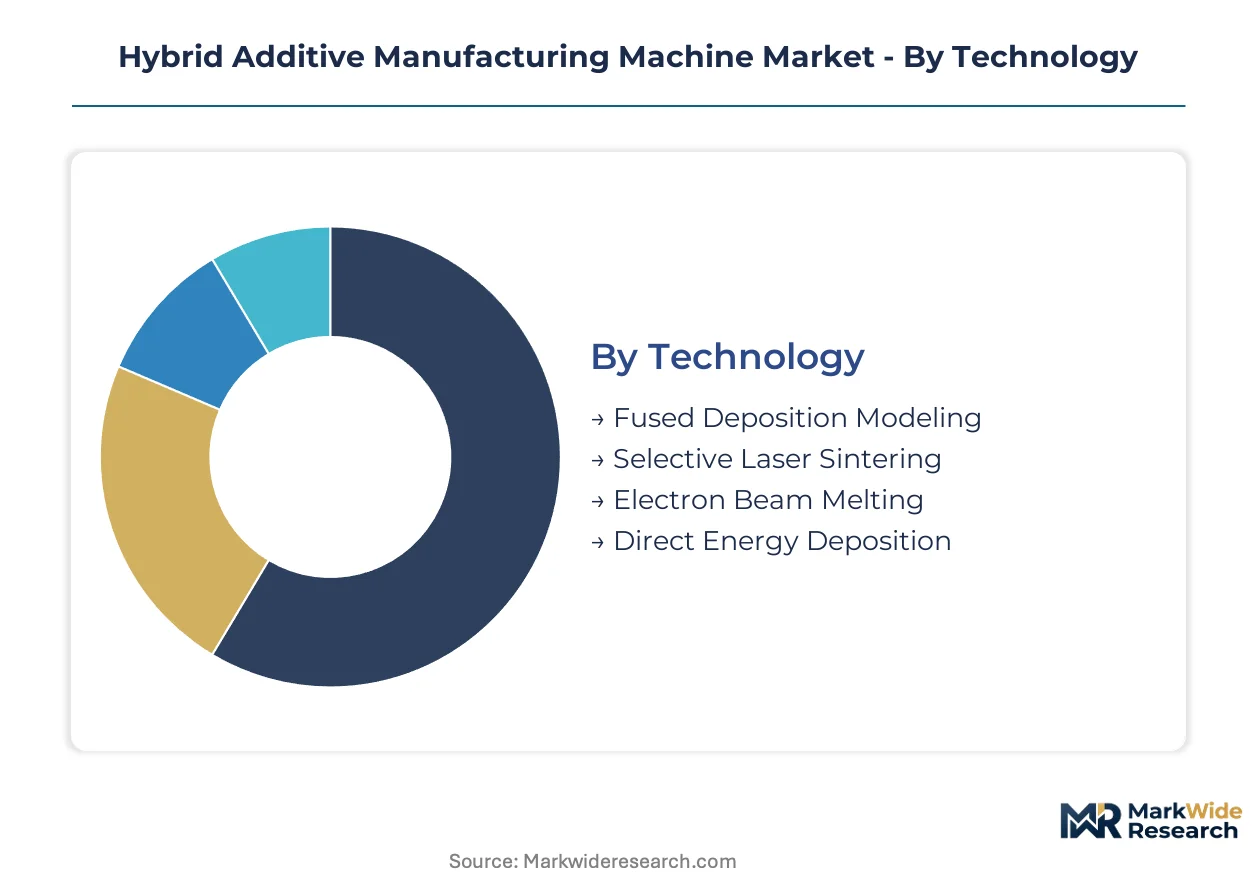
Hybrid additive manufacturing machines segment across technology platforms, end-use industries, material classes, and machine subsystems. Each dimension carries distinct qualification requirements and margin profiles that shape vendor strategy and buyer procurement patterns.
Technology:
Technology segmentation captures the core deposition or fusion mechanism that defines system capability, throughput, and surface finish characteristics.
- Direct Energy Deposition:Wire or powder-fed laser/electron beam systems build near-net shapes with high deposition rates. Aerospace maintenance facilities in Germany and the United States deploy DED for turbine blade restoration, cutting turnaround versus conventional weld-and-machine workflows.
- Selective Laser Sintering:Powder-bed fusion using CO2 or fiber lasers produces complex geometries with fine feature resolution. Medical device manufacturers in Switzerland and Japan concentrate demand here for surgical instrument tooling requiring internal cooling channels.
- Electron Beam Melting:Vacuum-based electron beam fusion excels with reactive alloys like titanium aluminide. Demand clusters in aerospace structural component production where material properties must withstand thermal cycling.
- Fused Deposition Modeling:Thermoplastic extrusion systems dominate polymer prototyping and fixture production. Automotive design studios in Italy and consumer goods developers in South Korea rotate this technology up for rapid iteration cycles.
DED holds installed capacity for repair applications. SLS is rotating up the share rankings in medical and aerospace qualification pathways.
End User:
End user segmentation reflects divergent certification burdens, volume requirements, and technical support expectations across industrial sectors.
- Aerospace:Flight-critical component production and depot-level repair command the highest system values. FAA and EASA airworthiness directives force extended qualification timelines, concentrating procurement among primes with captive engineering resources.
- Automotive:Electric vehicle platforms require topology-optimized structural nodes that subtractive machining cannot produce. Tier-one suppliers in Germany and Michigan are expanding fastest as OEMs specify hybrid-produced battery enclosures and motor housings.
- Healthcare:Patient-specific implants and surgical guides demand biocompatibility validation under FDA 510(k) and MDR frameworks. Swiss and Israeli medical device manufacturers anchor this segment.
- Consumer Goods:Premium sporting equipment and luxury watch components use hybrid systems for aesthetic surface finishes. Italian and Japanese precision manufacturers concentrate demand here.
Aerospace retains the highest average transaction values. Automotive is climbing the fastest as EV production scales.
Material:
Material segmentation determines powder supply chain configuration, inert gas requirements, and post-processing protocols.
- Metals:Nickel superalloys, titanium, and tool steels dominate aerospace and mold-making applications. Specialty alloy powder production concentrates among German and American suppliers, exposing buyers to input cost volatility.
- Polymers:High-performance thermoplastics like PEEK and ULTEM serve medical and aerospace interior components. Demand is accelerating for sterilizable, lightweight alternatives to metal.
- Ceramics:Oxide and non-oxide ceramics enable high-temperature applications in semiconductor processing equipment. Japanese and German industrial ceramic specialists anchor this niche.
- Composites:Continuous fiber-reinforced deposition combines polymer matrices with carbon or glass fiber. Automotive and sporting goods developers in Italy and California test these systems for structural load-bearing parts.
Metals command the majority of installed base value. Polymers are gaining share fastest as medical device tooling expands.
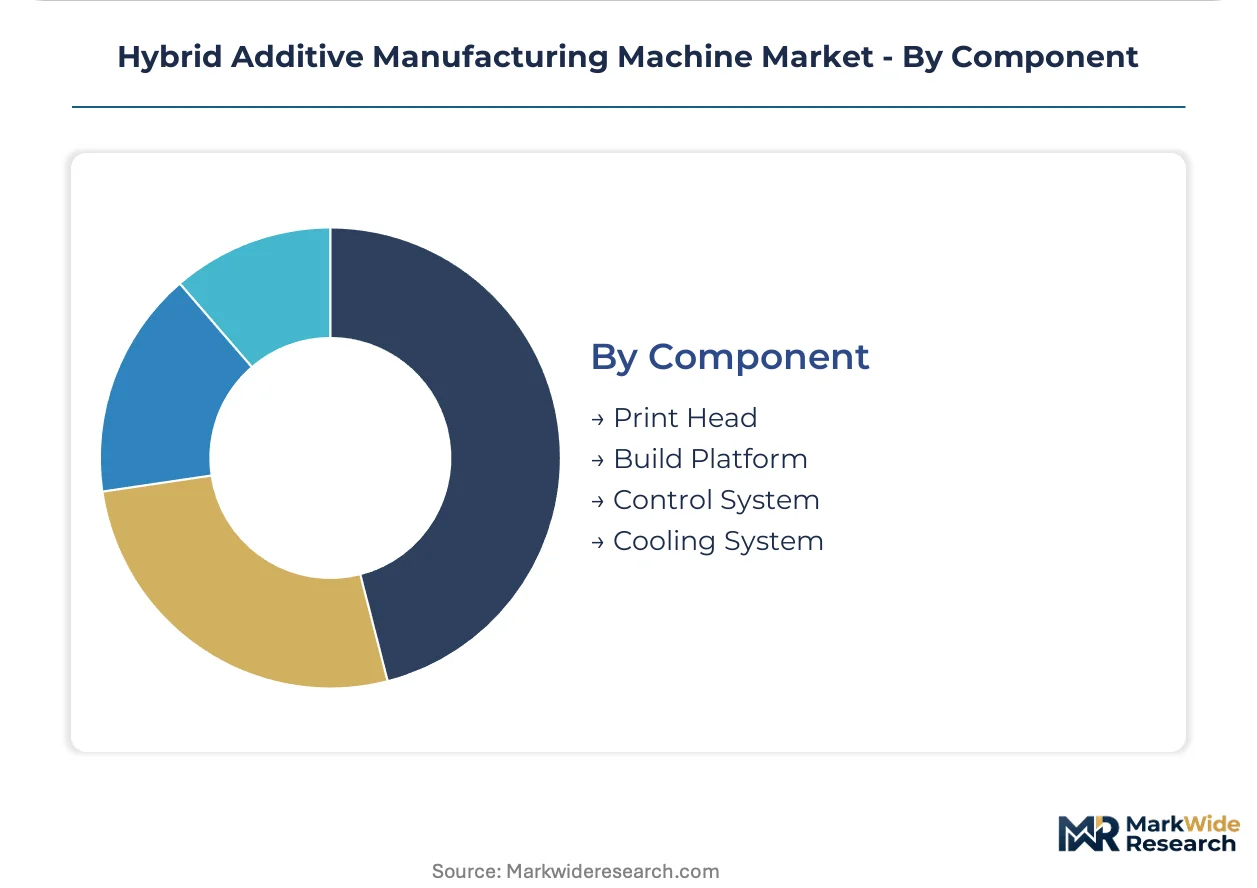
Component:
Component segmentation tracks the machine subsystems where technical differentiation and aftermarket service revenue concentrate.
- Control System:Multi-axis motion controllers and real-time thermal monitoring modules coordinate additive and subtractive operations. Vendors compete on open architecture that permits customer-specific process-parameter libraries.
- Print Head:Laser optics, electron beam columns, or extrusion nozzles define deposition precision and material compatibility. German and Japanese optical specialists supply critical subassemblies.
- Build Platform:Heated or cooled work surfaces with precision leveling systems ensure first-layer adhesion and thermal management. Large-format platforms for aerospace repair carry premium pricing.
- Cooling System:Closed-loop chillers and minimum-quantity lubrication units maintain CE marking compliance under REACH substance restrictions. European installations face the steepest redesign costs here.
Control systems capture the highest aftermarket margin. Print head technology is rotating up the competitive priority list as multi-material deposition advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's precision engineering clusters while North American buyers absorb premiums for FAA-qualified systems. Japanese and Chinese manufacturers compete on cost-adjusted throughput metrics. Regional differentiation stems from regulatory pathway complexity and captive supplier engineering resources.
United States
FAA airworthiness directives and depot-level aerospace repair contracts drive demand for qualified hybrid systems. EPA emissions standards and OSHA metalworking fluid regulations shape coolant system integration requirements. The Kentucky manufacturing corridor anchors Mazak Corporation's North American application engineering presence for localized customer support.
Germany
EU Green Deal carbon border adjustments redirect automotive and aviation supplier capital toward in-house hybrid production. REACH substance restrictions force minimum-quantity lubrication redesigns for CE marking compliance. Stuttgart and Munich precision engineering clusters accelerate OEM-to-customer feedback loops for system refinement.
Japan
METI industrial technology roadmaps prioritize multi-material deposition capabilities for aerospace and medical device applications. JIS standards alignment shapes domestic qualification protocols for export-bound systems. Nagoya and Osaka metropolitan areas concentrate machine tool development and optical subassembly supply chains.
China
MIIT advanced manufacturing initiatives accelerate domestic hybrid system development for aerospace and automotive sectors. GB standards and dual carbon goals pressure state-owned enterprises toward material-efficient production methods. Yangtze River Delta manufacturing hubs integrate hybrid platforms for mold-making and turbine component repair.
Switzerland
Swissmedic medical device regulations and FDA 510(k) parallel filings drive biocompatibility validation requirements for patient-specific implants. Precision watchmaking heritage translates into demand for aesthetic surface finish capabilities. Basel and Zurich medical device manufacturers anchor European demand for polymer and metal hybrid tooling.
Hybrid Additive Manufacturing Machine Market Vendor Landscape
Integrated machine-tool conglomerates and specialized additive technology firms split the market along qualification-depth versus speed-to-deployment vectors. Consolidation pressure intensifies as aerospace primes demand single-source accountability for flight-critical component workflows. Equipment vendors compete on captive service network density and co-developed process-parameter libraries rather than standalone machine specifications. Dominant competitive moves include regional technical center expansion and strategic partnerships for powder supply chain security.
Within the integrated machine-tool tier, DMG MORI Co., Ltd. and Mazak Corporation exemplify geographic anchoring strategies through localized manufacturing campuses and application engineering presence. SLM Solutions Group AG occupies a position among specialized metal powder-bed system developers competing on aerospace qualification pathway alignment. Maschinenfabrik Berthold Hermle AG represents German precision machining heritage translated into hybrid platform development. These archetypes illustrate divergent bets on whether market power accumulates to full-workflow integrators or best-in-class deposition technology specialists.
| Leading Market Players |
|---|
| Optomec, Inc. |
| voxeljet AG |
| DMG MORI Co., Ltd. |
| Maschinenfabrik Berthold Hermle AG |
| SLM Solutions Group AG |
| Mazak Corporation |
| Stratasys Ltd |
| GE Additive |
| Matsuura Machinery Corporation |
| Others |
Supply Flow & Price Mechanics
Rhine-Alpine freight corridors linking German machine tool clusters to Italian aerospace subassembly plants transmit logistics cost volatility directly into configured-to-order pricing spreads. Powder alloy supply concentration in Germany and the United States amplifies input cost pass-through to tier-one automotive buyers, while REACH compliance redesigns force cooling system premiums that widen standard-configuration discounts.
Pricing Analysis
Configured-to-order premiums for FAA-qualified hybrid systems run substantially above standard five-axis machining alternatives, with price differentiation anchored in certification grade and captive service bundling. Aerospace procurement teams absorb these premiums for depot-level repair workflows, while automotive tier-one suppliers negotiate volume-scale offsets against topology-optimized EV node contracts. Cost compression in standard-configuration segments intensifies as conventional machining retains viability for simple geometries. Medical device manufacturers exhibit the sharpest price sensitivity due to biocompatibility validation overhead.
Supply Chain Analysis
Upstream feedstock for specialty alloy powders concentrates in Germany, the United States, and Japan, with nickel superalloy and titanium aluminide production tethered to aerospace qualification protocols. Laser optics and electron beam columns draw from Japanese and German optical subassembly specialists, while build platform thermal management systems rest on Swiss precision engineering heritage. Single-source vulnerability in qualified powder supply exposes buyers to input cost volatility and batch certification delays. Distribution runs through OEM captive service networks and regional technical centers that capture aftermarket revenue previously lost to independent channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive returns as equipment vendors compete on integrated workflow validation rather than standalone machine specifications. Interoperability between additive deposition parameters and legacy ERP systems determines procurement decisions for aerospace primes consolidating supplier accountability.
For Market Incumbents: Insulate installed base revenue by deepening captive powder supply partnerships and expanding Kentucky and Stuttgart technical centers for localized application engineering. Certification investment in ISO/ASTM hybrid process standards defends against emerging deposition-technology specialists threatening aerospace qualification pathways. Channel control through dealership footprint consolidation captures aftermarket service margins.
For New Entrants and Emerging Players: Build out polymer-based medical device tooling capabilities in Swiss and Israeli precision manufacturing clusters where biocompatibility validation requirements create incumbent blind spots. Topology-optimized EV structural nodes for automotive tier-one suppliers represent the most penetrable volume segment. Go-to-market execution should anchor on outcome-based performance guarantees rather than equipment-only transactions.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded hybrid system development programs lacking captive service network scale. Long-term viability favors full-workflow integrators over best-in-class deposition technology specialists in isolation. Watch for FAA-EASA harmonization progress as the inflection signal for accelerated aerospace procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Powder Supply Partnership | Backward integration into qualified alloy production secures margin against input volatility for German OEMs. |
| Regional Technical Center Expansion | Kentucky and Stuttgart campuses localize application engineering for Mazak and DMG MORI aftermarket capture. |
| ISO/ASTM Standards Alignment | Early hybrid process qualification positioning opens aerospace procurement pathways for equipment vendors. |
| Outcome-Based Performance Contracts | Tier-one automotive suppliers now demand guaranteed throughput rather than equipment-only transactions. |
| Legacy ERP Middleware Development | Shop-floor data integration determines procurement decisions for primes consolidating single-source accountability. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with hybrid system OEM product managers, aerospace procurement directors, automotive tier-one manufacturing engineers, and aftermarket service heads; and secondary validation against SEC filings, EASA certification memoranda, EU Green Deal policy documentation, and ISO/ASTM standards development records. Bottom-up equipment shipment triangulation against top-down end-user capital expenditure patterns anchored volume estimates. Primary fieldwork concentrated in German precision engineering clusters, Kentucky manufacturing corridors, and Japanese machine tool development centers.
Forecast inputs span technology platform adoption curves, regulatory pathway timelines, and end-user vertical expansion patterns across the projection horizon. Segmentation modeling captures deposition mechanism, end-use industry certification burden, material class supply chain configuration, and machine subsystem aftermarket margin profiles. CAGRs derive from equipment shipment trajectories, installed base replacement cycles, and greenfield capacity expansion announcements. Industry-specific inputs include FAA-EASA harmonization progress and EU carbon border adjustment implementation scope.
Stress conditions across powder supply disruption, dual certification timeline divergence, and conventional machining substitution thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory compression and platform economics evolution. Cross-checking against disclosed aerospace prime capital expenditure guidance and automotive OEM supplier qualification announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
Binder Jet Market
3D Printing Technology
Additive Manufacturing Software Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
US Additive Manufacturing Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
Saudi Arabia and Egypt Healthcare 3D Printing Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
Global 3D Pens Market
3D Printing Technology
Food 3D Printing Market