
 Asia-Pacific 3D Printing Market | 2026-2036
Asia-Pacific 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific 3D Printing Market Insights
China's MIIT additive manufacturing industry development plan is decoupling equipment certification from legacy import dependencies, lowering capital barriers for domestic adopters. HP Inc. leverages its Multi Jet Fusion platform to anchor polymer production workflows across Japanese automotive supply chains. Farsoon sustains cost competitiveness in selective laser sintering systems through in-house laser and scanner production. Stratasys differentiates via its FDM ecosystem breadth, competing for aerospace tooling contracts in Australia and Singapore.
Asia-Pacific 3D Printing encompasses layer-by-layer fabrication of three-dimensional objects from digital model data, utilizing thermal, photopolymer, or laser-based processes to consolidate metals, polymers, or ceramics with tolerances ranging from ±0.1 mm to ±0.3 mm depending on technology. Its primary industrial purpose centers on producing complex geometries, lightweight lattice structures, and consolidated multi-part assemblies that subtractive machining cannot economically achieve. FDM technology occupies the broadest installed base across education and prototyping segments due to low equipment cost and material accessibility. Metal powder bed fusion systems command concentrated margin pools in aerospace and medical end-use applications where titanium and nickel superalloy certifications create supply scarcity. Polymer materials dominate unit volume while ceramics represent the fastest-growing material category for dental and semiconductor tooling applications.
Japan's METI governs industrial robot and manufacturing equipment standards that shape 3D printer interoperability requirements, while Australia's TGA regulates patient-specific implant production through medical device quality management frameworks. South Korea's MFDS enforces biocompatibility testing protocols for dental and orthopedic additively manufactured devices, creating compliance differentiation between certified and uncertified material suppliers. Stakeholders must monitor evolving national standards for powder recyclability, build chamber atmosphere controls, and post-processing emissions as these technical specifications increasingly determine market access across the region's fragmented regulatory landscape.
Market Dynamics
China's MIIT additive manufacturing development plan is accelerating domestic equipment certification pathways, decoupling capital procurement from legacy import dependencies and compressing adoption timelines across Yangtze River Delta manufacturing clusters.
Growth Catalysts
- MIIT Equipment Certification Reform:China's streamlined domestic equipment approval pathways lower capital barriers for metal powder bed fusion adoption in aerospace tooling workflows.
- Automotive Serial Production Integration:Japanese and South Korean OEMs embed polymer additive manufacturing into just-in-time supply chains for interior components and jigs.
- Titanium Lattice Medical Implants:Australia's TGA patient-specific implant framework creates certified demand channels for topology-optimized orthopedic devices.
Market Restraints
- Nickel Superalloy Powder Concentration:Supply of certified aerospace-grade metal powders concentrates among three primary producers, creating input cost volatility and allocation risk.
- Build Chamber Atmosphere Standards:Divergent national specifications for oxygen ppm limits in laser powder bed fusion create cross-border equipment incompatibility.
- CNC Machining Cost Compression:Five-axis subtractive centers in Vietnam and Thailand achieve geometric complexity previously exclusive to additive, pressuring polymer prototyping margins.
Strategic Opportunities
- Indonesian Archipelago Distributed Manufacturing:Island geography and port congestion create structural demand for point-of-use metal printing in maritime maintenance operations.
- Ceramic Semiconductor Tooling:Silicon carbide and alumina additive processes address wafer handling component shortages in South Korean and Taiwanese fabs.
- Dual Carbon Policy Alignment:China's MEE emissions frameworks favor localized additive production over carbon-intensive casting and forging imports.
Industry Challenges
- Multi-Material Process Engineering Talent:Scarce expertise in parameter optimization for gradient metal-ceramic structures limits aerospace component qualification velocity.
- Post-Processing Automation Capex:Heat treatment, HIP, and surface finishing equipment requires capital outlays comparable to primary printing systems.
- Legacy ERP Integration Friction:MES connectivity gaps between additive job scheduling and established SAP/Oracle production planning systems delay serial production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific 3D Printing Market |
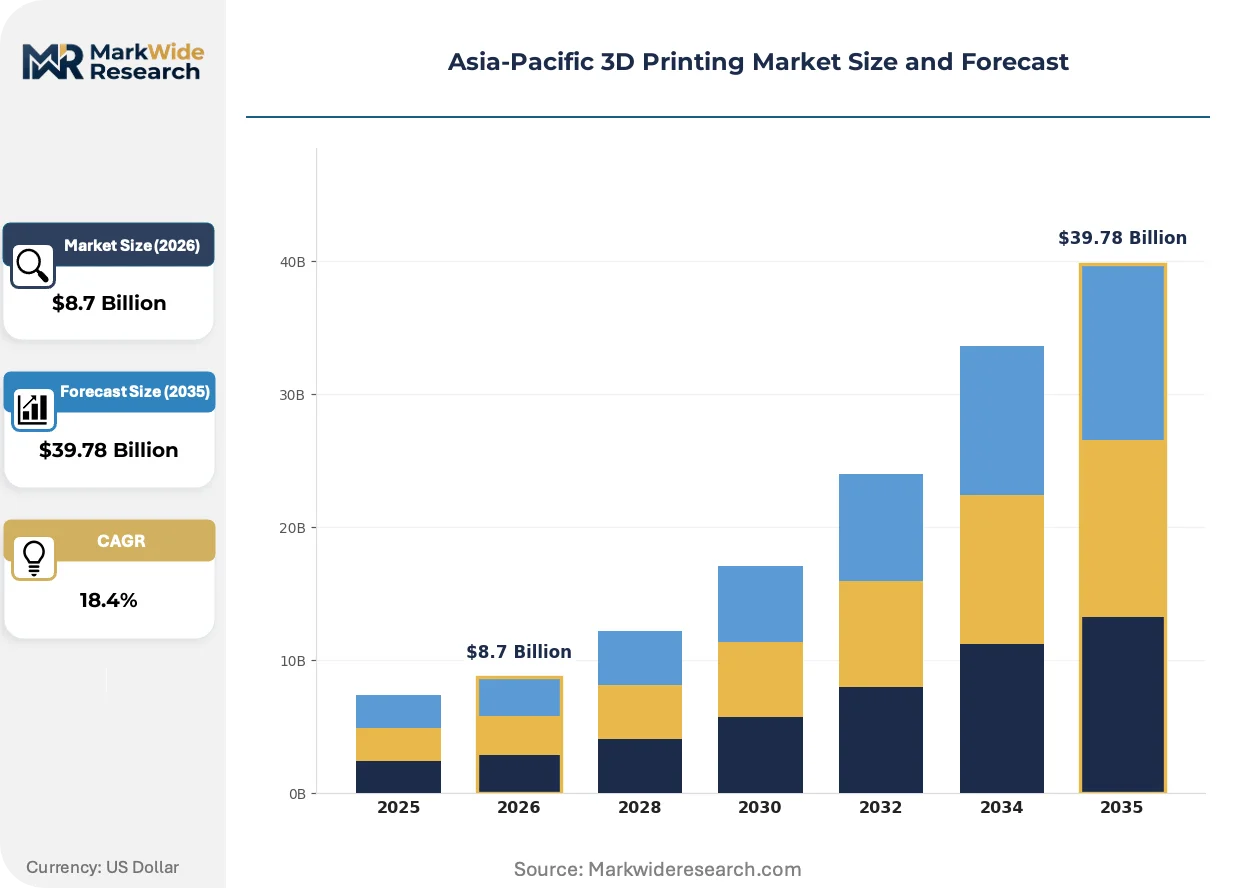
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: FDM, SLA, SLS, DLP End User: Aerospace, Healthcare, Automotive, Consumer Electronics Material Type: Metals, Polymers, Ceramics, Composites Application: Prototyping, Production, Tooling, Education |
| Companies Covered | HP Inc., Farsoon, Stratasys, Renishaw, Formlabs, 3D Systems, Materialise NV, Markforged, EOS GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific 3D Printing Market Trends and Innovations
Multi-laser metal powder bed fusion architectures and AI-driven build monitoring are compressing per-part economics while regulatory frameworks mature for flight-critical component certification.
Desktop metal binder jetting is decentralizing low-volume stainless steel production from centralized foundries to machine shop floors. Tier-two automotive suppliers in Thailand and Malaysia adopt these systems for tooling and fixturing with sub-48-hour turnaround requirements. The technology is decentralizing capital equipment ownership patterns previously concentrated among tier-one aerospace contractors.
Japan's METI industrial equipment interoperability standards now mandate open architecture data formats for 3D printer fleet management. This policy compresses vendor lock-in dynamics and accelerates multi-brand shop floor integration. Japanese automotive supply chains are responding by diversifying equipment procurement across polymer and metal platforms.
Contract manufacturers now bundle qualification documentation and post-processed finishing as unbundled service modules rather than all-inclusive per-gram pricing. Electronics OEMs in Shenzhen and Singapore select vendors based on certified material traceability depth rather than equipment brand. This purchasing pattern shift concentrates margin with integrated material-equipment-service providers in China's Pearl River Delta.
Asia-Pacific 3D Printing Market Segmentation
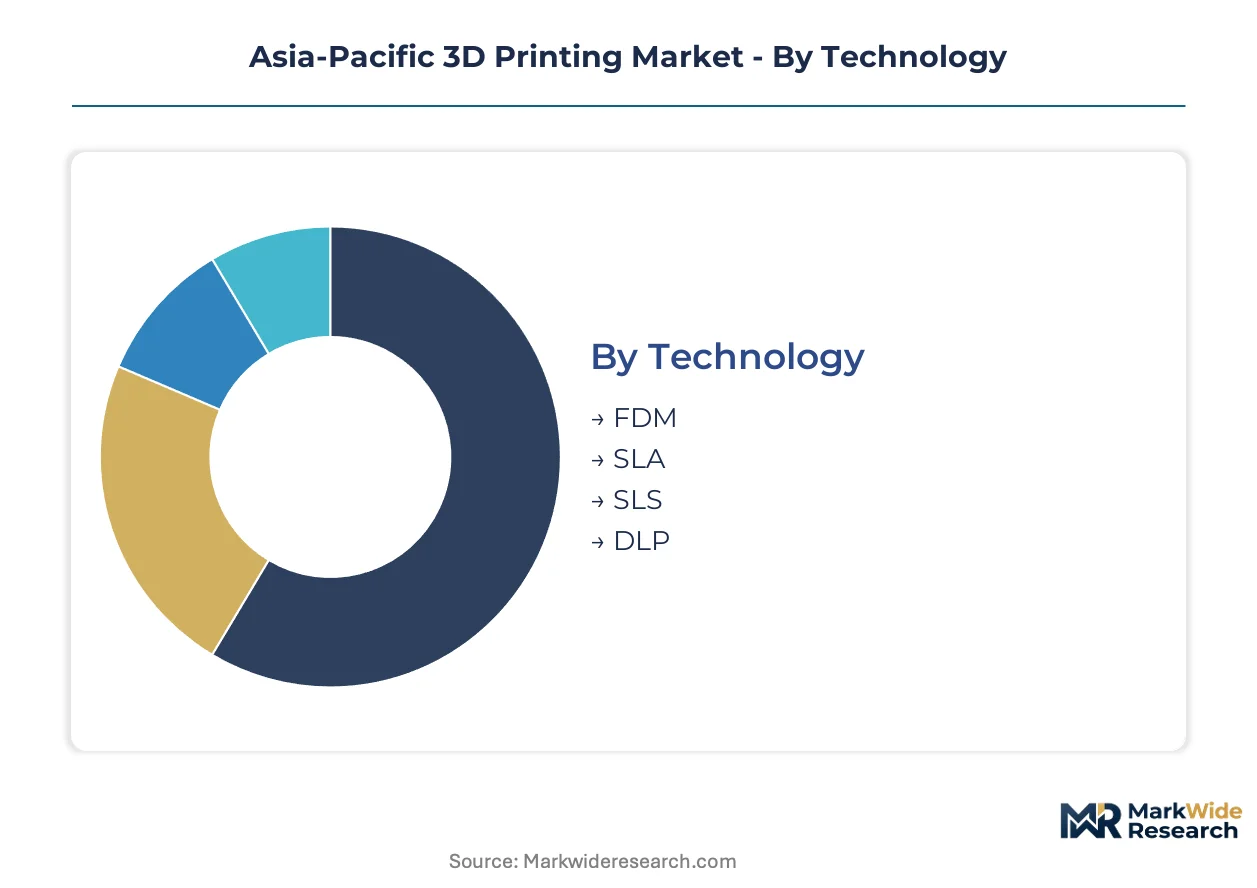
Technology choice in Asia-Pacific 3D printing hinges on tolerance requirements, throughput demands, and capital access. Material certification pathways and end-use regulatory frameworks further fragment procurement patterns across aerospace clusters and medical device hubs.
Technology:
Capital intensity and geometric precision requirements separate prototyping adopters from serial production buyers.
- FDM:Fused deposition modeling extrudes thermoplastic filaments through heated nozzles, building parts layer-by-layer with ±0.2 mm typical tolerance. China's Yangtze River Delta education and prototyping sectors drive installed base expansion, though throughput limitations constrain automotive serial adoption.
- SLS:Selective laser sintering fuses polymer powders with CO2 lasers, enabling unsupported geometries and nylon PA12 functional parts. Japanese automotive suppliers in Nagoya prefecture embed SLS into jigs and interior component workflows, leveraging Farsoon's domestic laser sourcing for cost control.
- SLA:Stereolithography cures photopolymer resins with UV lasers, delivering ±0.1 mm precision for dental and jewelry patterns.
- DLP:Digital light processing projects entire layers simultaneously, accelerating ceramic and microfluidic component throughput.
Volume sits with FDM; growth tilts toward SLS as automotive qualification accelerates.
End User:
Certification burden and part complexity dictate equipment selection and material sourcing strategies.
- Aerospace:Flight-critical titanium and nickel superalloy components demand MIIT-certified metal powder bed fusion systems. China's COMAC supply chain and South Korean engine manufacturers concentrate demand in Shanghai and Seoul metropolitan clusters, where traceability documentation determines vendor selection.
- Healthcare:Patient-specific implants and surgical guides require TGA or MFDS biocompatibility certification. Australia's Melbourne-Sydney corridor and South Korea's Seoul-Gyeonggi region dominate orthopedic lattice production, with topology optimization expertise creating supplier differentiation.
- Automotive:Interior components and tooling fixtures prioritize polymer throughput over metallurgical precision.
- Consumer Electronics:Rapid design iteration cycles favor desktop FDM and resin systems for enclosure prototyping.
Procurement scale clusters in aerospace; margin expansion tilts toward healthcare as implant personalization deepens.
Material Type:
Supply scarcity and post-processing requirements stratify cost structures across end-use categories.
- Metals:Titanium Ti-6Al-4V and nickel superalloy powders command premium pricing tied to aerospace certification scarcity. China's domestic atomization capacity expansion under MIIT guidance is compressing import dependency for Yangtze River Delta tooling manufacturers.
- Polymers:Nylon, ABS, and photopolymers dominate unit volume across prototyping and education segments. HP Inc.'s Multi Jet Fusion platform anchors Japanese automotive supply chain adoption, with open material architectures eroding single-source resin lock-in.
- Ceramics:Alumina and silicon carbide address semiconductor wafer handling and dental crown applications.
- Composites:Carbon fiber-reinforced filaments and continuous fiber deposition bridge stiffness-to-weight gaps in motorsport and drone manufacturing.
Revenue concentrates in metals; ceramics are expanding most quickly as Taiwanese and South Korean fab tooling demand accelerates.
Application:
Time-to-value expectations and quality documentation depth determine service pricing and equipment deployment models.
- Prototyping:Design validation and form-fit testing drive lowest-barrier technology adoption. Shenzhen electronics OEMs and Bangkok design houses operate dense FDM and SLA fleets, with 24-hour turnaround expectations compressing per-part pricing toward material cost floors.
- Production:Serial manufacturing of end-use components requires MES integration and statistical process control. Japan's METI interoperability standards are accelerating multi-brand shop floor deployment across Toyota and Honda supply chains.
- Tooling:Jigs, fixtures, and mold inserts exploit geometric freedom for conformal cooling channels.
- Education:University and vocational training programs build operator talent pipelines.
Unit volume sits with prototyping; value capture tilts toward production as automotive lot sizes scale beyond pilot quantities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta and Pearl River Delta manufacturing clusters concentrate regional demand for metal powder bed fusion systems, while Japan's automotive supply chains and Australia's medical device corridors anchor specialized end-use adoption across distinct regulatory environments.
China
Domestic aerospace tooling and automotive serial production drive equipment procurement in Shanghai and Shenzhen metropolitan areas. MIIT's additive manufacturing industry development plan accelerates equipment certification pathways and compresses capital procurement timelines for Yangtze River Delta manufacturers. Pearl River Delta electronics OEMs integrate polymer additive manufacturing into rapid prototyping workflows with 24-hour turnaround requirements.
Japan
Automotive interior components and conformal cooling tooling for injection molds sustain polymer system demand across Toyota and Honda supply chains. METI's industrial equipment interoperability standards mandate open architecture data formats, reducing vendor lock-in and accelerating multi-brand shop floor integration. Nagoya prefecture suppliers embed selective laser sintering into just-in-time jigs and fixture production.
South Korea
Engine component manufacturing and semiconductor fab tooling create dual demand channels for metal and ceramic additive processes. MFDS biocompatibility testing protocols for dental and orthopedic devices differentiate certified from uncertified material suppliers. Seoul-Gyeonggi region concentrates patient-specific implant production and topology-optimized lattice manufacturing for orthopedic applications.
Australia
Patient-specific titanium implants and surgical guides dominate healthcare demand within the Melbourne-Sydney corridor. TGA's medical device quality management frameworks regulate implant production traceability and post-processing documentation requirements. Distributed maritime maintenance operations across coastal cities generate point-of-use metal printing demand for spare part production.
Singapore
Aerospace tooling contracts and precision engineering services anchor high-value additive manufacturing in the city-state's Jurong and Tuas industrial zones. Port congestion and limited warehousing space create structural demand for on-demand production of marine maintenance components. Electronics contract manufacturers integrate desktop systems for enclosure prototyping serving regional OEMs.
Asia-Pacific 3D Printing Market Competitive Landscape
Chinese producers anchor the domestic equipment tier; European and North American specialists hold premium positions in certified aerospace and medical applications. Market structure fragments across three tiers: integrated material-equipment-service providers capturing margin in production workflows, pure-play equipment vendors competing on capital cost, and contract manufacturers unbundling qualification documentation from per-gram pricing. Dominant competitive moves include backward integration into laser and scanner production, plus strategic partnerships for MES connectivity with legacy ERP systems.
Among Asia-Pacific-based fabricators, Farsoon exemplifies cost competitiveness through in-house component production. HP Inc. and Stratasys occupy positions within the polymer production workflow tier, with the former anchoring Japanese automotive supply chain adoption and the latter competing for aerospace tooling contracts. These three companies represent distinct strategic archetypes: domestic vertical integration, multinational platform breadth, and specialized application focus.
| Leading Market Players |
|---|
| HP Inc. |
| Farsoon |
| Stratasys |
| Renishaw |
| Formlabs |
| 3D Systems |
| Materialise NV |
| Markforged |
| EOS GmbH |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between MIIT-certified metal powder bed fusion systems and uncertified polymer prototyping equipment manifests in divergent margin structures and procurement channel configurations across Asia-Pacific manufacturing clusters. Premium aerospace-grade titanium and nickel superalloy powder pricing rests on scarce atomization capacity, while commodity FDM filament supply chains compress toward material cost floors in China's Yangtze River Delta education sector.
Pricing Analysis
Volume sits with polymer prototyping equipment where per-gram pricing approaches material-plus-labor cost floors, while margin concentrates in certified metal powder bed fusion systems serving aerospace and medical implant workflows. Price differentiation hinges on material traceability documentation depth and MIIT certification tier, with Japanese automotive buyers prioritizing open-architecture material compatibility over single-source resin lock-in. Cost compression in desktop FDM segments intensifies as Chinese domestic equipment producers expand Yangtze River Delta distribution. Contract manufacturers exhibit highest price sensitivity, while COMAC supply chain and Seoul engine manufacturers accept premium positioning for qualified titanium lattice structures.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from COMAC and South Korean engine manufacturers, while distributor networks serve Thailand and Malaysia tier-two automotive suppliers with sub-48-hour tooling turnaround requirements. Geographic supply concentration centers on China for domestic laser and scanner components, Japan for precision optics and motion control systems, and Germany for high-power fiber laser sources. Raw material dependencies include aerospace-grade gas-atomized titanium powder, certified nylon PA12 polymer feedstock, and silicon carbide ceramic precursors for semiconductor tooling. Single-source vulnerability in nickel superalloy powder supply creates allocation risk for flight-critical component manufacturers. Distribution runs through integrated material-equipment-service providers in China's Pearl River Delta, with contract manufacturers unbundling qualification documentation from per-gram pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific 3D printing operates as a cost-of-compliance market where China's MIIT equipment certification reform and Australia's TGA patient-specific implant framework erect barrier-to-entry moats favoring certified domestic producers over import-dependent competitors.
For Market Incumbents: Anchor market position through backward integration into laser and scanner production, mirroring Farsoon's in-house component manufacturing model that sustains cost competitiveness in selective laser sintering systems. Expand certified material traceability depth to capture margin concentration in COMAC supply chain and Seoul-Gyeonggi orthopedic implant workflows. Defend against emerging Chinese domestic equipment producers by accelerating MES connectivity partnerships with legacy SAP and Oracle production planning systems. For New Entrants and Emerging Players: Indonesian archipelago maritime maintenance operators represent an underserved buyer archetype with structural demand for point-of-use metal printing driven by island geography and port congestion. Target ceramic semiconductor tooling for South Korean and Taiwanese fabs, where silicon carbide and alumina additive processes address wafer handling component shortages. Pursue qualification-documentation-as-service bundling to differentiate from incumbent per-gram pricing models. For Investors and Strategic Acquirers: Re-rating potential sits with integrated material-equipment-service providers given the shift toward certified material traceability depth as primary vendor selection criterion across China's Pearl River Delta. Long-term viability favors players with captive atomization capacity and MIIT certification pathways. Acquisition target archetype: domestic Chinese producers with in-house laser production and established Yangtze River Delta aerospace customer relationships. Monitor MFDS biocompatibility testing protocol enforcement as inflection indicator for orthopedic implant market access differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Production | Farsoon's in-house scanner sourcing compresses equipment cost structures for selective laser sintering systems. |
| MES-ERP Connectivity Partnership | Bridging additive job scheduling gaps with SAP and Oracle systems accelerates automotive serial production scaling. |
| Ceramic Semiconductor Tooling Qualification | Silicon carbide additive processes address wafer handling shortages in South Korean and Taiwanese fabrication facilities. |
| Open Architecture Material Certification | HP Inc.'s Multi Jet Fusion platform reduces single-source resin lock-in across Japanese automotive supply chains. |
| Distributed Maritime Maintenance Deployment | Indonesian archipelago point-of-use metal printing exploits structural port congestion and island geography constraints. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia-Pacific 3D printing analysis. Primary interviews with equipment procurement managers at Chinese aerospace contractors, biomedical engineers at Australian orthopedic implant producers, and polymer supply chain directors at Japanese automotive tier-one suppliers combined with MIIT certification database cross-referencing and TGA medical device register extraction. Bottom-up equipment shipment tracking from Yangtze River Delta and Pearl River Delta manufacturing clusters reconciled with top-down market sizing across technology, material, and end-use segmentation dimensions.
Data-stream reconciliation across customs import records, domestic production registrations, and end-user equipment deployment surveys shaped the analytical framework across the projection horizon. Segmentation modeling incorporated technology type, material certification tier, end-use regulatory cluster, and geographic manufacturing hub. CAGRs derived from equipment replacement cycle analysis and serial production adoption curve calibration, with specific inputs including MIIT additive manufacturing industry development plan implementation velocity and METI industrial equipment interoperability standard enforcement timelines.
Revisions become necessary when MIIT certification pathway acceleration exceeds baseline assumptions, when nickel superalloy powder supply concentration shifts through new atomization capacity entry, or when divergent national build chamber atmosphere standards create cross-border equipment incompatibility beyond modeled friction. Periodic stress-testing of base assumptions against actual vendor selection criteria evolution in China's Pearl River Delta electronics OEM procurement patterns is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Europe 3D Printing Market
3D Printing Technology
Global 3D Printing in Medical Applications Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
Global 4D Printing in Healthcare Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
3D Printer Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
North America Additive Manufacturing Market
3D Printing Technology
3D Printing Enabled Augmented Manufacturing Market