
 Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market | 2026-2036
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market Outlook
China's titanium powder production base is expanding, lowering feedstock costs for regional medical device fabricators. GE Healthcare leverages its imaging-to-print workflow integration to anchor hospital contracts across East Asian markets. Stratasys competes through polymer expertise in dental aligner manufacturing, while Materialise sustains software dominance in surgical planning platforms that drive hardware utilization.
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) encompasses layer-by-layer fabrication of patient-specific implants, surgical instruments, and biological scaffolds using biocompatible polymers, metals, and living cell suspensions, with typical build resolutions ranging from 20 to 100 microns depending on the modality. Its primary purpose is to convert digital anatomical models into physical objects that match individual patient geometry, reducing operative time and improving clinical outcomes. Medical implants command the largest product type revenue pool due to spinal and cranial reconstruction demand, while bioprinting materials represent the fastest-expanding category as academic medical centers in South Korea and Australia scale organoid research programs. Selective laser sintering dominates orthopedic applications for cobalt-chrome and titanium porosity control, whereas digital light processing is displacing conventional molding in dental crown production across Japanese clinics.
Japan's PMDA custom-made medical device notification system and South Korea's MFDS biocompatibility testing requirements for powder-bed fusion implants shape product development timelines and market entry costs. China's NMPA has tightened quality management specifications for 3D-printed implantable metals, forcing domestic manufacturers toward ISO 13485 certification. India's CDSCO draft guidance on patient-specific implants signals emerging regulatory clarity that contract manufacturing organizations must monitor for facility investment decisions.
Market Dynamics
Hospital procurement centralization across China's tier-one clusters is compressing vendor margins while accelerating ISO 13485 adoption among domestic metal powder suppliers. This structural shift toward consolidated purchasing power is redrawing competitive boundaries for implant fabricators.
Growth Catalysts
- PMDA Notification Pathway:Japan's streamlined custom-made medical device framework reduces approval timelines for patient-specific cranial implants, encouraging hospital adoption of point-of-care manufacturing workflows.
- Titanium Powder Supply:China's expanding domestic sponge production base is lowering feedstock costs for regional selective laser sintering operations serving spinal implant manufacturers.
- Organoid Research Scaling:Academic medical centers in South Korea and Australia are accelerating bioprinting platform deployment for liver and kidney tissue engineering, creating pull-through demand for bioink formulations.
Market Restraints
- Metal Powder Concentration:High-purity titanium and cobalt-chrome feedstock supply concentrates among a limited set of plasma atomization specialists, exposing fabricators to input cost volatility.
- Biocompatibility Testing Burden:South Korea's MFDS powder-bed fusion implant requirements impose extended validation timelines that delay product commercialization by 18-24 months.
- Polymer Substitution Threat:Conventional CNC milling of PEEK spinal cages retains cost advantages for standard geometries, limiting addressable market expansion for additive alternatives.
Strategic Opportunities
- India's Emerging Clarity:CDSCO draft guidance on patient-specific implants signals forthcoming regulatory structure that contract manufacturers can anticipate for facility investment planning.
- Imaging-to-Print Convergence:Integration of preoperative CT segmentation software with in-house metal printing is enabling same-day surgical guide production at Japanese orthopedic centers.
- Dental Channel Innovation:Chairside digital light processing systems are displacing traditional crown molding across Japanese clinics, opening direct-to-practice distribution bypassing dental laboratories.
Industry Challenges
- Process Validation Complexity:China's NMPA tightened quality management specifications for implantable metals require manufacturers to demonstrate batch-to-batch porosity consistency across build platforms.
- Computational Anatomy Expertise Gap:Hospital adoption of surgical planning software outpaces availability of biomedical engineers capable of translating DICOM data into print-ready mesh files.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market |
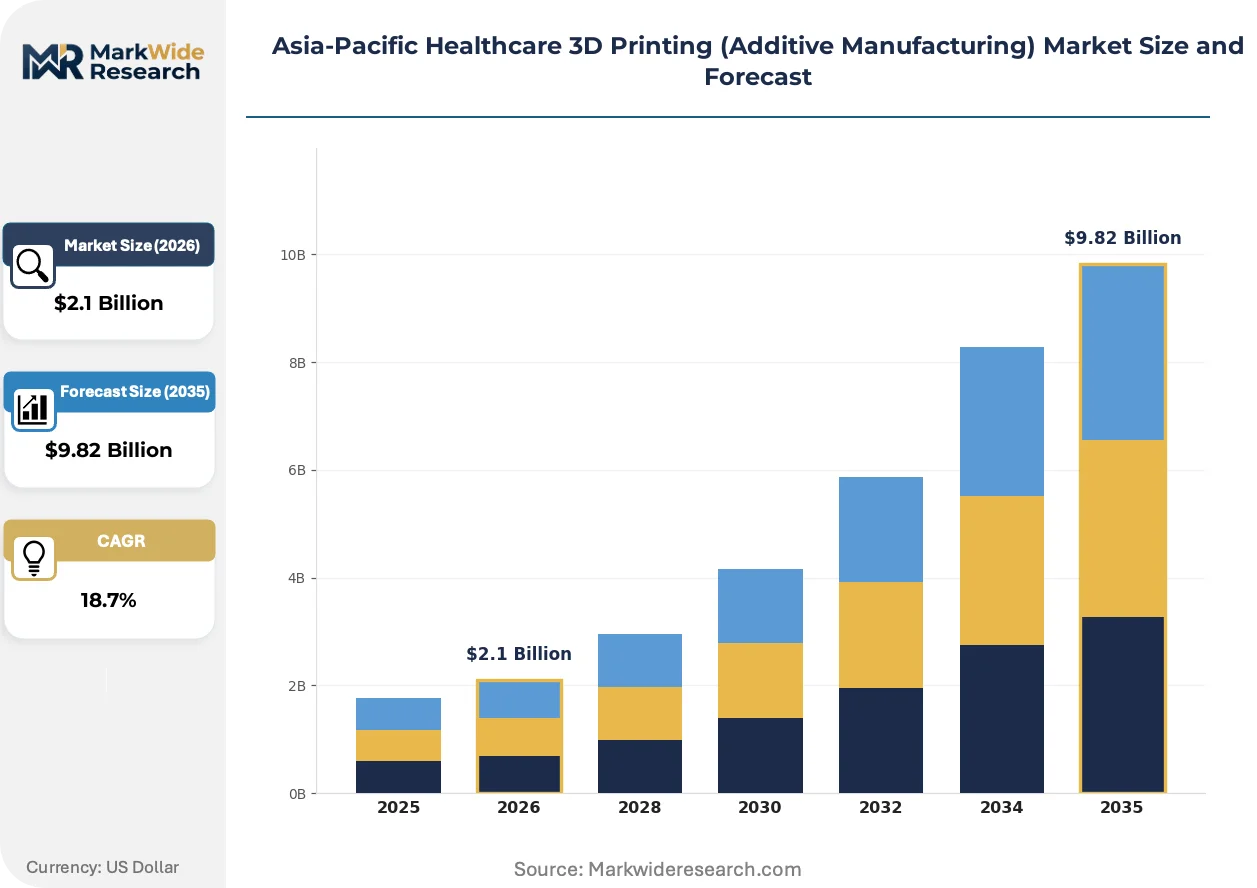
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.82 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Implants, Surgical Instruments, Prosthetics, Bioprinting Materials End User: Hospitals, Clinics, Research Institutions, Contract Manufacturing Organizations Technology: Stereolithography, Fused Deposition Modeling, Selective Laser Sintering, Digital Light Processing Application: Orthopedic Surgery, Dental applications, Cardiovascular Devices, Tissue Engineering |
| Companies Covered | EnvisionTEC, GE Healthcare, 3D Systems, Imaginarium, Nanoscribe, Materialise, EOS GmbH, JGroup Robotics, Stratasys, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market Strategic Shifts
Workflow automation and point-of-care manufacturing are collapsing traditional boundaries between diagnostic imaging, surgical planning, and implant fabrication across Asia-Pacific hospital networks.
Multi-material jetting systems incorporating both rigid and flexible photopolymers are rewriting dental restoration production by enabling monolithic dentures with differentiated tissue-contact and occlusal surfaces in a single build. Japanese prosthodontic laboratories are adopting these platforms at accelerating pace to replace labor-intensive conventional casting. This capability compression is eroding the historical separation between crown fabrication and full-arch reconstruction services.
China's NMPA has tightened quality management specifications for 3D-printed implantable metals, forcing domestic manufacturers toward ISO 13485 certification and documented process validation. The industrial consequence is a bifurcation between certified suppliers eligible for centralized hospital procurement and uncertified fabricators relegated to research or export markets. Spinal implant categories face the most immediate compliance pressure as tier-one hospital clusters consolidate vendor qualification.
Centralized procurement of surgical guides is concentrating purchasing authority within China's provincial health commissions, displacing the traditional hospital-level autonomy that previously sustained fragmented vendor relationships. Large orthopedic centers in Shanghai and Beijing are consolidating annual contract values across multi-hospital systems, replacing transactional spot purchasing. This behavioral shift is most visible in spinal and trauma applications where standard guide geometries permit volume aggregation.
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market Segmentation
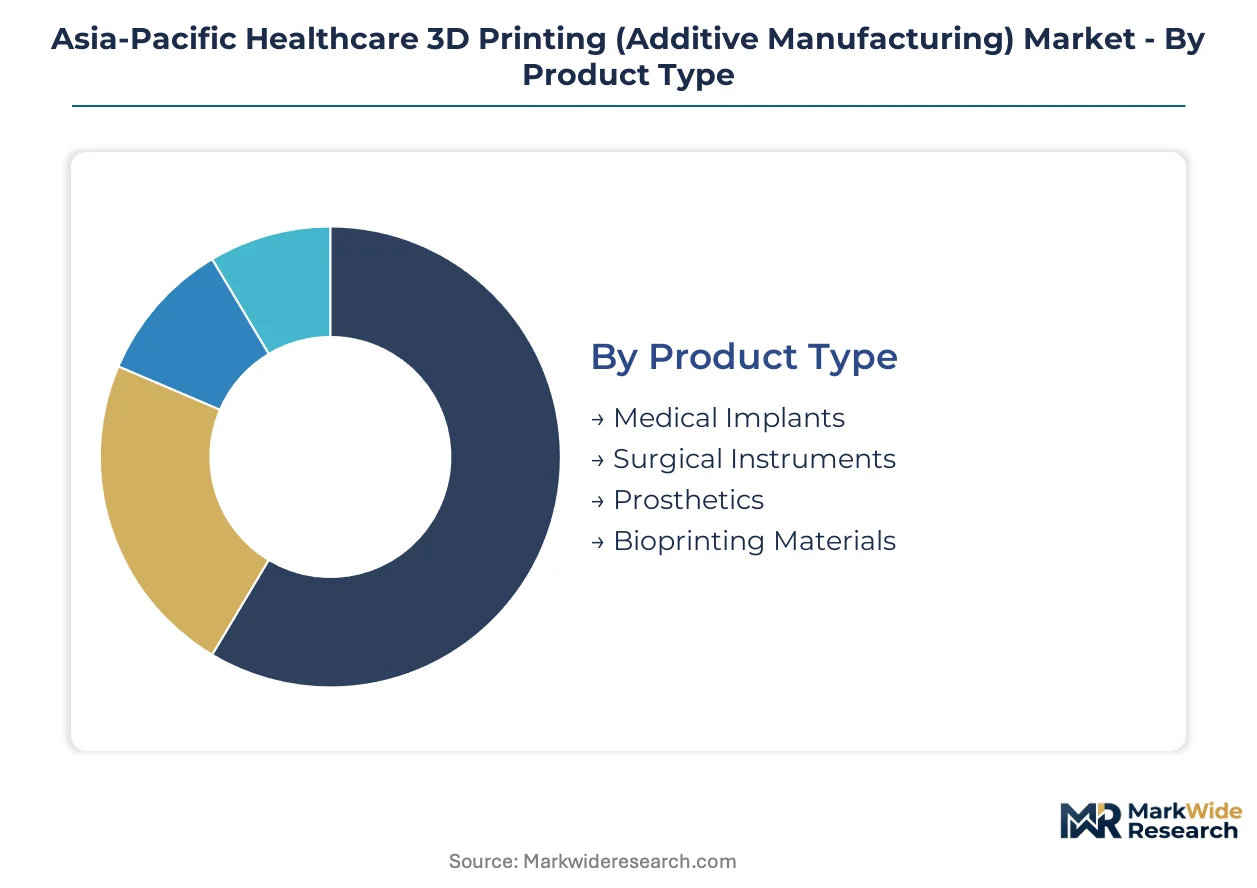
Patient-specific geometry requirements and regulatory pathways across Japan, China, and South Korea create divergent demand profiles that reward granular segment targeting. Fabricators must align technology portfolios with end-user procurement centralization and application-specific biocompatibility validation timelines.
Product Type:
Material specifications and regulatory classification tiers determine margin structures and hospital procurement eligibility across the region's tier-one clusters.
- Medical Implants:Titanium and cobalt-chrome spinal cages, cranial plates, and hip acetabular cups fabricated through selective laser sintering dominate revenue pools. China's NMPA tightened quality management specifications for implantable metals force ISO 13485 certification for centralized hospital procurement eligibility.
- Bioprinting Materials:Bioink formulations incorporating living cell suspensions and hydrogel scaffolds for organoid research programs. Academic medical centers in South Korea and Australia are accelerating platform deployment for liver and kidney tissue engineering, creating pull-through demand for specialized formulations.
- Surgical Instruments:Patient-specific cutting guides and drill jigs in sterilizable polymers. Japanese orthopedic centers leverage same-day production workflows integrated with preoperative CT segmentation software.
- Prosthetics:Custom-fit limb sockets and facial prostheses utilizing multi-material jetting for differentiated tissue-contact surfaces. Japanese prosthodontic laboratories adopt these platforms to replace labor-intensive conventional casting methods.
Medical Implants leads on scale; Bioprinting Materials leads on momentum.
End User:
Procurement authority concentration and technical capability requirements segment addressable markets by validation burden and contract value thresholds.
- Hospitals:Tier-one clusters in Shanghai and Beijing consolidate annual contract values across multi-hospital systems, displacing transactional spot purchasing for spinal and trauma surgical guides. Centralized provincial health commissions now control vendor qualification and pricing negotiations.
- Contract Manufacturing Organizations:CDSCO draft guidance on patient-specific implants signals emerging regulatory clarity that CMOs must monitor for facility investment decisions across India's developing market structure.
- Research Institutions:Academic medical centers drive bioprinting platform adoption for organoid research with less immediate commercial pressure but significant technology pull-through potential.
- Clinics:Chairside digital light processing systems in Japanese dental clinics enable direct crown production bypassing traditional laboratory intermediaries.
Hospitals capture the largest contract values; Contract Manufacturing Organizations face the steepest compliance ramp.
Technology:
Build resolution, material compatibility, and throughput economics position each modality for specific anatomical applications and end-user scale requirements.
- Selective Laser Sintering:Powder-bed fusion of titanium and cobalt-chrome enables controlled porosity for osseointegration in spinal and cranial implants. South Korea's MFDS biocompatibility testing requirements impose extended validation timelines that delay commercialization by 18-24 months.
- Digital Light Processing:Photopolymer vat polymerization delivers 20-50 micron resolution for dental crown production and full-arch reconstructions. Japanese prosthodontic laboratories adopt multi-material systems enabling monolithic dentures with differentiated surface properties in single builds.
- Stereolithography:Laser-cured resin systems for surgical guide prototypes and anatomical models requiring high surface fidelity.
- Fused Deposition Modeling:Thermoplastic extrusion for low-cost anatomical models and surgical planning aids with broader accessibility but limited implant-grade material options.
Selective Laser Sintering commands orthopedic market share; Digital Light Processing expands fastest in dental channels.
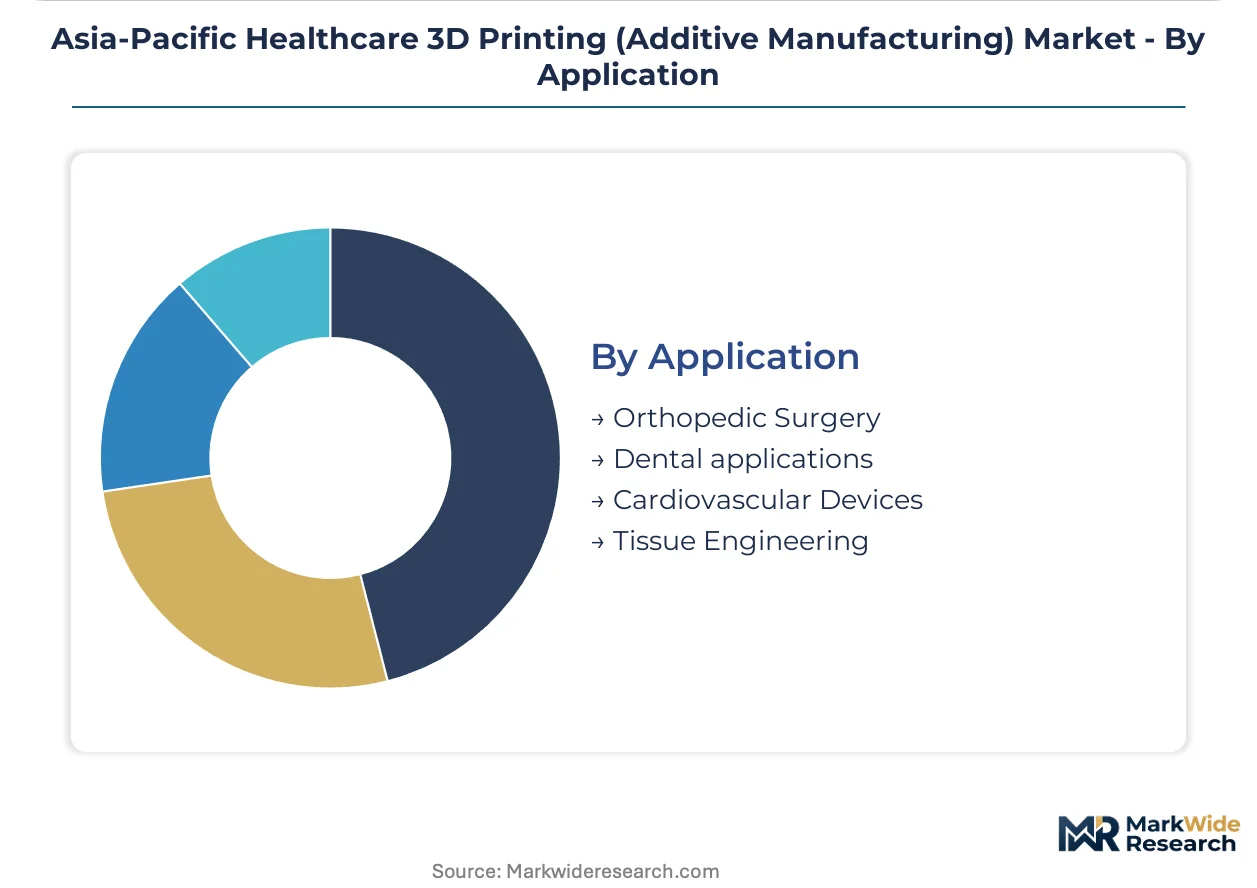
Application:
Anatomical complexity and reimbursement pathways determine technology selection and point-of-care manufacturing feasibility across regional hospital networks.
- Orthopedic Surgery:Patient-specific implants and surgical guides for spinal reconstruction and trauma fixation. Japan's PMDA custom-made medical device notification system reduces approval timelines for cranial implants, encouraging point-of-care manufacturing workflows.
- Dental Applications:Crown, bridge, and denture fabrication through chairside and laboratory-based systems. Chinese tier-one hospital clusters drive centralized procurement of surgical guides for implant placement procedures.
- Tissue Engineering:Bioprinted scaffolds and organoid research programs for regenerative medicine applications. Australian academic medical centers scale liver and kidney tissue engineering initiatives.
- Cardiovascular Devices:Patient-specific vascular models and device sizing tools from preoperative imaging data.
Orthopedic Surgery anchors revenue concentration; Tissue Engineering gains share fastest from research scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production footprints across Asia-Pacific as fabricators migrate toward jurisdictions offering streamlined custom-device pathways and lower validation burdens. Cost-of-compliance gaps between mature and emerging frameworks are accelerating facility investment decisions.
Japan
PMDA's custom-made medical device notification system attracts cranial implant fabricators seeking reduced approval timelines. Tokyo's orthopedic centers deploy same-day surgical guide production integrated with CT segmentation workflows. Kanto region hospitals anchor point-of-care manufacturing adoption.
China
NMPA tightened quality specifications force ISO 13485 certification for centralized tier-one hospital procurement eligibility. Yangtze River Delta metal powder suppliers expand sponge production to lower selective laser sintering feedstock costs. Shanghai and Beijing clusters consolidate multi-hospital annual contracts.
South Korea
MFDS biocompatibility testing requirements for powder-bed fusion implants extend validation timelines. Academic medical centers in Seoul accelerate bioprinting platform deployment for liver and kidney organoid research. Seoul Capital Area drives bioink formulation demand.
Australia
TGA oversight of patient-specific implants aligns with EU MDR convergence trends. Melbourne and Sydney academic medical centers scale tissue engineering research programs. Victoria anchors bioprinting infrastructure investment.
India
CDSCO draft guidance on patient-specific implants signals emerging regulatory structure for contract manufacturing planning. Maharashtra and Gujarat medical device zones attract fabrication facility interest. Mumbai-Pune corridor positions for CMO investment.
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bioprinting specialization and dental chairside integration. The vendor base stratifies across imaging-to-print workflow integrators, polymer platform specialists, and metal powder-bed fusion fabricators. Three archetypes dominate: diversified healthcare conglomerates leveraging diagnostic imaging relationships, pure-play additive equipment manufacturers, and software-centric surgical planning platforms. Capacity expansion and strategic technology licensing represent the primary competitive vectors as participants defend hospital contract positions.
Among imaging-integrated conglomerates, GE Healthcare anchors workflow convergence between diagnostic equipment and point-of-care fabrication. Polymer specialists Stratasys and Materialise occupy distinct positions—Stratasys exemplifies dental aligner manufacturing expertise while Materialise represents software-driven surgical planning dominance that drives hardware utilization across regional hospital networks.
| Leading Market Players |
|---|
| EnvisionTEC |
| GE Healthcare |
| 3D Systems |
| Imaginarium |
| Nanoscribe |
| Materialise |
| EOS GmbH |
| JGroup Robotics |
| Stratasys |
| Others |
Value Chain & Pricing Dynamics
Titanium sponge price indices cascading from China's Yangtze River Delta production hubs compress feedstock costs for regional selective laser sintering operations while tier-one hospital procurement centralization in Shanghai and Beijing squeezes finished-implant margins into three distinct certification-grade tiers.
Pricing Analysis
Distributor markups on biocompatible metal powders stratify across ISO 13485-certified premium channels, uncertified standard-tier spot markets, and research-grade economy supply. Price differentiation hinges on NMPA audit documentation completeness and batch-to-batch porosity validation depth. Pricing pressure intensifies as provincial health commissions consolidate annual contract negotiations across multi-hospital systems. Research institutions exhibit lowest price sensitivity due to grant-funded procurement autonomy.
Supply Chain Analysis
China's domestic-content mandates for medical device procurement reshape sourcing patterns toward Yangtze River Delta sponge producers and Shanxi titanium powder atomizers. High-purity cobalt-chrome feedstock draws from plasma atomization specialists in Japan and Germany. Single-source vulnerability concentrates in gas-atomization equipment for superfine powder grades. Distribution runs through hospital GPO contracts and direct OEM relationships with tier-one orthopedic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge from the eighteen-to-twenty-four-month validation gap between South Korea's MFDS biocompatibility requirements and Japan's streamlined PMDA notification pathway, rewarding fabricators with dual-jurisdiction production footprints.
For Market Incumbents: Cement hospital contract positions through backward integration into titanium powder production and captive CT-segmentation software development. Polymer substitution threats from CNC-milled PEEK cages demand defensive certification investments in multi-material jetting capabilities for dental prosthetics. For New Entrants and Emerging Players: Dental laboratory channel partnerships offer lowest barrier-to-entry penetration in Japan's prosthodontic market. India's CDSCO draft guidance window presents white-space opportunity for contract manufacturing facility pre-positioning ahead of formalized patient-specific implant rules. Target bioprinting bioink formulation supply to Seoul and Melbourne academic medical centers. For Investors and Strategic Acquirers: Asymmetric upside sits with software-centric surgical planning platforms whose hospital utilization rates drive hardware pull-through across Asia-Pacific networks. Five-to-ten-year viability favors imaging-to-print workflow integrators over pure-play equipment manufacturers. Monitor PMDA notification volume trends as inflection signal for point-of-care manufacturing adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Dual-Jurisdiction Certification | Japan's notification pathway reduces approval timelines versus South Korea's MFDS validation burden. |
| Imaging-to-Print Workflow Integration | GE Healthcare anchors hospital contracts through CT-segmentation-to-fabrication convergence. |
| ISO 13485 Certification Investment | China's NMPA tightened specifications force domestic manufacturers toward centralized procurement eligibility. |
| Bioink Formulation Partnership | Academic medical centers in Seoul and Melbourne drive organoid research platform deployment. |
| Provincial GPO Contract Consolidation | Shanghai and Beijing health commissions displace hospital-level autonomy with multi-hospital annual contracts. |
Study Parameters
Multiple input streams — primary interviews with biomedical engineers and hospital purchasing committee members, secondary validation against NMPA filing databases and GPO contract registries, and trade-flow analysis of titanium powder customs records — were reconciled through bottom-up and top-down triangulation. Hospital procurement managers, selective laser sintering operations directors, PMDA regulatory consultants, and dental laboratory owners provided qualitative ground-truth on workflow adoption and pricing dynamics.
Segmentation dimensions across the projection horizon encompass product type, end-user procurement authority concentration, technology modality, and application-specific reimbursement pathways. CAGRs derive from installed-base growth modeling for metal powder-bed fusion systems and bioink platform deployment rates at academic medical centers. Forecast inputs incorporate NMPA certification timeline probabilities and MFDS biocompatibility testing queue lengths.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA notification pathway revisions, MFDS testing requirement modifications, and China's provincial procurement centralization pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
Metal 3D Printing Service Market
3D Printing Technology
Additive Manufacturing Software Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
Selective Laser Sintering Market
3D Printing Technology
Military 3D and 4D Printing Market
3D Printing Technology
Global 4D Printing in Healthcare Market
3D Printing Technology
Europe Industrial 3D Printing Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
Conventional and Rapid Prototyping Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market