
 3D Manufacturing Software Market | 2026-2036
3D Manufacturing Software Market Size, Share, and Industry Trends Forecast 2026-2036
3D Manufacturing Software Market Insights
Subscription-based access to simulation modules is rebalancing how vendors monetize 3D manufacturing software, shifting capital expenditure into recurring operational budgets. Autodesk leverages its cloud-native architecture to sustain multi-tenant deployment across dispersed engineering teams. Siemens anchors industrial-grade digital thread capabilities through deep PLM integration. PTC differentiates by specializing in closed-loop feedback between generative design and shop-floor execution.
3D manufacturing software encompasses computer-aided design, manufacturing, and simulation tools that translate digital models into machine-ready instructions for additive and subtractive production systems. These platforms manage mesh generation, toolpath optimization, thermal modeling, and material deposition parameters to ensure geometric fidelity and structural integrity in final parts. CAD software retains the largest revenue footprint due to entrenched design workflows, while simulation software captures the fastest expansion as aerospace and automotive buyers stress-test additive components before physical builds. CAM software occupies a mature margin pool where post-processor customization for specific printer hardware creates vendor stickiness.
FDA's software-as-a-medical-device framework and the EU MDR's Annex I general safety requirements impose validation documentation burdens on healthcare-oriented 3D manufacturing platforms. REACH substance restrictions and the EU F-Gas Regulation constrain material qualification databases that software must maintain for compliant production planning. Stakeholders must monitor whether emerging carbon-accounting standards under the EU Green Deal embed emissions tracking as a mandatory software module rather than an optional add-on.
Market Dynamics
Simulation-driven additive workflows are compressing the design-to-production cycle, forcing software vendors to integrate thermal modeling and geometric fidelity tools into unified platforms rather than standalone modules.
Growth Catalysts
- EU AI Act compliance mandates:Aerospace and medical device manufacturers in Europe must validate algorithmic decision-making in production software, creating pull for certified simulation suites.
- Titanium lattice structures:Lightweighting demands in aviation are driving adoption of topology optimization modules that manage stress distribution across additively manufactured components.
- Germany's industrial software corridor:Concentrated engineering talent around Munich and Stuttgart accelerates co-development partnerships between OEMs and platform vendors.
Market Restraints
- GPU compute cost volatility:Cloud-based thermal simulation requires sustained access to high-performance processing, with pricing swings compressing margins for mid-tier vendors.
- Post-processor customization lock-in:Hardware-specific CAM configurations create switching costs that fragment buyer choice and slow platform consolidation.
- REACH substance database maintenance:European material qualification requirements impose recurring compliance burdens on software vendors managing material libraries.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are creating first-mover advantage for software vendors establishing localized validation support.
- Carbon-accounting module integration:Emerging EU Green Deal requirements may embed emissions tracking as mandatory functionality, opening subscription revenue streams.
- Generative design-to-execution convergence:Closed-loop feedback between AI-driven topology optimization and real-time build monitoring represents unclaimed platform territory.
Industry Challenges
- Multiphysics simulation expertise scarcity:The intersection of thermal, structural, and fluid dynamics modeling requires specialized talent that outpaces current training pipelines.
- FDA software-as-a-medical-device documentation:Healthcare-oriented platforms face extended validation timelines that delay revenue recognition and strain R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Manufacturing Software Market |
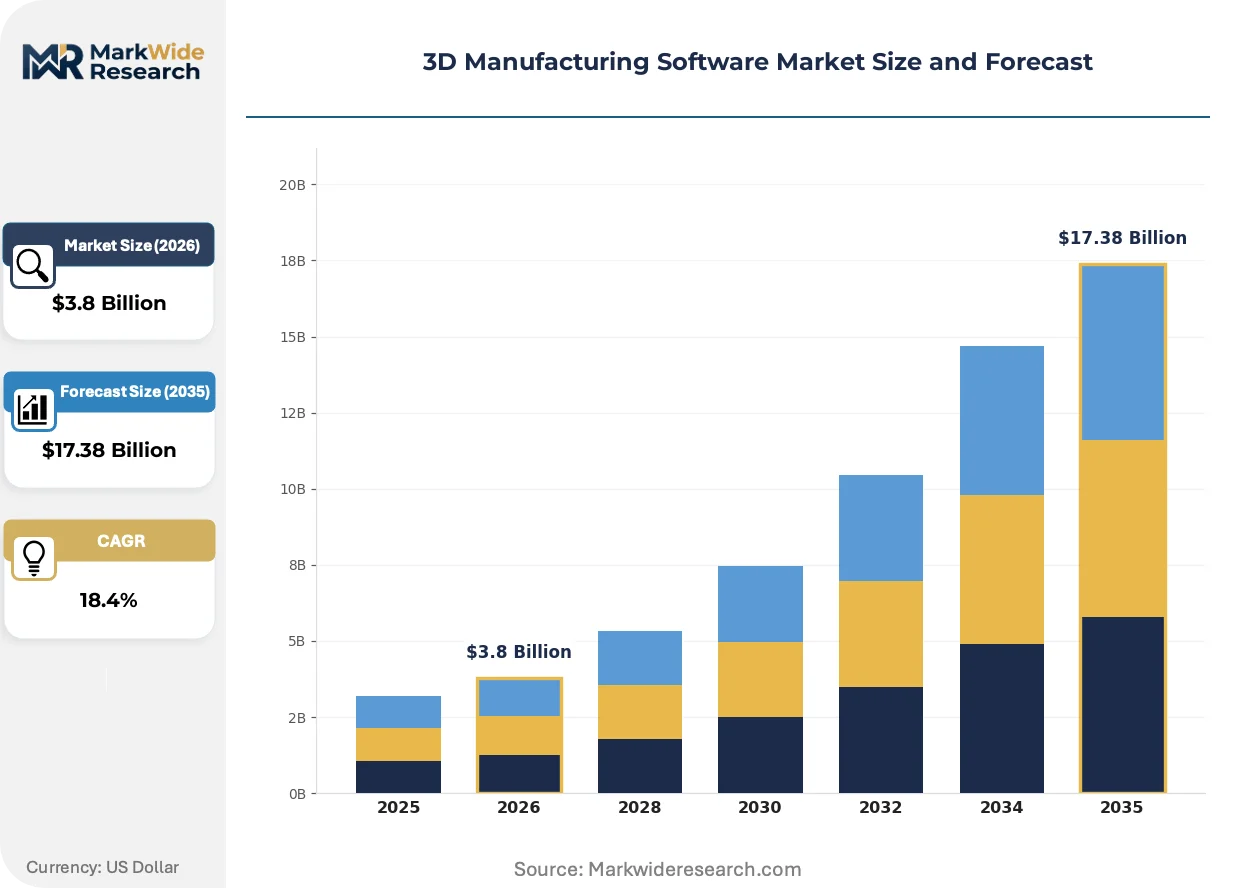
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAD Software, CAM Software, Simulation Software, Slicing Software End User: Aerospace, Automotive, Healthcare, Consumer Electronics Application: Prototyping, Tooling, Production, Post-Processing Technology: FDM, SLA, SLS, DLP |
| Companies Covered | Dassault Systèmes, Autodesk, PTC, Siemens, Hexagon, Materialise, Robert McNeel & Associates, Maxon Computer, UnionTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Manufacturing Software Market Trends and Innovations
Cloud-native architectures are dissolving the boundary between design, simulation, and production planning, enabling real-time iteration loops that were previously batch-processed overnight.
Digital thread platforms are unifying CAD, PLM, and shop-floor execution data into continuous feedback loops. Aerospace tier-one suppliers are adopting these integrated stacks to trace design changes through to final part qualification. This unification is compressing the validation window from weeks to days for critical flight hardware.
REACH substance restrictions and the EU F-Gas Regulation are forcing material database updates that cascade through entire software ecosystems. Vendors must now maintain dynamic compliance layers that flag restricted substances during the design phase. Medical device and automotive segments bear the heaviest adaptation costs as they manage multi-jurisdictional material approvals.
Engineering teams are consolidating vendor relationships around platforms that bundle simulation credits with core subscriptions. Discrete module purchasing is giving way to consumption-based access models. This pattern is most pronounced in North American aerospace clusters where capital efficiency pressures favor operational expenditure treatment.
3D Manufacturing Software Market Segmentation
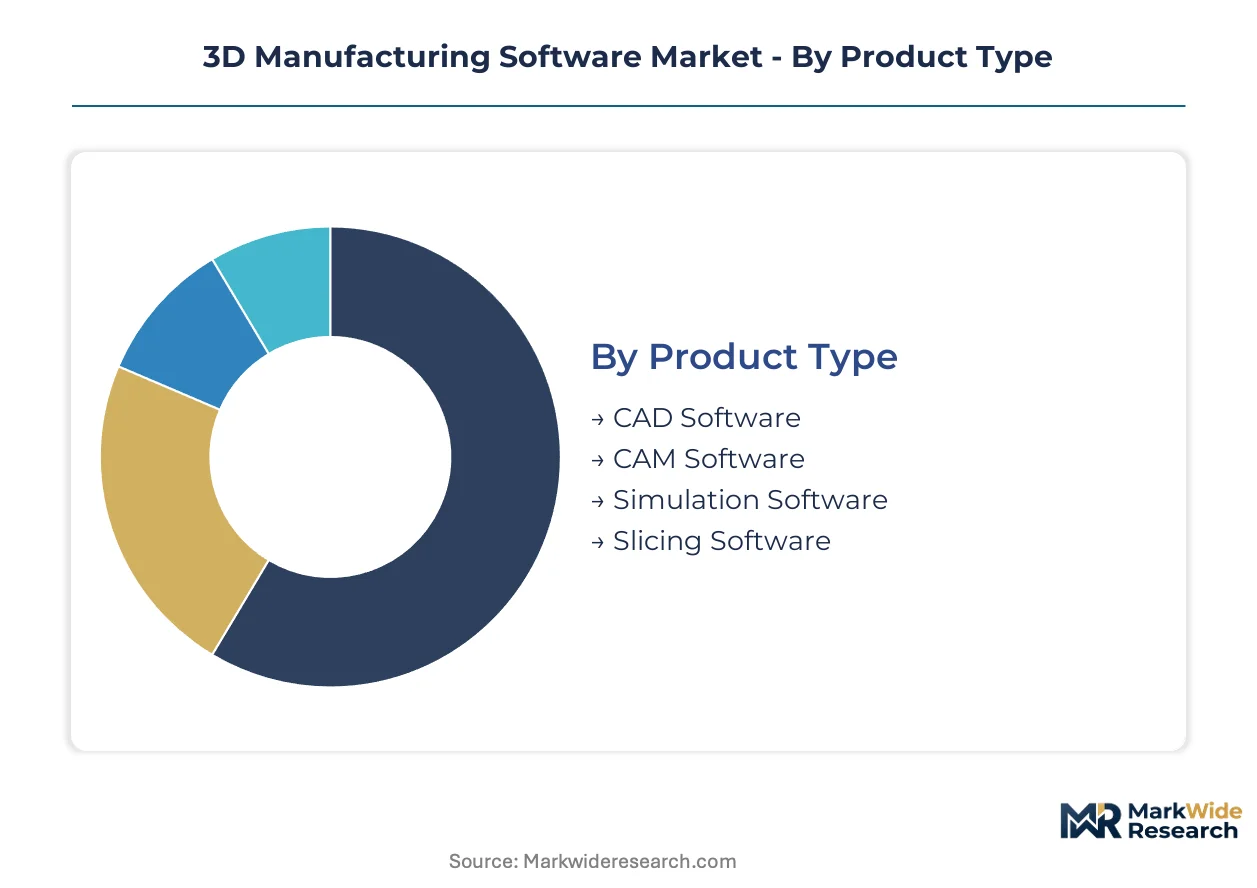
Segmentation in 3D manufacturing software reflects divergent buyer priorities across design complexity, production volume, and regulatory exposure. Procurement teams weight thermal simulation fidelity against post-processor flexibility depending on whether their mandate centers on aerospace qualification or consumer electronics speed-to-market.
Product Type:
Capital allocation patterns separate buyers investing in perpetual licenses from those favoring consumption-based simulation credits.
- CAD Software:Core geometry modeling and parametric design tools anchor entrenched engineering workflows across automotive and industrial machinery sectors. German automotive OEMs in Stuttgart and Munich maintain deep integration with legacy PLM systems, resisting platform migration despite cloud-native alternatives.
- Simulation Software:Multiphysics platforms combining thermal, structural, and fluid dynamics modeling command premium positioning as aerospace manufacturers validate additive components prior to physical builds. Lattice topology optimization for titanium aviation structures drives specialized module demand.
- CAM Software:Toolpath generation and post-processor customization for specific printer hardware creates vendor stickiness through hardware-specific configuration investments.
- Slicing Software:Layer-by-layer deposition planning utilities bridge design files and machine-ready instructions, with open-source alternatives pressuring commercial pricing in entry-level printer segments.
CAD software leads on scale; simulation software leads on momentum.
End User:
Regulatory burden intensity determines platform sophistication requirements and validation documentation depth.
- Aerospace:Flight-critical component qualification mandates traceable digital threads from design through production, with FAA airworthiness standards and EASA certification requirements imposing rigorous software validation protocols. Tier-one suppliers around Toulouse, Hamburg, and Seattle compress design-to-production cycles through integrated simulation suites.
- Healthcare:Patient-specific implant manufacturing falls under FDA software-as-a-medical-device frameworks and EU MDR Annex I safety requirements, extending validation timelines and documentation burdens. Patient-matched surgical guides and orthopedic implants drive specialized segmentation algorithms.
- Automotive:Tooling and prototyping applications prioritize speed over qualification depth, with Germany's industrial corridor accelerating co-development partnerships.
- Consumer Electronics:Rapid iteration cycles and cost-sensitive positioning favor entry-level CAD and slicing tools over enterprise simulation investments.
Aerospace leads on scale; healthcare leads on momentum.
Application:
Production maturity stage dictates software module bundling and subscription tier selection.
- Prototyping:Early-stage design validation emphasizes geometric fidelity checking and rapid iteration loops without production-grade material qualification requirements.
- Tooling:Jig, fixture, and mold insert manufacturing bridges prototype and production workflows, with automotive stamping die applications driving specialized CAM configurations.
- Production:Serial additive manufacturing demands closed-loop feedback between build monitoring and parameter adjustment, particularly for aerospace flight hardware qualification.
- Post-Processing:Support removal, surface finishing, and heat treatment planning modules gain traction as buyers recognize downstream quality impacts on final part performance.
Prototyping leads on scale; production leads on momentum.
Technology:
Deposition mechanism determines software specialization in thermal modeling, support generation, and material database architecture.
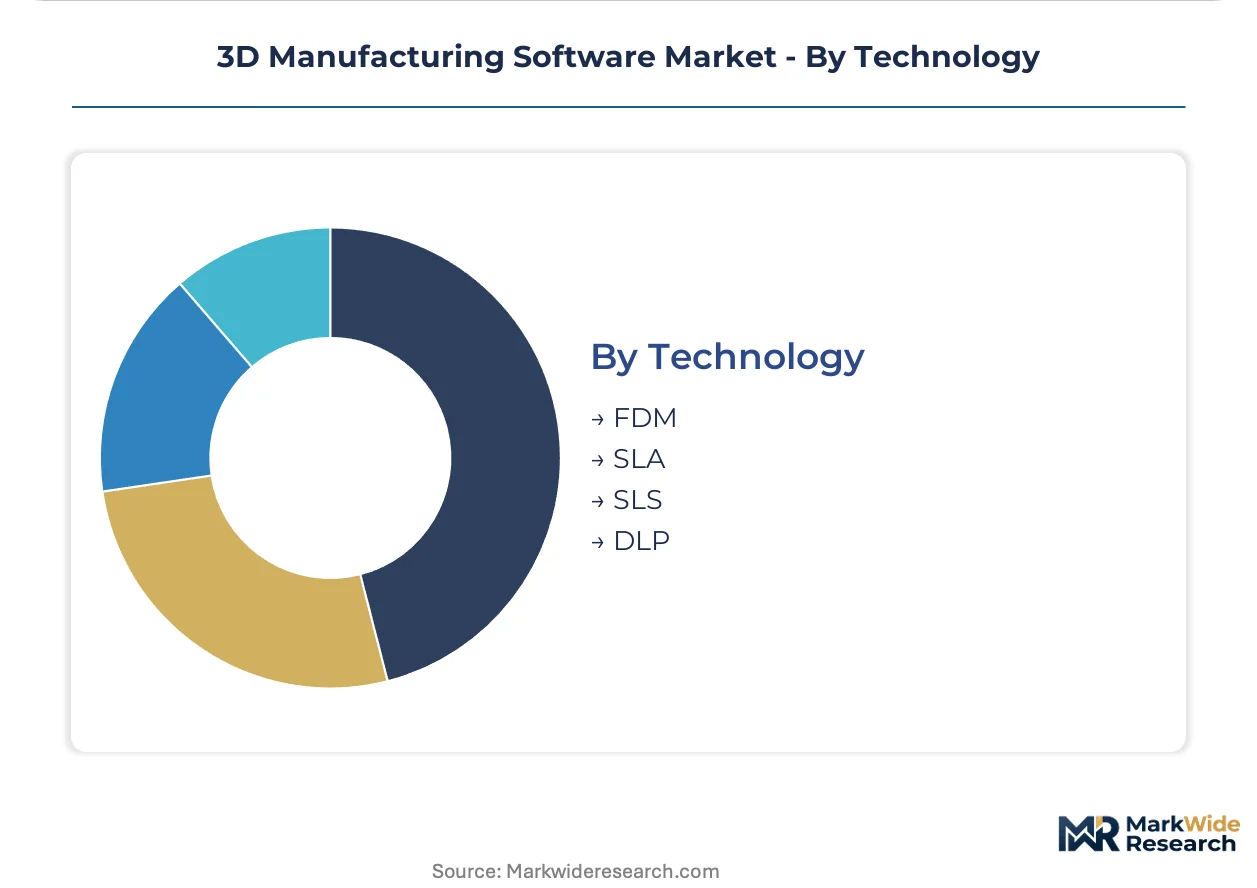
- FDM:Fused deposition modeling dominates desktop and industrial polymer printing through accessible material extrusion workflows, with slicing algorithms optimizing for support minimization and layer adhesion.
- SLA:Stereolithography resin curing requires precise exposure time calculations and vat-level monitoring, with dental and jewelry applications driving high-resolution build preparation tools.
- SLS:Selective laser sintering of polymer powders enables support-free geometries but demands sophisticated thermal management to prevent part warping and powder degradation.
- DLP:Digital light projection accelerates resin printing through masked exposure patterns, with hearing aid and dental aligner manufacturing favoring its throughput advantages.
FDM leads on scale; SLS leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial software corridor generates deeper platform integration than China's dispersed additive manufacturing base, where standardization lags behind concentrated European engineering ecosystems.
United States
Aerospace tier-one suppliers in Seattle and Los Angeles compress design-to-production cycles through integrated simulation suites. FAA airworthiness standards impose rigorous software validation protocols on flight-critical component qualification. The Pacific Northwest aerospace cluster anchors demand for thermal modeling and geometric fidelity tools.
Germany
Automotive OEMs in Stuttgart and Munich maintain deep PLM integration with legacy systems while resisting cloud-native platform migration. The EU AI Act compliance mandates validate algorithmic decision-making in production software, pulling certified simulation suites into industrial workflows. Bavaria's engineering talent concentration accelerates co-development partnerships between OEMs and platform vendors.
China
Domestic printer hardware manufacturers drive post-processor customization demand across polymer and metal deposition systems. MIIT standardization initiatives for additive manufacturing software interfaces remain fragmented across provincial industrial zones. The Yangtze River Delta manufacturing belt generates tooling and prototyping applications prioritizing speed over qualification depth.
India
The PLI scheme for medical devices creates first-mover advantage for software vendors establishing localized validation support. CDSCO regulatory frameworks for patient-specific implants extend documentation burdens comparable to FDA timelines. Karnataka's medical device manufacturing corridor in Bangalore attracts simulation platform investments for surgical guide production.
France
Aerospace supply chains around Toulouse integrate digital thread platforms to trace design changes through final part qualification. EASA certification requirements align with FAA protocols on software validation for flight hardware. The Occitanie aerospace cluster demands closed-loop feedback between build monitoring and parameter adjustment for titanium lattice structures.
3D Manufacturing Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with perpetual license vendors defending entrenched automotive workflows while subscription-native platforms capture aerospace and healthcare expansion. The vendor base concentrates around three tiers: legacy PLM-integrated suites, cloud-native simulation specialists, and hardware-coupled CAM providers. Two strategic moves dominate competitive positioning: deep integration into digital thread architectures and consumption-based pricing models that convert capital expenditure to recurring operational budgets.
Within the legacy PLM-integrated tier, Dassault Systèmes and Siemens occupy positions anchoring industrial-grade digital thread capabilities through entrenched automotive and aerospace relationships. Autodesk exemplifies the cloud-native archetype with multi-tenant deployment across dispersed engineering teams. PTC represents the closed-loop specialization vector, linking generative design algorithms to shop-floor execution monitoring.
| Leading Market Players |
|---|
| Dassault Systèmes |
| Autodesk |
| PTC |
| Siemens |
| Hexagon |
| Materialise |
| Robert McNeel & Associates |
| Maxon Computer |
| UnionTech |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up simulation specialists anchor supply-side consolidation in 3D manufacturing software, tightening pricing discipline as recurring revenue models displace perpetual licensing. Their capital structures favor subscription-based monetization that smooths cash flows while concentrating platform control among fewer scaled vendors.
Pricing Analysis
Capacity additions in Germany's industrial software corridor are reshaping price floors for enterprise simulation suites. Three-tier pricing structure across premium, standard, and economy levels segments buyers by validation depth and regulatory exposure. Price differentiation centers on FDA and EU MDR certification tiers, with healthcare-oriented platforms commanding substantial premiums over prototyping tools. Pricing pressure stems from open-source slicing alternatives commoditizing entry-level deposition planning. Consumer electronics manufacturers exhibit highest price sensitivity, while aerospace tier-one suppliers prioritize thermal fidelity over cost.
Supply Chain Analysis
Dual-sourcing requirements for cloud compute infrastructure mandate multi-supplier qualification among AWS, Microsoft Azure, and Google Cloud Platform for thermal simulation workloads. Software development concentrates in Germany, the United States, and India, with Bangalore's engineering talent feeding validation support for medical device applications. Raw material dependencies center on GPU silicon from Taiwan, specialized solver libraries from academic institutions, and material qualification databases maintained by European chemical registrars. Supply chain risk crystallizes around single-source vulnerability in high-performance GPU provisioning for multiphysics workloads. Distribution runs through direct enterprise sales teams and specialized additive manufacturing channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
3D Manufacturing Software operates as a late-cycle quality story as aerospace and healthcare buyers shift demand toward FDA-validated, EU MDR-certified platforms that compress design-to-production risk.
For Market Incumbents: Lock in aerospace tier-one relationships through embedded digital thread architectures that trace design changes through FAA airworthiness qualification. Deepen solver integration with legacy PLM systems to raise switching costs for German automotive OEMs. Threaten open-source alternatives by bundling consumption-based simulation credits with core subscriptions. Vertical integration into GPU-reserved instances secures margin control against cloud pricing volatility. For New Entrants and Emerging Players: Enter via India's PLI scheme for medical devices, where localized CDSCO validation support remains underdeveloped relative to demand growth. Target surgical guide manufacturing in Karnataka's medical device corridor as the most penetrable healthcare segment. Pursue co-development partnerships with domestic printer hardware manufacturers to bypass post-processor customization barriers. Cloud-native deployment architectures lower capital barriers against entrenched on-premise competitors. For Investors and Strategic Acquirers: Valuations sit cheapest among closed-loop feedback specialists linking generative design to shop-floor execution monitoring. Long-term viability favors platforms with demonstrated FDA software-as-a-medical-device clearance pathways. Acquisition target archetype: simulation vendors with titanium lattice topology optimization modules and existing EASA certification relationships. Watch for inflection in EU Green Deal carbon-accounting mandate timing that would force emissions tracking module adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CAD, PLM, and shop-floor data for aerospace digital thread compliance with FAA standards. |
| Regulatory Certification Investment | Accelerates FDA software-as-a-medical-device pathways for patient-specific implant manufacturing platforms. |
| Geographic Expansion | Establishes localized validation support in India's PLI scheme corridors for medical device software. |
| Strategic Partnership | Links generative design algorithms to real-time build monitoring for closed-loop titanium lattice production. |
| Acquisition of Specialist Firm | Consolidates multiphysics thermal-structural-fluid dynamics expertise scarce in current training pipelines. |
Research Methodology
Bottom-up aerospace and healthcare procurement modeling reconciled against top-down cloud-native deployment tracking forms the analytical core of this study. Primary interviews with CTOs at tier-one aerospace suppliers, biomedical engineers in hospital purchasing committees, platform engineers at additive hardware OEMs, and regulatory affairs leads at medical device manufacturers combined with secondary validation. Secondary sources encompass SEC filings from publicly traded software vendors, EMA and FDA submission databases for software-as-a-medical-device clearances, hyperscaler capex disclosures for GPU infrastructure scaling, and customs records for additive manufacturing equipment imports. Triangulation between bottom-up end-use demand signals and top-down vendor revenue segmentation ensures consistency across market sizing.
Input-output matrices map deployment model, organization size, vertical application, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derive from modeled segment growth rates weighted by current revenue footprints and forward-looking procurement intention surveys. Industry-specific forecast inputs include aerospace build rate projections from Toulouse and Seattle supply chains, and EU AI Act implementation timelines affecting algorithmic validation requirements. Segmentation dimensions capture product type, end user regulatory exposure, production maturity stage, and deposition technology specialization.
Inputs from EMA submission databases and hyperscaler infrastructure disclosures were available through the study window; gaps in real-time cloud compute pricing transparency introduce uncertainty bands around margin projections for mid-tier simulation vendors. Forecasts reflect documented assumptions regarding EU MDR enforcement consistency and FAA software validation protocol stability. Deviation in EU Green Deal carbon-accounting mandate timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
4D Printing Market
3D Printing Technology
3D Printing Enabled Augmented Manufacturing Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
Global 4D Printing in Healthcare Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
Metal 3D Printing Service Market
3D Printing Technology
Binder Jet Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
PEEK Filament Market
3D Printing Technology
3D Printing Robots Market