
 United Kingdom 3D Printing Market | 2026-2036
United Kingdom 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom 3D Printing Market Analytics
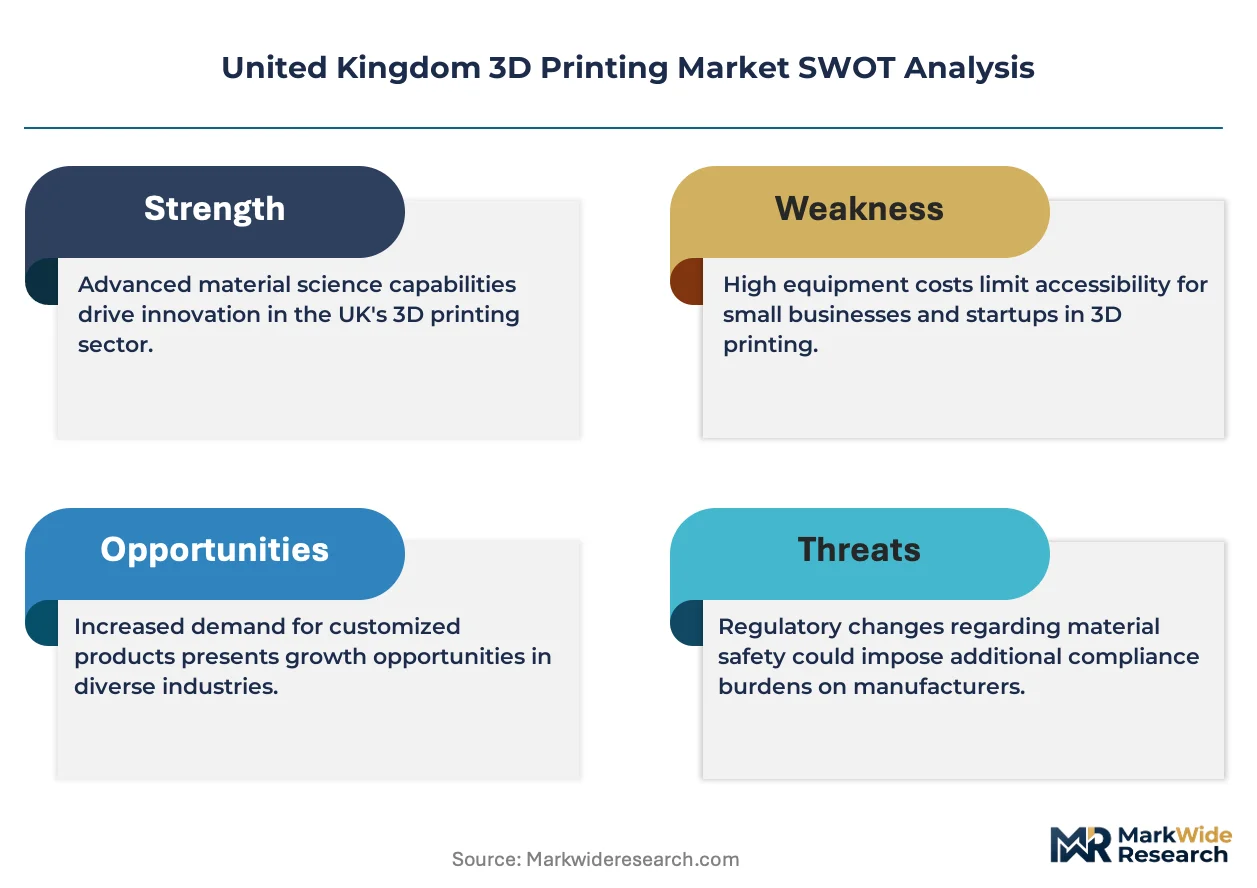
CE marking under the EU Medical Device Regulation is decoupling compliance costs from pure hardware economics for UK-based medical 3D printing entrants. Renishaw PLC anchors metal powder bed fusion capabilities across dental and aerospace verticals. Stratasys Limited leverages polymer expertise to sustain installed-base loyalty among design engineers. Wayland Additive specializes in electron beam systems for high-value alloy processing.
United Kingdom 3D Printing encompasses additive manufacturing systems that build objects layer-by-layer from digital models using thermoplastics, photopolymers, or metal powders fused by laser, electron beam, or extrusion processes at resolutions from 25 to 100 microns. The technology serves industrial prototyping, production tooling, and end-use part fabrication across sectors requiring geometric complexity or lot-size flexibility. Industrial Printers capture the dominant margin pool as aerospace and medical OEMs qualify multi-laser metal systems for flight-critical and implantable applications. Healthcare within the Application dimension shows the steepest trajectory as patient-specific surgical guides and orthopedic implants gain National Health Service procurement traction. FDM retains volume leadership in educational and prototyping settings though SLS and SLA command premium pricing in functional end-use production.
The Medicines and Healthcare products Regulatory Agency shapes clinical adoption pathways for printed medical devices while the Health and Safety Executive governs powder handling and emissions in production facilities. British Standards Institution certification requirements for metal additive manufacturing processes influence supplier qualification timelines for defense and nuclear supply chains. Stakeholders must monitor divergence between retained EU technical standards and emerging UK-specific conformity assessment routes post-Brexit.
Market Dynamics
Metal powder bed fusion is compressing qualification timelines for flight-critical aerospace components, while NHS procurement frameworks accelerate patient-specific implant adoption across UK hospital trusts.
Growth Catalysts
- Advanced Manufacturing Plan:UK government capital allowances for domestic production equipment are lowering effective capex thresholds for SME tier-one suppliers.
- Midlands engineering cluster:Concentrated aerospace supply chains enable shared qualification data and pooled technician training across adjacent facilities.
- Electron beam processing:High-value alloy capabilities unlock reactive metal applications previously excluded from laser-based workflows.
Market Restraints
- Titanium powder supply:Spherical plasma-atomized feedstock concentrates among three global suppliers, exposing UK processors to spot-price volatility.
- CE marking divergence:Retained EU MDR compliance costs now layer against emerging UKCA routes, doubling certification burden for dual-market medical entrants.
- Build-rate limitations:Single-laser systems face displacement pressure from multi-laser architectures, stranding installed-base depreciation schedules.
Strategic Opportunities
- Greater Manchester materials ecosystem:Graphene-enhanced polymer feedstock development opens lightweight structural applications beyond current metal dominance.
- Net-zero construction mandates:BSI standards for printed concrete structural elements align with UK building regulations tightening embodied carbon thresholds.
- Digital inventory models:Spare part on-demand printing eliminates physical warehousing for legacy defense and nuclear plant equipment.
Industry Challenges
- Multi-laser technician scarcity:Optical alignment and in-process monitoring expertise lags hardware deployment across Midlands production facilities.
- Nuclear supply chain qualification:BSI additive manufacturing certification timelines extend 18-24 months, delaying revenue recognition for defense contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom 3D Printing Market |
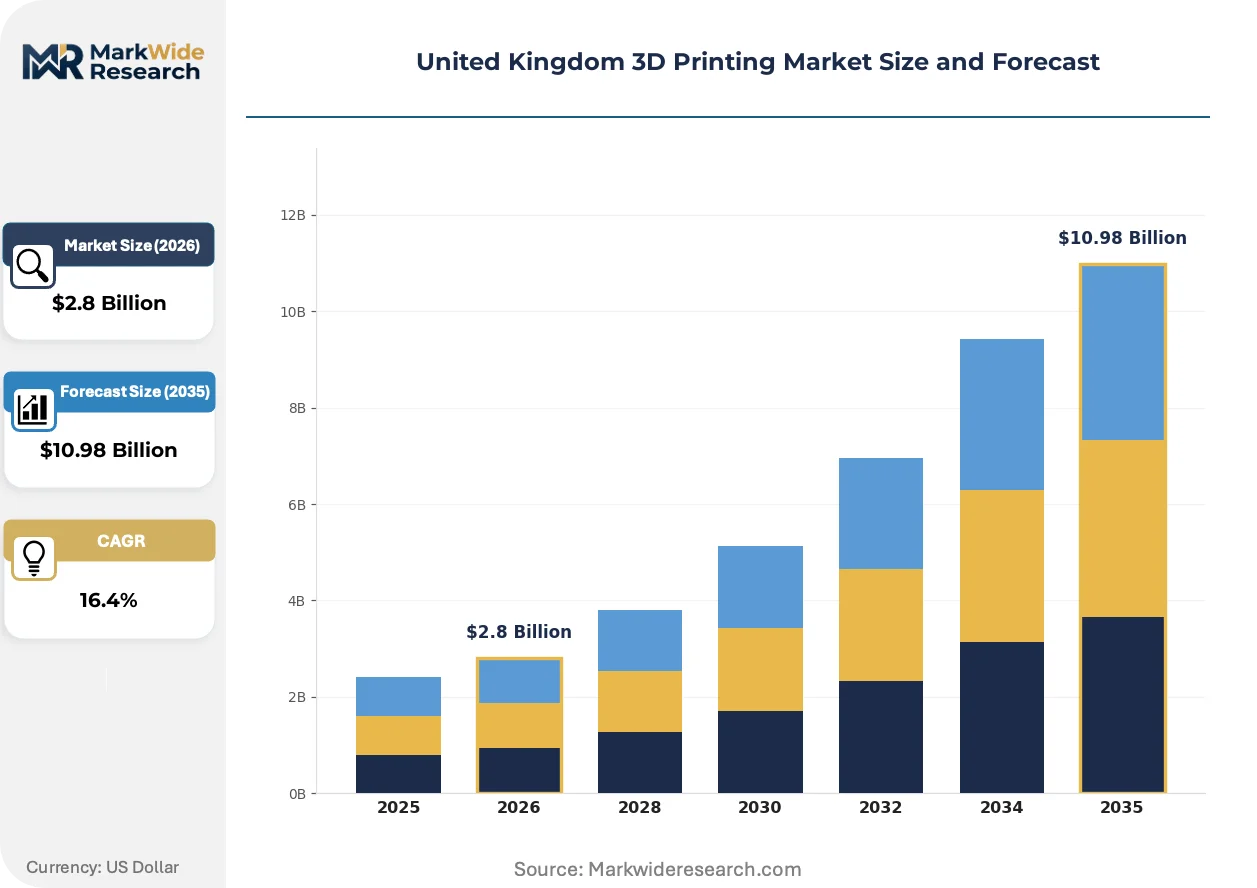
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Printers, Commercial Printers, Desktop Printers, Materials Application: Aerospace, Automotive, Healthcare, Consumer Goods Technology: FDM, SLA, SLS, DLP End User: Manufacturers, Designers, Engineers, Educational Institutions |
| Companies Covered | Materialise NV, Nexa 3D Inc., Renishaw PLC, HP Development Company LP, Protolabs, Stratasys Limited, AnisoPrint, Wayland Additive, EOS GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom 3D Printing Market Evolving Landscape
Process monitoring automation and feedstock traceability systems are compressing the gap between prototype qualification and production scale across UK industrial sites.
Multi-laser metal powder bed fusion is overtaking single-laser architectures in aerospace engine component production. Rolls-Royce and BAE Systems suppliers are qualifying four-laser systems for turbine blade repair workflows. This shift is compressing per-part processing economics below subtractive machining thresholds for lot sizes under fifty units.
UKCA marking divergence from retained EU MDR frameworks is fragmenting conformity assessment routes for implantable medical devices. The Medicines and Healthcare products Regulatory Agency is establishing parallel clinical evidence requirements for patient-specific orthopedic hardware. Dental and cranio-maxillofacial segments face the steepest compliance cost escalation as dual-certification becomes mandatory for EU market access.
Hospital trust procurement is consolidating supplier panels around ISO 13485-certified production facilities with embedded design engineering capabilities. Traditional distributor relationships are thinning as NHS Supply Chain mandates direct manufacturer qualification for Class III implantables. Orthopedic and maxillofacial surgical units in Greater Manchester and Birmingham hospital clusters are driving this specification tightening.
United Kingdom 3D Printing Market Segmentation
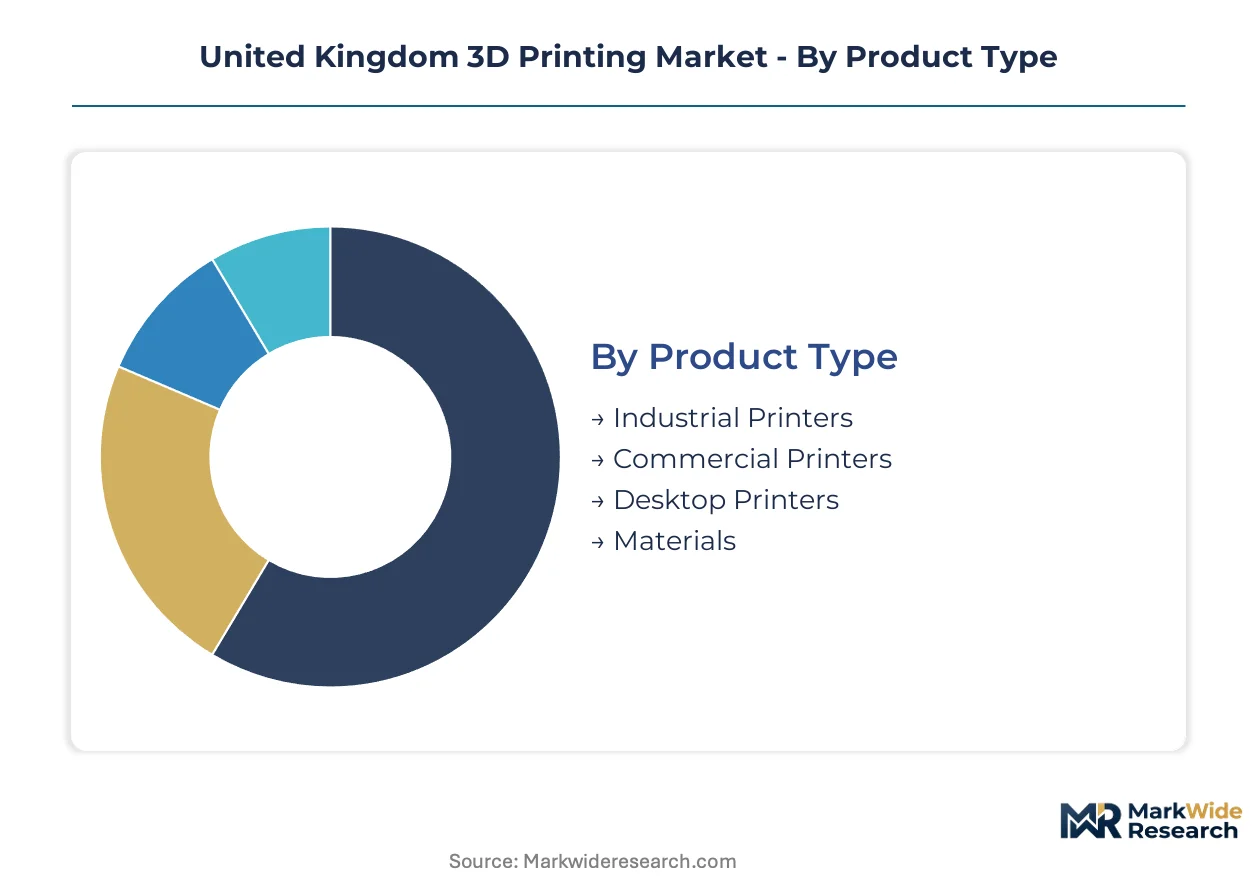
Segmentation reveals how UK 3D printing demand fragments across equipment scale, regulatory burden, and end-use qualification requirements. Each category maps distinct certification pathways and margin structures that determine supplier viability.
Product Type:
Certification burden intensifies with equipment scale: industrial systems require BSI additive manufacturing process certification for defense and nuclear supply chains, while desktop units face minimal conformity assessment.
- Industrial Printers:Multi-laser metal powder bed fusion systems dominate aerospace engine component production. Midlands engineering cluster demand concentrates around four-laser architectures qualifying for Rolls-Royce and BAE Systems supplier networks, with NHS Supply Chain mandating direct manufacturer qualification for Class III implantables.
- Materials:Spherical plasma-atomized titanium feedstock concentrates among three global suppliers, exposing UK processors to spot-price volatility. Graphene-enhanced polymer development in Greater Manchester opens lightweight structural applications beyond current metal dominance.
- Commercial Printers:Mid-scale systems serve prototyping and short-run production for SME tier-one suppliers benefiting from Advanced Manufacturing Plan capital allowances.
- Desktop Printers:FDM systems retain volume leadership in educational settings and design engineering workflows, with Stratasys sustaining installed-base loyalty through polymer expertise.
Leading the category by volume: Desktop Printers. Growing fastest: Industrial Printers.
Application:
End-use qualification timelines stretch from months for consumer goods to years for flight-critical aerospace and implantable medical devices.
- Healthcare:Patient-specific surgical guides and orthopedic implants gain National Health Service procurement traction. Hospital trust consolidation around ISO 13485-certified facilities with embedded design engineering capabilities is thinning traditional distributor relationships.
- Aerospace:Metal additive manufacturing scales for engine components as multi-laser systems compress per-part economics below subtractive machining thresholds for lot sizes under fifty units.
- Automotive:Production tooling and end-use part fabrication leverage geometric complexity for electric vehicle thermal management and lightweight structural components.
- Consumer Goods:Design prototyping and limited customization applications face margin pressure from mass production alternatives.
Highest certification barrier: Healthcare. Steepest volume expansion: Aerospace.
Technology:
Resolution and material compatibility determine segment positioning across functional prototyping versus end-use production.
- FDM:Thermoplastic extrusion at 100-micron resolution dominates educational and prototyping settings through equipment accessibility and material cost efficiency.
- SLS:Selective laser sintering of polymer powders commands premium pricing in functional end-use production for automotive and consumer goods applications.
- SLA:Stereolithography's photopolymer precision serves dental and medical modeling where surface finish requirements exceed FDM capabilities.
- DLP:Digital light processing accelerates photopolymer throughput for orthodontic and jewelry applications requiring speed over build envelope scale.
Widest installed base: FDM. Premium pricing capture: SLS.
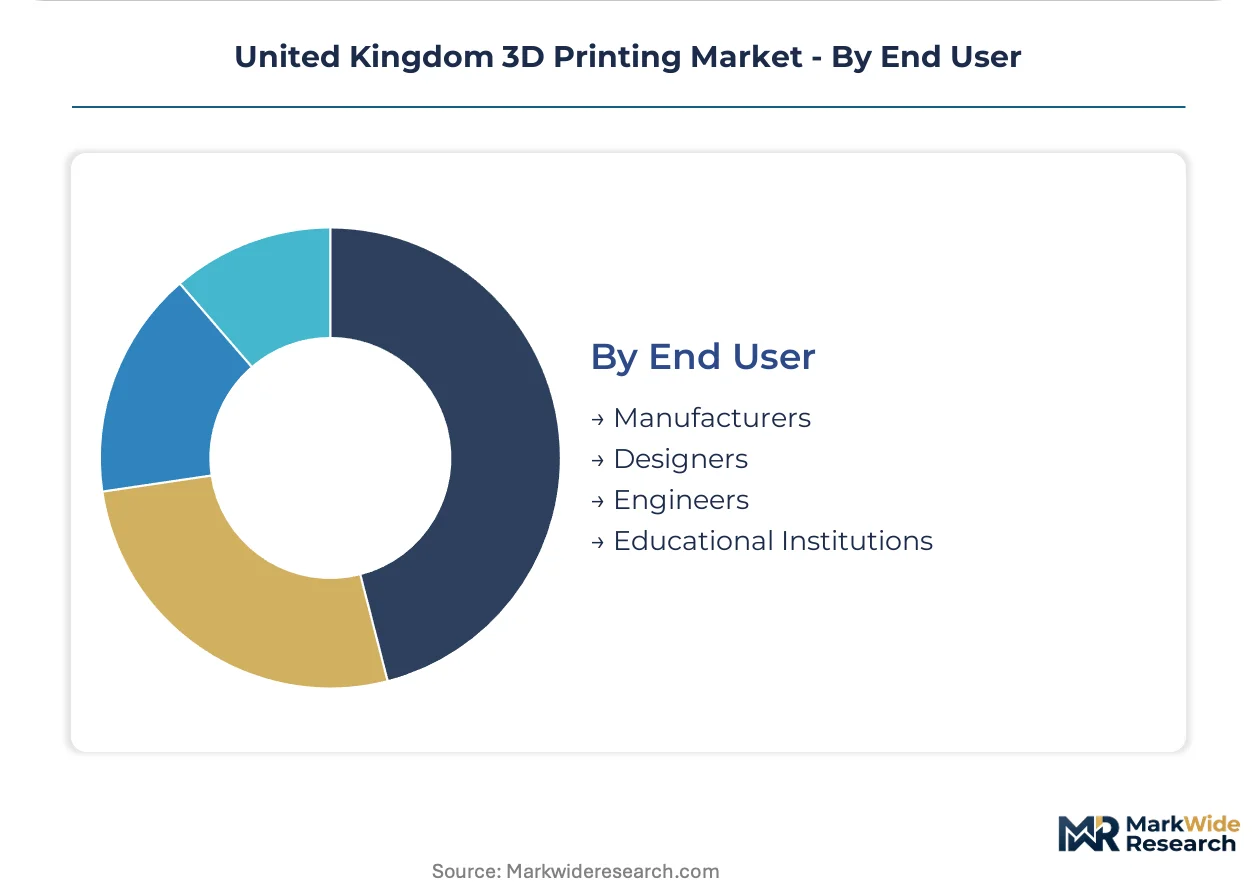
End User:
Technical sophistication and procurement authority separate production-scale adopters from experimental users.
- Manufacturers:Production-scale adopters qualify multi-laser metal systems for flight-critical and implantable applications, with BSI certification timelines extending eighteen to twenty-four months for nuclear supply chains.
- Engineers:Design-for-additive expertise concentrates in Midlands and Greater Manchester clusters where shared qualification data and pooled technician training reduce barrier-to-entry.
- Designers:Polymer system users sustain Stratasys installed-base loyalty through workflow integration and material portfolio breadth.
- Educational Institutions:FDM volume leadership reflects curriculum integration and equipment capital constraints relative to industrial metal systems.
Primary revenue source: Manufacturers. Fastest skill development: Engineers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midlands Enterprise Zone tax incentives concentrate aerospace supply chain investment across Coventry, Birmingham, and Derby. Greater Manchester's advanced materials ecosystem anchors graphene-polymer feedstock development. The Advanced Manufacturing Plan capital allowances accelerate SME equipment deployment nationwide.
Midlands
Rolls-Royce turbine blade repair workflows drive multi-laser metal system qualification. The Health and Safety Executive governs powder handling emissions across Derby and Coventry production facilities. Birmingham's hospital clusters consolidate ISO 13485-certified supplier panels for NHS orthopedic implant procurement.
Greater Manchester
Graphene-enhanced polymer R&D unlocks lightweight structural applications beyond metal dominance. The Medicines and Healthcare products Regulatory Agency establishes parallel UKCA clinical evidence requirements for patient-specific devices. Trafford and Salford advanced materials hubs pool technician training across shared qualification datasets.
Scotland
BAE Systems suppliers qualify four-laser architectures for defense component production. British Standards Institution certification timelines extend eighteen to twenty-four months for nuclear supply chain entry. Glasgow and Edinburgh engineering clusters face technician scarcity in optical alignment expertise.
South East England
Renishaw PLC anchors metal powder bed fusion capabilities across dental and aerospace verticals. CE marking divergence from retained EU MDR layers dual certification costs for medical device entrants. Oxfordshire and Buckinghamshire precision engineering corridors concentrate electron beam system development for reactive metal processing.
Wales
Net-zero construction mandates drive printed concrete structural element qualification. BSI standards alignment with tightening embodied carbon thresholds in UK building regulations accelerates adoption. Cardiff and Newport manufacturing zones experiment with on-demand spare part printing for legacy infrastructure.
United Kingdom 3D Printing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment, materials, and service provision tiers. The vendor base stratifies into industrial system manufacturers, feedstock specialists, and design-engineering service bureaus. Three archetypes dominate: multi-technology platform providers, single-technology depth specialists, and vertical-integrated production service operators. Competitive moves center on multi-laser system portfolio expansion and NHS Supply Chain direct qualification pathways.
Among UK-anchored specialists, Renishaw PLC and Wayland Additive occupy positions within the metal system architecture tier, while Stratasys Limited exemplifies polymer platform breadth. Materialise NV represents the design-engineering service bureau archetype bridging software-to-production workflows. EOS GmbH anchors European-origin powder bed fusion technology supply. These named entities illustrate how geographic clustering in the Midlands and Greater Manchester correlates with capability concentration across electron beam, laser fusion, and polymer extrusion modalities.
| Leading Market Players |
|---|
| Materialise NV |
| Nexa 3D Inc. |
| Renishaw PLC |
| HP Development Company LP |
| Protolabs |
| Stratasys Limited |
| AnisoPrint |
| Wayland Additive |
| EOS GmbH |
| Others |
Value Network & Pricing Analysis
Multi-laser metal powder bed fusion deployment across Midlands aerospace facilities is simultaneously compressing per-part cost economics below subtractive machining thresholds and concentrating procurement leverage among four-laser system operators qualifying for Rolls-Royce supplier networks.
Pricing Analysis
Lead-time-driven pricing stratification separates NHS Supply Chain direct-qualification premiums from spot-market titanium powder volatility. Three-tier pricing structure across certified production, qualified prototyping, and educational desktop tiers reflects BSI additive manufacturing certification grade and embedded design engineering capabilities. Cost compression in mid-scale commercial systems intensifies as single-laser depreciation schedules face displacement pressure. SME tier-one suppliers benefiting from Advanced Manufacturing Plan capital allowances exhibit highest price sensitivity, while defense contractors absorbing eighteen-to-twenty-four-month nuclear qualification timelines show lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for spherical plasma-atomized titanium feedstock mandate qualification across three global suppliers concentrated in the United States, Germany, and China. UK processors draw from this concentrated upstream for reactive metal applications in electron beam systems, with graphene-enhanced polymer R&D anchoring alternative feedstock development in Greater Manchester. Single-source vulnerability concentrates in plasma-atomized spherical powder production, exposing spot-price volatility. Distribution runs through direct manufacturer relationships consolidating around ISO 13485-certified facilities with embedded hospital trust procurement pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom 3D printing market functions as a vertical-integration race where control over spherical powder atomization capacity and embedded NHS design engineering capabilities determines margin capture across aerospace and medical verticals.
For Market Incumbents: Deepen backward integration into spherical titanium powder production to offset feedstock spot-price volatility threatening multi-laser system economics. Anchor installed-base loyalty through embedded technician training pools addressing optical alignment scarcity across Midlands production facilities. Defend against electron beam system displacement by accelerating four-laser architecture qualification for BAE Systems defense networks. For New Entrants and Emerging Players: Graphene-enhanced polymer feedstock development represents the most penetrable wedge for lightweight structural applications beyond current metal dominance in Greater Manchester. Target net-zero construction mandates driving printed concrete structural element qualification under tightening BSI embodied carbon thresholds. Pursue direct NHS Supply Chain qualification pathways for Class III implantables as hospital trust procurement consolidates around ISO 13485-certified production facilities. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap specialists with captive electron beam or multi-laser metal system capabilities and embedded hospital trust relationships. Long-term viability over the next decade hinges on UKCA marking divergence resolution and retained EU MDR dual-certification cost absorption. Watch for inflection in BSI additive manufacturing certification timeline compression for nuclear supply chain entry as the signal for defense contractor revenue recognition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Laser System Qualification | Four-laser architectures compress per-part economics below subtractive machining for Rolls-Royce turbine blade repair workflows. |
| Backward Integration into Powder Atomization | Captive spherical titanium feedstock production insulates UK processors from three-supplier concentration risk. |
| NHS Direct Qualification Pathway | ISO 13485-certified facilities with embedded design engineering capture hospital trust procurement consolidation. |
| Graphene-Polymer Feedstock Development | Greater Manchester materials ecosystem unlocks lightweight structural applications beyond current metal dominance. |
| UKCA Marking Parallel Certification | MHRA clinical evidence requirements for patient-specific devices address dual-market medical entrant compliance burden. |
Research Methodology
Document review covered BSI additive manufacturing certification standards, MHRA medical device registration databases, and NHS Supply Chain procurement frameworks, complemented by interviews with aerospace procurement directors at Rolls-Royce and BAE Systems tier-one suppliers, biomedical engineers at Greater Manchester hospital trusts, and powder metallurgy specialists at Midlands production facilities. Secondary validation drew from Health and Safety Executive emissions filings, Advanced Manufacturing Plan capital allowance utilization records, and retained EU MDR technical documentation. Bottom-up equipment deployment tallies triangulated against top-down sectoral investment flow analysis.
Segmented volume and value trajectories emerged from modeling across product type, application, technology, and end-user dimensions, with additional stratification by regional cluster concentration and certification pathway complexity. CAGRs derived from regression against capital equipment shipment data and feedstock consumption patterns. Key inputs included multi-laser system qualification timelines for flight-critical aerospace components and patient-specific implant adoption rates across NHS hospital trust procurement panels.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated UKCA-MDR divergence or titanium powder supply disruption scenarios. Projections reflect assumptions regarding BSI certification timeline stability and Advanced Manufacturing Plan allowance continuity. A model refresh is warranted upon material change in MHRA clinical evidence requirements or Health and Safety Executive powder handling emissions enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
Digital 3D Printing Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
Additive Manufacturing Software Market
3D Printing Technology
Online 3D Printing Service Market
3D Printing Technology
Military 3D and 4D Printing Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
Food 3D Printing Market
3D Printing Technology
Europe Industrial 3D Printing Market
3D Printing Technology
Metal 3D Printing Service Market
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
Desktop 3D Printing Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
North America Industrial 3D Printing Market