
 Model Based Testing Tools Market | 2026-2036
Model Based Testing Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Model Based Testing Tools Market Foresight
Enterprise compliance teams are bifurcating from traditional QA departments as the primary procurement authority for model-based testing platforms. Tricentis leverages its channel control across European automotive hubs to sustain enterprise relationships. IBM Corporation anchors its position through deep integration with legacy systems engineering workflows. Microsoft Corporation competes by embedding testing capabilities within its cloud-native development ecosystems.
Model based testing tools generate executable test cases from formal system models using state machines, decision tables, and UML diagrams to verify software behavior before code deployment. These platforms automate traceability between requirements and test outcomes, reducing defect escape rates in safety-critical applications. Commercial tools command premium pricing due to certified compliance modules for ISO 26262 and DO-178C, while open source tools attract mid-tier software developers prioritizing customization over certification. Cloud-based deployment is expanding fastest among IT departments managing distributed agile teams, though on-premises installations retain dominance in defense and aerospace sectors where data sovereignty requirements are strict.
FDA software validation guidelines for medical devices, EMA's computerized system assurance framework, and ISO 26262 automotive functional safety standards collectively mandate traceable verification methodologies that model-based testing directly addresses. NHTSA's emerging software-defined vehicle guidance in the United States is accelerating OEM procurement of certified toolchains. Stakeholders must evaluate whether their current tool investments align with impending harmonization between EU AI Act risk classification and existing safety-critical software standards.
Market Dynamics
ISO 26262 functional safety mandates in Europe and North America are compelling automotive OEMs to replace manual verification workflows with automated model-based testing platforms, restructuring procurement authority toward enterprise compliance teams.
Growth Catalysts
- ISO 26262 Mandates:European and North American automotive safety regulations now require traceable verification methodologies that only certified model-based testing platforms deliver, forcing tool upgrades across Tier-1 suppliers.
- Autonomous Driving Complexity:Self-driving system validation demands exhaustive scenario coverage that manual testing cannot achieve, pulling investment toward state-machine-based test generation.
- Germany:The country's automotive software engineering concentration creates concentrated demand for certified toolchains as domestic OEMs expand model-based verification for ADAS platforms.
Market Restraints
- Certified Module Premiums:ISO 26262 and DO-178C compliance modules command substantial price premiums over baseline offerings, compressing accessibility for mid-tier developers.
- Defense Sector Lock-in:Aerospace and defense procurement cycles favor entrenched incumbents with existing airworthiness certifications, creating high barriers for new platform entrants.
- Open Source Substitution:Uncertified open-source frameworks attract cost-sensitive software teams willing to sacrifice compliance documentation for customization flexibility.
Strategic Opportunities
- Cloud-Native Deployment:Distributed agile teams across IT departments are rapidly adopting SaaS-based testing platforms, displacing traditional on-premises installations in non-regulated sectors.
- NHTSA Software-Defined Vehicle Guidance:Emerging federal guidance in the United States is accelerating OEM procurement of certified toolchains ahead of formal rulemaking.
- EU AI Act Harmonization:Risk classification frameworks for AI-enabled automotive systems will require verification methodologies that model-based testing directly addresses, creating new compliance-driven demand.
Industry Challenges
- Formal Methods Expertise Scarcity:State machine modeling and UML diagram proficiency remains concentrated among specialized systems engineers, constraining platform adoption rates.
- Legacy Workflow Integration:Enterprises with decades-old systems engineering infrastructure face substantial reconfiguration costs when embedding model-based testing into existing DevOps pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Model Based Testing Tools Market |
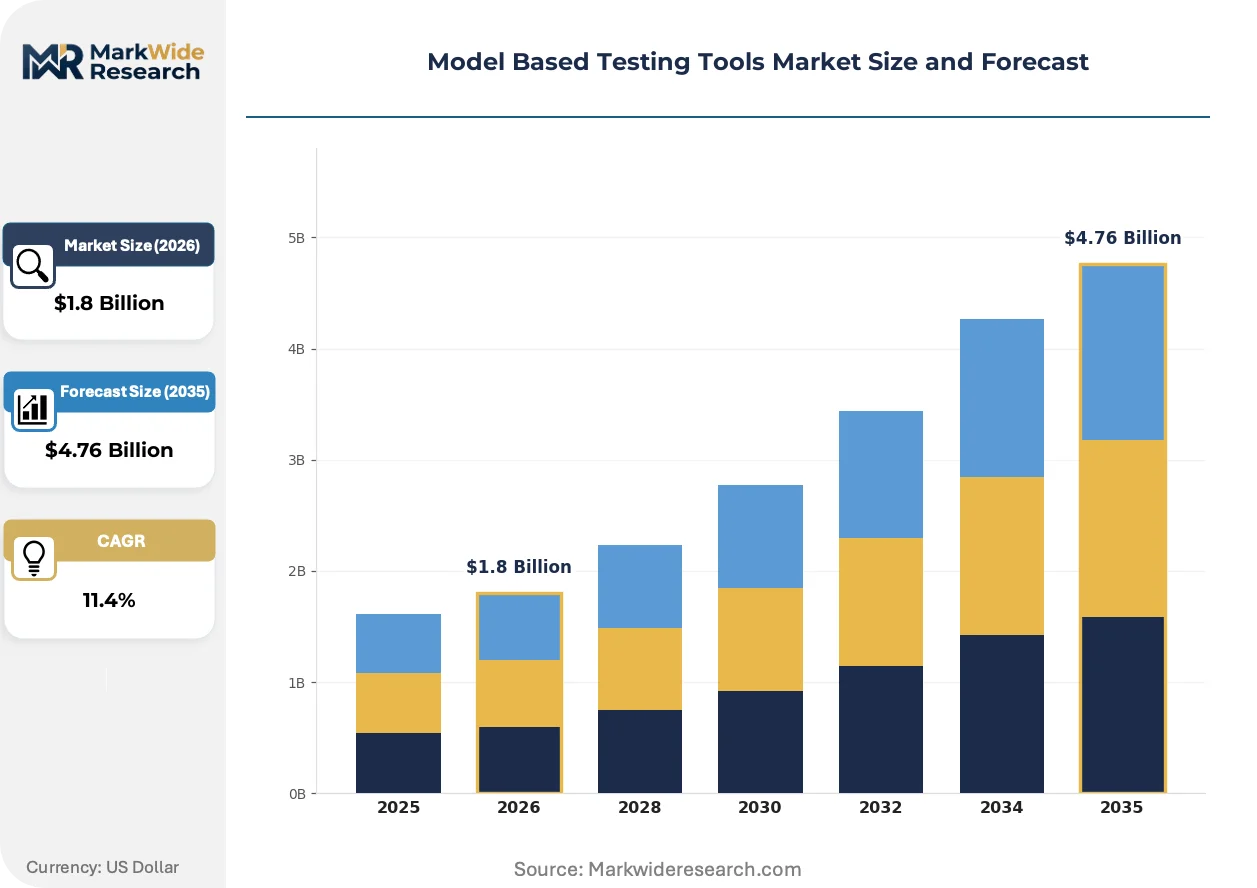
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Tools, Open Source Tools, Custom Solutions, Hybrid Solutions Technology: Static Analysis, Test Automation, Performance Testing, Continuous Integration End User: Software Developers, QA Engineers, IT Departments, Compliance Teams Deployment: On-Premises, Cloud-Based, Hybrid, SaaS |
| Companies Covered | Teveron, Testing Technologies IST GmbH, Tricentis, MBTsuite, GraphWalker, Testoptimal, Oracle, Microsoft Corporation, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Model Based Testing Tools Market Shifts & Advancements
Artificial intelligence is actively reshaping how test cases are generated from formal models, compressing the gap between specification and executable verification while forcing incumbents to rearchitect their core engines.
Neuro-symbolic test generation is displacing traditional state-space exploration methods in safety-critical applications. Automotive OEMs in Germany and Japan are deploying these hybrid engines for autonomous driving verification. The technology is displacing rule-based test prioritization by learning failure patterns from historical defect databases.
The EU AI Act's risk classification framework for high-risk AI systems is mandating traceable verification documentation that model-based testing platforms uniquely provide. Automotive suppliers must now demonstrate formal verification coverage for AI-enabled perception systems. European OEMs are responding by procuring certified toolchains with built-in audit trails before the Act's full enforcement timeline.
Enterprise buyers are consolidating testing procurement under central compliance functions rather than distributed QA departments. Automotive and medical device manufacturers are replacing departmental tool selection with enterprise-wide platform mandates. This concentration is most visible in Germany and the United States where functional safety liability exposure drives standardization.
Model Based Testing Tools Market Segmentation
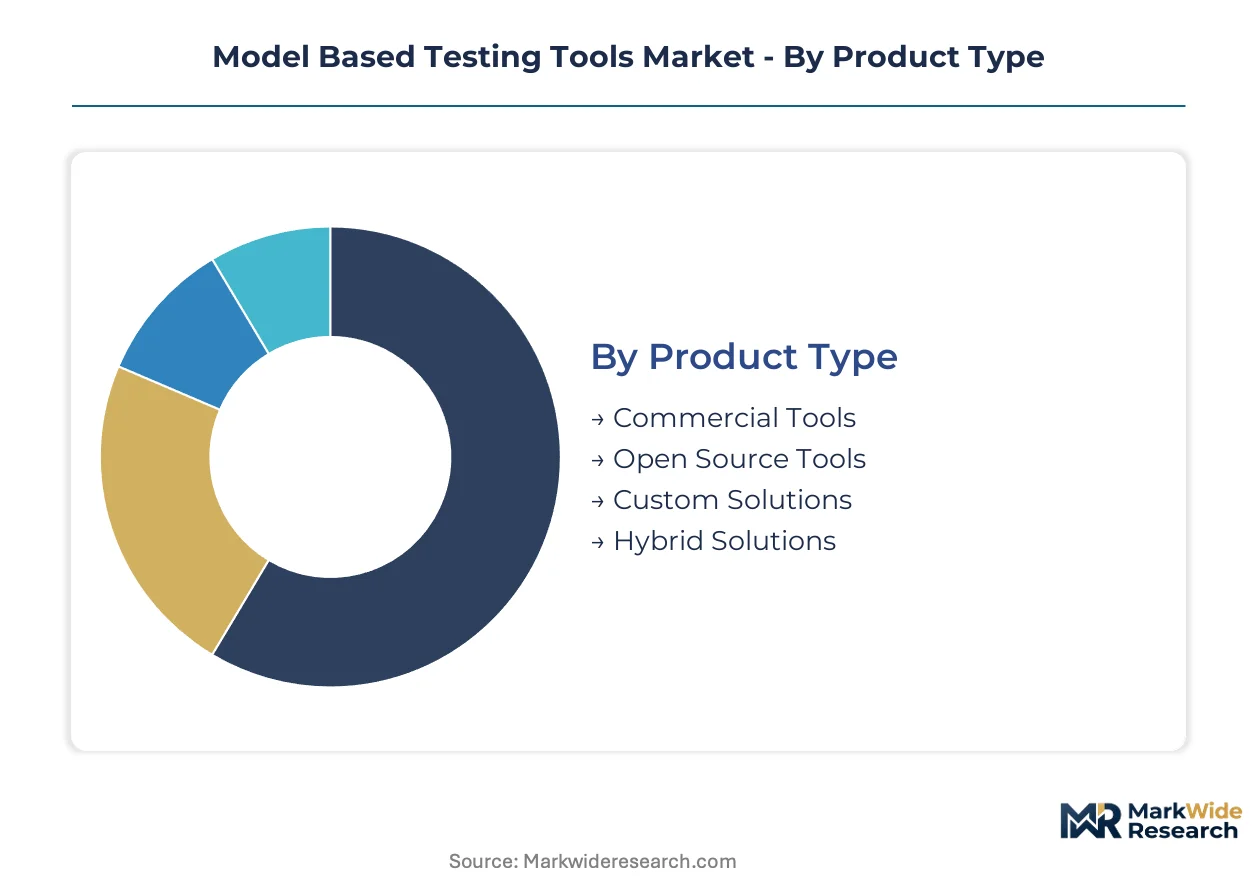
Segmentation in the Model Based Testing Tools Market reveals how procurement authority, certification requirements, and deployment constraints reshape vendor go-to-market strategies. Understanding these divides explains why commercial platforms command premium pricing while open-source alternatives capture mid-tier volume.
Product Type:
Margin pools concentrate in certified commercial offerings where ISO 26262 and DO-178C compliance modules justify substantial price premiums over baseline functionality.
- Commercial Tools:These platforms bundle certified compliance modules for automotive functional safety and aerospace software standards. German automotive OEMs and Tier-1 suppliers anchor demand as they replace manual verification workflows with automated traceability systems ahead of regulatory deadlines.
- Open Source Tools:Community-developed frameworks prioritize customization flexibility over formal certification documentation. Mid-tier software developers in cost-sensitive sectors adopt these tools despite sacrificing audit trail capabilities required by FDA and EMA guidelines.
- Custom Solutions:Engineering services firms build proprietary testing environments for specific client toolchains. Defense contractors favor this approach to maintain airworthiness certification continuity with legacy systems.
- Hybrid Solutions:These deployments combine commercial cores with open-source extensions for specialized verification tasks. IT departments managing distributed agile teams deploy hybrid architectures to balance compliance coverage with customization needs.
Commercial Tools hold installed capacity across safety-critical sectors. Hybrid Solutions is rotating up the share rankings as enterprises seek middle-ground procurement strategies.
Technology:
Volume concentrates in test automation engines where state-machine-based test generation addresses autonomous driving complexity that manual methods cannot achieve.
- Static Analysis:These engines parse formal models without execution to identify structural defects and specification inconsistencies early in development cycles. Automotive suppliers in Japan deploy static analysis for ADAS platform verification where exhaustive scenario coverage is mandatory.
- Test Automation:Platforms automatically generate executable test cases from UML diagrams and decision tables. This technology is climbing the fastest as NHTSA software-defined vehicle guidance accelerates OEM procurement of certified toolchains in the United States.
- Performance Testing:These tools validate system behavior under load and timing constraints. Aerospace manufacturers apply performance testing to verify real-time control systems against DO-178C objectives.
- Continuous Integration:CI-embedded testing pipelines execute verification suites automatically upon code commits. Cloud-native development teams across IT departments favor this approach for distributed agile workflows.
Test Automation commands the steepest expansion trajectory. Static Analysis maintains foundational positioning in safety-critical verification workflows.
End User:
Procurement authority is bifurcating toward compliance functions as liability exposure from functional safety failures restructures enterprise buying patterns.
- Software Developers:Individual contributors leverage model-based testing for unit-level verification before code integration. These users prioritize rapid feedback loops over comprehensive compliance documentation.
- QA Engineers:Quality assurance specialists execute system-level test campaigns and analyze failure patterns. Their workflows increasingly intersect with formal methods expertise that remains scarce in the labor market.
- IT Departments:Central technology functions procure enterprise-wide platforms for distributed development teams. Cloud-based deployment options dominate their evaluations as they manage globally dispersed agile operations.
- Compliance Teams:Enterprise compliance functions now control procurement authority for certified toolchains in automotive and medical device manufacturers. These buyers mandate ISO 26262 and FDA validation features that command premium pricing tiers.
Compliance Teams are consolidating procurement control. Software Developers retain volume influence through grassroots tool adoption.
Deployment:
Data sovereignty requirements in defense and aerospace sectors preserve on-premises dominance despite cloud-native momentum in unregulated industries.
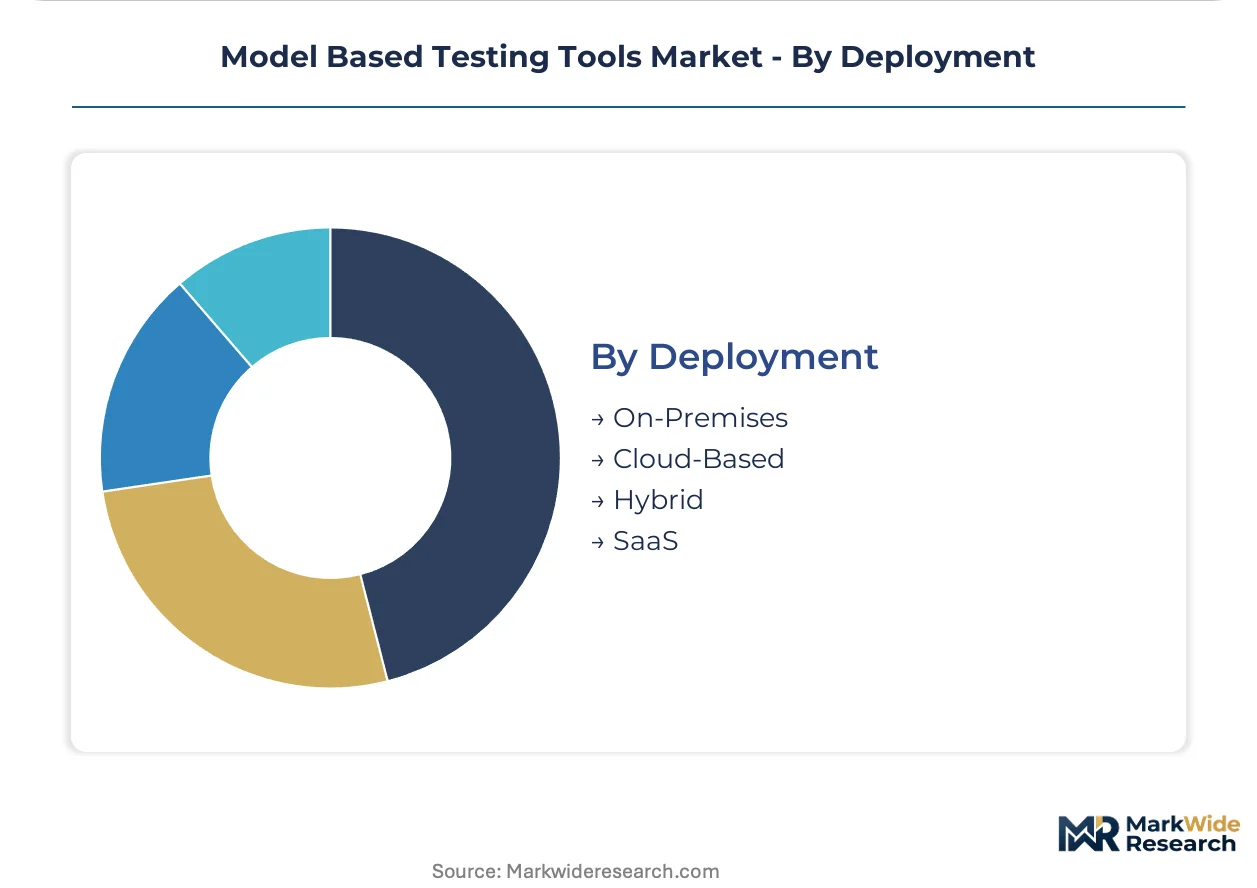
- On-Premises:Installed software running within client-controlled infrastructure satisfies strict data residency mandates. Defense and aerospace sectors maintain this deployment mode to protect classified development artifacts and satisfy airworthiness certification continuity.
- Cloud-Based:Hosted platforms deliver scalable compute resources for test execution without capital infrastructure investment. IT departments managing distributed agile teams are expanding cloud-based adoption fastest in non-regulated software development.
- Hybrid:Mixed deployments keep sensitive verification data on-premises while leveraging cloud elasticity for compute-intensive test campaigns. European automotive suppliers favor this architecture to reconcile GDPR data localization with processing scalability.
- SaaS:Subscription-based access to fully managed testing platforms eliminates operational overhead for mid-market enterprises. These offerings attract software developers prioritizing rapid onboarding over deep customization.
On-Premises retains dominance in regulated sectors. Cloud-Based deployment is gaining share fastest among IT departments with distributed team structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates among German automotive engineering clusters, Japanese precision manufacturing hubs, and United States defense-aerospace corridors where functional safety certification demands intersect with deep systems engineering expertise.
Germany
KBA enforcement of ISO 26262 compliance deadlines drives Tier-1 supplier procurement of certified toolchains for ADAS verification. The EU AI Act's risk classification framework mandates traceable documentation for AI-enabled perception systems. Stuttgart and Munich engineering clusters anchor demand as domestic OEMs expand model-based verification for autonomous driving platforms.
United States
NHTSA software-defined vehicle guidance accelerates OEM investment in automated verification ahead of formal rulemaking. FDA software validation guidelines for medical devices mandate traceable methodologies that model-based testing addresses. Detroit automotive corridors and Seattle-Bellevue cloud engineering clusters concentrate procurement authority within enterprise compliance functions.
Japan
METI industrial policy prioritizes autonomous system verification as domestic OEMs advance Level 4 driving capabilities. JIS standards alignment with ISO 26262 creates regulatory pressure for toolchain upgrades across automotive suppliers. Nagoya and Tokyo-Yokohama manufacturing belts deploy state-machine-based test generation for exhaustive scenario coverage.
United Kingdom
MHRA alignment with FDA software validation guidelines drives medical device manufacturer adoption of certified platforms. The UK AI Regulation white paper signals forthcoming traceability requirements for high-risk AI systems. Cambridge and London fintech-engineering clusters apply model-based methods to safety-critical financial infrastructure verification.
India
Automotive software export growth from domestic IT services firms creates demand for ISO 26262-aligned verification capabilities. BIS adoption of international functional safety standards pressures supplier base toward certified toolchain investment. Bangalore and Hyderabad technology corridors concentrate agile development teams adopting cloud-native testing platforms.
Model Based Testing Tools Market Competitive Landscape
Concentration sits with diversified technology conglomerates and specialized testing platform vendors. The vendor base spans three tiers: enterprise software incumbents with legacy systems integration capabilities, pure-play testing specialists with automotive safety certification depth, and open-source framework maintainers serving cost-sensitive development teams. Strategic moves center on cloud-native architecture migration and compliance module certification expansion for emerging AI safety standards.
Within the enterprise software tier, IBM Corporation and Microsoft Corporation exemplify platform consolidation strategies that embed testing capabilities within broader development ecosystems. Tricentis occupies a position among specialized vendors with concentrated channel control across European automotive hubs. Testing Technologies IST GmbH represents German engineering-focused specialists serving Tier-1 supplier verification requirements. These archetypes reflect divergent paths: breadth versus depth, cloud-native versus on-premises heritage, and geographic certification proximity versus global scale.
| Leading Market Players |
|---|
| Teveron |
| Testing Technologies IST GmbH |
| Tricentis |
| MBTsuite |
| GraphWalker |
| Testoptimal |
| Oracle |
| Microsoft Corporation |
| IBM Corporation |
| Others |
Supply & Pricing Matrix
ISO 26262 functional safety certification gates both supplier qualification and price differentiation in the model-based testing tools market, forcing Tier-1 automotive suppliers to absorb substantial premiums for compliance modules while mid-tier developers retreat to uncertified alternatives.
Pricing Analysis
ISO 26262 dictates the pricing tier structure across the model-based testing landscape, separating certified commercial platforms from open-source frameworks by audit trail capabilities. Three-tier pricing stratifies across enterprise compliance-grade, professional developer, and community editions, with certification level and after-sales support bundling as primary differentiation drivers. Cost compression in the mid-market tier is intensifying because open-source substitution erodes baseline pricing power. Software developers exhibit highest price sensitivity, while automotive compliance teams accept premium positioning to satisfy KBA enforcement timelines.
Supply Chain Analysis
Just-in-time delivery preferences dominate software distribution, though defense contractors maintain strategic stockpiles of airworthiness-certified tool versions to preserve certification continuity. Supply concentrates in Germany, the United States, and Japan where automotive software engineering clusters anchor development. The supply chain draws from specialized systems engineering talent pools, cloud infrastructure providers, and third-party certification auditors. Single-source vulnerability in certified compliance module provision creates structural risk for European OEMs facing EU AI Act deadlines. Distribution runs through direct enterprise sales channels for regulated sectors and self-service SaaS marketplaces for IT departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The model-based testing tools market is cycling through a compliance-driven expansion phase as automotive OEMs replace manual verification ahead of NHTSA formal rulemaking.
For Market Incumbents: Secure certification module depth for emerging AI safety standards before EU AI Act full enforcement. Deepen channel control across Stuttgart and Munich automotive clusters to lock out emerging cloud-native competitors. Prioritize backward integration into formal methods training ecosystems to address state machine modeling expertise scarcity. For New Entrants and Emerging Players: Differentiate on neuro-symbolic test generation capabilities where incumbent engines remain rule-based. Target cloud-native deployment white space among IT departments managing distributed agile teams outside regulated sectors. Pursue partnership-led go-to-market strategies with hyperscaler marketplaces to bypass entrenched direct sales channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-enabled verification sub-segments as R&D allocation shifts toward hybrid symbolic-neural architectures. Long-term viability favors platforms with embedded compliance documentation rather than point-test automation tools. Acquisition targets should display existing ISO 26262 certification relationships with German Tier-1 suppliers. Watch NHTSA software-defined vehicle guidance formalization as inflection indicator for OEM procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Module Expansion | ISO 26262 and EU AI Act alignment secures automotive compliance team procurement authority. |
| Cloud-Native Architecture Migration | SaaS delivery captures IT department demand from distributed agile development teams. |
| Neuro-Symbolic Engine Development | Hybrid AI architectures displace rule-based prioritization for autonomous driving verification. |
| Formal Methods Training Ecosystem | Addressing state machine expertise scarcity accelerates platform adoption beyond specialized engineers. |
| Channel Control in German Automotive Hubs | Proximity to Stuttgart and Munich OEMs sustains enterprise relationship defensibility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing enterprise compliance officers, automotive platform engineers, QA specialists at Tier-1 suppliers, IT procurement leads, and cloud-native development team managers. Secondary validation incorporated SEC filings from diversified technology conglomerates, FDA software validation guidance documents, NHTSA regulatory dockets, ISO 26262 certification registries, and hyperscaler marketplace transaction data. Bottom-up segment sizing triangulated against top-down industry spend estimates.
Across the projection horizon, the analytical framework modeled deployment mode, organization size, vertical industry, integration complexity, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from fitted growth curves anchored to observable procurement cycle timing and compliance deadline schedules. Forecast inputs included automotive software complexity indices, autonomous driving validation scenario counts, and cloud infrastructure spend trajectories.
The analysis sits within stated boundaries; outcomes outside sustained automotive software investment cycles or delayed NHTSA formal rulemaking would require recalibration. Forecasts reflect documented assumptions regarding certification timeline adherence and labor market expertise availability. Revision becomes warranted when open-source framework maturity crosses thresholds sufficient to satisfy audit trail requirements in regulated sectors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Spain Sports Management Software Market
Software & Services
Binary Drivers Market
Software & Services
Global Quoting Software Market
Software & Services
Torque Software Market
Software & Services
Enterprise Content Management Software Market
Software & Services
Warranty Management Software Market
Software & Services
Generative Design Software Market
Software & Services
Data Conversion Services Market
Software & Services
Global Help Desk Software Market
Software & Services
Global Smartphone Operating System (OS) Market
Software & Services
Pay-Per-Click (PPC) Software Market
Software & Services
User Research Repositories Software Market
Software & Services
Enterprise Resource Planning (ERP) Software Market
Software & Services
Java Integrated Development Environment (IDE) Market
Software & Services
Ecommerce Software and Platform Market
Software & Services
Stone Analysis Software Market