
 Global Additive Manufacturing with Metal Powders Market | 2026-2036
Global Additive Manufacturing with Metal Powders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Additive Manufacturing with Metal Powders Market Analysis
Multi-sourced powder procurement is decoupling from the single-supplier models that dominated early metal additive manufacturing. EOS leverages its installed base of laser sintering systems to sustain recurring material sales across European aerospace shops. Sandvik AB anchors its position through captive production of gas-atomized superalloys, while Höganäs AB competes via broad portfolio breadth across iron-based and tool steel powders.
Additive manufacturing with metal powders encompasses layer-by-layer fusion or binding of metallic feedstocks—typically particle sizes of 15-45 micrometers—to produce near-net-shape components with complex internal geometries. The process serves industries requiring weight reduction, part consolidation, or supply chain compression that conventional subtractive methods cannot achieve economically. Titanium alloys command premium positioning in aerospace and medical end uses where strength-to-weight ratios and biocompatibility justify material costs. Selective laser melting dominates current installed capacity, though binder jetting is capturing interest for higher-throughput production runs where post-process sintering tolerances align with application requirements.
FDA device regulations and EU MDR conformity requirements shape qualification protocols for medical implant producers, extending validation timelines but raising barriers against unapproved suppliers. EPA air emissions standards and OSHA metal fume exposure limits govern powder handling facilities in the United States, while REACH compliance in Europe constrains novel alloy compositions containing restricted elements. Stakeholders must weigh capital intensity against the strategic optionality of qualifying multiple powder grades and machine platforms before demand scale renders late entry prohibitively expensive.
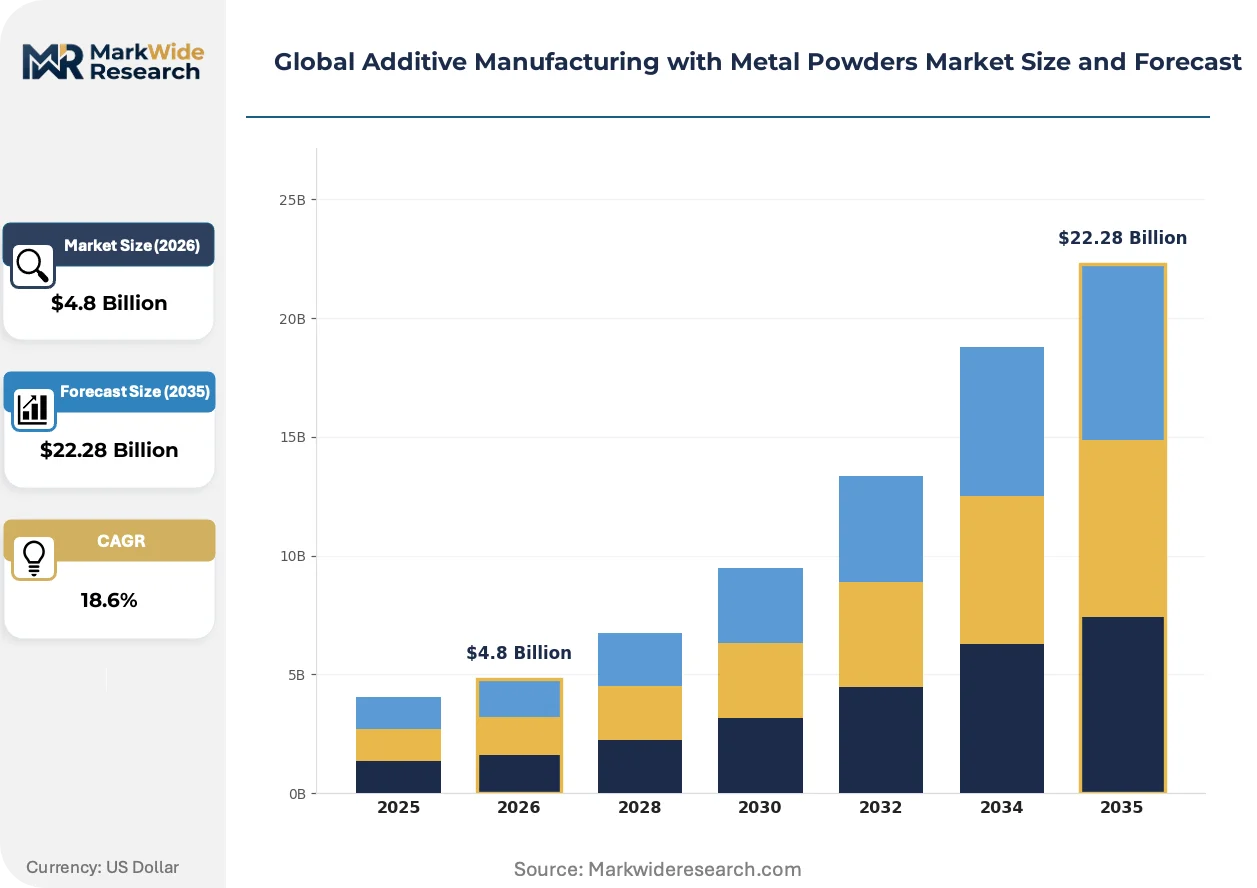
Market Dynamics
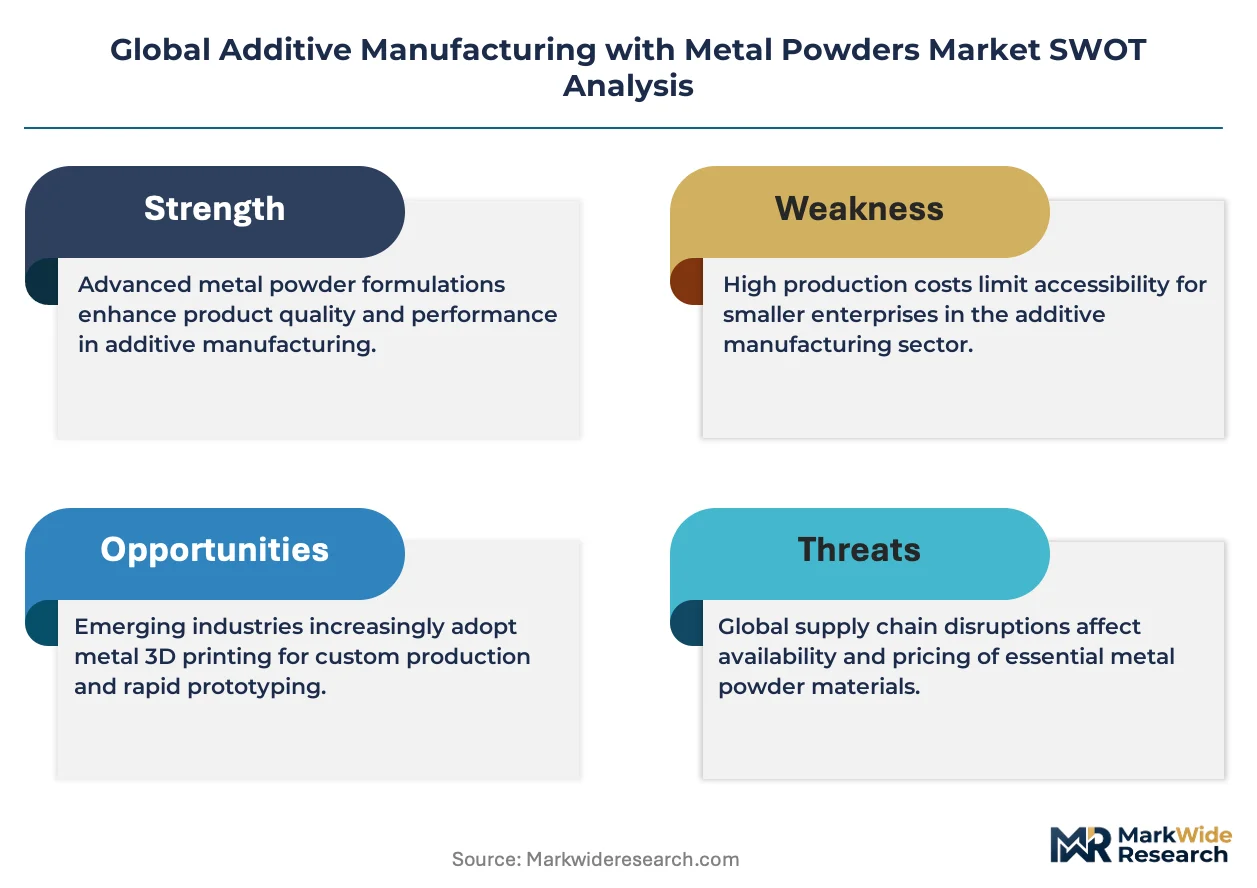
Multi-sourced powder procurement is decoupling from single-supplier dependency as aerospace and medical buyers demand qualified secondary sources for titanium and nickel superalloy grades. This structural shift toward supply redundancy is reshaping contract structures, inventory minimums, and qualification timelines across the value chain.
Growth Catalysts
- EU MDR conformity requirements:Medical device producers must validate implant-grade powders through notified bodies, extending supplier lock-in and raising switching costs for approved vendors.
- Titanium alloy demand in aerospace:Structural airframe programs specify additively manufactured Ti-6Al-4V components for weight reduction and part consolidation benefits.
- Gas-atomized superalloy production:Captive atomization capacity in Sweden and Germany secures supply chains for turbine blade and heat exchanger applications.
Market Restraints
- Argon and helium feedstock costs:Inert gas atomization consumes substantial noble gas volumes, exposing powder producers to commodity price volatility and supply interruptions.
- Single-source qualification risk:Aerospace primes often mandate sole-qualified powder lots, creating concentration vulnerability when primary suppliers face production constraints.
- REACH substance restrictions:Novel alloy compositions containing cobalt, nickel, or chromium face extended toxicity dossier requirements, delaying commercialization timelines.
Strategic Opportunities
- Binder jetting for production runs:Higher-throughput sintering-based systems enable cost-competitive batch manufacturing where tolerances permit post-process densification.
- India's PLI scheme for advanced manufacturing:Domestic medical implant and aerospace component production incentives attract powder qualification investments and localized atomization capacity.
- Convergence of AI-driven process monitoring:Real-time melt pool analytics integrated with selective laser melting platforms reduce defect rates and accelerate first-article approval.
Industry Challenges
- Certified technician scarcity:Operators trained in powder handling, machine calibration, and post-processing heat treatment command premium wages and extended recruitment cycles.
- Multi-platform powder qualification:Buyers must validate identical powder lots across laser melting and electron beam systems, duplicating metallurgical testing and mechanical property documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Additive Manufacturing with Metal Powders Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Titanium Alloys, Aluminum Alloys, Copper Alloys Technology: Selective Laser Melting, Electron Beam Melting, Direct Energy Deposition, Binder Jetting End User: Aerospace, Automotive Parts, Medical Devices, Tooling Application: Prototyping, Production Parts, Repair, Custom Manufacturing |
| Companies Covered | EOS, 3D Systems, Renishaw, Höganäs AB, GE Additive, GKN PLC, Sandvik AB, Bright Laser Technologies, DMG MORI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Additive Manufacturing with Metal Powders Market Emerging Trajectories
Process automation and closed-loop quality assurance are compressing the gap between prototype validation and production-scale metal additive manufacturing. These advances are enabling consistent part-to-part repeatability that aerospace and medical regulators demand.
Binder jetting metal printing is absorbing mid-volume production applications previously served by metal injection molding and small-lot machining. Automotive suppliers in Germany are adopting the technology for stainless steel brackets and fluid manifold prototypes. The process is absorbing tooling spend as buyers recognize sintering tolerances now align with functional non-critical component specifications.
REACH compliance deadlines in Europe are forcing reformulation of legacy nickel-based powders containing restricted elemental additives. Powder producers are submitting updated safety dossiers to ECHA ahead of substance evaluation windows. Medical implant manufacturers face the tightest adaptation requirements as biocompatibility certifications must be re-issued for modified compositions.
Consolidated procurement through approved supplier lists is displacing spot-market powder purchasing in aerospace tier-one supply chains. Buyers in France and the United Kingdom now mandate dual-qualified sources for flight-critical titanium grades. This concentration of purchasing authority favors incumbent powder atomizers with established aerospace quality systems and existing Nadcap accreditation.
Global Additive Manufacturing with Metal Powders Market Segmentation
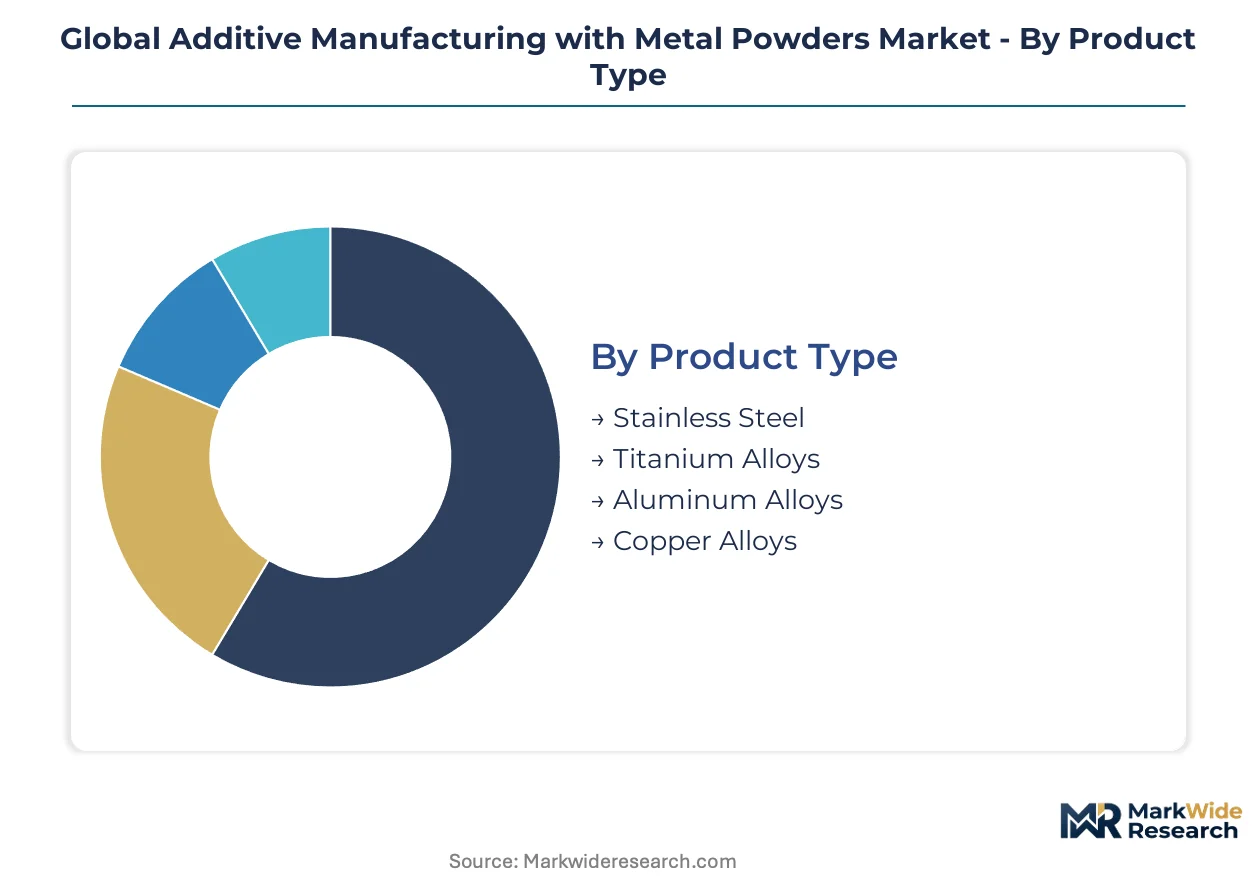
Metal powder additive manufacturing segments diverge sharply across material cost tiers, process maturity, and regulatory qualification burdens. Buyers map procurement strategies to these divisions, prioritizing titanium and nickel superalloys for flight-critical applications while deploying aluminum and stainless steel for faster qualification cycles.
Product Type:
Customization intensity runs highest in titanium and superalloy grades, where aerospace primes specify lot-controlled chemistries and particle size distributions. Standardized stainless and aluminum powders trade specification breadth for volume availability and multi-source procurement flexibility.
- Titanium Alloys:Ti-6Al-4V and Ti-6Al-4V ELI dominate aerospace structural applications, with gas-atomized spherical powder commanding premium positioning. Demand concentrates in Germany and the United States, where Boeing and Airbus tier-one suppliers qualify captive atomization lots through Nadcap-accredited facilities. REACH substance restrictions on vanadium content are forcing reformulation timelines for European medical implant producers.
- Stainless Steel:316L and 17-4 PH grades serve medical instruments, food processing equipment, and chemical industry components where corrosion resistance and printability balance cost. Automotive suppliers in Stuttgart and Wolfsburg deploy these powders for functional prototyping and small-series manifold production.
- Aluminum Alloys:AlSi10Mg offers the lowest density among printable metals, attracting automotive lightweighting programs and consumer electronics heat sink applications.
- Copper Alloys:Pure copper and CuCrZr enable thermal management components and electrical connectors, though high reflectivity challenges laser absorption and requires specialized system configurations.
Most installed capacity flows through stainless steel and titanium grades. Expansion is steepest in aluminum alloys as automotive thermal management applications multiply.
Technology:
Process selection hinges on throughput requirements versus geometric complexity, with laser-based systems commanding precision markets and binder jetting absorbing cost-sensitive production volumes.
- Selective Laser Melting:Fiber laser fusion of 20-50 micron powder layers delivers the finest feature resolution and surface finish, dominating aerospace turbine blade and medical implant production. EOS and SLM Solutions equipment anchors installed bases across Munich, Aachen, and Swedish industrial clusters.
- Binder Jetting:Polymer binder deposition followed by sintering enables 10x throughput advantages over fusion processes, capturing automotive bracket and fluid manifold production where tolerances permit post-process densification. ExOne and Desktop Metal systems are penetrating German automotive supplier networks.
- Electron Beam Melting:Vacuum chamber processing eliminates oxidation in reactive titanium and superalloy builds, serving orthopedic implant manufacturers requiring fully dense, stress-relieved components.
- Direct Energy Deposition:Wire or powder-fed laser/warc hybrid systems repair turbine blades and fabricate large structural features, extending component life in military aviation maintenance depots.
Technology deployment clusters geographically around equipment manufacturer headquarters and aerospace tier-one concentrations. Binder jetting is climbing the fastest as sintering tolerance improvements unlock production economics.
End User:
End-use sectors separate by certification burden and lot traceability requirements, with medical and aerospace demanding full supply chain documentation while automotive and tooling tolerate broader specification windows.
- Aerospace:Structural airframe programs specify additively manufactured Ti-6Al-4V brackets and pylon components for weight reduction. FAA and EASA certification protocols mandate powder lot retention and mechanical property testing across build orientations.
- Medical Devices:FDA 510(k) and EU MDR conformity requirements extend validation timelines for implant-grade powders, creating supplier lock-in for approved vendors. Spinal cages and acetabular cups drive titanium and cobalt-chrome consumption.
- Automotive Parts:Stainless steel brackets, aluminum heat exchangers, and copper busbars serve electric vehicle thermal management and power electronics cooling. German OEMs lead qualification of production-scale binder jetting applications.
- Tooling:Conformal cooling channels in injection molds and die casting inserts reduce cycle times and extend tool life, with H13 and maraging steel powders serving mold makers in the United States and Japan.
Aerospace and medical command the highest powder premiums per kilogram. Automotive tooling applications are expanding most quickly as production economics mature.
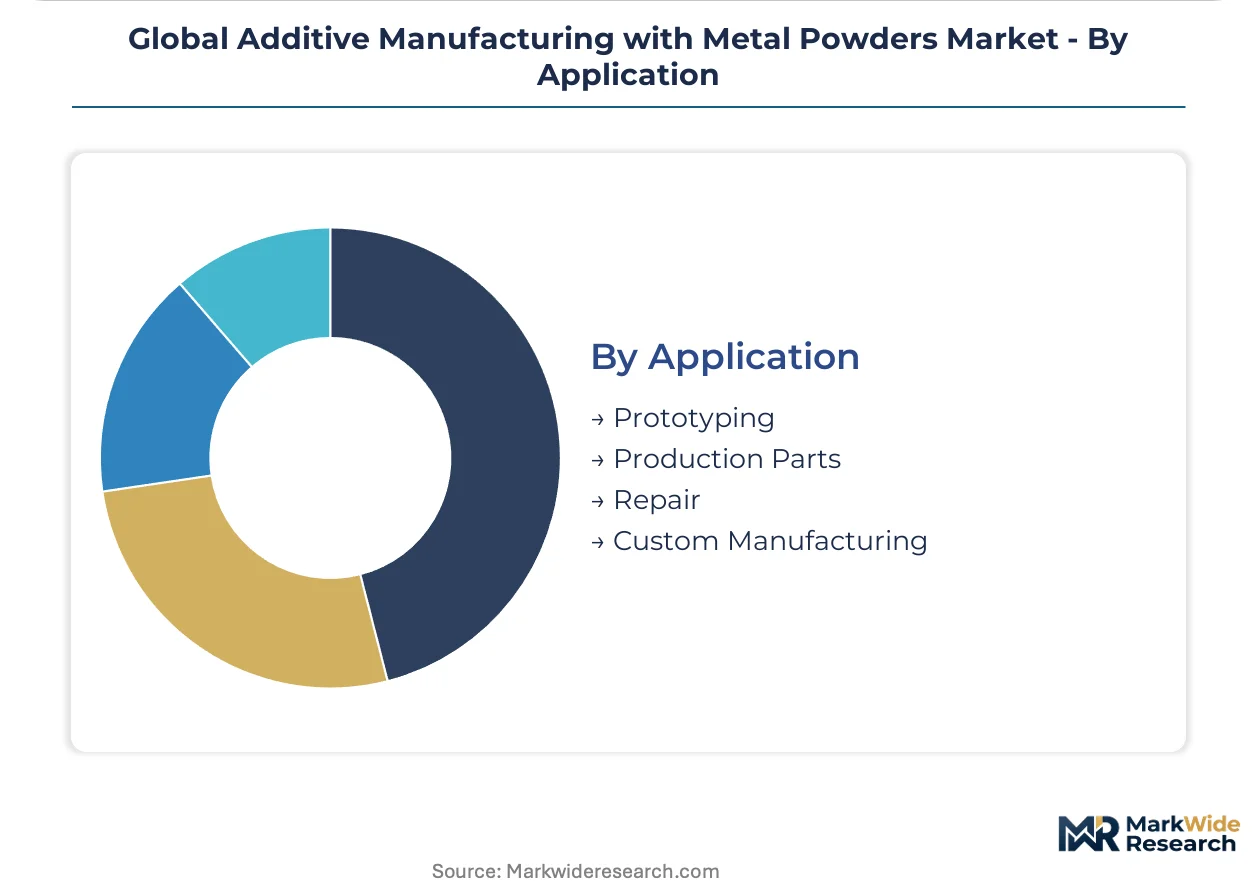
Application:
Application mode determines powder lot sizing, quality documentation depth, and post-processing requirements, with production parts and repair operations demanding distinct supply chain configurations.
- Production Parts:Series manufacturing of flight brackets, medical implants, and automotive manifolds requires statistical process control and continuous powder qualification. Contract manufacturers in Germany and the United States are consolidating approved supplier lists for titanium and superalloy grades.
- Prototyping:Design validation and fit-check components tolerate broader powder specification windows, enabling spot purchasing and faster iteration cycles across aluminum and stainless steel grades.
- Repair:Turbine blade tip restoration and shaft cladding extend component life through directed energy deposition, with powder consumption tied to maintenance schedules at airline overhaul facilities and power generation service centers.
- Custom Manufacturing:Patient-specific orthopedic implants and dental frameworks require lot sizes below 10 kilograms, favoring flexible atomization campaigns and rapid qualification protocols.
Prototyping retains the largest share of build hours. Production parts are gaining share fastest as aerospace qualification timelines compress and automotive adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as powder atomizers migrate toward jurisdictions with streamlined REACH dossier pathways and lower noble-gas energy costs. Manufacturers now site captive capacity where compliance timelines compress and inert gas feedstock prices stabilize.
United States
FAA certification protocols for flight-critical titanium brackets sustain demand for Nadcap-accredited powder lots. EPA air emissions standards and OSHA metal fume exposure limits govern handling facilities in Texas and California. The Greater Boston corridor anchors medical implant prototyping, while Pacific Northwest aerospace clusters qualify superalloy grades for turbine applications.
Germany
EU MDR conformity requirements extend validation timelines for implant-grade powders, locking in approved suppliers. REACH substance restrictions on vanadium content force reformulation of medical-grade titanium alloys. Industrial clusters around Munich and Aachen concentrate both laser sintering equipment supply and gas-atomized powder research.
Sweden
Captive gas-atomized superalloy production secures supply chains for European turbine blade manufacturers. ECHA substance evaluation windows drive proactive safety dossier submissions from powder producers. Sandviken and Stockholm regions host vertically integrated atomization capacity serving aerospace primes with lot-controlled chemistries.
China
Domestic titanium alloy demand for structural airframe programs accelerates qualification of localized powder production. MIIT standards for additive manufacturing equipment shape certification protocols for industrial laser systems. Yangtze River Delta industrial zones concentrate metal powder research institutes and aerospace tier-two suppliers.
India
PLI scheme incentives for advanced manufacturing attract powder qualification investments and localized atomization capacity. CDSCO medical device regulations extend validation timelines for implant-grade materials. Maharashtra and Gujarat industrial corridors anchor emerging medical implant and aerospace component production clusters.
Global Additive Manufacturing with Metal Powders Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue binder-jetting scale economics and aluminum alloy specialization. The vendor base stratifies across three maturity tiers: legacy equipment manufacturers with installed-base material lock-in, captive atomizers with superalloy metallurgy depth, and contract manufacturers consolidating approved supplier lists. Dominant competitive moves include backward integration into gas-atomization capacity and geographic expansion toward PLI-subsidized production zones.
Among European-based powder specialists, EOS and Höganäs AB exemplify contrasting archetypes—equipment-driven material recurring revenue versus portfolio-breadth commodity positioning. Sandvik AB anchors the captive-atomization tier with Swedish superalloy metallurgy heritage. These three entities represent the dominant competitive postures: installed-base monetization, specification breadth, and upstream metallurgical control.
| Leading Market Players |
|---|
| EOS |
| 3D Systems |
| Renishaw |
| Höganäs AB |
| GE Additive |
| GKN PLC |
| Sandvik AB |
| Bright Laser Technologies |
| DMG MORI |
| Others |
Supply Flow & Price Mechanics
Aerospace tier-one procurement concentration around Munich and Aachen anchors contract-based long-term offtake structures, with Nadcap-accredited suppliers commanding premium positioning over spot-market alternatives.
Pricing Analysis
Distributor margins on gas-atomized titanium powders absorb 15-25 percent of final delivered cost to medical implant manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates flight-critical superalloy grades from industrial stainless steel and prototyping aluminum. Cost compression in standard-grade stainless powders is intensifying because automotive suppliers are consolidating volume commitments. Medical device OEMs exhibit the lowest price sensitivity due to locked-in qualification timelines, while prototyping shops face acute margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with Swedish and German captive atomizers controlling gas-atomized superalloy supply for European turbine manufacturers. Raw material dependencies span argon and helium feedstocks from Qatar and the United States, plus sponge titanium from Ukraine and Japan. Tariff exposure on noble gas imports threatens margin stability at powder producers. Distribution runs through approved supplier lists mandated by aerospace primes, displacing open-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory-arbitrage dynamics between REACH-constrained Europe and PLI-subsidized India create geographic-arbitrage opportunities for powder atomizers seeking lower compliance costs and subsidized capacity buildout.
For Market Incumbents: Lock in aerospace tier-one relationships through dual-qualified source contracts before emerging Indian atomizers achieve Nadcap accreditation. Backward integration into noble gas recycling capacity mitigates feedstock volatility. Binder jetting equipment manufacturers represent a substitution threat requiring monitoring. For New Entrants and Emerging Players: The mid-tier pricing gap between premium superalloys and economy stainless grades offers white-space entry for aluminum alloy specialization and automotive thermal management applications. India's Maharashtra industrial corridor presents the most penetrable geography given PLI scheme incentives. A contract-manufacturing-for-qualification go-to-market angle accelerates first-article approval without captive atomization investment. For Investors and Strategic Acquirers: Aerospace primes and Tier 1 suppliers are the most active acquirers in this space, consolidating approved supplier lists to secure supply chain redundancy. Long-term viability hinges on qualification moat durability against emerging low-cost atomizers. Watch for binder jetting tolerance improvements as the inflection signal threatening laser-melting incumbent economics.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Gas Atomization Capacity | Secures supply chain autonomy for Boeing and Airbus tier-one suppliers facing REACH restrictions. |
| Dual-Source Qualification Investment | Reduces concentration risk for medical implant producers navigating EU MDR extended timelines. |
| Binder Jetting Platform Deployment | Captures automotive bracket production previously served by metal injection molding in Stuttgart. |
| India PLI-Aligned Localization | Positions atomizers for CDSCO medical device qualification and aerospace tier-two supply. |
| AI-Driven Process Monitoring Integration | Accelerates first-article approval for EOS and SLM Solutions equipment operators. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with powder metallurgy R&D directors, aerospace procurement managers, medical device regulatory affairs leads, and gas atomization plant engineers combined with secondary validation from ECHA substance dossiers, FAA certification databases, EU MDR notified body filings, and customs trade data on noble gas imports.
Historical trendline analysis across installed equipment capacity, qualified powder lots, and build-hour utilization informed projection framework development. Segmentation dimensions modeled include material grade tier, process technology, end-use sector certification burden, and regional regulatory cluster. CAGRs derived from slope analysis of adoption curves, adjusted for qualification timeline compression and automotive production ramp assumptions.
Caveats apply where REACH substance evaluation outcomes, noble gas supply interruptions, or binder jetting tolerance breakthroughs could materially shift the outlook. Forecasts assume continuation of current aerospace qualification protocols and PLI scheme incentive structures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Printing Software Market
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
Digital 3D Printing Market
3D Printing Technology
Additive Manufacturing Software Market
3D Printing Technology
PEEK Filament Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
Europe 3D Printing Market
3D Printing Technology
3D Printing Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
3D Printing Materials and Equipment Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
North America Industrial 3D Printing Market