
 3D Printing Medical Device Software Market | 2026-2036
3D Printing Medical Device Software Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Medical Device Software Market Analysis
The EU Green Deal is restructuring procurement criteria across European healthcare systems, favoring software platforms that minimize material waste in patient-specific production. Materialise NV anchors its position through deep specialization in surgical planning workflows. EOS GmbH competes by controlling high-precision laser sintering parameters within integrated software stacks. Stratasys Ltd differentiates through polymer expertise that extends from hardware into proprietary print preparation algorithms.
3D printing medical device software comprises computational platforms that translate anatomical imaging data into machine-executable build instructions, incorporating mesh repair, topology optimization, and thermal simulation with layer-resolution control down to 20 microns. These systems enable fabrication of patient-matched orthopedic implants, dental restorations, and surgical guides directly from DICOM datasets. Design software captures the largest margin pool by locking users into proprietary file formats and recurring license structures. Simulation software represents the fastest-expanding category as regulators demand in-silico validation of mechanical performance before physical testing. Slicing software remains the most mature segment, though cloud-based deployment is displacing traditional desktop installations among smaller dental clinics and research labs.
The FDA's 510(k) pathway for patient-specific devices and the EU MDR's software-as-medical-device classification are tightening validation requirements, forcing vendors to embed audit trails and risk management documentation directly into their platforms. ISO 13485 quality management standards now extend to software lifecycle processes, creating compliance barriers for non-certified entrants. Stakeholders must monitor how the FDA's emerging guidance on artificial intelligence in device software intersects with generative design capabilities before committing to platform architectures.
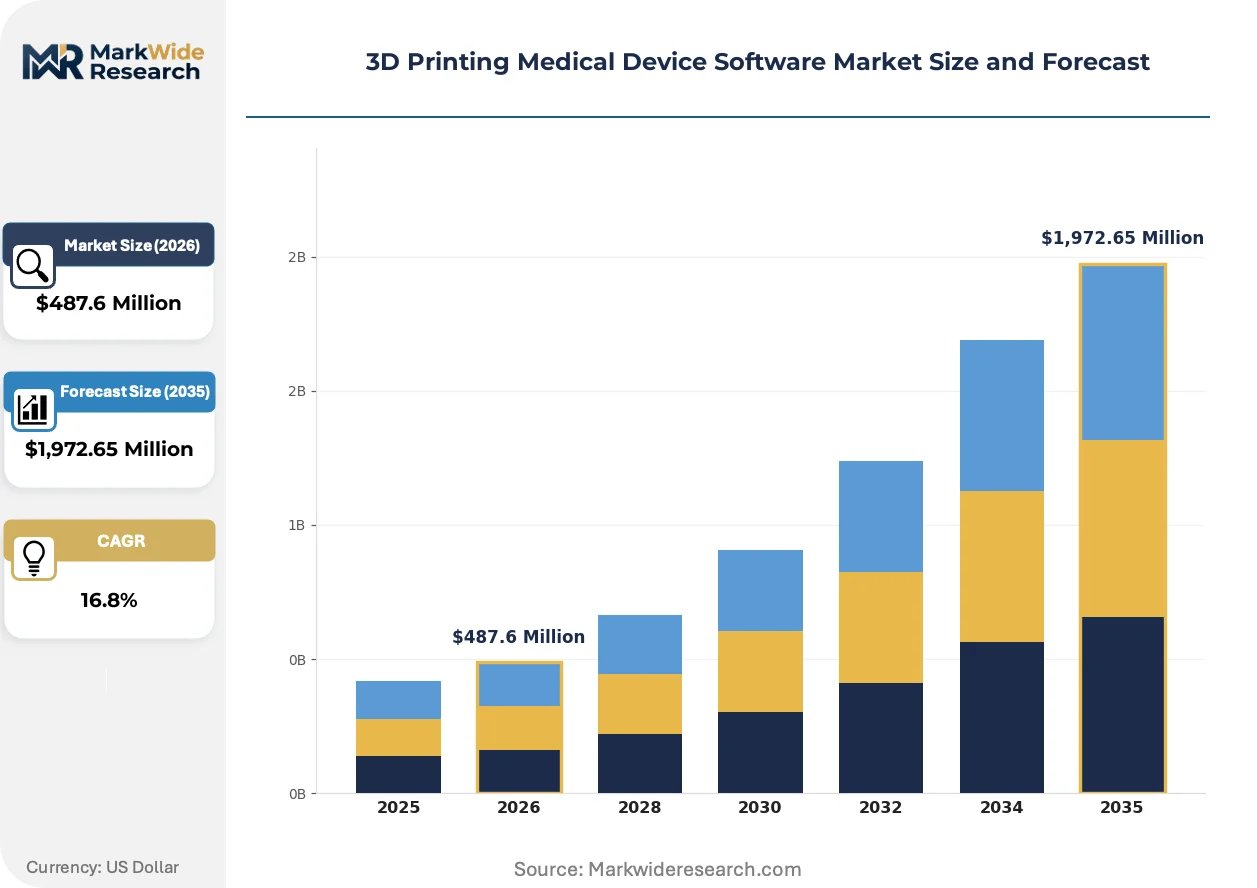
Market Dynamics
Regulatory reclassification of software as a medical device under the EU MDR and FDA's evolving AI guidance is compressing development timelines while elevating compliance costs for platform vendors.
Growth Catalysts
- Patient-matched orthopedic demand:Hospitals in Germany are mandating pre-surgical planning software for complex joint reconstructions, accelerating procurement cycles for integrated design-to-print platforms.
- EU Green Deal procurement criteria:Healthcare systems now weight material waste reduction in vendor selection, favoring topology optimization algorithms that minimize support structures.
- In-silico validation mandates:Mechanical simulation software is displacing physical prototyping as regulators accept computational evidence for biocompatibility assessments.
Market Restraints
- ISO 13485 certification barriers:Quality management audits for software lifecycle processes extend market entry timelines by 18-24 months for non-established vendors.
- Specialized talent scarcity:The intersection of biomedical engineering, computational geometry, and regulatory science concentrates in Munich and Hamburg industrial clusters.
- High-precision hardware coupling:Software margins remain tethered to laser sintering and material extrusion equipment refresh cycles controlled by EOS GmbH and Stratasys Ltd.
Strategic Opportunities
- Cloud-based slicing for dental clinics:Subscription deployment models are penetrating smaller practices in Spain and Italy that previously relied on desktop installations.
- Generative design-AI convergence:Topology optimization platforms incorporating machine learning are creating white space for automated implant lattice generation.
- Swissmedic fast-track pathways:Switzerland's streamlined software-as-medical-device classification offers expedited market access for validated patient-specific planning tools.
Industry Challenges
- DICOM-to-mesh conversion expertise:Clinical engineering teams lack personnel trained in anatomical segmentation and STL repair workflows.
- Legacy PACS integration friction:Hospital IT infrastructure requires custom middleware to connect radiology archives with print preparation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Medical Device Software Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,972.65 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Design Software, Simulation Software, Slicing Software, Monitoring Software Application: Orthopedics, Dental, Prosthetics, Surgical Instruments End User: Hospitals, Research Labs, Dental Clinics, OEMs Deployment: Cloud-Based, On-Premises, Hybrid, Mobile |
| Companies Covered | Stratasys Ltd, 3D Systems Corporation, Materialise NV, Nemotec, PS-Medtech, DWS Systems, Carima, Autodesk Inc, EOS GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Medical Device Software Market Emerging Trajectories
Computational platforms are evolving from isolated design tools into integrated quality systems that embed regulatory documentation directly within build preparation workflows.
Real-time thermal simulation with layer-resolution feedback is electrifying process control for titanium and cobalt-chrome orthopedic implants. Device manufacturers in Germany and Switzerland are adopting these modules to reduce build failure rates without physical iteration. The technology is compressing validation timelines from months to weeks for patient-specific spinal cages.
The EU AI Act's risk classification framework is reshaping software development priorities for generative design capabilities. Vendors must now embed explainability documentation and bias testing into algorithmic topology optimization. High-risk patient-specific implant applications face mandatory conformity assessments before commercial deployment.
Hospital procurement committees are unbundling software licenses from hardware service contracts, forcing vendors to demonstrate standalone clinical value. Academic medical centers in the Netherlands and Belgium are piloting per-case pricing for surgical planning modules. This shift is most visible in craniomaxillofacial reconstruction programs where case volumes fluctuate unpredictably.
3D Printing Medical Device Software Market Segmentation
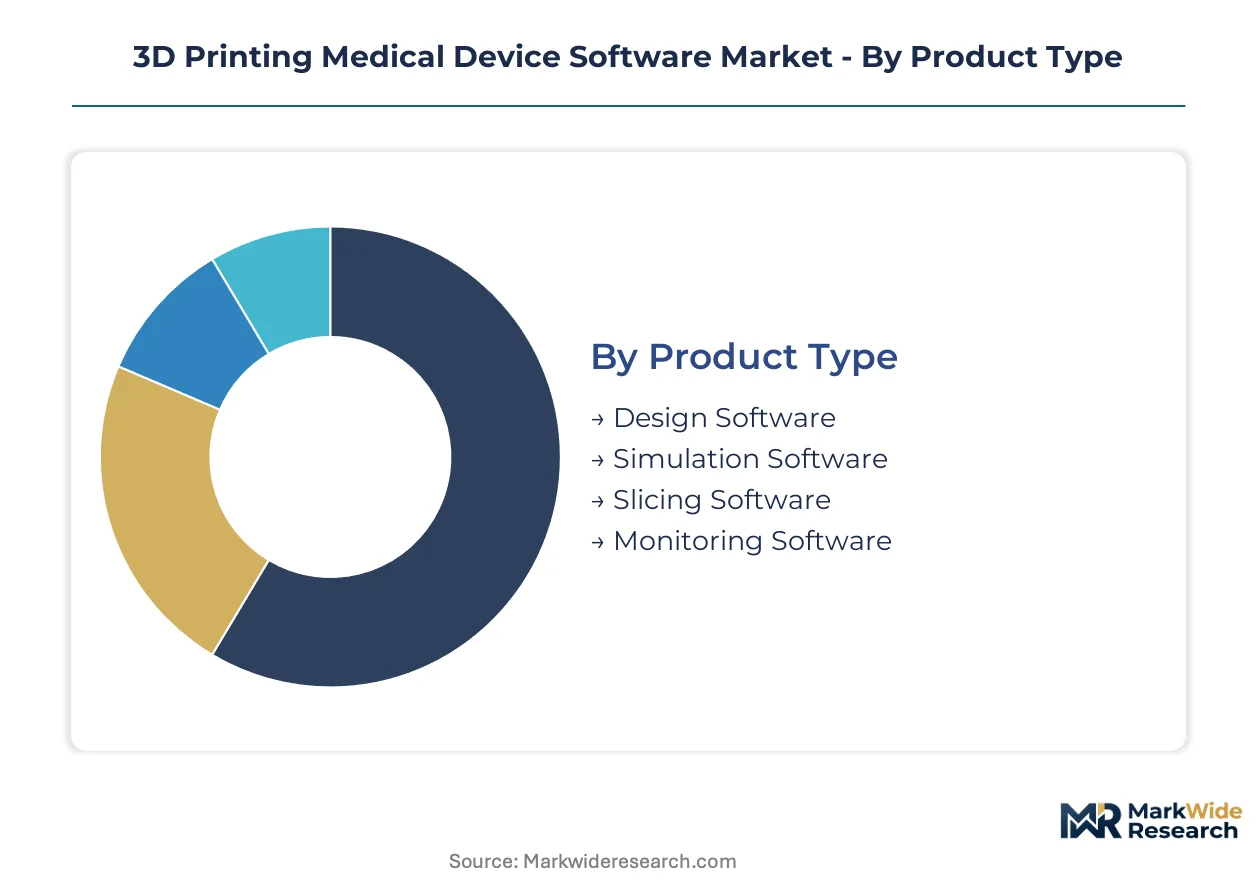
Software segmentation in medical additive manufacturing reveals distinct capital requirements, regulatory pathways, and customer acquisition economics. Each product category demands specialized engineering talent and certification investments that reshape competitive boundaries.
Product Type:
Capital intensity varies sharply across software layers, with simulation modules requiring the most substantial upfront investment in computational infrastructure and regulatory documentation.
- Design Software:Platforms converting DICOM imaging into printable mesh geometries through automated segmentation and topology optimization. German orthopedic implant manufacturers anchor demand here, driven by EU MDR mandates for patient-specific device documentation. Licensing models lock hospitals into recurring revenue streams through proprietary file formats.
- Simulation Software:Computational engines validating mechanical performance, thermal behavior, and biocompatibility through finite element analysis before physical builds. Swiss and German regulators now accept in-silico evidence for implant clearance, compressing validation timelines. This segment demands the heaviest investment in high-performance computing clusters and specialized biomedical engineering teams.
- Slicing Software:Layer-generation tools translating 3D models into machine-executable G-code with parameter control down to 20-micron resolution.
- Monitoring Software:Real-time build tracking systems capturing thermal signatures and dimensional accuracy during fabrication.
Design software absorbs the bulk of installed capacity; simulation software is expanding most quickly.
Application:
Clinical use cases stratify by surgical complexity, reimbursement pathways, and the volume of anatomical variation each presents.
- Orthopedics:Pre-surgical planning and patient-matched implant generation for joint reconstructions and spinal fusions. Academic medical centers in Germany and Switzerland mandate these platforms for complex cases, with procurement committees weighting material waste reduction under EU Green Deal criteria.
- Dental:Crown, bridge, and surgical guide fabrication from intraoral scan data. Smaller clinics in Spain and Italy are migrating from desktop to cloud-based deployment, expanding addressable market reach.
- Prosthetics:Socket design and limb component customization for amputee patients.
- Surgical Instruments:Patient-specific guides and sterilizable tool fabrication for craniomaxillofacial and orthopedic procedures.
Orthopedics commands the deepest software integration; dental applications are climbing the fastest as cloud deployment penetrates smaller practices.
End User:
Customer types diverge in procurement authority, technical staffing, and sensitivity to total cost of ownership versus per-case pricing.
- Hospitals:Integrated delivery networks with dedicated biomedical engineering departments and direct regulatory relationships. German university hospitals lead adoption, mandating pre-surgical planning software for complex reconstructions and driving integrated design-to-print procurement.
- Dental Clinics:Independent practices and small group networks prioritizing subscription flexibility over capital expenditure. Cloud-based slicing platforms are displacing perpetual licenses in Spain and Italy where case volumes fluctuate seasonally.
- Research Labs:Academic and clinical research institutions validating novel biomaterials and fabrication protocols.
- OEMs:Device manufacturers embedding software into vertically integrated production systems for orthopedic and dental implants.
Hospitals concentrate the highest-value contracts; dental clinics are gaining share fastest through subscription penetration.
Deployment:
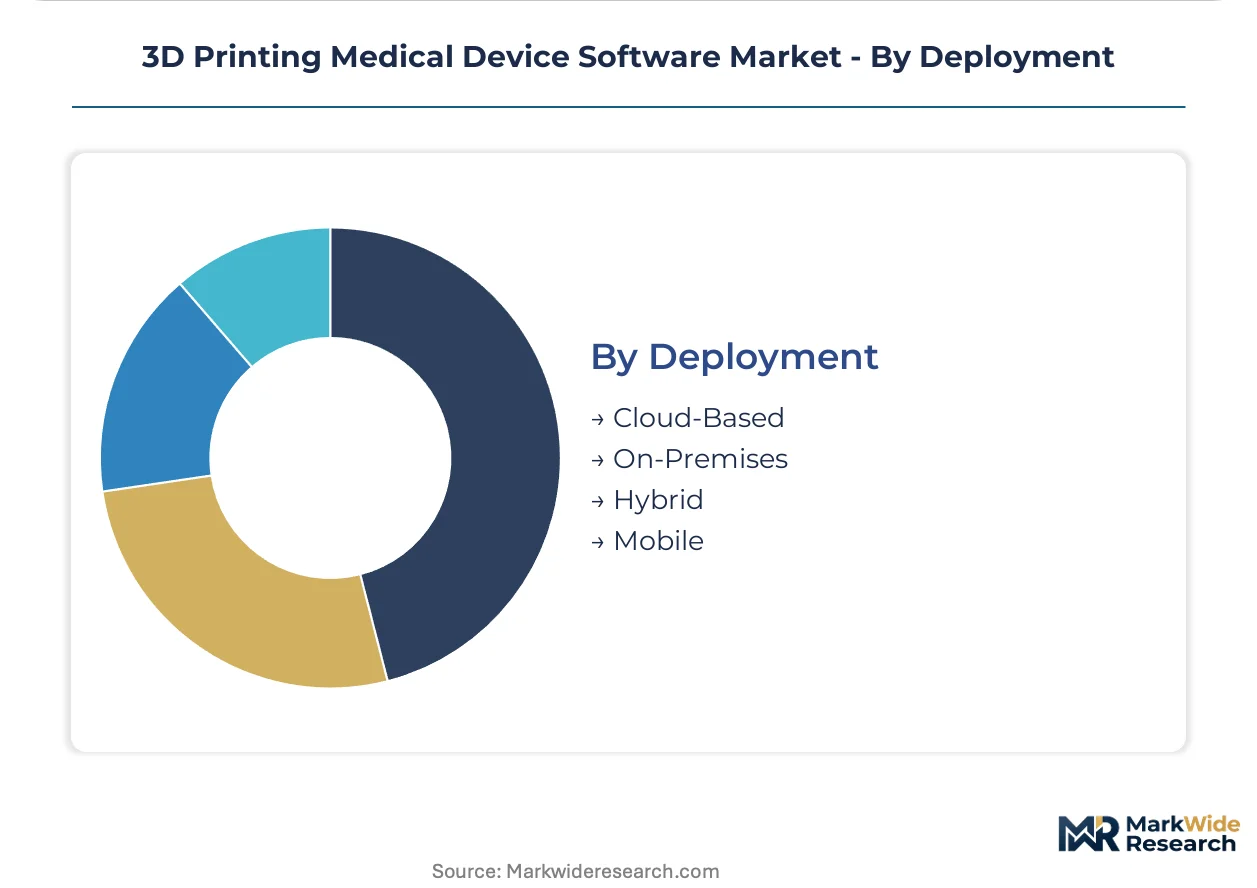
Infrastructure choices reflect data sovereignty requirements, IT staffing constraints, and the computational intensity of specific workflows.
- Cloud-Based:Browser-accessible platforms with elastic compute for simulation and centralized regulatory documentation. Spanish and Italian dental clinics are adopting these models to avoid server maintenance overhead.
- On-Premises:Locally installed systems maintaining full data control within hospital firewalls. German orthopedic centers favor this architecture for patient data protection compliance.
- Hybrid:Mixed deployments with sensitive design work on-premises and burst compute in cloud.
- Mobile:Tablet and smartphone interfaces for surgical review and case collaboration.
On-premises installations retain the largest installed base; cloud-based deployment is expanding most quickly among smaller clinical users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors the densest concentration of medical additive manufacturing expertise, where industrial clusters fuse orthopedic engineering with precision laser sintering capabilities.
Germany
University hospitals in Bavaria and Hamburg mandate pre-surgical planning software for complex joint reconstructions, compressing procurement cycles for integrated platforms. The EU MDR's software-as-medical-device classification forces vendors to embed ISO 13485-compliant audit trails directly into build preparation workflows. The Munich-Hamburg corridor concentrates the continent's deepest pool of biomedical engineering talent trained in computational geometry and regulatory science.
Switzerland
Swiss orthopedic manufacturers demand real-time thermal simulation modules to reduce titanium implant build failures without physical iteration. Swissmedic's streamlined software-as-medical-device pathway offers expedited market access for validated patient-specific planning tools. The Basel-Zurich region hosts specialized engineering teams focused on in-silico validation protocols that regulators now accept for mechanical clearance.
United States
The FDA's 510(k) pathway for patient-specific devices and emerging AI guidance is tightening validation requirements for generative design platforms. Academic medical centers in Massachusetts and California pilot per-case pricing models for craniomaxillofacial reconstruction software. The Boston-Cambridge cluster concentrates venture-backed startups developing automated lattice generation algorithms.
Netherlands
Dutch hospital procurement committees unbundle software licenses from hardware service contracts, forcing vendors to demonstrate standalone clinical value. The EU AI Act's risk classification framework mandates explainability documentation for algorithmic topology optimization in high-risk implant applications. The Eindhoven-Tilburg corridor specializes in PACS integration middleware connecting radiology archives with print preparation platforms.
Spain
Independent dental clinics in Madrid and Barcelona migrate from desktop to cloud-based slicing platforms to avoid server maintenance overhead. The EU Green Deal's procurement criteria weight material waste reduction, favoring topology optimization algorithms that minimize support structures. Catalonia's medical device ecosystem concentrates cloud deployment expertise for smaller practices with seasonal case volume fluctuations.
3D Printing Medical Device Software Market Vendor Landscape
The competitive structure tilts toward specialized software vendors with deep regulatory certification rather than diversified industrial conglomerates. Three archetypes dominate: design-to-print platform integrators, simulation engine specialists, and hardware-coupled slicing providers. Consolidation pressure concentrates among firms lacking ISO 13485 quality management coverage. Strategic moves center on embedding compliance documentation directly into software workflows and securing hospital procurement committee relationships ahead of hardware contract renewals.
Among European platform specialists, Materialise NV and EOS GmbH exemplify divergent competitive positions. Materialise NV anchors the design software tier through surgical planning workflow specialization. EOS GmbH occupies the hardware-coupled vector by controlling high-precision laser sintering parameters within integrated software stacks. Stratasys Ltd represents the polymer-focused archetype, extending hardware expertise into proprietary print preparation algorithms. Autodesk Inc sits within the broader design software category, leveraging cross-industrial computational geometry capabilities.
| Leading Market Players |
|---|
| Stratasys Ltd |
| 3D Systems Corporation |
| Materialise NV |
| Nemotec |
| PS-Medtech |
| DWS Systems |
| Carima |
| Autodesk Inc |
| EOS GmbH |
| Others |
Supply Flow & Price Mechanics
German hospital procurement committees mandating standalone software value demonstration are forcing vendors to unbundle licenses from hardware service contracts, compressing margins and accelerating cloud-based deployment models among smaller clinical buyers.
Pricing Analysis
Per-case throughput pricing anchors the market as Dutch academic medical centers pilot outcome-based models for craniomaxillofacial reconstruction modules. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 13485 certification depth and thermal simulation capability. Pricing pressure stems from dental clinics in Spain and Italy migrating to subscription slicing platforms. Independent practices exhibit highest price sensitivity; German university hospitals with dedicated biomedical engineering departments demonstrate lowest.
Supply Chain Analysis
High-performance computing infrastructure for finite element analysis rests on specialized semiconductor supply from Taiwan, Germany, and the United States. Software vendors draw from precision laser sintering hardware controlled by EOS GmbH, proprietary polymer systems from Stratasys Ltd, and DICOM-to-mesh conversion middleware developed in the Netherlands. Single-source vulnerability concentrates in laser sintering parameter control modules. Distribution runs through direct hospital procurement committees and dental clinic subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is becoming a vertical-integration race as platform vendors pursue upstream control over laser sintering parameter libraries to lock in hardware-software coupling.
For Market Incumbents: Anchor defensive positions by embedding ISO 13485 audit trails directly into build preparation workflows before hardware contract renewals expire. Deepen control over thermal simulation intellectual property to offset generative design-AI convergence threats from venture-backed entrants. Prioritize certification investment in Swissmedic fast-track pathways for expedited patient-specific planning tool clearance. For New Entrants and Emerging Players: Cloud-native deployment routes offer the most penetrable entry vector for Spanish and Italian dental clinics abandoning desktop installations. Target automated lattice generation algorithms for orthopedic implant applications where incumbent topology optimization platforms lack machine learning integration. Pursue per-case pricing pilots with Netherlands hospital procurement committees unbundling software from hardware contracts. For Investors and Strategic Acquirers: The window for entry favors simulation engine specialists with in-silico validation capabilities accepted by Swiss and German regulators. Long-term viability centers on platforms demonstrating standalone clinical value independent of hardware refresh cycles. Watch FDA artificial intelligence guidance intersection with generative design capabilities as the critical inflection signal for platform architecture commitments.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Embeds quality management documentation directly into software lifecycle processes for EU MDR compliance. |
| Cloud-Based Slicing Platform Launch | Captures seasonal dental clinic demand in Spain and Italy through subscription flexibility. |
| Thermal Simulation Module Acquisition | Compresses titanium implant validation timelines from months to weeks for German manufacturers. |
| Swissmedic Fast-Track Partnership | Expedites software-as-medical-device classification for patient-specific planning tools. |
| Generative Design-AI Integration | Automates implant lattice generation for orthopedic applications under EU AI Act risk frameworks. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, triangulated with primary interviews involving biomedical engineers, hospital procurement committee members, GPO contracts managers, and regulatory affairs specialists at orthopedic implant manufacturers. FDA 510(k) submissions, EU MDR technical documentation databases, Swissmedic classification rulings, and hospital procurement databases provided validation layers. Bottom-up sizing of software license deployments converged with top-down expenditure tracking across German, Swiss, and Dutch healthcare systems.
Granularity-level modeling captured deployment mode transitions, application-specific adoption curves, and end-user procurement authority structures across the projection horizon. Segmentation dimensions included product type, clinical application, customer archetype, and infrastructure architecture. CAGRs derived from elasticity-adjusted penetration rates and hardware refresh cycle timing. Industry-specific inputs encompassed EU AI Act implementation timelines and FDA emerging guidance on artificial intelligence in device software.
The model holds under stable regulatory classification frameworks; deviation in FDA AI guidance finalization or EU MDR enforcement intensity would shift vendor platform architecture commitments. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Ad Creation Software Market
Software & Services
Content Moderation Software Market
Software & Services
Automotive Dealer Management Systems (DMS) Market
Software & Services
Global Email Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Data Conversion Services Market
Software & Services
Reporter Systems Market
Software & Services
Avionics Software Market
Software & Services
ELD Compliance Software Market
Software & Services
Global Remote Work Software Market
Software & Services
Online Paint Editor App Market
Software & Services
Global Manufacturing Operations Management (MOM) Software Market
Software & Services
Design Collaboration Software Market
Software & Services
Asia-Pacific ERP Software Market
Software & Services
Point Cloud Processing Software Market
Software & Services
Camera Tracking Software Market