
 3D Printing Service Bureaus Market | 2026-2036
3D Printing Service Bureaus Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Service Bureaus Market Insights
Aerospace and healthcare procurement is rebalancing toward certified production runs rather than disposable prototypes. Xometry leverages its distributed manufacturing network to capture multi-industry quoting volume. Protolabs sustains rapid-turn injection molding and additive hybrid capacity for medical device validation. Materialise specializes in FDA-validated orthopedic implant printing through its proprietary software-to-build workflow.
3D Printing Service Bureaus operate as contract manufacturing intermediaries that convert digital CAD files into physical parts using layer-by-layer deposition, sintering, or photopolymerization processes with tolerances typically ranging from ±0.1 mm to ±0.3 mm depending on technology and material. Their primary commercial purpose is to eliminate capital equipment barriers for end users requiring low-to-medium volume, complex-geometry components without in-house additive infrastructure. Metal and plastic material categories dominate current revenue, with metal bureau capacity expanding fastest as aerospace and medical OEMs qualify titanium and nickel superalloy builds for flight-critical and implantable applications. Production service types now outpace prototyping in margin contribution at leading bureaus, reflecting a structural shift from design validation to serial manufacturing.
FDA quality system regulations and EU MDR requirements are mandating lot traceability and process validation for patient-contacting devices, which advantages bureaus with ISO 13485 certification and dedicated clean-room build environments. REACH and RoHS frameworks in Europe restrict certain polymer chemistries, pushing material suppliers and bureaus toward bio-based and recycled feedstock qualification. Stakeholders must monitor evolving FAA airworthiness criteria for additively manufactured structural components, as certification harmonization between regulators will determine which bureau networks can serve cross-border aerospace supply chains.
Market Dynamics
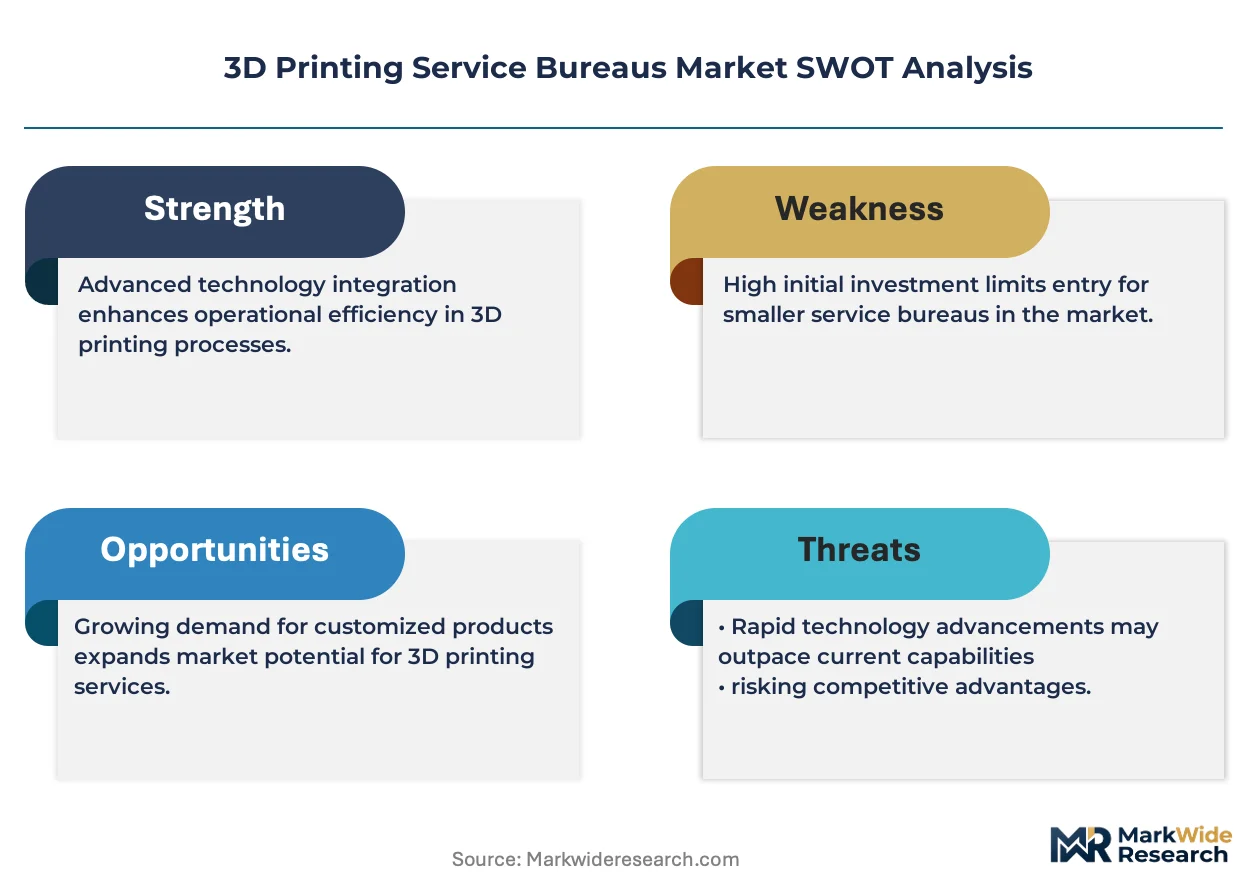
Aerospace and medical OEM procurement is rebalancing toward certified production runs, forcing bureau networks to absorb capital-intensive qualification costs that smaller operators cannot shoulder. This structural shift toward production-grade additive manufacturing is concentrating viable capacity among ISO 13485 and AS9100-certified facilities.
Growth Catalysts
- FDA Quality System Regulation:Mandated lot traceability for patient-contacting devices advantages bureaus with validated clean-room environments and dedicated quality management systems.
- Titanium and nickel superalloy builds:Flight-critical aerospace applications are qualifying metal additive for structural components, expanding addressable contract manufacturing spend.
- Germany:Densest cluster of certified bureau capacity in Europe attracts cross-border medical device and automotive prototyping demand from neighboring markets.
Market Restraints
- Powder feedstock cost volatility:Titanium and cobalt-chrome powder prices fluctuate with aerospace alloy demand, compressing margins on fixed-price production contracts.
- Build chamber equipment concentration:High-throughput metal systems from a limited supplier base create capacity bottlenecks during qualification surges.
- EU MDR compliance timeline:Extended validation periods for implantable device bureaus delay revenue recognition on new orthopedic contracts.
Strategic Opportunities
- India:Underpenetrated certified bureau capacity creates first-mover advantage for PLI scheme beneficiaries establishing medical device additive operations.
- Multi-material hybrid workflows:Convergence of polymer and metal deposition within single build jobs enables functional assembly consolidation for robotics OEMs.
- Digital inventory platforms:Distributed manufacturing networks are capturing spare parts demand from industrial equipment operators seeking on-demand replacement components.
Industry Challenges
- Process engineer scarcity:Qualified technicians for parameter optimization across laser powder bed fusion systems command premium compensation in Germany and the United States.
- AS9100 certification timeline:Eighteen-month qualification periods for aerospace production bureaus delay market entry and strain working capital reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Service Bureaus Market |
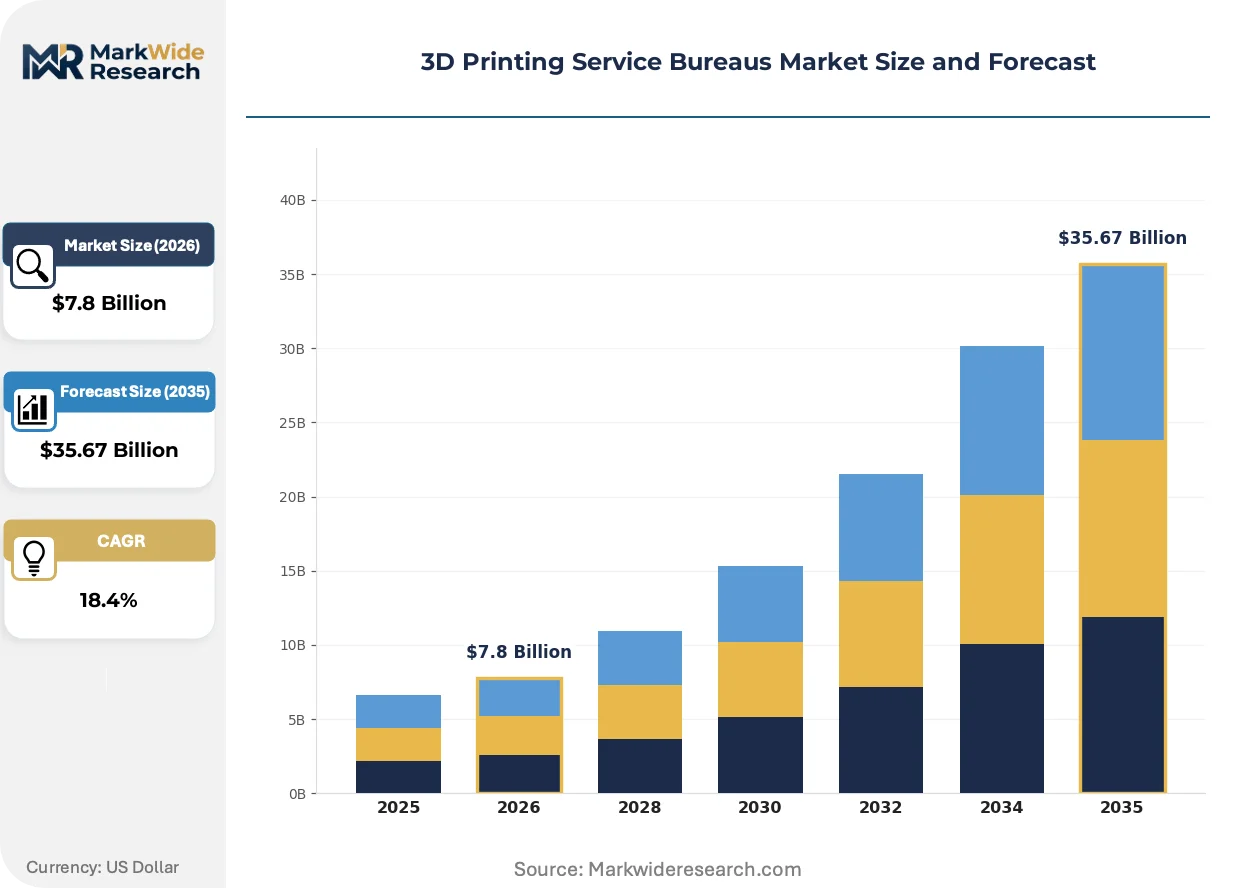
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $35.67 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Prototyping, Production, Design Assistance, Finishing Material Type: Plastic, Metal, Ceramics, Composites Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing End User: Aerospace, Automotive, Healthcare, Consumer Electronics |
| Companies Covered | Xometry, Protolabs, Stratasys Direct, 3D Systems, Materialise, Shapeways, Sculpteo, Unionfab, Fictiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Service Bureaus Market Trends and Innovations
Process automation and regulatory harmonization are compressing the gap between prototype validation and serial production. Three developments are restructuring how bureau capacity is deployed and monetized.
Multi-laser metal powder bed fusion is modularizing production economics for aerospace structural components. Tier-one suppliers are adopting these systems for medium-volume bracket and manifold runs. Build-chamber scalability is modularizing the traditional trade-off between prototyping agility and unit cost efficiency.
EU MDR lot traceability mandates are tightening material pedigree requirements across orthopedic implant supply chains. Bureaus must now maintain digital thread documentation from powder atomization through post-processing. European orthopedic OEMs are consolidating supplier panels to MDR-validated facilities with dedicated quality infrastructure.
Spare parts procurement for industrial machinery is migrating toward on-demand digital inventory models. Asset operators are disintermediating traditional warehousing networks in favor of certified bureau networks with guaranteed turnaround windows. German automotive and energy equipment manufacturers are piloting this shift for legacy tooling and obsolete component categories.
3D Printing Service Bureaus Market Segmentation
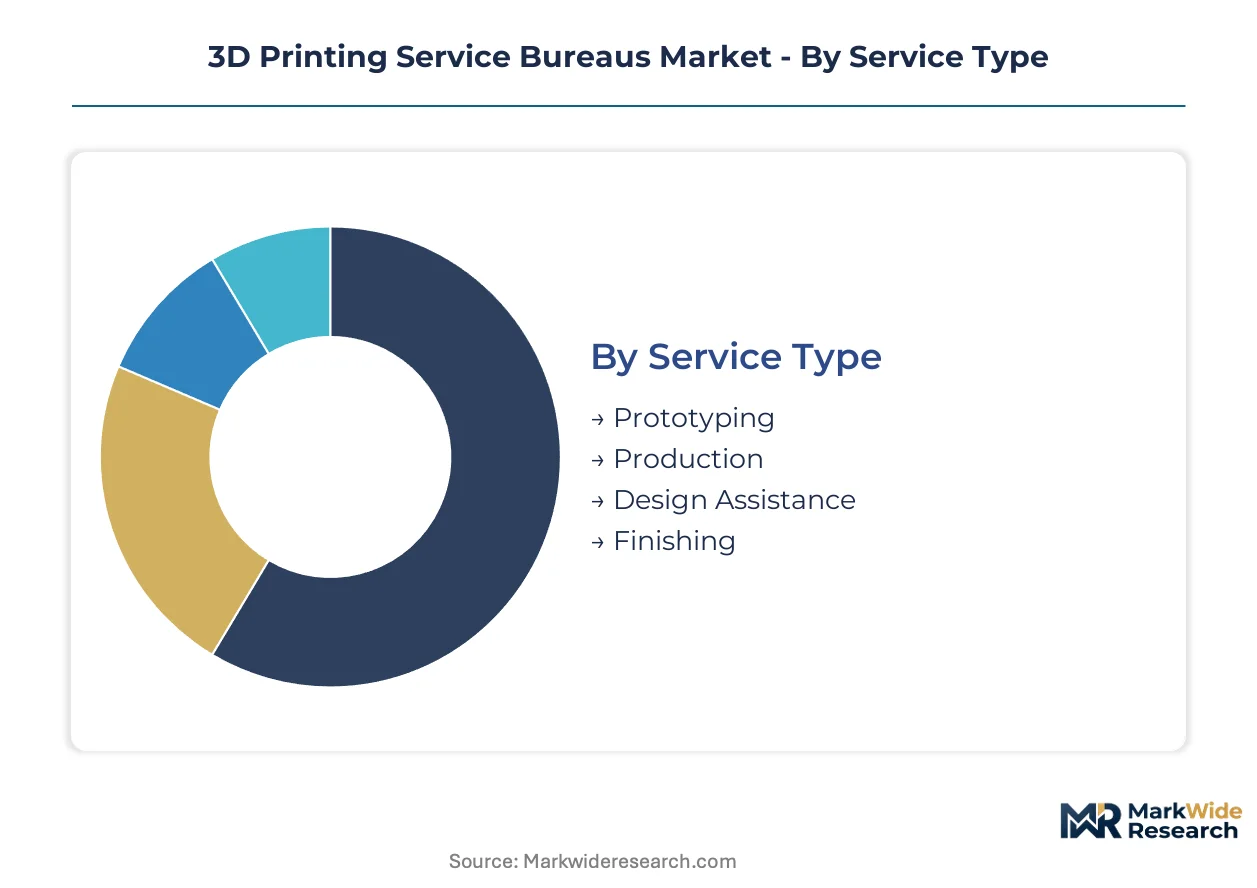
Segmentation in 3D printing service bureaus reveals how procurement priorities diverge between validation-focused buyers and serial manufacturers. Understanding these splits enables capacity planners to align equipment investments with margin concentration.
Service Type:
Volume concentration sits with repeat production contracts, while premium pricing attaches to specialized design and finishing workflows.
- Prototyping:Rapid-turn validation builds using polymer and metal technologies for design iteration cycles. Demand concentrates in German automotive and US medical device clusters where compressed development timelines dominate procurement criteria.
- Production:Certified serial manufacturing with AS9100 and ISO 13485-validated processes for flight-critical and implantable components. Aerospace OEMs in the United States and China are consolidating supplier panels toward bureaus with dedicated quality infrastructure and lot traceability systems.
- Design Assistance:Topology optimization and DfAM consulting for complex geometries.
- Finishing:Post-processing services including heat treatment, surface polishing, and coating application.
Mature deployment sits with Prototyping. Newer deployment is concentrated in Production.
Material Type:
Cost tier separation runs from commodity polymers through certified superalloys, with qualification requirements steepening at each level.
- Metal:Titanium, aluminum, nickel superalloy, and cobalt-chrome powders processed through laser powder bed fusion and directed energy deposition. Demand is climbing fastest in US and Chinese aerospace supply chains qualifying structural brackets and manifolds for flight-critical applications.
- Plastic:ABS, nylon, polycarbonate, and photopolymer resins for functional prototypes and end-use housings.
- Ceramics:Alumina, zirconia, and bioactive glass for dental and orthopedic applications requiring biocompatibility.
- Composites:Carbon fiber-reinforced polymers and continuous fiber deposition for lightweight structural components.
Established revenue concentration rests with Plastic. Steepest expansion trajectory belongs to Metal.
Technology:
Application requirements dictate technology selection, with tolerance demands and surface finish specifications driving equipment mix decisions.
- Selective Laser Sintering:Polymer powder bed fusion producing durable nylon components with isotropic mechanical properties. Healthcare procurement in Germany favors SLS for patient-specific surgical guides requiring sterilization compatibility.
- Fused Deposition Modeling:Thermoplastic extrusion systems offering lowest cost per part for large-format tooling and fixtures.
- Stereolithography:Photopolymer vat polymerization delivering finest feature resolution for microfluidic devices and dental models.
- Digital Light Processing:Projector-based photopolymer curing enabling faster throughput than SLA for jewelry and hearing aid shell production.
Volume leadership belongs to Fused Deposition Modeling. Margin expansion concentrates in Selective Laser Sintering.
End User:
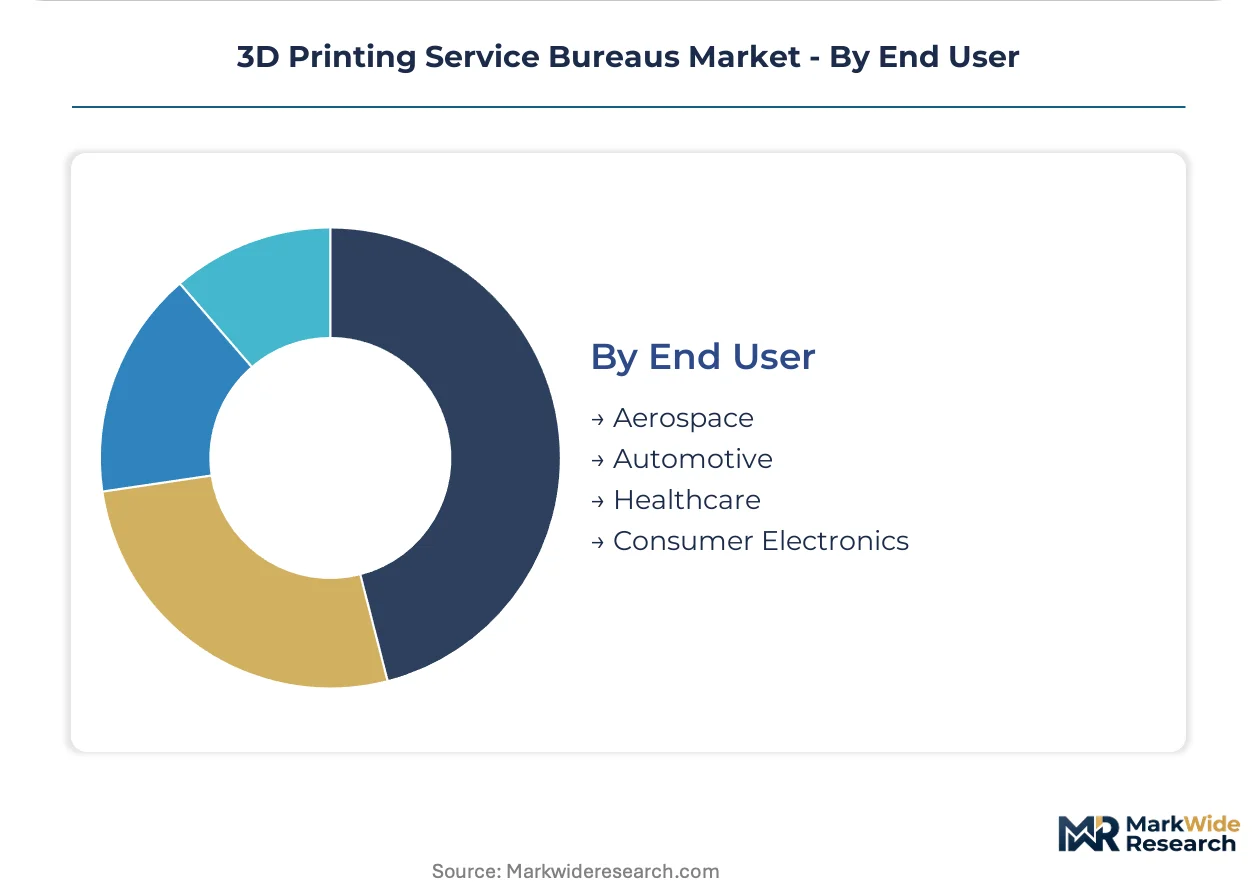
Customer type determines certification burden, with regulated industries commanding premium pricing for validated supply chains.
- Healthcare:Patient-specific implants, surgical instruments, and anatomical models requiring FDA and EU MDR compliance. German and US orthopedic OEMs are consolidating supplier panels to bureaus with ISO 13485 certification and clean-room build environments.
- Aerospace:Structural brackets, ducting, and engine components subject to FAA airworthiness criteria.
- Automotive:Prototyping and low-volume tooling for powertrain and interior component validation.
- Consumer Electronics:Enclosure prototypes and custom accessories with compressed turnaround requirements.
Regulatory intensity peaks in Healthcare. Procurement scale concentrates in Aerospace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany, the United States, and China concentrate certified bureau capacity through targeted tax incentives and streamlined regulatory pathways for aerospace and medical device production.
United States
Aerospace OEMs in Texas and California are consolidating supplier panels toward AS9100-certified bureaus with dedicated quality infrastructure for flight-critical titanium builds. FAA airworthiness criteria for additively manufactured structural components are tightening process validation requirements. The Greater Boston cluster anchors medical device additive operations with FDA-validated clean-room environments serving orthopedic implant manufacturers.
Germany
Automotive prototyping demand from Bavarian OEMs intersects with cross-border medical device work from neighboring EU markets seeking ISO 13485-certified capacity. EU MDR lot traceability mandates are forcing material pedigree documentation from powder atomization through post-processing. The Baden-Württemberg region hosts Europe's densest cluster of certified bureau capacity, attracting orthopedic OEM supplier consolidation.
China
Domestic aerospace supply chains are qualifying nickel superalloy builds for engine components under MIIT industrial additive manufacturing directives. NMPA medical device regulations are aligning with international quality system standards for implantable device bureaus. The Yangtze River Delta concentration spans Shanghai and Jiangsu province, where bureau networks serve robotics OEMs with multi-material hybrid workflows.
India
Underpenetrated certified bureau capacity creates positioning opportunity for PLI scheme beneficiaries establishing medical device additive operations. CDSCO quality system requirements for patient-contacting devices are mandating dedicated clean-room infrastructure that advantages early entrants. The Maharashtra-Gujarat industrial corridor is attracting initial investments in titanium and cobalt-chrome powder bed fusion capacity for orthopedic implant contract manufacturing.
Japan
PMDA medical device regulations are converging with ISO 13485 standards for implantable device bureaus serving domestic orthopedic OEMs. METI industrial policy is subsidizing metal additive qualification for aerospace tier-one suppliers. The Nagoya-Chubu region concentrates precision manufacturing expertise that bureau operators are leveraging for parameter optimization across laser powder bed fusion systems.
3D Printing Service Bureaus Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with distributed networks capturing multi-industry quoting volume while integrated fabricators retain premium-tier medical and aerospace certification work. Three archetypes dominate: platform-based aggregators with distributed supplier networks, vertically integrated specialists with captive equipment fleets, and hybrid operators combining rapid-turn prototyping with validated production capacity. Consolidation pressure favors players absorbing capital-intensive qualification costs that smaller operators cannot shoulder, while strategic partnerships between material suppliers and bureau operators accelerate feedstock qualification timelines.
Among US-based platform operators, Xometry and Fictiv exemplify the aggregator archetype by connecting digital demand with distributed manufacturing capacity across multiple technologies and material categories. Materialise anchors the specialist tier with proprietary software-to-build workflows and FDA-validated orthopedic implant printing operations. These three companies occupy distinct competitive positions: platform scale, software-integrated specialization, and rapid-turn hybrid capacity respectively.
| Leading Market Players |
|---|
| Xometry |
| Protolabs |
| Stratasys Direct |
| 3D Systems |
| Materialise |
| Shapeways |
| Sculpteo |
| Unionfab |
| Fictiv |
| Others |
Pricing and Supply Chain Analysis
Titanium powder spot indices cascade through bureau pricing tiers, compressing margins on fixed-rate aerospace contracts while amplifying premiums for AS9100-validated capacity with guaranteed lead times. Powder feedstock volatility feeds directly into contract structures, separating bureaus with long-term alloy offtake agreements from spot-market exposed operators.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with same-turnaround builds commanding substantial markups over standard-queue orders. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with ISO 13485-validated medical builds pricing furthest from commodity prototyping. Cost compression in metal powder bed fusion is intensifying as build-chamber equipment concentration limits throughput expansion. Automotive prototyping buyers exhibit highest price sensitivity, while orthopedic OEMs prioritize lot traceability over unit cost.
Supply Chain Analysis
Freight costs for titanium and nickel superalloy powders from Germany, the United States, and China anchor landed feedstock expenses at destination bureaus. Powder atomization capacity concentrates among a limited supplier base in these three markets, creating single-source vulnerability for cobalt-chrome and specialized aerospace alloys. Tariff exposure on Chinese-origin metal powders is forcing European bureaus toward domestic feedstock qualification. Distribution runs through certified bureau networks with validated logistics chains, bypassing traditional distributor intermediaries for flight-critical and implantable components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story. FDA Quality System Regulation and EU MDR requirements erect barrier-to-entry moats that concentrate viable capacity among certified operators with dedicated quality infrastructure.
For Market Incumbents: To counter powder feedstock cost volatility, deepen backward integration into long-term alloy offtake agreements with German and US atomization suppliers. Absorb capital-intensive AS9100 and ISO 13485 qualification costs that strain smaller competitors, consolidating supplier panels through guaranteed turnaround windows and digital thread documentation capabilities. For New Entrants and Emerging Players: Industrial equipment operators seeking on-demand spare parts represent an underserved buyer archetype with compressed certification requirements relative to medical and aerospace segments. India's underpenetrated certified bureau capacity offers white-space positioning for PLI scheme beneficiaries establishing titanium powder bed fusion operations. Target digital inventory platform partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with captive AS9100-certified metal capacity in Germany and the United States, where process engineer scarcity sustains pricing power. Long-term viability hinges on regulatory harmonization between FAA, EASA, and CAAC airworthiness criteria. Monitor NMPA alignment with international quality system standards as the inflection signal for Chinese medical device additive market entry.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Investment | Opens flight-critical titanium build contracts with Boeing and Airbus tier-one suppliers. |
| Multi-Laser Metal System Deployment | Modularizes production economics for medium-volume aerospace bracket and manifold runs. |
| Digital Thread Documentation Platform | Enables EU MDR lot traceability compliance for orthopedic implant supply chains. |
| Long-Term Powder Feedstock Agreement | Insulates margins from titanium spot price volatility in fixed-rate production contracts. |
| Clean-Room Build Environment Expansion | Supports FDA-validated medical device operations for patient-contacting implantables. |
Research Methodology
Trade publications, aerospace alloy pricing databases, and medical device regulatory filings formed the secondary backbone for market sizing and competitive mapping. Primary interviews with bureau operations directors, orthopedic OEM procurement managers, aerospace tier-one supplier quality engineers, and powder metallurgy specialists validated capacity estimates and qualification timelines. Bottom-up equipment installation counts and top-down contract manufacturing spend analysis were triangulated against build-chamber utilization rates.
Historical trendline analysis of metal powder bed fusion capacity additions and certification timelines informed the projection framework. Segmentation dimensions modeled include service type, material category, technology platform, end-use industry, and geographic regulatory cluster. CAGRs were derived from equipment shipment forecasts cross-referenced with OEM contract manufacturing outsourcing intentions. Forecast inputs incorporated FAA airworthiness criteria evolution and EU MDR validation period extensions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory harmonization between aviation authorities and powder feedstock supply disruptions. Forecasts reflect documented assumptions regarding certification timeline stability and alloy demand from adjacent aerospace markets. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
Military 3D and 4D Printing Market
3D Printing Technology
Global 3D Printed Electronics Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
Asia-Pacific Industrial 3D Printing Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
Additive Manufacturing Platform Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
North America Additive Manufacturing Market
3D Printing Technology
3D Concrete Printers Market