
 3D Printing Materials and Equipment Market | 2026-2036
3D Printing Materials and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Materials and Equipment Market Insights
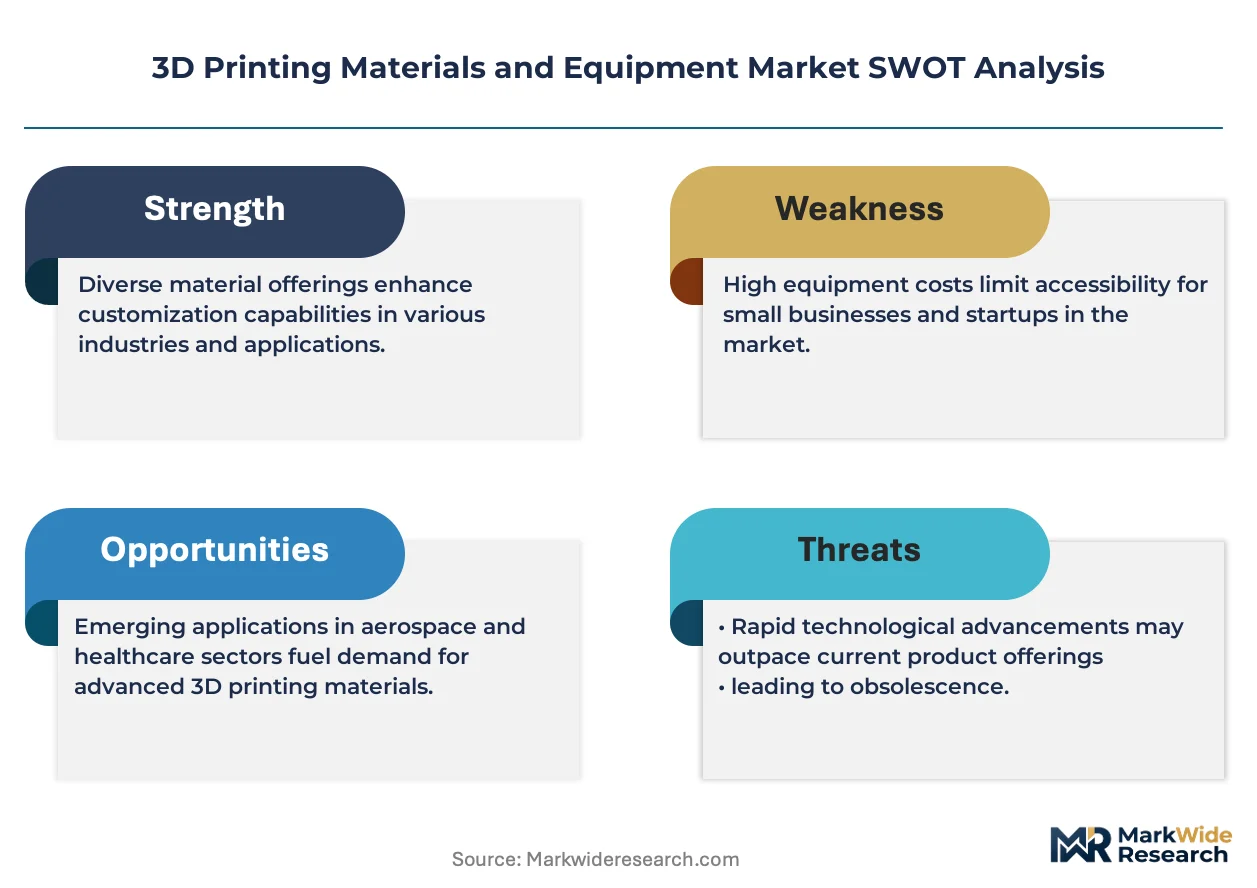
Aftermarket service revenue is narrowing as equipment vendors bundle predictive maintenance into hardware contracts. EOS GmbH dominates powder-bed metal systems for aerospace qualification. Stratasys Ltd anchors polymer FDM and PolyJet platforms across healthcare and automotive prototyping. Materialise NV extends software-to-manufacturing workflows that control build preparation and quality traceability.
3D printing materials and equipment encompasses photopolymer resins, thermoplastic filaments, metal powders, and sintering or fusion systems that deposit, cure, or melt feedstock layer-by-layer to net-shape tolerances of 50-200 microns. The primary purpose is to eliminate tooling lead times and enable topology-optimized geometries for low-volume production and functional prototyping. FDM technology sustains the largest installed base due to low capital thresholds, yet SLS powder systems capture higher margins in industrial end-use manufacturing. Aerospace and healthcare applications lead adoption where part consolidation and patient-specific geometries justify qualification costs.
FDA 510(k) clearance pathways govern medical device additive manufacturing in the United States, while EMA MDR frameworks impose biocompatibility and traceability standards across European markets. China's NMPA and GB standards now require domestic registration for metal powder compositions used in implantable devices. Stakeholders must monitor evolving material qualification databases and harmonize quality systems across jurisdictions before scaling production footprints.
Market Dynamics
Flight-certification protocols for polymer and metal additive parts are compressing aerospace procurement cycles while forcing material vendors to rebuild qualification databases around traceable batch records rather than conventional lot testing.
Growth Catalysts
- Aerospace qualification pipelines:FAA certification pathways for flight-critical polymer brackets and titanium structural nodes are accelerating production adoption at Boeing and Airbus tier suppliers. EOS powder-bed systems now dominate this qualification workflow.
- EU MDR traceability mandates:European medical device regulation is forcing implant manufacturers to adopt serialized powder tracking from atomization through sterilization, pulling software-to-manufacturing platforms into compliance architectures.
- Topology optimization software:Generative design tools from Autodesk and Siemens are generating lattice geometries impossible to mill conventionally, creating pull-through demand for metal powder-bed capacity in automotive lightweighting programs.
Market Restraints
- Titanium powder cost volatility:Sponge input prices fluctuate with aerospace mill demand cycles, compressing margins for implant manufacturers locked into fixed-price hospital contracts.
- Machine OEM concentration:Powder-bed fusion hardware relies on single-source electron beam gun assemblies from German and Japanese suppliers, creating vulnerability in build chamber uptime guarantees.
- Post-processing bottleneck:Support removal and hot isostatic pressing add 40-60% to effective part cost, limiting addressable markets to geometries where conventional machining is truly impossible.
Strategic Opportunities
- India medical implant localization:CDSCO registration pathways and PLI scheme incentives are attracting powder atomization investments to serve domestic hip and knee replacement demand.
- Ceramic matrix composite nozzles:Silicon carbide printing for hypersonic thermal protection systems represents white-space application with no incumbent supply chain.
- Digital inventory platforms:Spare part file repositories are enabling distributed manufacturing networks that compress logistics lead times for obsolete aerospace brackets.
Industry Challenges
- Process engineer scarcity:Qualified technicians who can interpret thermal camera data and adjust laser parameters mid-build command premium wages that inflate operating costs at contract manufacturers.
- Multi-jurisdictional qualification:FDA 510(k), EMA MDR, and NMPA GB standards require parallel but non-identical validation studies, stretching R&D budgets for implantable device startups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Materials and Equipment Market |
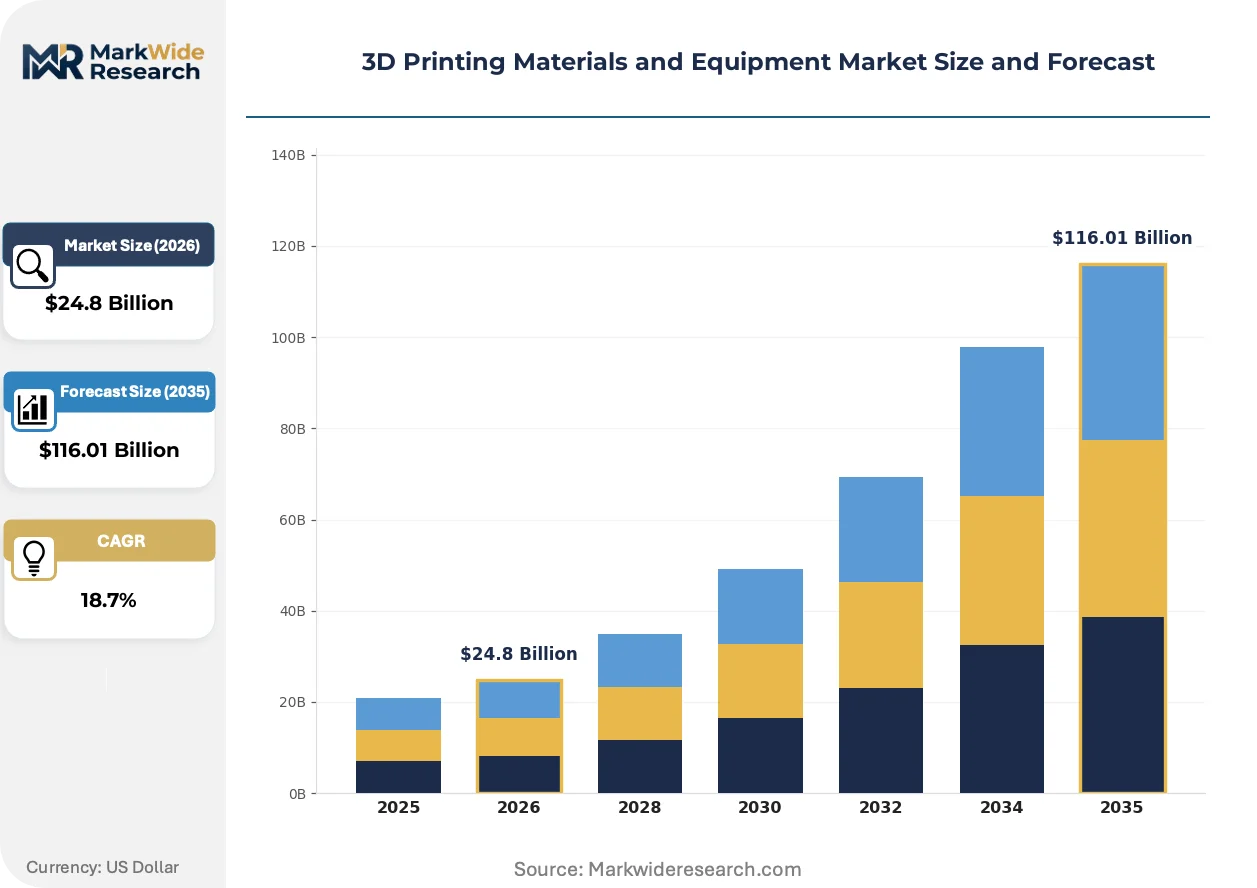
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $116.01 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, ABS, Nylon, TPU Technology: FDM, SLA, SLS, DLP Application: Aerospace, Automotive, Healthcare, Education End User: Consumer, Professional, Industrial, Hobbyist |
| Companies Covered | Stratasys Ltd, 3D Systems Inc, EOS GmbH, HP Development Company, SLM Solutions, Materialise NV, Evonik Industries AG, Höganäs AB, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Materials and Equipment Market Trends and Innovations
Digital thread architectures are collapsing the boundary between design software and shop-floor execution, enabling real-time parameter adjustment based on in-situ melt pool monitoring rather than post-build inspection.
Multi-laser powder-bed fusion is virtualizing the throughput limitations that previously constrained metal additive to prototyping volumes. Aerospace tier suppliers now deploy twelve-laser systems for satellite bracket serial production, compressing per-part cycle times from days to hours while maintaining flight-critical porosity specifications.
REACH substance restrictions on nickel powder classifications are forcing European material suppliers to reformulate 718 superalloy compositions. Atomization vendors are shifting to nitrogen atomization protocols that reduce chromium oxidation, though this requires recertification of existing aerospace part numbers under EASA amended type certificates.
Hospital procurement committees now demand FDA 510(k) clearance documentation before considering patient-specific cutting guides, compressing vendor selection to firms with established regulatory dossiers. This certification-driven preference shift favors incumbents with multi-year quality databases over emerging competitors offering price discounts, particularly in US orthopedic centers.
3D Printing Materials and Equipment Market Segmentation
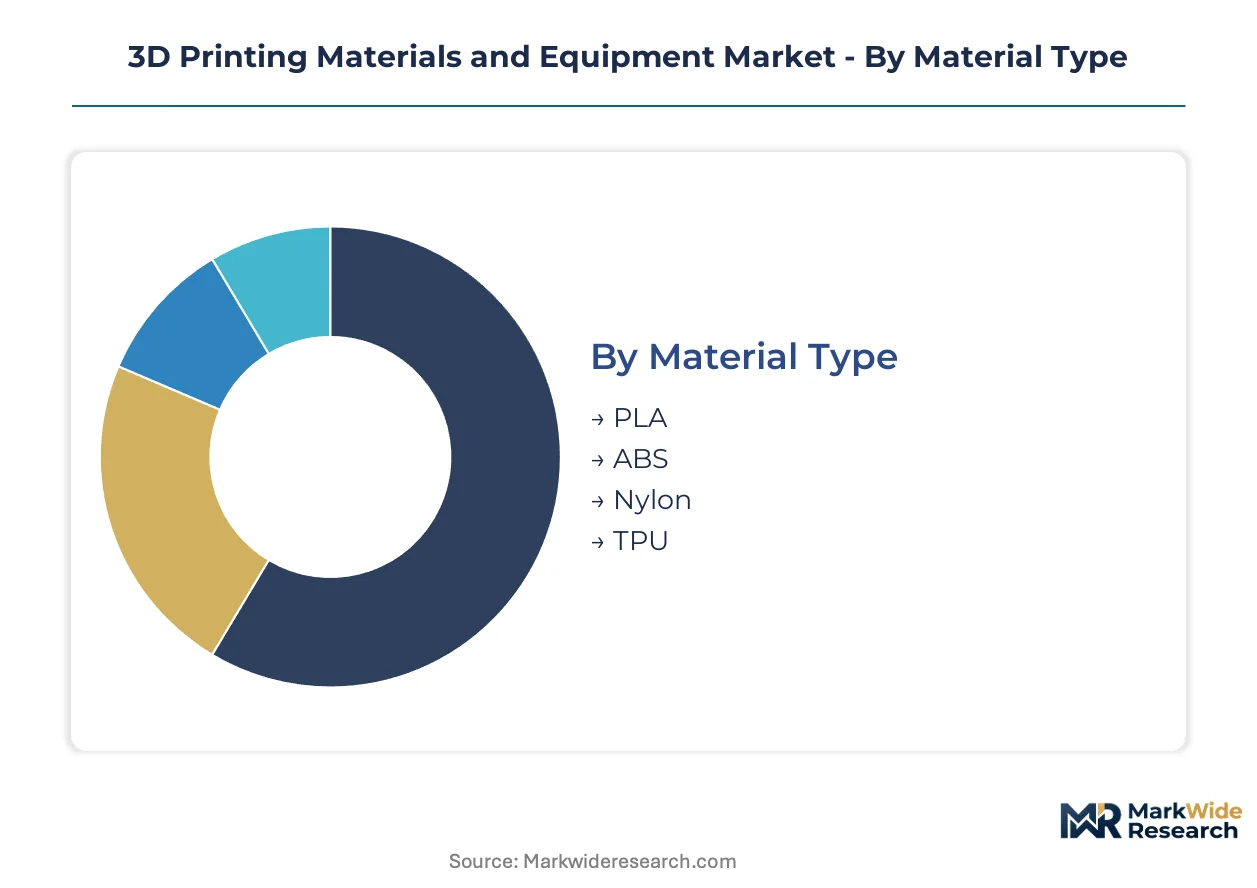
Material selection dictates build chamber specifications and post-processing workflows across aerospace certification and patient-specific healthcare applications. Technology segmentation separates low-cost prototyping from flight-critical metal fusion systems with distinct capital intensity and regulatory burdens.
Material Type:
Biodegradable polymers dominate educational entry points while engineering thermoplastics capture industrial load-bearing applications.
- PLA:Corn-starch derived polyester prints at low temperatures without heated beds, making it the default for classroom makerspaces and consumer desktop systems across Germany and the United States. Demand concentrates in educational procurement cycles tied to STEM curriculum mandates, though brittleness limits functional prototyping.
- ABS:Acrylonitrile butadiene styrene delivers impact resistance and acetone vapor smoothing for automotive interior trim prototypes and consumer electronics housings. German automotive tier suppliers specify ABS for dashboard component validation ahead of injection molding tooling commits.
- Nylon:Polyamide variants absorb moisture and resist abrasion in functional gears and living hinges.
- TPU:Thermoplastic polyurethane enables flexible lattice structures for orthopedic insoles and drone vibration dampeners.
The dominant share belongs to PLA, while TPU is closing the gap fastest.
Technology:
Capital thresholds stratify adoption from desktop hobbyists to qualified aerospace production cells.
- FDM:Fused deposition modeling extrudes thermoplastic filament through heated nozzles, sustaining the largest installed base due to sub-thousand-dollar hardware entry points. Automotive prototyping shops in Michigan and Bavaria deploy FDM for full-scale concept models before committing to CNC machining.
- SLA:Stereolithography cures photopolymer resin with ultraviolet lasers, delivering surface finishes below 25 microns for dental aligner molds and jewelry master patterns. Demand clusters in Shenzhen dental labs serving export markets with same-day turnaround requirements.
- SLS:Selective laser sinters nylon powder without support structures, enabling complex geometries for aerospace ducting.
- DLP:Digital light processing projects entire layer images simultaneously, accelerating dental crown production.
FDM retains volume leadership, though SLS commands the steepest expansion trajectory in industrial end-use manufacturing.
Application:
Regulatory burden and part criticality separate qualification-intensive sectors from rapid prototyping environments.
- Aerospace:Flight-certified brackets and engine components require EASA and FAA material traceability from atomization through heat treatment. EOS powder-bed systems dominate this workflow at Airbus and Boeing tier suppliers near Hamburg and Seattle.
- Automotive:Topology-optimized suspension nodes and custom tooling fixtures leverage metal additive for low-volume motorsport variants. Porsche and BMW deploy multi-laser systems at their Zuffenhausen and Munich development centers.
- Healthcare:Patient-specific surgical guides and cranial implants demand FDA 510(k) or EMA MDR clearance with serialized powder tracking.
- Education:University engineering programs and secondary school makerspaces drive filament consumption without qualification requirements.
Aerospace captures the highest value per kilogram, while healthcare is gaining share fastest through implant personalization.
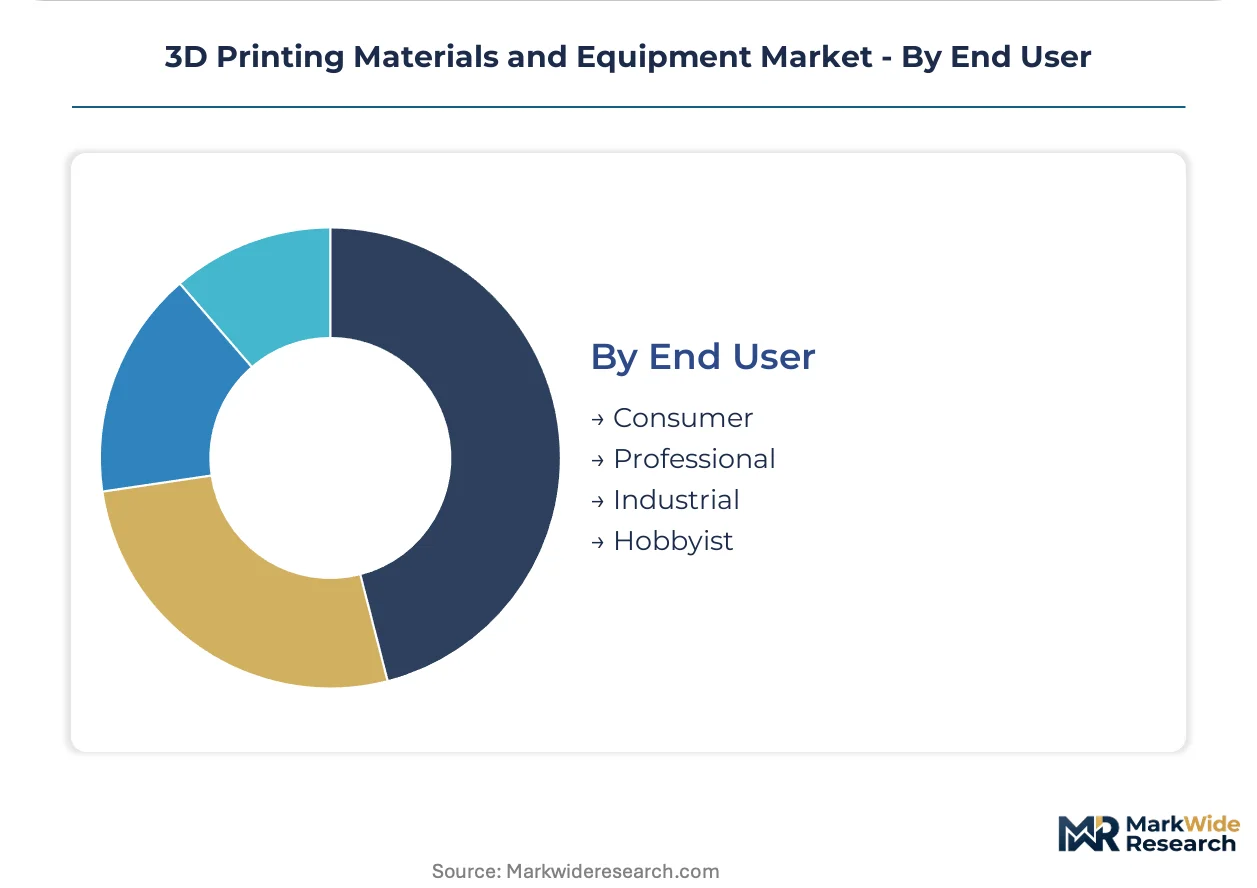
End User:
Technical sophistication and procurement authority segment hardware and material demand across price-performance tiers.
- Consumer:Desktop FDM systems under five hundred dollars serve home hobbyists printing decorative objects and replacement household parts. Chinese brands dominate this channel through direct-to-consumer e-commerce.
- Professional:Design studios and architectural firms operate mid-range SLA and FDM systems for client presentation models. Demand concentrates in London, New York, and Tokyo creative districts.
- Industrial:Contract manufacturers and OEM production cells operate qualified metal powder-bed systems with predictive maintenance contracts.
- Hobbyist:Enthusiast communities drive filament variety demand through online forums and open-source design repositories.
Industrial end users generate the dominant revenue share, while professional adoption is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes metal powder-bed systems for flight-certified aerospace production while the United States deploys polymer platforms across patient-specific healthcare workflows, creating divergent equipment-mix patterns across major demand centers.
United States
FDA 510(k) clearance pathways govern medical device additive manufacturing, with hospital procurement committees demanding serialized documentation for patient-specific cutting guides. Boeing and Airbus tier suppliers near Seattle operate EOS powder-bed systems for titanium structural node qualification under FAA protocols.
Germany
REACH substance restrictions and EASA amended type certificates are forcing 718 superalloy reformulation among atomization vendors concentrated around Munich and Nuremberg. Porsche and BMW deploy multi-laser systems at Zuffenhausen and Munich development centers for topology-optimized suspension nodes.
China
NMPA and GB standards now require domestic registration for metal powder compositions used in implantable devices, pulling software-to-manufacturing platforms into compliance architectures. Shenzhen dental labs drive SLA demand for same-day aligner mold turnaround serving export markets.
India
CDSCO registration pathways and PLI scheme incentives are attracting powder atomization investments to serve domestic hip and knee replacement demand. Contract manufacturers face acute process engineer scarcity as qualified technicians command premium wages for thermal camera interpretation and laser parameter adjustment.
Japan
METI industrial policy supports metal additive adoption for automotive lightweighting programs, with generative design tools from domestic software vendors creating pull-through demand for powder-bed capacity. JIS standards govern material qualification protocols for aerospace bracket serial production.
3D Printing Materials and Equipment Market Competitive Landscape
Capability concentration sits with powder-bed fusion specialists holding aerospace qualification databases; scale advantage sits with polymer platform vendors serving prototyping volumes across healthcare and automotive. The vendor base stratifies into three tiers: flight-certified metal system providers, mid-range professional equipment suppliers, and desktop filament extrusion manufacturers. Dominant competitive moves include predictive maintenance bundling into hardware contracts and software-to-manufacturing workflow integration.
Within the flight-certification tier, EOS GmbH and SLM Solutions exemplify capability concentration around traceable batch records and EASA-compliant qualification databases. Stratasys Ltd occupies a position spanning polymer FDM and PolyJet platforms across healthcare prototyping and automotive concept validation. Materialise NV anchors the software-to-manufacturing workflow segment, controlling build preparation and quality traceability architectures required by EU MDR mandates.
| Leading Market Players |
|---|
| Stratasys Ltd |
| 3D Systems Inc |
| EOS GmbH |
| HP Development Company |
| SLM Solutions |
| Materialise NV |
| Evonik Industries AG |
| Höganäs AB |
| Arkema |
| Others |
Pricing and Supply Chain Analysis
Titanium sponge price volatility determines both the spread between aerospace-grade and industrial-grade powder pricing and the geographic configuration of atomization capacity. Buyers locked into long-term hospital contracts for hip implants absorb cost swings that contract manufacturers cannot pass through, forcing supply chain consolidation around vertically integrated powder producers.
Pricing Analysis
Long-term offtake contracts dominate aerospace powder procurement, with Boeing and Airbus tier suppliers securing eighteen-to-twenty-four-month price locks for Ti-6Al-4V feedstock. Price differentiation hinges on EASA/FAA certification tier and lot-traceability documentation depth. Cost compression in dental-grade titanium powders is intensifying because Chinese atomization capacity is expanding faster than aligner mold demand. Hospital procurement committees exhibit the lowest price sensitivity due to patient-outcome liability, while consumer desktop filament buyers drive aggressive supplier switching.
Supply Chain Analysis
Contract manufacturing concentration sits with German powder-bed specialists near Munich and Nuremberg, plus emerging Chinese electron beam system integrators in Xi'an and Beijing. The supply chain draws from Ukrainian titanium sponge, Chinese rare earth magnet components, and Japanese electron beam gun assemblies. Single-source vulnerability concentrates in electron beam emitter supply from two Japanese precision manufacturers. Distribution runs through OEM direct sales for industrial systems and Alibaba/Tmall channels for consumer filament.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as patient-specific implant demand splinters production into micro-batches that disqualify mass-scale manufacturers. Hospital procurement committees now demand serialized powder tracking that only software-integrated vendors can deliver.
For Market Incumbents: Harden regulatory dossiers against emerging software-to-manufacturing competitors by accelerating FDA 510(k) submissions for next-generation lattice structures. Acquire captive atomization capacity in India to neutralize titanium sponge tariff exposure. Deepen backward integration into nitrogen atomization protocols before REACH reformulation mandates take full effect.
For New Entrants and Emerging Players: Establish a beachhead in ceramic matrix composite nozzles for hypersonic thermal protection, a white-space application with zero incumbent qualification databases. Target India's CDSCO-registered implant market where process engineer scarcity has stalled local production scale-up. Lead with distributed digital inventory platforms that compress logistics lead times for obsolete aerospace brackets.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated powder-to-part specialists with multi-jurisdictional qualification dossiers. Long-term viability over the next decade hinges on regulatory data moats rather than hardware differentiation. Watch for inflection when hospital GPOs mandate serialized powder tracking as a contract prerequisite.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Bundling | Hardware vendors lock in recurring revenue by embedding thermal camera monitoring and laser parameter optimization into EOS and SLM Solutions contracts. |
| Software-to-Manufacturing Integration | Materialise NV and competitors control EU MDR traceability architectures that hospital procurement committees now require for implant sourcing. |
| Multi-Laser Capacity Expansion | Aerospace tier suppliers deploy twelve-laser systems at Airbus and Boeing facilities to compress satellite bracket cycle times from days to hours. |
| India Atomization Investment | CDSCO registration pathways and PLI scheme incentives attract powder production to serve domestic hip and knee replacement demand. |
| REACH Reformulation Compliance | European atomization vendors shift to nitrogen protocols for 718 superalloy to meet EASA amended type certificate requirements. |
Research Methodology
Initial hypotheses were tested against primary input from additive manufacturing process engineers, hospital biomedical procurement managers, aerospace tier supplier quality directors, and powder atomization plant managers and refined through secondary validation against FAA certification databases, EMA MDR submission filings, SEC 10-K equipment vendor disclosures, and customs trade data for titanium sponge imports. Bottom-up equipment shipment tallies were triangulated against top-down aerospace and healthcare capital expenditure surveys.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by material type, technology platform, application criticality, and end-user sophistication tier. CAGRs were derived from installed base expansion curves and replacement cycle analysis. Industry-specific forecast inputs included FAA/EASA certification pipeline timelines and hospital GPO contract renewal patterns.
Sensitivities concentrate around titanium sponge price shocks, electron beam gun supply disruptions, and REACH substance restriction amendments. Forecasts reflect documented assumptions on qualification timeline compression and multi-laser system adoption curves. Quarterly review of FAA certification submission rates and hospital procurement committee documentation requirements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
3D Printing Robots Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
Online 3D Printing Service Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
Saudi Arabia and Egypt Healthcare 3D Printing Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
3D Printing Vacuum Furnaces Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
3D Printing Software Market