
 Satellite Internet Market | 2026-2036
Satellite Internet Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Internet Market Intelligence
Subscription-based managed services is recalibrating what satellite internet providers monetize, shifting capital recovery from hardware sales to recurring revenue streams. SpaceX leverages its vertically integrated launch and constellation operations to compress deployment costs. Viasat anchors its position through high-throughput geostationary capacity focused on enterprise and government verticals. OneWeb specializes in polar-orbiting coverage that serves maritime and aviation routes underserved by equatorial systems.
Satellite internet delivers broadband connectivity through constellations of orbiting transponders that relay signals between ground terminals and gateway stations, operating across Ku-band, Ka-band, and emerging V-band frequencies with latency profiles ranging from 20 milliseconds in low Earth orbit to 600 milliseconds in geostationary configurations. Low Earth Orbit technology is capturing the fastest expansion as constellation operators deploy thousands of small satellites to reduce latency and enable real-time applications previously impractical from higher altitudes. Fixed Connectivity within service type retains the largest revenue pool due to persistent rural and remote household demand, though Mobile Connectivity is narrowing the gap as aviation and maritime sectors standardize always-on link requirements.
The Federal Communications Commission governs spectrum licensing and orbital debris mitigation rules in the United States, while the International Telecommunication Union coordinates cross-border frequency assignments and interference standards that determine where constellations may operate. The European Union's Space Traffic Management initiative and proposed constellation certification requirements are tightening market access conditions for non-EU operators seeking to serve member states. Stakeholders must monitor spectrum auction schedules, orbital slot allocations, and emerging national security screening regimes for foreign satellite infrastructure investments.
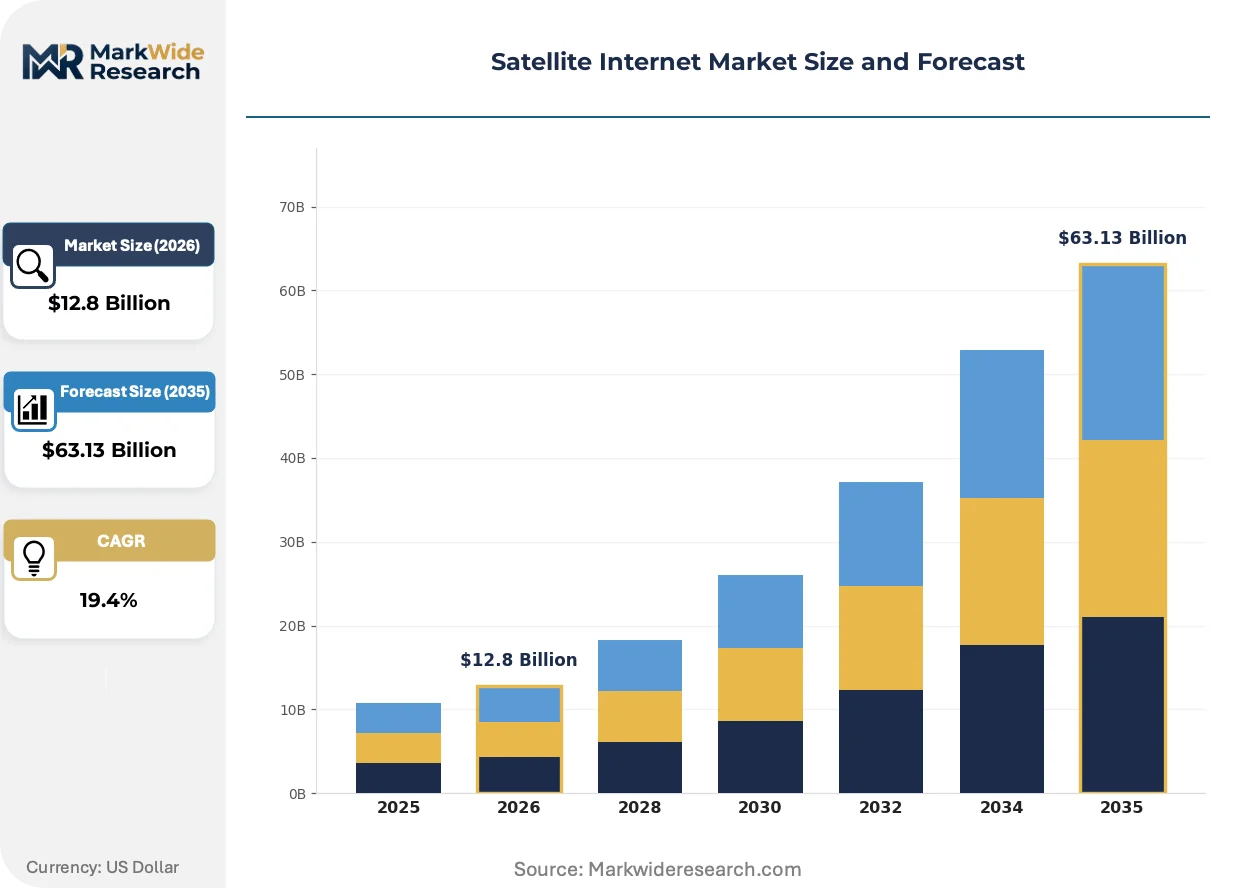
Market Dynamics
Low Earth Orbit constellation deployment is compressing latency benchmarks and forcing geostationary incumbents to reposition throughput versus coverage trade-offs. Spectrum coordination bottlenecks at the International Telecommunication Union are lengthening licensing timelines just as maritime and aviation operators demand always-on connectivity.
Growth Catalysts
- Rural broadband mandates:Brazil's Amazon basin connectivity projects and comparable universal service obligations in Indonesia are pulling capacity deployment toward equatorial latitudes previously deprioritized by polar-optimized constellations.
- Ka-band frequency availability:Regulators in the United States and India are releasing additional Ka-band spectrum for satellite broadband, enabling higher throughput per satellite and reducing ground terminal costs for fixed connectivity deployments.
- Maritime digitalization:Container shipping lines are standardizing vessel-to-shore data links for route optimization and predictive maintenance, creating pull-through demand for stabilized maritime terminals.
Market Restraints
- Launch capacity concentration:Dependence on a narrow supplier base for heavy-lift orbital deployment creates scheduling risk and cost volatility for constellation operators planning thousand-satellite networks.
- Geostationary latency floor:Physics-bound signal propagation delays of 500-600 milliseconds render high-throughput geostationary systems unsuitable for real-time gaming, high-frequency trading, and telemedicine applications.
- Orbital debris mitigation compliance:The Federal Communications Commission's de-orbit mandates and collision-avoidance requirements are extending satellite design cycles and raising insurance costs for constellation operators.
Strategic Opportunities
- In-flight connectivity penetration:Narrow-body aircraft fleets across Southeast Asia remain underserved by existing satellite capacity, presenting white space for regional beam optimization and airline partnership structures.
- V-band spectrum exploitation:Emerging very-high-frequency allocations offer terabit-scale throughput potential for next-generation constellations, though rain fade mitigation remains an unproven engineering challenge.
- Direct-to-device integration:Convergence between satellite modems and unmodified smartphones is eliminating terminal cost barriers for consumer adoption in remote recreation and emergency response segments.
Industry Challenges
- RF engineer scarcity:Phased-array antenna design and spectrum coordination expertise concentrates within a small cohort of aerospace and defense contractors, constraining ground terminal innovation velocity.
- Gateway station permitting:Terrestrial fiber backhaul coordination and local zoning approvals for gateway earth stations are extending deployment timelines in jurisdictions with fragmented land-use authority.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Internet Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $63.13 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Broadband, Narrowband, Mobile Connectivity, Fixed Connectivity Technology: Geostationary Orbit, Low Earth Orbit, Medium Earth Orbit, Hybrid Systems End User: Residential Users, Businesses, Government, Maritime Applications Deployment: Direct-to-Home, Managed Services, Enterprise Solutions, Emergency Services |
| Companies Covered | SpaceX, Viasat, EchoStar Corporation, SES, Hughes Network Systems, Eutelsat Communications, Intelsat, OneWeb, Telesat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Internet Market Strategic Shifts & Innovations
Constellation operators are racing to compress end-to-end latency while regulators grapple with spectrum scarcity and debris mitigation. Three interconnected developments are reshaping competitive positioning and investment allocation across the sector.
Laser inter-satellite links are expanding into the backbone architecture of operational constellations, replacing ground-based gateway hops with optical cross-connects that slash latency and reduce gateway infrastructure density requirements. Maritime and aviation operators are adopting these capabilities fastest, as polar and oceanic routes lack fiber backhaul alternatives. This expansion is compressing the coverage advantage historically held by geostationary systems in mid-ocean corridors.
The European Union's proposed constellation certification framework and space traffic management initiative are tightening market access for non-EU operators seeking to serve member states. Industrial consequence includes mandatory end-of-life disposal plans and interference coordination protocols that extend pre-launch compliance timelines. Small constellation operators targeting European enterprise and government verticals are responding by establishing EU-based ground segment partnerships and legal entities.
Enterprise buyers are consolidating satellite connectivity procurement under managed service contracts that bundle hardware, bandwidth, and network operations into single-vendor accountability structures. Systems integrators and maritime fleet operators are displacing direct terminal purchases with subscription-based arrangements that transfer obsolescence risk to providers. This pattern is most visible in North Sea offshore energy and Asia-Pacific container shipping, where fleet standardization favors vendor consolidation over multi-supplier fragmentation.
Satellite Internet Market Segmentation
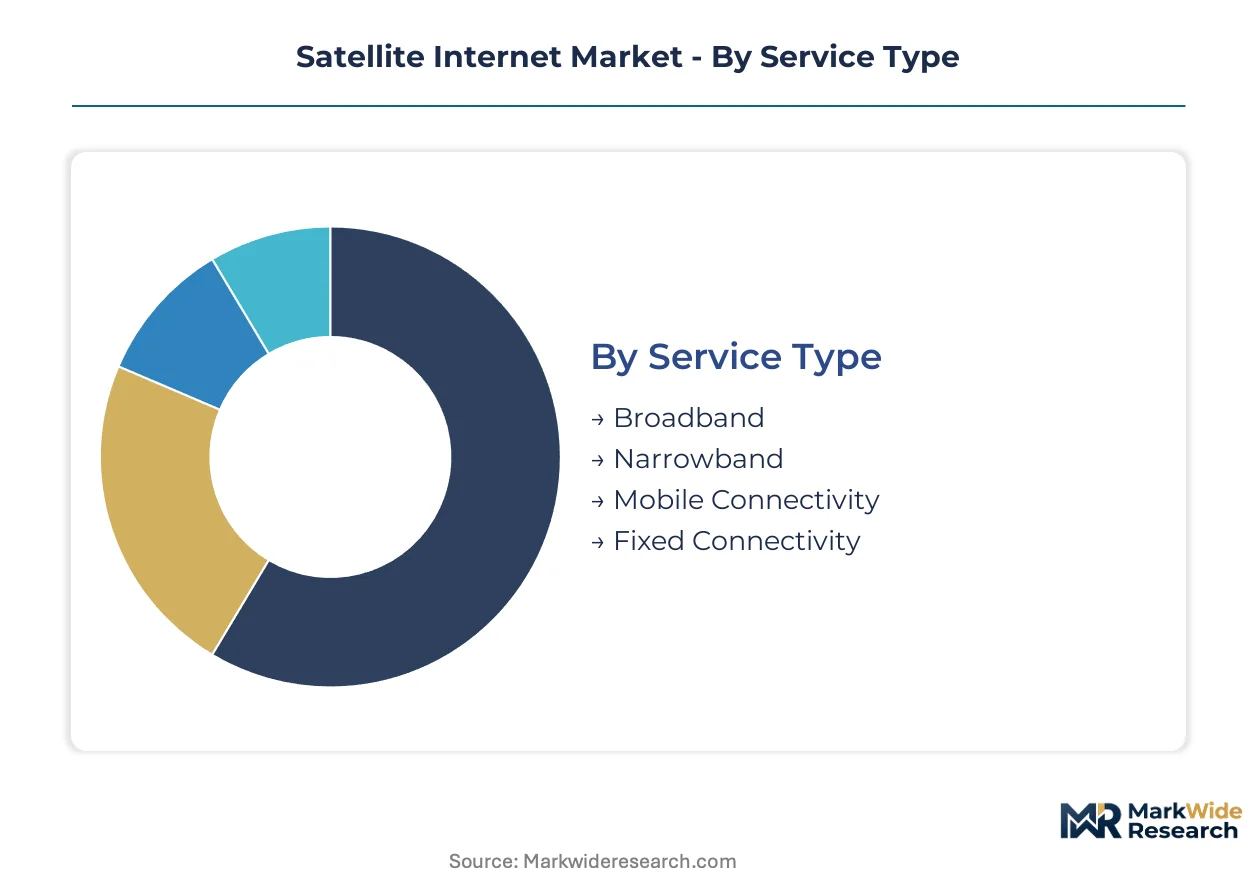
Satellite internet segmentation reveals how service architecture, orbital mechanics, and procurement models interact to shape revenue capture. Constellation operators must align segment-specific capabilities with distinct latency tolerances, terminal cost sensitivities, and regulatory exposure profiles.
Service Type:
Standalone subscription models dominate consumer-facing segments, while embedded connectivity integrates satellite links into broader telecommunications portfolios.
- Broadband:High-throughput data delivery supporting video streaming, teleconferencing, and cloud applications. Residential demand clusters in rural Brazil and Indonesia where terrestrial fiber remains uneconomical.
- Fixed Connectivity:Permanent ground terminal installations serving households and small enterprises. Persistent gaps in Amazon basin infrastructure and Indonesian archipelago logistics sustain volume leadership in this category.
- Narrowband:Low-data-rate transmission for sensor networks and machine-to-machine communication. Agricultural monitoring in remote Australian stations and pipeline surveillance across Kazakh oilfields absorb capacity.
- Mobile Connectivity:Vehicle-mounted and portable terminals for aviation, maritime, and land transport. Container shipping standardization for vessel-to-shore data links accelerates deployment timelines.
Volume placements concentrate in Fixed Connectivity; the faster expansion belongs to Mobile Connectivity.
Technology:
Orbital altitude determines latency profiles, coverage patterns, and capital intensity requirements for constellation deployment.
- Low Earth Orbit:Constellations operating 300-2,000 kilometers altitude deliver 20-40 millisecond latency through dense small-satellite networks. Real-time gaming, high-frequency trading, and telemedicine applications in United States and European urban corridors drive uptake.
- Geostationary Orbit:Satellites fixed at 35,786 kilometers altitude provide continental coverage from three orbital positions. Enterprise and government verticals in Viasat's served markets tolerate 500-600 millisecond delays in exchange for proven reliability.
- Medium Earth Orbit:Intermediate altitude systems balancing latency reduction against constellation size requirements. O3b Networks serves equatorial maritime routes and Pacific island nations from this orbital regime.
- Hybrid Systems:Integrated architectures combining multiple orbital layers for seamless handoff. Military and disaster response applications in United States and allied nations prioritize resilience over unit cost.
Capital deployment tilts toward Low Earth Orbit; Geostationary Orbit retains entrenched enterprise relationships.
End User:
Procurement sophistication varies sharply across customer categories, from price-sensitive residential subscribers to mission-critical government buyers.
- Residential Users:Individual households purchasing direct-to-home terminals and monthly service plans. Rural broadband mandates in Brazil and universal service obligations in Indonesia concentrate demand.
- Businesses:Corporate accounts requiring service level agreements and managed network operations. Mining camps in Western Australia and remote banking branches across Sub-Saharan Africa standardize procurement.
- Government:National security, civilian agency, and disaster response applications with classified or priority spectrum access. United States Department of Defense and European defense ministries drive specialized terminal development.
- Maritime Applications:Commercial shipping, offshore energy, and recreational vessel operators. Polar route container lines and North Sea offshore platforms command premium pricing for always-on connectivity.
Revenue per terminal peaks in Maritime Applications; subscriber scale concentrates in Residential Users.
Deployment:
Channel structure determines whether satellite operators capture hardware margins or cede them to systems integrators and service aggregators.
- Managed Services:Bundled offerings combining terminals, bandwidth, and network operations under subscription contracts. Maritime fleet operators and offshore energy contractors in North Sea and Gulf of Mexico prefer this model.
- Enterprise Solutions:Custom-engineered ground segment and backhaul integration for corporate networks. Mining conglomerates and financial institutions across Australia and South Africa procure through this channel.
- Direct-to-Home:Consumer self-installation of retail terminals with minimal technical support. Brazilian rural households and Indonesian archipelago residents access connectivity through this lowest-touch deployment mode.
- Emergency Services:Rapid-deploy terminals for disaster response and humanitarian operations. United States Federal Emergency Management Agency and international relief organizations maintain standby procurement contracts.
Margin protection concentrates in Managed Services; volume expansion accelerates in Direct-to-Home.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Constellation manufacturing concentrates in California and Washington state facilities, while bandwidth consumption spreads across equatorial and polar routes. Deployment timelines track regulatory clearance velocity more than demand density.
United States
The Federal Communications Commission processes orbital debris mitigation filings and spectrum coordination requests for low Earth orbit operators. The FCC's de-orbit mandates and collision-avoidance rules extend satellite design cycles for constellation builders in Hawthorne and Redmond. Seattle-area engineering clusters supply phased-array antenna expertise to maritime terminal manufacturers serving Pacific shipping lanes.
Brazil
Amazon basin connectivity projects and universal service obligations pull capacity toward rural municipalities previously unreachable by fiber. ANATEL, the national telecommunications regulator, auctions satellite spectrum parcels under rural broadband mandates. São Paulo-based systems integrators deploy fixed terminals across Mato Grosso agricultural zones and offshore pre-salt platforms.
India
TRAI liberalizes satellite broadband licensing to bridge connectivity gaps across the Himalayan corridor and island territories. The Indian Space Research Organisation coordinates frequency assignments with the International Telecommunication Union for domestic constellation operators. Bengaluru and Hyderabad host ground segment engineering centers serving maritime routes through the Indian Ocean.
United Kingdom
Ofcom governs non-geostationary licensing and interference coordination for operators seeking European coverage. The UK Space Agency funds satellite broadband pilots for remote Scottish Highlands and North Sea offshore platforms. Harwell and Glasgow manufacturing clusters produce small satellite buses and inter-satellite link terminals.
Japan
METI promotes satellite broadband adoption for disaster resilience and maritime connectivity across Pacific shipping corridors. The Ministry of Internal Affairs and Communications allocates Ka-band spectrum for fixed connectivity in rural Hokkaido and island prefectures. Tokyo-Yokohama engineering centers develop stabilized maritime terminals for container shipping lines.
Satellite Internet Market Key Industry Players
Top-tier vendors anchor vertically integrated launch and constellation operations, while mid-tier specialists concentrate on geostationary capacity and regional beam optimization. The market structures around three archetypes: launch-captive constellation operators, high-throughput geostationary incumbents, and polar-orbit specialists serving mobility verticals. Dominant competitive moves include spectrum acquisition at International Telecommunication Union filings and managed service contract consolidation with maritime fleet operators.
Within the vertically integrated tier, SpaceX exemplifies launch-captive constellation deployment through its Hawthorne-based manufacturing and Cape Canaveral launch cadence. Viasat occupies a position among geostationary incumbents focused on enterprise and government verticals. OneWeb sits within the polar-orbit specialist archetype, anchoring coverage strategies for maritime and aviation routes underserved by equatorial systems.
| Leading Market Players |
|---|
| SpaceX |
| Viasat |
| EchoStar Corporation |
| SES |
| Hughes Network Systems |
| Eutelsat Communications |
| Intelsat |
| OneWeb |
| Telesat |
| Others |
Cost & Logistics Intelligence
Phased-array terminal manufacturing automation is compressing ground equipment costs while concentrating supplier qualification among California and Washington engineering clusters. This dual effect simultaneously lowers consumer entry pricing and raises barriers for non-integrated constellation operators lacking captive antenna production.
Pricing Analysis
Margin tightening in consumer broadband tiers reflects SpaceX's vertically integrated cost position forcing competitor repricing. Three-tier pricing structure across premium maritime, standard enterprise, and economy residential levels stratifies by latency tolerance and terminal sophistication. Price differentiation hinges on orbital altitude performance and managed service bundling. Residential subscribers in Brazil and Indonesia exhibit highest price sensitivity; maritime operators accept premium positioning for always-on polar coverage.
Supply Chain Analysis
Dual-sourcing requirements from constellation operators mandate qualified suppliers across United States, United Kingdom, and Japan for radiation-hardened components and phased-array substrates. Manufacturing draws from California satellite bus production, Glasgow inter-satellite link terminals, and Tokyo-Yokohama maritime antenna stabilization systems. Single-source vulnerability concentrates in heavy-lift launch capacity anchored to Cape Canaveral and Vandenberg facilities. Distribution runs through managed service integrators for enterprise verticals and direct-to-home retail channels for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FCC de-orbit mandates and collision-avoidance compliance create a cost-of-compliance moat favoring capitalized incumbents with dedicated regulatory affairs infrastructure and insurance relationships.
For Market Incumbents: Deepen backward integration into phased-array manufacturing to defend against terminal cost erosion from emerging Asian suppliers. Expand Ka-band gateway footprints in Brazil and India ahead of spectrum auction deadlines. Lock maritime fleet operators into multi-year managed service contracts before polar-optimized competitors achieve full constellation density. For New Entrants and Emerging Players: Enter via narrow-body in-flight connectivity partnerships in Southeast Asia, where regional beam capacity remains underserved by existing operators. Target hybrid orbital systems for military and disaster response procurement, where resilience requirements justify premium positioning against latency-optimized alternatives. Pursue direct-to-device modem integration with unmodified smartphones as the go-to-market angle for emergency response and remote recreation segments. For Investors and Strategic Acquirers: Re-rating potential sits with polar-orbit specialists given maritime digitalization pull-through and aviation route standardization. Long-term viability favors operators with demonstrated spectrum coordination capabilities and ITU filing precedence. Watch gateway station permitting velocity in fragmented land-use jurisdictions as the inflection indicator for deployment timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Inter-Satellite Link Deployment | Optical cross-connects slash latency for maritime routes lacking fiber backhaul alternatives. |
| Managed Service Contract Consolidation | Subscription bundling transfers obsolescence risk from maritime fleet operators to providers. |
| Ka-Band Spectrum Acquisition | Additional allocations in United States and India enable higher throughput per satellite. |
| Direct-to-Device Modem Integration | Satellite-smartphone convergence eliminates terminal cost barriers for consumer adoption. |
| EU Ground Segment Partnership | Local legal entities satisfy proposed constellation certification and space traffic mandates. |
Research Approach
Independent corroboration across constellation engineering executives, maritime fleet procurement officers, spectrum coordination specialists, and gateway station operators underwrites the qualitative findings. Primary fieldwork combined with secondary validation from FCC licensing databases, ITU coordination filings, ANATEL auction records, and customs trade data for satellite terminal equipment. Bottom-up subscriber and terminal deployment estimates triangulate against top-down bandwidth consumption and capacity supply projections.
Comparable-period anchoring to historical constellation deployment timelines and spectrum clearance velocities structured the forecast window. Segmentation modeling spans service type, orbital technology, end-user vertical, and deployment channel dimensions across the analysis window. CAGRs derive from subscriber growth trajectories, terminal cost curves, and bandwidth pricing elasticity specific to maritime, aviation, and residential applications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under launch capacity constraints or ITU coordination delays. Deviation in FCC debris mitigation rule enforcement or EU certification timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
UK Satellite Connectivity Market
Satellite
China Satellite Imagery Services Market
Satellite
United Kingdom Satellite Communications Market
Satellite
Satellite Communications Service Market
Satellite
Commercial Satellite Launch Service Market
Satellite
UK Satellite-Based Earth Observation Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Europe Satellite Manufacturing and Launch Systems Market
Satellite
Mexico Satellite Connectivity Market
Satellite
Advanced Satellite Market
Satellite
France Satellite Connectivity Market
Satellite
South Korea Satellite Communication Market
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
Asia-Pacific Satellite Bus Market
Satellite
Latin America Satellite Connectivity Market
Satellite
South Korea Satellite Imagery Services Market