
 Europe Airport Operations Market | 2026-2036
Europe Airport Operations Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Airport Operations Market Analytics
Market Context
CE marking under the EU's Airport Operations Certification framework is collapsing the supplier base to technically qualified operators. Fraport AG leverages its integrated terminal management platform across Frankfurt and international concessions. Vinci Airports anchors its competitive position through long-term operating contracts at Lisbon, Lyon, and London Gatwick. Groupe ADP differentiates via Orly and Charles de Gaulle hub coordination with Air France-KLM network planning.
Technical Definition and Structural Segments
Europe airport operations encompasses the coordinated management of aircraft turnaround, passenger processing, baggage handling, and airside logistics across regulated aviation infrastructure, typically operating under 99.5% slot utilization thresholds at Category III instrument landing system-equipped runways. The primary commercial purpose is minimizing gate-to-gate cycle times while maintaining EASA safety compliance for scheduled and charter services. Ground handling services occupy the largest revenue pool due to labor intensity and equipment requirements, while automated check-in technology represents the fastest-expanding segment as airlines push for reduced counter staffing. Security screening commands premium margins driven by ECAC Common Evaluation Process certification barriers and rising passenger throughput mandates.
Regulatory Framework
EASA airworthiness directives and the EU Green Deal's ReFuelEU Aviation mandate shape capital allocation toward sustainable ground support equipment and SAF-compatible fueling systems. The EU AI Act introduces algorithmic transparency requirements for automated baggage tracking and biometric boarding gates deployed at Schengen airports. Stakeholders must monitor how the forthcoming EASA drone integration regulations reshape airspace management contracts and ground handling coordination protocols.
Market Dynamics
The EU Green Deal's ReFuelEU Aviation mandate is forcing capital reallocation toward sustainable ground support equipment and SAF-compatible fueling infrastructure, compressing payback periods for legacy diesel-powered fleets.
Growth Catalysts
- SAF Infrastructure Mandates:ReFuelEU Aviation requires progressive blending of sustainable aviation fuel, driving airport fueling system upgrades and dedicated storage investments across Schengen hubs.
- Low-Cost Carrier Expansion:Eastern European fleet deployments by Ryanair, Wizz Air, and emerging entrants are multiplying ground handling contract volumes at secondary airports in Poland, Hungary, and Romania.
- Biometric Processing:Automated check-in and boarding gates using facial recognition are slashing passenger processing times and reducing counter staffing requirements at Category III-equipped terminals.
Market Restraints
- Labor Cost Escalation:Ground handling services remain labor-intensive, with unionized workforces in Germany and France resisting automation-driven headcount reductions.
- Equipment Supplier Concentration:Specialized GSE manufacturers cluster in Germany and the Netherlands, creating single-source vulnerability for electric tow tractors and belt loaders.
- CE Marking Barriers:EASA's Airport Operations Certification framework is collapsing the supplier base, excluding smaller operators lacking technical documentation capabilities.
Strategic Opportunities
- Secondary Airport Modernization:Underpenetrated airports in Croatia, Bulgaria, and the Baltic states seek integrated terminal management platforms to attract LCC route allocations.
- AI-Enabled Baggage Tracking:The EU AI Act's algorithmic transparency requirements create first-mover advantage for compliant machine-vision sorting systems at high-volume hubs.
- Drone Integration Services:Forthcoming EASA drone regulations will reshape airspace management contracts, opening ground handling coordination protocols for unmanned cargo and inspection flights.
Industry Challenges
- Skilled Technician Shortage:Maintenance of automated baggage systems and electric GSE fleets demands mechatronics expertise that vocational pipelines in Italy and Spain fail to supply.
- Legacy System Integration:Biometric boarding gates must interface with decades-old passenger processing architectures at Charles de Gaulle and Frankfurt, extending deployment timelines.
- Capex Intensity:Slot-constrained hubs face 99.5% utilization thresholds that permit only overnight construction windows for infrastructure upgrades, inflating project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Airport Operations Market |
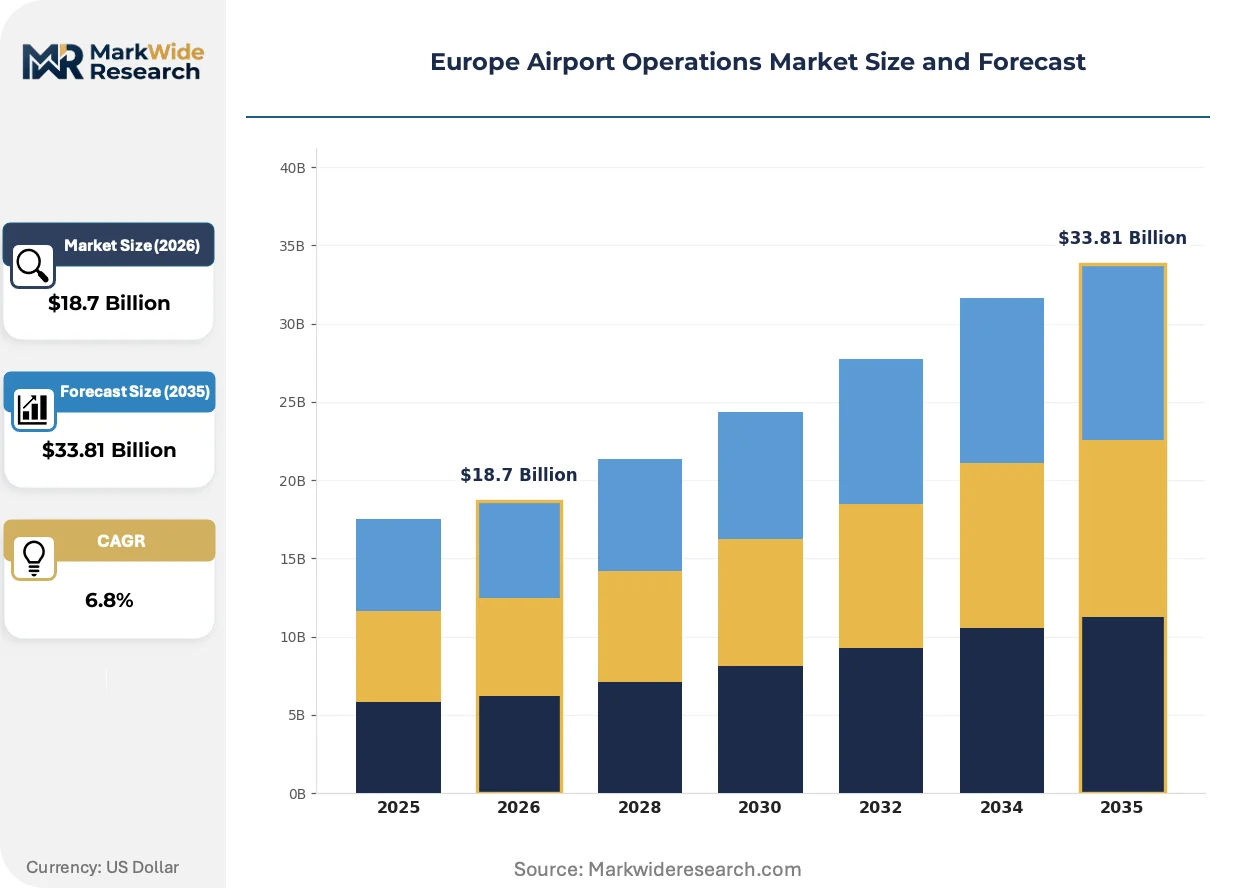
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ground Handling, Air Traffic Control, Fueling Services, Maintenance Services Technology: Automated Check-in, Baggage Tracking, Flight Information Display, Security Screening Customer Type: Passengers, Airlines, Freight Forwarders, Airport Authorities End User: Commercial Aviation, Cargo Carriers, Private Jets, Aircraft Charters |
| Companies Covered | Fraport AG, Groupe ADP, Vinci Airports, Aena SME, Swissport International AG, Menzies Aviation, Aviapartner, Worldwide Flight Services, Heathrow Airport Holdings, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Airport Operations Market Evolving Landscape
Digital automation and decarbonization mandates are compressing operational models across European airport operations, forcing simultaneous investment in passenger-facing technology and airside equipment replacement.
Electric ground support equipment is displacing diesel-powered counterparts across European hub operations. Major handlers at Frankfurt, Amsterdam, and Madrid are mandating fleet electrification for new contracts. This transition is displacing incumbent GSE lessors lacking battery maintenance capabilities and charging infrastructure expertise.
ReFuelEU Aviation's binding SAF blending targets are reshaping airport fueling infrastructure investments. Fuel farm operators must install segregated storage and dedicated hydrant systems for synthetic and bio-based fuels. Ground handling segments at Paris and London hubs are most affected, with fueling contractors accelerating SAF-compatible dispenser retrofits ahead of 2025 enforcement.
Airline procurement departments are unbundling ground handling contracts into discrete service modules. Legacy full-service agreements covering passenger, ramp, and cargo handling are fragmenting into standalone awards by function. This pattern is most visible in Germany, where Lufthansa's tender processes now separate baggage sorting from aircraft cleaning and pushback operations.
Europe Airport Operations Market Segmentation
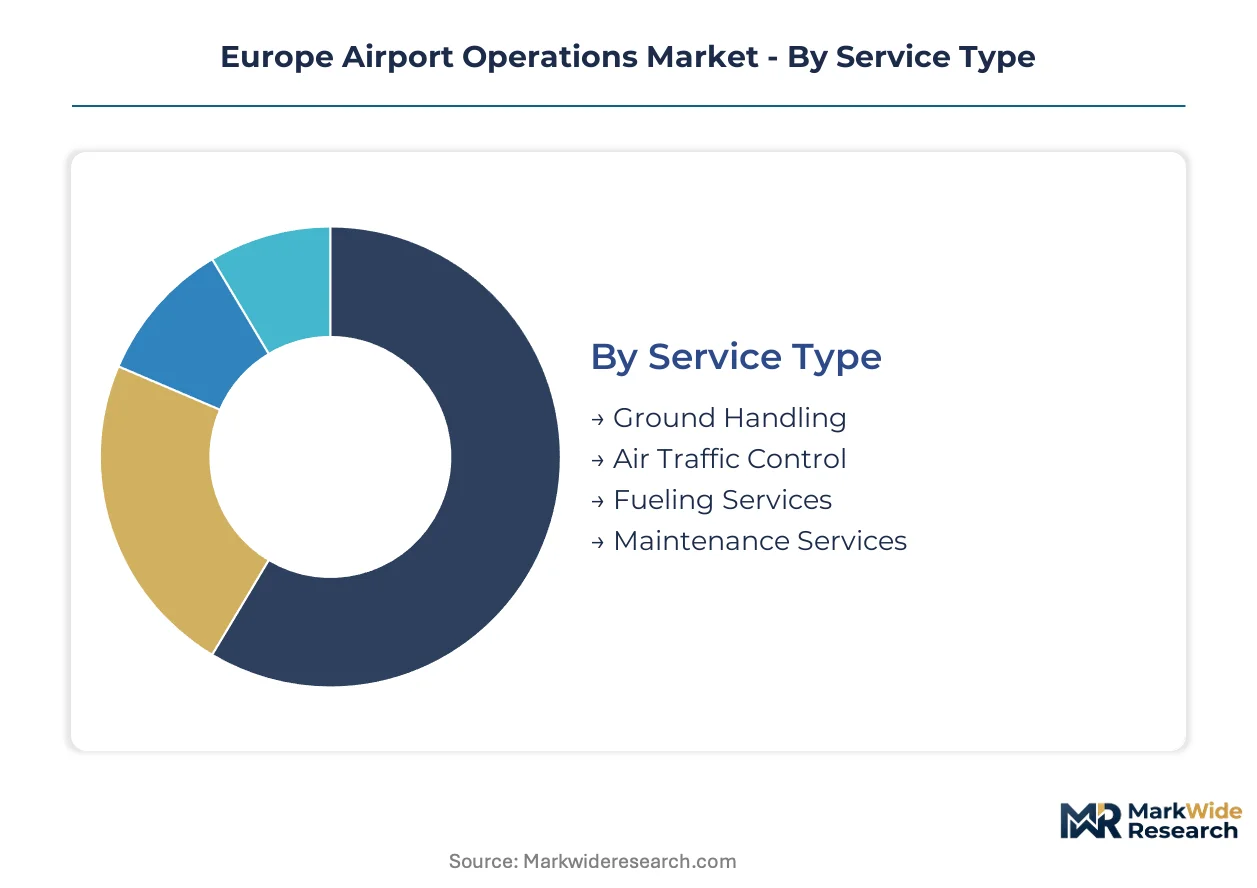
Segmentation reveals how regulatory mandates and carrier procurement patterns split contract value across functionally distinct service layers. Each dimension carries different margin profiles and substitution vulnerabilities that reshape competitive positioning.
Service Type:
Ground handling faces the strongest substitution pressure as electric GSE and autonomous tow tractors displace labor-intensive diesel fleets.
- Ground Handling:Aircraft turnaround coordination including pushback, catering, and cleaning operations. Labor costs at Frankfurt and Charles de Gaulle consume 60% of contract value, driving automation investment. ReFuelEU mandates accelerate electric equipment replacement cycles.
- Air Traffic Control:Slot allocation and ground movement sequencing within controlled airspace. EASA's forthcoming drone integration regulations will expand service scope to unmanned traffic management at Schengen hubs.
- Fueling Services:Into-plane fueling and hydrant system maintenance. Segregated SAF storage infrastructure now required under ReFuelEU Aviation.
- Maintenance Services:Airside equipment repair and preventive servicing. Mechatronics technician shortages in Southern Europe constrain expansion.
Ground handling retains volume leadership; fueling services hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium biometric installations from legacy hardware refresh cycles at secondary airports.
- Automated Check-in:Self-service kiosks and mobile boarding pass validation. LCCs at Eastern European bases mandate reduced counter staffing, multiplying kiosk deployment.
- Baggage Tracking:RFID and machine-vision sorting systems. The EU AI Act's algorithmic transparency requirements favor compliant vendors at high-volume hubs.
- Flight Information Display:Real-time gate and baggage claim signage. Integration with legacy passenger processing architectures extends deployment timelines at established terminals.
- Security Screening:ECAC-certified explosive detection and body scanners. Certification barriers protect margins despite throughput pressure.
Security screening commands premium pricing; baggage tracking is gaining share fastest.
Customer Type:
Application intensity varies sharply between passenger-facing services and back-of-house airline operations.
- Airlines:Contract ground handling and fueling procurement. Unbundling of full-service agreements into discrete modules fragments vendor relationships at German hubs.
- Airport Authorities:Terminal management platform licensing and concession oversight. Fraport and Vinci anchor demand through integrated international portfolios.
- Passengers:Direct-paid services including priority security and lounge access. Biometric boarding adoption reduces friction for frequent flyers.
- Freight Forwarders:Cargo handling and customs coordination. E-commerce volume growth at Leipzig and Liège drives specialized cold chain infrastructure.
Airlines dominate contract value; freight forwarders are expanding most quickly.
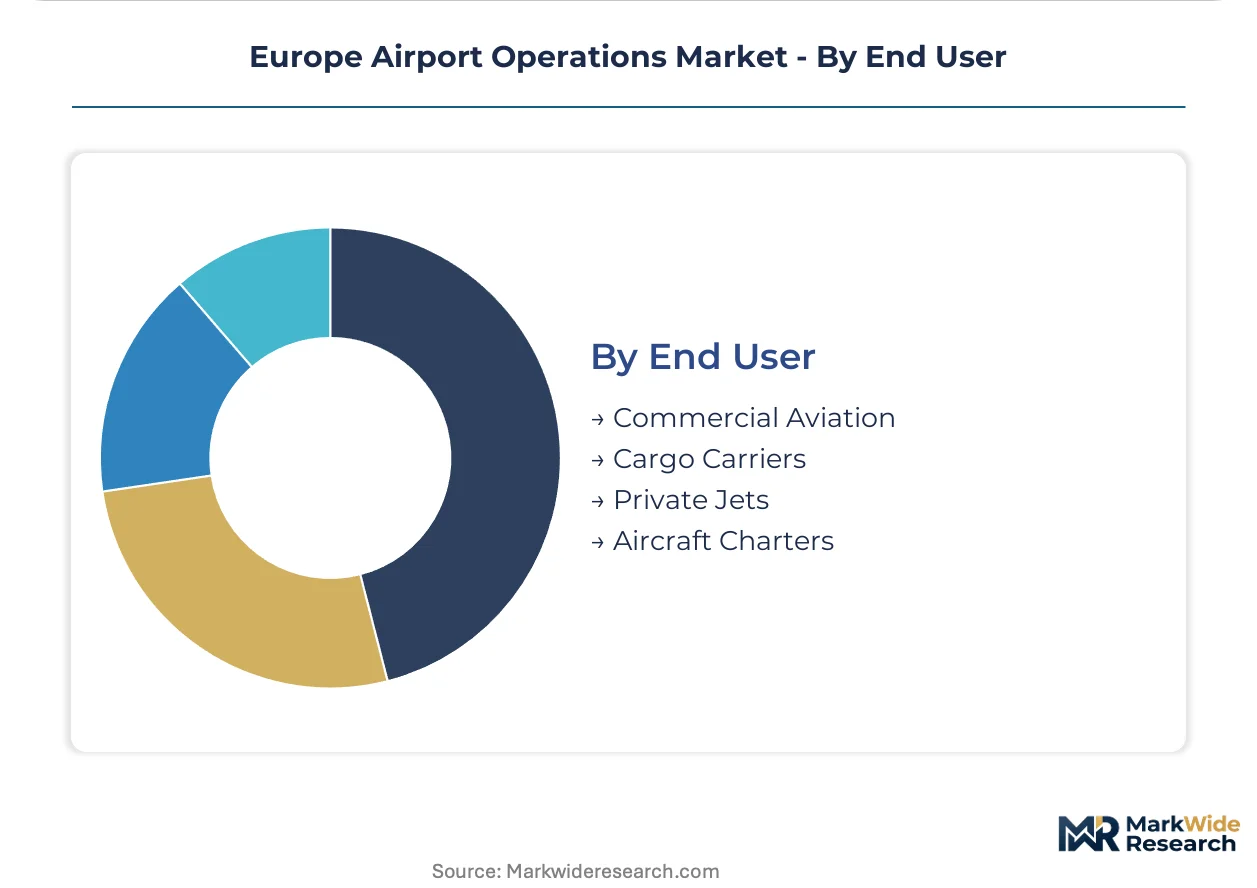
End User:
Maturity gradients separate saturated commercial aviation from emerging private jet segments across Mediterranean leisure corridors.
- Commercial Aviation:Scheduled passenger and cargo services at Category III-equipped hubs. Slot utilization thresholds above 99% constrain infrastructure upgrade windows.
- Cargo Carriers:Dedicated freighter operations and belly-hold logistics. DHL and FedEx concentration at Cologne and Paris-Charles de Gaulle shapes regional demand.
- Private Jets:Business aviation handling at dedicated FBO terminals. Fragmented across smaller airports in Switzerland and Monaco.
- Aircraft Charters:Ad-hoc passenger and cargo services. Seasonal peaks in Greek islands and Alpine resorts drive intermittent ground handling demand.
Commercial aviation retains volume leadership; cargo carriers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airport authorities and ground handling contractors concentrate procurement power at major Schengen hubs, with LCC route planners and cargo integrators driving secondary airport investments across Eastern and Southern Europe.
Germany
Lufthansa's unbundled tender processes fragment ground handling contracts into discrete service modules at Frankfurt and Munich. EASA airworthiness directives mandate upgraded Category III instrument landing system maintenance protocols. The Rhine-Main cluster anchors hub modernization programs with 99.5% slot utilization thresholds constraining overnight construction windows.
France
Air France-KLM network coordination drives hub synchronization investments at Charles de Gaulle and Orly. ReFuelEU Aviation's SAF blending targets accelerate fuel farm segregated storage installations. The Paris basin concentrates premium-margin security screening contracts under ECAC Common Evaluation Process certification barriers.
United Kingdom
Heathrow slot constraints and Gatwick's LCC traffic mix bifurcate ground handling demand between legacy full-service and modular procurement models. The EU AI Act's algorithmic transparency requirements reshape biometric boarding gate deployments. London's dual-hub structure splits automation investment between premium passenger processing and cargo handling at Stansted and East Midlands.
Spain
Aena SME's integrated concession portfolio drives standardized terminal management platform rollouts across Madrid-Barajas and Barcelona-El Prat. Unionized ground handling workforces in Catalonia resist automation-driven headcount reductions. The Mediterranean leisure corridor fragments private jet handling demand across dedicated FBO terminals in Palma, Málaga, and Ibiza.
Poland
Ryanair and Wizz Air base expansions multiply ground handling contract volumes at Warsaw Chopin and Kraków-Balice. CE marking barriers under the EU Airport Operations Certification framework collapse the supplier base to technically qualified operators. The Central European LCC corridor concentrates secondary airport modernization demand in Gdańsk, Wrocław, and Poznań.
Europe Airport Operations Market Competitive Landscape
Player mix skews toward integrated airport operators with international concession portfolios, creating a tiered structure where scale-driven handlers compete against specialized regional contractors. Strategic archetypes include hub-centric platform licensors, multi-airport concession aggregators, and modular ground handling specialists. Competitive moves center on long-term operating contract extensions and electric ground support equipment fleet transitions.
Among integrated operators, Fraport AG, Vinci Airports, and Groupe ADP exemplify the concession-aggregator archetype, each anchoring competitive position through multi-jurisdictional terminal management portfolios rather than single-asset dominance. Fraport represents the hub-centric platform model with its Frankfurt anchor and international concessions. Vinci occupies the scale-driven expansion vector through long-term contracts at Lisbon, Lyon, and London Gatwick. Groupe ADP exemplifies network-coordinated hub management through Orly and Charles de Gaulle synchronization with legacy carrier planning cycles.
| Leading Market Players |
|---|
| Fraport AG |
| Groupe ADP |
| Vinci Airports |
| Aena SME |
| Swissport International AG |
| Menzies Aviation |
| Aviapartner |
| Worldwide Flight Services |
| Heathrow Airport Holdings |
| Others |
Value Network & Pricing Analysis
Electric ground support equipment substitution for diesel-powered fleets simultaneously redraws procurement geography toward Germany and the Netherlands while compressing contract pricing through accelerated depreciation schedules and energy arbitrage economics.
Pricing Analysis
Cost-plus ground handling contracts with labor indexation clauses dominate at Frankfurt and Charles de Gaulle, where union-negotiated wage escalators pass through to airline clients. Price differentiation separates ECAC-certified security screening from commodity ramp services, with certification barriers protecting premium tiers. Cost compression in electric GSE leasing is intensifying because battery maintenance capabilities remain scarce outside specialized handlers. Low-cost carriers exhibit highest price sensitivity, demanding modular unbundling of full-service agreements.
Supply Chain Analysis
CE marking bottlenecks under EASA's Airport Operations Certification framework concentrate qualified ground support equipment manufacturing in Germany, the Netherlands, and France. Specialized electric tow tractors and belt loaders draw from lithium-ion cell supply anchored in South Korea and China, with charging infrastructure components sourced from industrial automation clusters in Italy and Spain. Single-source vulnerability persists for SAF-compatible fueling system retrofits, where segregated storage fabricators cluster in Northern Europe. Distribution runs through multi-year operating concessions held by integrated airport operators rather than spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe airport operations sits at a platform-economics inflection where terminal management system interoperability determines vendor lock-in duration and concession renewal probability.
For Market Incumbents: Fortify hub-centric platform positions through backward integration into electric GSE maintenance capabilities, insulating against battery-servicing specialists. Deepen concession portfolios in secondary Eastern European airports before LCC route allocations crystallize competitor relationships. CE marking compliance investments now exclude smaller regional handlers from tender eligibility. For New Entrants and Emerging Players: Differentiate on AI-enabled baggage tracking compliance under the EU AI Act's algorithmic transparency mandates, where incumbent legacy systems face retrofit friction. Target underpenetrated Croatian and Bulgarian secondary airports seeking integrated terminal platforms to attract Ryanair and Wizz Air base expansions. Lead with machine-vision sorting pilots that demonstrate throughput gains against RFID-dependent competitors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors scale-driven concession aggregators over single-asset operators. Long-term viability hinges on SAF infrastructure positioning ahead of ReFuelEU enforcement milestones. Acquisition candidates should demonstrate integrated international portfolios with embedded EASA certification capabilities. Monitor EASA drone integration regulation finalization as the signal for unmanned traffic management contract inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Electric GSE Fleet Transition | Battery maintenance capabilities displace diesel-dependent handlers at Frankfurt and Amsterdam. |
| SAF-Compatible Fueling Infrastructure | Segregated storage installations at Paris and London hubs satisfy ReFuelEU mandates. |
| Terminal Management Platform Licensing | Fraport and Vinci extend integrated software across international concession portfolios. |
| AI-Enabled Baggage Tracking Deployment | Machine-vision sorting captures EU AI Act first-mover advantage at high-volume terminals. |
| Secondary Airport Concession Expansion | Eastern European bases multiply ground handling contract volumes for Ryanair and Wizz Air. |
Research Methodology
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings in this study. Primary fieldwork encompassed airport operations directors, ground handling procurement leads at major carriers, EASA certification specialists, and electric GSE fleet managers. Secondary sources included EASA airworthiness directives, EU Green Deal implementation progress reports, ECAC Common Evaluation Process certification databases, and concession contract disclosures from Fraport, Vinci, and Groupe ADP. Bottom-up service segment sizing triangulated against top-down airport throughput and slot utilization data.
Sensitivity analysis around SAF blending mandate enforcement timelines and LCC fleet deployment schedules shaped the projection framework. Segmentation modeling spanned service type, technology tier, customer archetype, and end-use intensity across the analysis window. CAGRs derived from fitted trend extrapolation with scenario-weighted adjustments for regulatory acceleration risk. Electric GSE penetration curves and biometric boarding gate deployment rates served as industry-specific demand inputs.
Material uncertainties — EASA drone regulation finalization, ReFuelEU penalty enforcement consistency, and union automation resistance outcomes — sit outside the modeled envelope. Forecasts reflect documented assumptions about slot utilization thresholds and concession renewal probabilities. Practitioners should keep alternative scenarios live as EASA regulatory timelines and EU Green Deal funding disbursements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market
Airport Operations
South Korea Airport Operations Market
Airport Operations
Global Air Charter Services Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
Middle East Airport Operations Market
Airport Operations
Aircraft Ground Handling System Market
Airport Operations
Global Airside Services Market
Airport Operations
Airport Terminal Operations Market
Airport Operations
UK Airport Operations Market
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
Airport Operations Market
Airport Operations
Canada Airport Operations Market
Airport Operations
France Airport Operations Market
Airport Operations
Business Jet Ground Handling Services Market