
 United Kingdom Satellite Communications Market | 2026-2036
United Kingdom Satellite Communications Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Satellite Communications Market Insights
GaN-on-SiC power amplifiers are replacing traditional traveling-wave tube amplifiers across high-throughput payloads, and this substitution is realigning cost structures for British satellite manufacturers. Airbus Defence and Space Ltd leverages its Portsmouth facility to sustain sovereign manufacturing capability for military and civil platforms. OneWeb anchors the low Earth orbit segment with its constellation deployment from Cornwall's Spaceport. Inmarsat Plc dominates mobile satellite services through its geostationary fleet serving maritime and aviation clients.
United Kingdom satellite communications encompasses space-based and ground-based systems transmitting voice, data, and video via radio frequency links operating across L-band through V-band frequencies, with orbital altitudes spanning 600 km to 35,786 km depending on service architecture. Ka-band technology leads capacity expansion for broadband delivery, while laser communication represents the fastest-growing segment for inter-satellite links requiring precise pointing acquisition and tracking mechanisms. Government end users command premium pricing for encrypted military-grade terminals, whereas commercial maritime applications generate recurring service revenue through subscription-based connectivity models.
Ofcom regulates spectrum licensing under the Wireless Telegraphy Act, while the UK Space Agency coordinates national space policy and launch licensing through the Space Industry Act 2018. The Civil Aviation Authority shapes aeronautical terminal certification standards for inflight connectivity services. Stakeholders must monitor Ofcom's upcoming mm-wave spectrum consultations and the UK Space Agency's orbital debris mitigation requirements as these frameworks will determine market access conditions for next-generation constellation operators.
Market Dynamics
The Ministry of Defence's satellite procurement expansion is compressing development timelines for British manufacturers while Ofcom's Ka-band reforms reallocate spectrum rights across military and commercial users.
Growth Catalysts
- Secure Military Communications Mandate:The Ministry of Defence's procurement programs for encrypted satellite terminals are creating dedicated demand streams for sovereign British manufacturing capabilities.
- Ofcom Spectrum Liberalization:The Wireless Telegraphy Act reforms are accelerating Ka-band deployment authorization for broadband satellite services across British territories.
- Scotland Space Cluster Concentration:Glasgow and Prestwick are aggregating launch infrastructure, payload integration facilities, and specialized engineering talent pools.
Market Restraints
- Traveling-Wave Tube Supply Concentration:Legacy amplifier supply chains remain concentrated among a limited set of European and US defense contractors, creating input vulnerability.
- Orbital Debris Compliance Costs:The UK Space Agency's mitigation requirements under the Space Industry Act 2018 are extending licensing timelines and increasing insurance burdens.
- Laser Communication Technical Maturity:Inter-satellite optical links require precision pointing acquisition mechanisms that remain unproven at constellation scale.
Strategic Opportunities
- Cornwall Spaceport Utilization:Horizontal launch capabilities from Newquay are enabling dedicated UK-based constellation deployment without foreign facility dependency.
- Maritime Connectivity Subscriptions:Commercial shipping operators are transitioning from capital-intensive terminal ownership to recurring service contracts for broadband at sea.
- Civil Aviation Terminal Certification:The Civil Aviation Authority's inflight connectivity standards are creating regulatory pathways for aeronautical broadband services.
Industry Challenges
- GaN-on-SiC Fabrication Talent Scarcity:Compound semiconductor manufacturing expertise for power amplifiers remains concentrated among a handful of UK facilities.
- Legacy Geostationary Integration Complexity:New low Earth orbit constellations must interoperate with existing Inmarsat infrastructure serving maritime and aviation clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Satellite Communications Market |
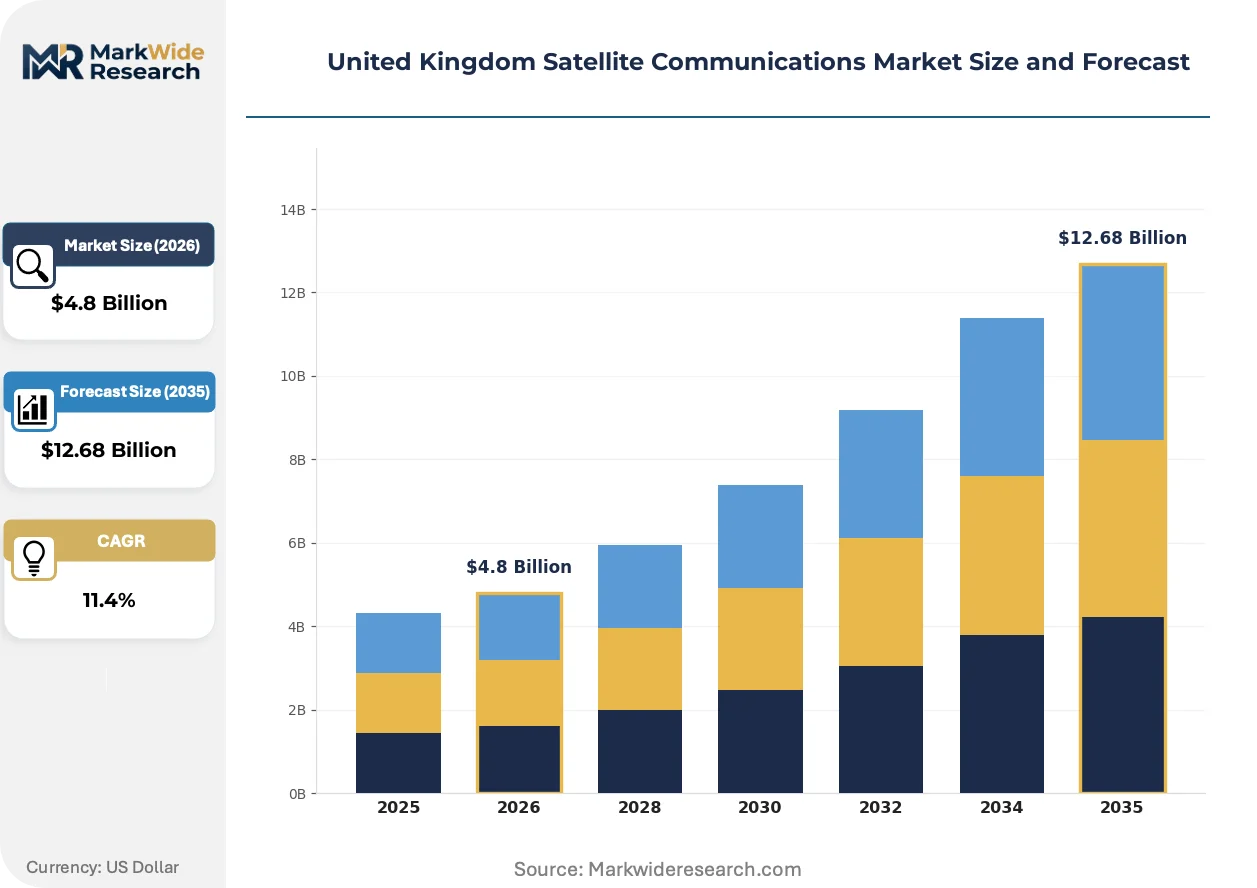
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellite Systems, Ground Equipment, User Terminals, Signal Processors Application: Defense, Broadcasting, Telecommunication, Remote Sensing End User: Government, Commercial, Aerospace, Maritime Technology: Ka-band, Ku-band, C-band, Laser Communication |
| Companies Covered | L3Harris Technologies Inc, Avanti Communications, Surrey Satellite Technology Limited (SSTL), Airbus Defence and Space Ltd, SES SA, OneWeb, Viasat Inc, Peak Communications Ltd, Inmarsat Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Satellite Communications Market Trends and Innovations
Radio frequency technology substitution and spectrum policy reforms are restructuring how British satellite manufacturers design payloads and price services across defense and commercial segments.
GaN-on-SiC power amplifiers deliver higher efficiency and thermal performance for high-throughput satellite payloads. The Ministry of Defence and commercial constellation operators are adopting these solid-state devices for new procurements. This technology is overtaking traveling-wave tube amplifiers in cost-sensitive applications while enabling smaller satellite form factors.
Ofcom's mm-wave spectrum consultations are preparing framework revisions for Q-band and V-band allocation. British satellite operators are positioning for additional capacity expansion beyond current Ka-band deployments. Military end users anticipate priority access rights under national security provisions.
Maritime and aviation clients are unbundling terminal hardware from connectivity service contracts. Satellite operators are responding with managed service offerings that shift capital expenditure to recurring operational expenditure models. This transition is most visible among North Sea shipping operators and British Airways long-haul fleet procurement.
United Kingdom Satellite Communications Market Segmentation
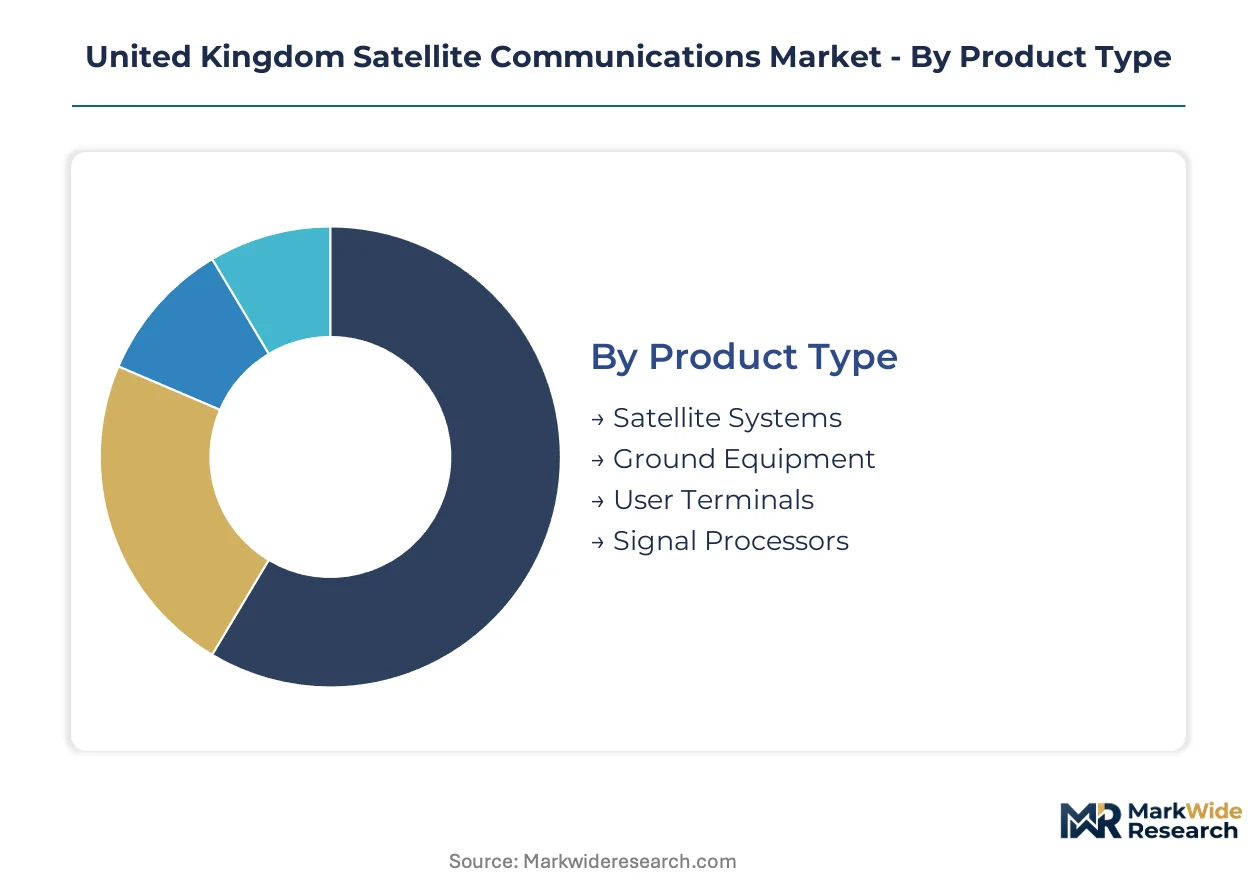
Segmentation reveals how capital allocation and regulatory exposure diverge across the United Kingdom satellite communications value chain. Product architecture and frequency band selection determine upfront investment thresholds and licensing timelines for British operators.
Product Type:
Capital intensity peaks with satellite systems requiring orbital deployment, while ground equipment and user terminals demand manufacturing scale rather than launch expenditure.
- Satellite Systems:Complete orbital platforms integrate payloads, power subsystems, and propulsion for geostationary or low Earth orbit deployment. The Ministry of Defence procurement programs concentrate demand in Portsmouth and Stevenage manufacturing clusters, where sovereign capability requirements extend development timelines.
- Ground Equipment:Earth stations and gateway infrastructure manage signal uplink, downlink, and network coordination across British territories. Scotland's space cluster around Glasgow aggregates integration facilities for these systems, driven by Ofcom's spectrum liberalization mandates.
- User Terminals:Flat-panel and parabolic antennas deliver last-mile connectivity to end customers.
- Signal Processors:Onboard and ground-based units handle modulation, demodulation, and encryption functions.
Most installed capacity flows through Satellite Systems. Expansion is steepest in Ground Equipment.
Application:
Defense applications command premium pricing through encrypted military-grade specifications, while broadcasting and telecommunication segments compete on bandwidth efficiency and service reliability.
- Defense:Secure military communications mandate anti-jam waveforms, nuclear-hardened components, and sovereign supply chain verification. The Ministry of Defence's procurement expansion drives demand for British-manufactured terminals with classified encryption standards.
- Telecommunication:Broadband satellite services deliver connectivity to underserved regions across the Scottish Highlands, Welsh valleys, and offshore installations. OneWeb's constellation deployment from Cornwall Spaceport accelerates coverage expansion for rural enterprises.
- Broadcasting:Direct-to-home television and radio distribution utilize geostationary capacity.
- Remote Sensing:Earth observation payloads support environmental monitoring and agricultural analytics.
Defense captures the highest revenue per terminal. Telecommunication is expanding most quickly.
End User:
Government end users impose stringent certification requirements that extend sales cycles, while commercial maritime and aerospace clients prioritize service continuity over capital expenditure minimization.
- Government:Civil and military agencies require encrypted, sovereign-controlled infrastructure for national security communications. The UK Space Agency's orbital debris mitigation requirements under the Space Industry Act 2018 shape procurement specifications for government satellite programs.
- Maritime:Commercial shipping operators in the North Sea and transatlantic routes demand uninterrupted broadband for crew welfare and operational efficiency. Inmarsat's geostationary fleet anchors service delivery through subscription-based connectivity models replacing terminal ownership.
- Commercial:Enterprise and consumer broadband subscribers purchase connectivity services.
- Aerospace:Airlines and business aviation operators seek inflight connectivity certification from the Civil Aviation Authority.
Government contracts concentrate procurement authority. Maritime subscriptions are climbing the fastest.
Technology:
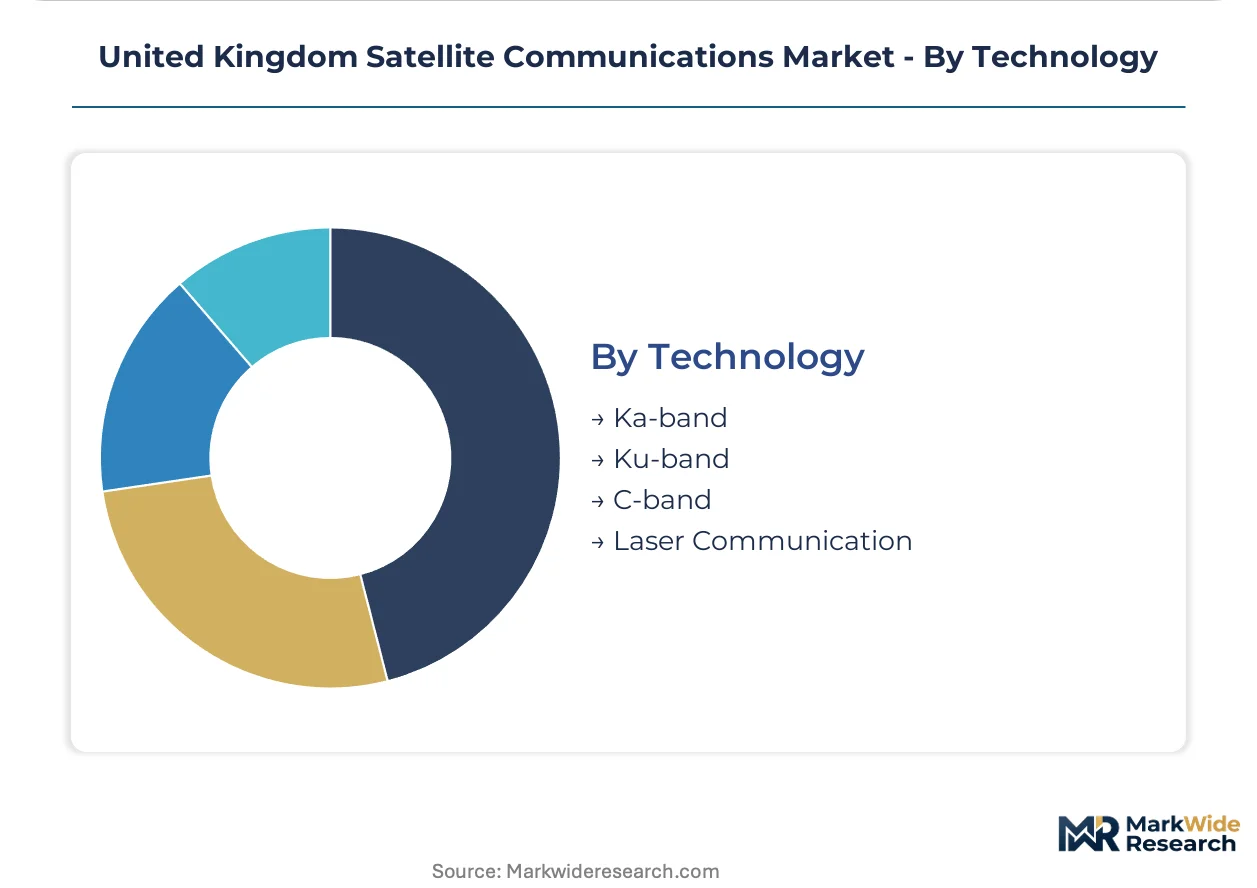
Frequency band selection determines spectrum licensing costs, rain fade susceptibility, and antenna form factor constraints across British deployment scenarios.
- Ka-band:High-frequency spectrum enables high-throughput broadband with compact user terminals. Ofcom's spectrum allocation reforms are accelerating Ka-band deployment authorization across British territories, displacing legacy Ku-band infrastructure for rural connectivity programs.
- Laser Communication:Optical inter-satellite links deliver terabit-scale capacity with minimal spectrum licensing burden. Precision pointing acquisition mechanisms remain unproven at constellation scale, constraining near-term deployment for British operators.
- Ku-band:Established frequency range supports broadcast and broadband applications with proven terminal economics.
- C-band:Lower frequencies provide rain-resilient connectivity for maritime and tropical applications.
Ku-band carries the majority of active throughput. Ka-band is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland's space cluster around Glasgow and Prestwick anchors United Kingdom satellite communications development, concentrating launch infrastructure, payload integration facilities, and specialized engineering talent pools that service both military and commercial demand streams.
Scotland
Glasgow manufactures more satellites than any other European city, with Clyde Space and Spire Global operating production lines for CubeSats and smallsats. The UK Space Agency's Space Industry Act 2018 licensing framework accelerates orbital deployment authorization from Prestwick's proposed spaceport. Scottish Enterprise coordinates public funding for vertical launch sites in Sutherland and horizontal launch capabilities at Prestwick Airport.
England — South
Airbus Defence and Space Ltd maintains sovereign manufacturing capability at its Portsmouth facility for military and civil satellite platforms. Ofcom's Wireless Telegraphy Act reforms reallocate Ka-band spectrum rights between Ministry of Defence and commercial broadband operators. Cornwall Spaceport at Newquay hosts Virgin Orbit horizontal launches for OneWeb constellation deployment.
England — East
Inmarsat Plc operates geostationary fleet management from its London headquarters, serving maritime and aviation subscription clients across transatlantic routes. The Civil Aviation Authority certifies aeronautical terminals for inflight connectivity services under evolving safety standards. Stevenage hosts Airbus satellite integration facilities alongside QinetiQ defense research campuses.
Wales
South Wales valleys present underserved broadband demand that satellite telecommunication services target through rural connectivity programs. Welsh Government innovation funding supports ground equipment manufacturing for Ka-band terminal deployment. Cardiff University research centers advance signal processing algorithms for interference mitigation in congested spectrum environments.
Northern Ireland
Belfast's aerospace heritage translates into satellite subcomponent supply for UK prime contractors, with Thales Alenia Space operating precision manufacturing facilities. Invest Northern Ireland coordinates foreign direct investment for space technology transfer from Scottish and English clusters. Queen's University Belfast specializes in antenna design for user terminal miniaturization.
United Kingdom Satellite Communications Market Competitive Landscape
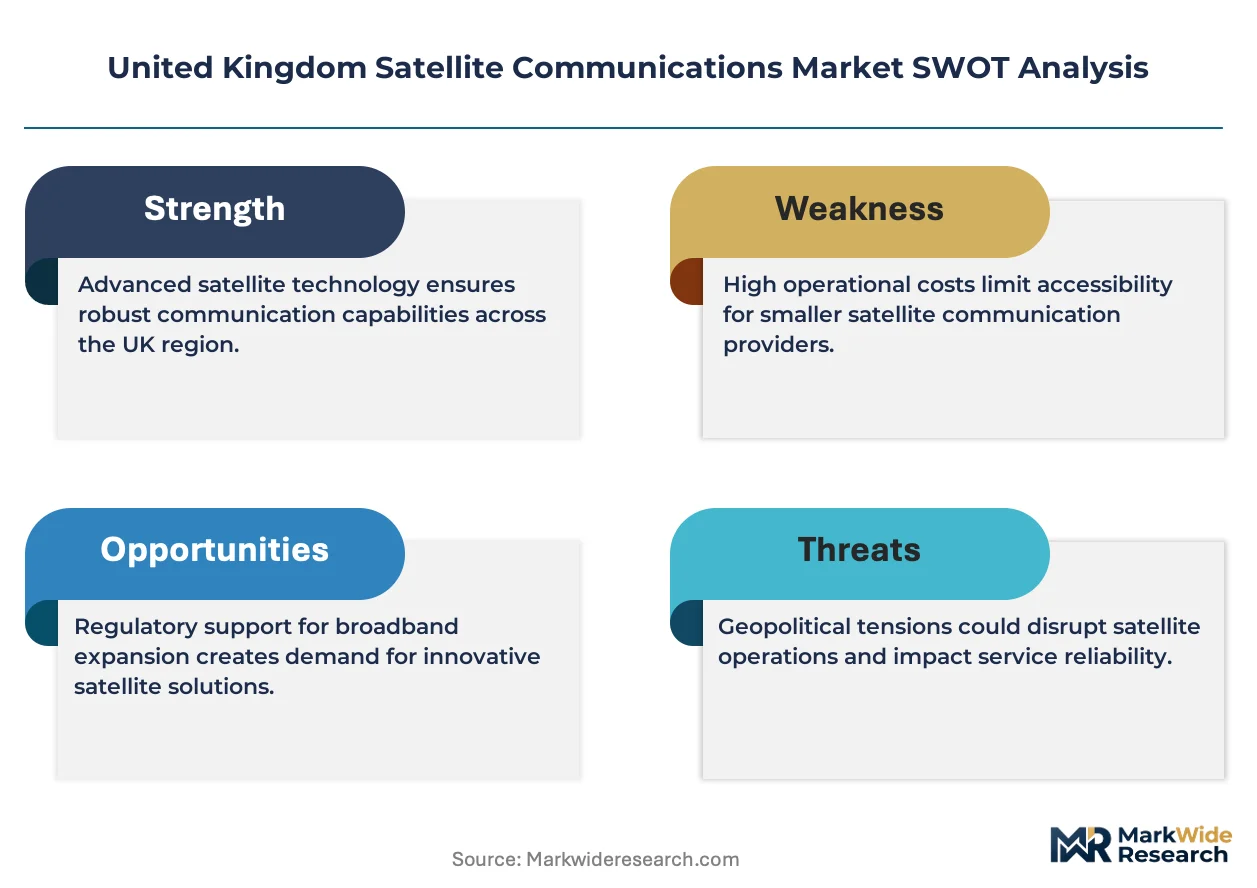
Strategic partnerships dominate the current landscape as constellation operators seek sovereign manufacturing partnerships and spectrum coordination agreements. The United Kingdom satellite communications market structures around three tiers: vertically integrated primes with Ministry of Defence contracts, mid-scale specialists in payload components, and emerging low Earth orbit constellation operators. Defense procurement programs favor established primes with security clearances, while commercial broadband segments reward agile operators with rapid deployment capabilities. Competitive moves concentrate on capacity expansion through new manufacturing facilities and technology licensing for GaN-on-SiC power amplifier substitution.
Among defense-oriented primes, Airbus Defence and Space Ltd and L3Harris Technologies Inc occupy positions exemplifying sovereign capability requirements, while Inmarsat Plc represents the geostationary service incumbent transitioning toward hybrid constellation architectures. OneWeb anchors the low Earth orbit segment with its Cornwall deployment pathway, illustrating how new entrants bypass legacy infrastructure dependencies through dedicated launch agreements.
| Leading Market Players |
|---|
| L3Harris Technologies Inc |
| Avanti Communications |
| Surrey Satellite Technology Limited (SSTL) |
| Airbus Defence and Space Ltd |
| SES SA |
| OneWeb |
| Viasat Inc |
| Peak Communications Ltd |
| Inmarsat Plc |
| Others |
Pricing and Supply Chain Analysis
Captive manufacturing of GaN-on-SiC power amplifiers at Airbus Defence and Space Ltd's Portsmouth facility anchors both supply security and pricing power for British satellite manufacturers serving Ministry of Defence procurement programs. This backward integration into compound semiconductor fabrication insulates prime contractors from traveling-wave tube supply concentration while enabling premium pricing for sovereign-certified payloads.
Pricing Analysis
Input-cost pass-through from gallium nitride substrate scarcity is intensifying pricing pressure across high-throughput satellite payloads, though Ministry of Defence contracts partially absorb these shocks through cost-plus structures. Three-tier pricing structure across military-grade encrypted terminals, commercial maritime subscriptions, and rural broadband consumer packages stratifies the market. Price differentiation hinges on certification level under UK Space Agency orbital debris standards and volume scale of constellation deployment. Cost compression in commercial maritime terminals is accelerating because shipping operators are unbundling hardware ownership from managed service contracts.
Supply Chain Analysis
Reverse-logistics flows for satellite component refurbishment remain underdeveloped across the United Kingdom, with end-of-life traveling-wave tube amplifiers typically scrapped rather than remanufactured due to radiation-hardening degradation. Geographic supply concentration centers on the United States for GaN-on-SiC substrates, Germany for precision antenna components, and Japan for radiation-hardened integrated circuits. Raw material dependencies include rare earth elements for magnetic subsystems, high-purity silicon carbide wafers, and specialty alloys for thermal management. Single-source vulnerability in compound semiconductor fabrication creates procurement risk for British payload manufacturers. Distribution runs through direct prime contractor relationships with government agencies and long-term service contracts with maritime fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom satellite communications market compounds regulatory tailwinds from Ofcom's Ka-band spectrum liberalization and the Space Industry Act 2018 licensing framework into sustained demand expansion for sovereign manufacturing capabilities.
For Market Incumbents: Hedge against GaN-on-SiC fabrication talent scarcity by securing captive supply agreements with Scottish semiconductor facilities before competitor lock-up. Incumbents should accelerate vertical integration into laser communication pointing acquisition mechanisms to preempt emerging low Earth orbit constellation operators from eroding geostationary service margins. Ministry of Defence procurement concentration creates customer dependency risk that demands diversification into commercial maritime managed services. For New Entrants and Emerging Players: Ofcom's mm-wave spectrum consultations in the United Kingdom open a window for Q-band and V-band positioning ahead of incumbent frequency migration. New entrants should target Welsh rural broadband connectivity programs as the most penetrable geography, leveraging Cardiff University signal processing research for interference mitigation capabilities. A direct go-to-market angle through local authority digital infrastructure partnerships bypasses established prime contractor channel control. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale payload component specialists because Ministry of Defence sovereign capability requirements fragment manufacturing across multiple sub-tier suppliers. Long-term viability centers on five-to-ten year orbital deployment windows where launch cost compression and satellite miniaturization converge. The acquisition target archetype is Scottish CubeSat manufacturers with established UK Space Agency licensing relationships. The signal to monitor is Cornwall Spaceport launch cadence acceleration as an inflection indicator for constellation operator capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Manufacturing Scale-Up | Airbus Portsmouth facility expansion solidifies sovereign amplifier supply for Ministry of Defence programs. |
| Cornwall Spaceport Launch Agreement | OneWeb's dedicated horizontal launch pathway eliminates foreign facility dependency for constellation deployment. |
| Maritime Managed Service Transition | Inmarsat subscription model shift captures recurring revenue from North Sea shipping operators. |
| Ka-band Spectrum Certification | Ofcom authorization enables broadband service expansion across Scottish Highlands and Welsh valleys. |
| Laser Communication R&D Partnership | Precision pointing acquisition development addresses inter-satellite link maturity gaps for next-generation constellations. |
Research Methodology
Direct dialogue with satellite payload engineers, Ministry of Defence procurement officers, Ofcom spectrum licensing specialists, and maritime fleet connectivity managers grounded qualitative insights in operational reality. Secondary validation drew from UK Space Agency orbital deployment filings, Ofcom Wireless Telegraphy Act consultation documents, Civil Aviation Authority terminal certification records, and Cornwall Spaceport launch manifests. Bottom-up and top-down triangulation reconciled manufacturer capacity data with end-user demand signals across defense, maritime, and rural broadband segments.
Bottom-up modeling aggregated individual satellite system, ground equipment, and terminal unit economics across product type and application dimensions, while top-down analysis calibrated aggregate market expansion against Ministry of Defence budget allocations and commercial constellation operator capital expenditure disclosures. Segmentation dimensions included orbital altitude architecture, frequency band selection, end-user procurement authority, and technology maturity tier. CAGRs were derived from fitted growth curves against historical deployment trajectories and regulatory milestone timing. Industry-specific forecast inputs incorporated launch cost elasticity and spectrum licensing queue depths.
Revisions become necessary when Ofcom spectrum allocation decisions, UK Space Agency debris mitigation requirement changes, or Ministry of Defence procurement timeline shifts materialize differently than modeled assumptions anticipate. Forecasts reflect documented expectations regarding GaN-on-SiC substitution rates and Cornwall Spaceport operational ramp schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
Middle East Satellite-Based Earth Observation Market
Satellite
Communication Satellite Launch Services Market
Satellite
Global Satellite Modem Market
Satellite
North America Remote Sensing Satellites Market
Satellite
Satellite Parts and Components Market
Satellite
Broadband Satellite System Market
Satellite
North America Satellite IoT Market
Satellite
Commercial Satellite Launch Service Market
Satellite
Japan Satellite Connectivity Market
Satellite
Europe Satellite Manufacturing and Launch Systems Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Earth Observation Satellite Market
Satellite
Asia-Pacific Small Satellite Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market