
 Asia-Pacific Satellite Bus Market | 2026-2036
Asia-Pacific Satellite Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Satellite Bus Market Insights
Standardized platform architectures is reconfiguring how satellite buses are engineered for multi-mission adaptability across the Asia-Pacific. Mitsubishi Electric leverages deep vertical integration in power and thermal subsystems to anchor its position in Japanese government programs. China Academy of Space Technology sustains manufacturing scale through captive supply chains serving domestic constellation deployments. ISRO Satellite Centre competes on cost-optimized bus designs for international launch services.
A satellite bus comprises the structural frame, power distribution, thermal management, propulsion, attitude control, and telemetry systems that support the payload without direct mission-specific instrumentation; modern buses in this region integrate gallium nitride power electronics and autonomous fault-management firmware to extend operational life beyond fifteen years in LEO or GEO orbits. Small Satellites dominate volume shipments as commercial operators deploy dense constellations for Earth observation and telecommunications. Propulsion Systems technology captures concentrated margin pools where electric thruster adoption reduces wet mass and extends station-keeping duration. Civil Government end users represent the fastest-growing demand segment as national meteorological and disaster-management agencies procure dedicated bus platforms.
China's MIIT enforces GB standards for electromagnetic compatibility and orbital debris mitigation that dictate bus design verification protocols for domestic manufacturers. India's ISRO and Japan's METI coordinate spectrum allocation and launch licensing frameworks that shape market access timelines for commercial bus providers. Australia's Space Agency and South Korea's MFDS are developing sovereign certification pathways that will fragment compliance requirements across the region. Stakeholders must monitor which regulatory jurisdiction captures de facto standard-setting authority for inter-satellite link protocols and refueling interface specifications.
Market Dynamics
Standardized bus architectures are compressing development cycles across Asia-Pacific as constellation operators demand rapid reconfigurability between Earth observation, telecommunications, and navigation payloads.
Growth Catalysts
- India's PLI scheme for space manufacturing:Production-linked incentives are accelerating domestic component ecosystems for satellite buses, reducing import dependency for power distribution modules.
- Commercial Earth observation constellations:Dense LEO deployments by private operators are generating sustained procurement volume for small satellite bus platforms optimized for rapid revisit cycles.
- Gallium nitride power electronics:Wide-bandgap semiconductor adoption is extending operational life beyond fifteen years while reducing thermal management mass.
Market Restraints
- Propulsion system supply concentration:Electric thruster manufacturing concentrates among limited qualified suppliers, creating bottleneck risk for constellation scale-up timelines.
- GB standards compliance overhead:China's MIIT electromagnetic compatibility verification protocols extend qualification periods for non-domestic bus components seeking market access.
- Launch cost volatility:Ride-share pricing uncertainty compresses bus procurement budgets and delays fleet deployment commitments.
Strategic Opportunities
- South Korea's sovereign certification pathway:MFDS orbital debris mitigation standards will create first-mover advantage for bus manufacturers achieving early compliance.
- Autonomous fault-management firmware:Machine learning-driven anomaly detection convergence with existing telemetry systems enables reduced ground segment staffing for commercial operators.
- Australia's civil government meteorological procurement:Dedicated bus platforms for disaster management agencies represent underpenetrated demand within national space programs.
Industry Challenges
- Attitude control specialist scarcity:Precision pointing algorithm development requires rare cross-training in orbital mechanics and embedded systems engineering.
- Inter-satellite link protocol fragmentation:Competing optical and RF interface specifications across Chinese, Indian, and Japanese programs complicate multi-national constellation integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Satellite Bus Market |
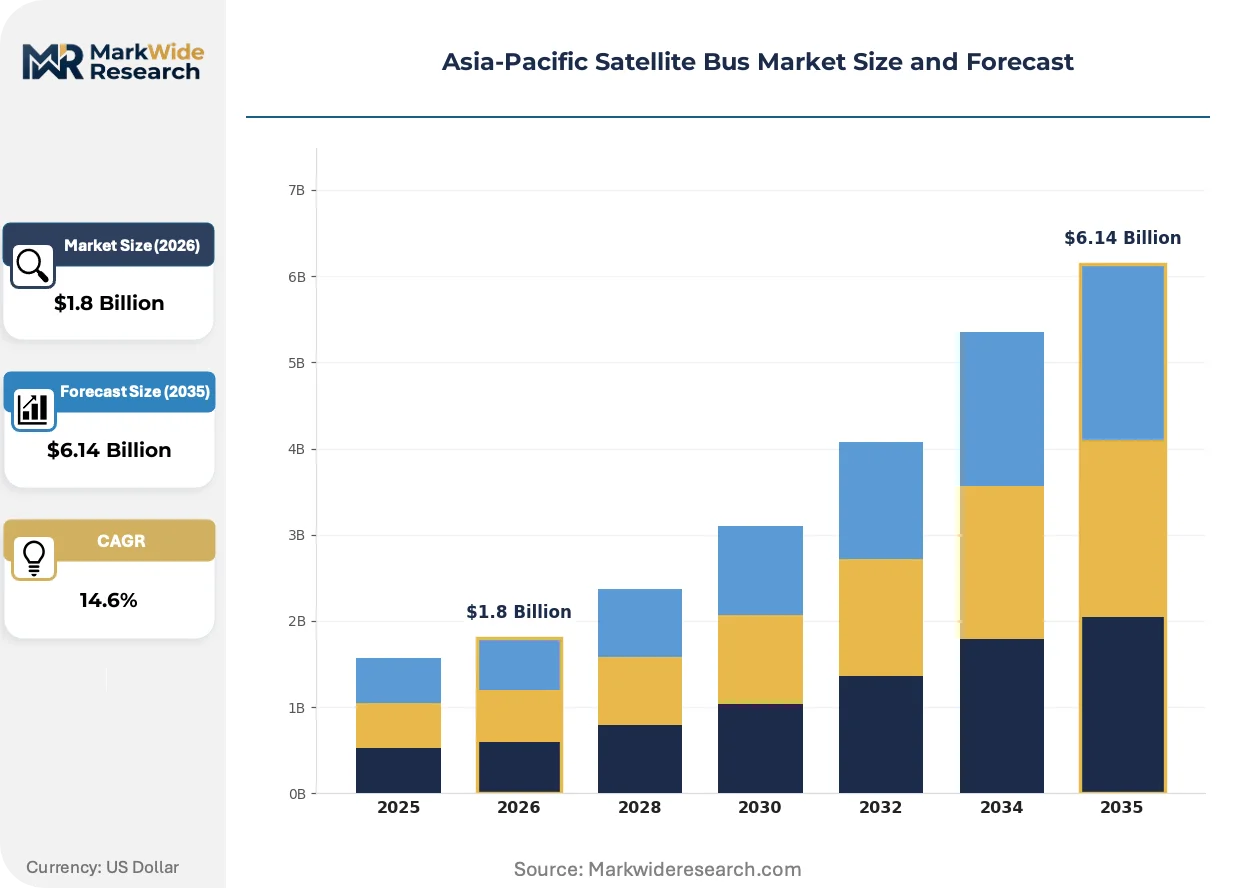
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Satellites, Medium Satellites, Large Satellites, Communication Satellites Technology: Thermal Control, Power Systems, Propulsion Systems, Payload Integration End User: Defense, Civil Government, Commercial, Research Institutions Application: Earth Observation, Telecommunications, Scientific Research, Navigation |
| Companies Covered | NEC Corporation, Lockheed Martin Corporation, Mitsubishi Electric, Thales Group, Northrop Grumman Corporation, China Academy of Space Technology, Airbus SE, Astroscale, ISRO Satellite Centre, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Satellite Bus Market Trends and Innovations
Digital engineering workflows are compressing satellite bus design cycles from conceptualization to qualification across Asia-Pacific manufacturing facilities.
Model-based systems engineering is digitizing requirements traceability from structural frame specification through thermal vacuum testing. Chinese constellation operators are adopting these toolchains fastest, collapsing traditional document-based handoff delays between subsystem teams. This compression is digitizing competitive differentiation around delivery speed rather than hardware performance alone.
Japan's METI has tightened spectrum allocation frameworks for inter-satellite links, mandating coordination with domestic constellation licensing windows. This policy is forcing commercial bus providers to pre-integrate multi-band RF payloads during manufacturing rather than post-delivery customization. Small satellite operators in Tokyo and Osaka metropolitan clusters are responding by consolidating procurement with vertically integrated bus suppliers capable of in-house RF subsystem qualification.
Buying committees at civil government agencies are unbundling after-sales engineering support from initial bus procurement contracts. Commercial operators in India are replacing traditional long-term service agreements with pay-per-anomaly troubleshooting arrangements. This behavioral shift is most visible in ISRO's commercial arm, where international launch customers now demand modular support tiers keyed to mission criticality rather than blanket coverage.
Asia-Pacific Satellite Bus Market Segmentation
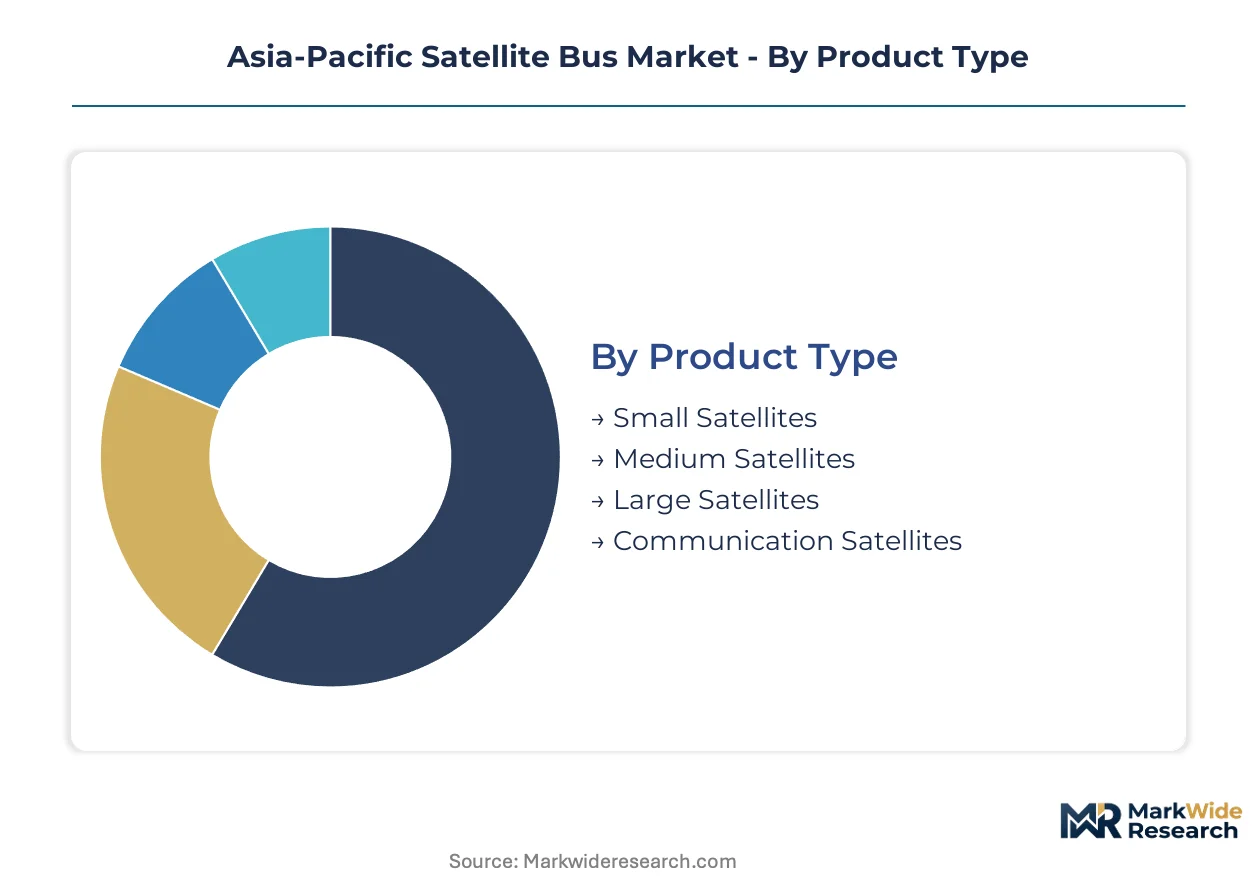
Asia-Pacific satellite bus procurement patterns fragment sharply across mass classes and mission profiles, with constellation density requirements and national security specifications driving divergent platform specifications. Manufacturers must architect production lines capable of spanning sub-100 kg small satellite volume runs through heavy geostationary platforms without losing subsystem commonality.
Product Type:
Mass class and payload capacity tier determines thermal management complexity, propulsion wet mass allocation, and structural frame material selection across Asia-Pacific procurement.
- Small Satellites:Platforms under 500 kg dominate constellation deployment volumes, with standardized aluminum honeycomb structures and fixed solar arrays reducing unit costs. China's commercial Earth observation operators in Beijing and Hangzhou are procuring these platforms in batch quantities exceeding fifty units annually.
- Medium Satellites:The 500-2,500 kg class balances payload flexibility with launch vehicle compatibility, incorporating deployable radiators and bipropellant propulsion for multi-mission reconfigurability. India's ISRO Satellite Centre optimizes these designs for polar launch services serving Southeast Asian meteorological agencies.
- Large Satellites:Heavy platforms exceed 2,500 kg with high-power bus architectures supporting synthetic aperture radar and advanced telecommunications payloads.
- Communication Satellites:Dedicated bus variants integrate high-gain antenna pointing mechanisms and extended station-keeping propulsion for geostationary service.
Small Satellites holds installed capacity. Medium Satellites is rotating up the share rankings.
Technology:
Subsystem technology selection governs operational life, fault tolerance, and cross-platform compatibility for multi-orbit deployments.
- Thermal Control:Multi-layer insulation blankets, heat pipes, and louvers maintain payload temperature stability across eclipse cycles. Japanese government programs specify proprietary thermal interface materials that complicate supplier qualification for international bus integrators.
- Power Systems:Gallium nitride-based power conditioning and distribution modules extend operational life while reducing mass. China's MIIT GB standards mandate electromagnetic compatibility verification that extends qualification timelines for non-domestic component suppliers.
- Propulsion Systems:Electric thruster adoption concentrates manufacturing among qualified suppliers, creating supply risk for constellation scale-up.
- Payload Integration:Standardized mechanical and electrical interfaces enable rapid payload swap between Earth observation and telecommunications missions.
Power Systems commands subsystem margin concentration. Propulsion Systems is climbing the fastest as electric thruster adoption accelerates.
End User:
Customer type shapes procurement contracting structures, security classification requirements, and aftermarket support expectations.
- Defense:Classified mission specifications drive hardened bus architectures with encrypted telemetry and anti-jam capabilities. Australia's Department of Defence is procuring sovereign small satellite buses for signals intelligence under accelerated acquisition pathways.
- Civil Government:Meteorological and disaster-management agencies represent expanding procurement volume with transparent budgeting cycles. Japan's JAXA and India's ISRO are deploying dedicated buses for climate monitoring constellations with fifteen-year design lives.
- Commercial:Constellation operators prioritize unit economics and rapid revisit cycles over extended operational life.
- Research Institutions:University and laboratory missions demand configurable bus platforms with educational payload accommodation.
Defense holds legacy platform inventory. Civil Government is expanding most quickly as national space programs mature.
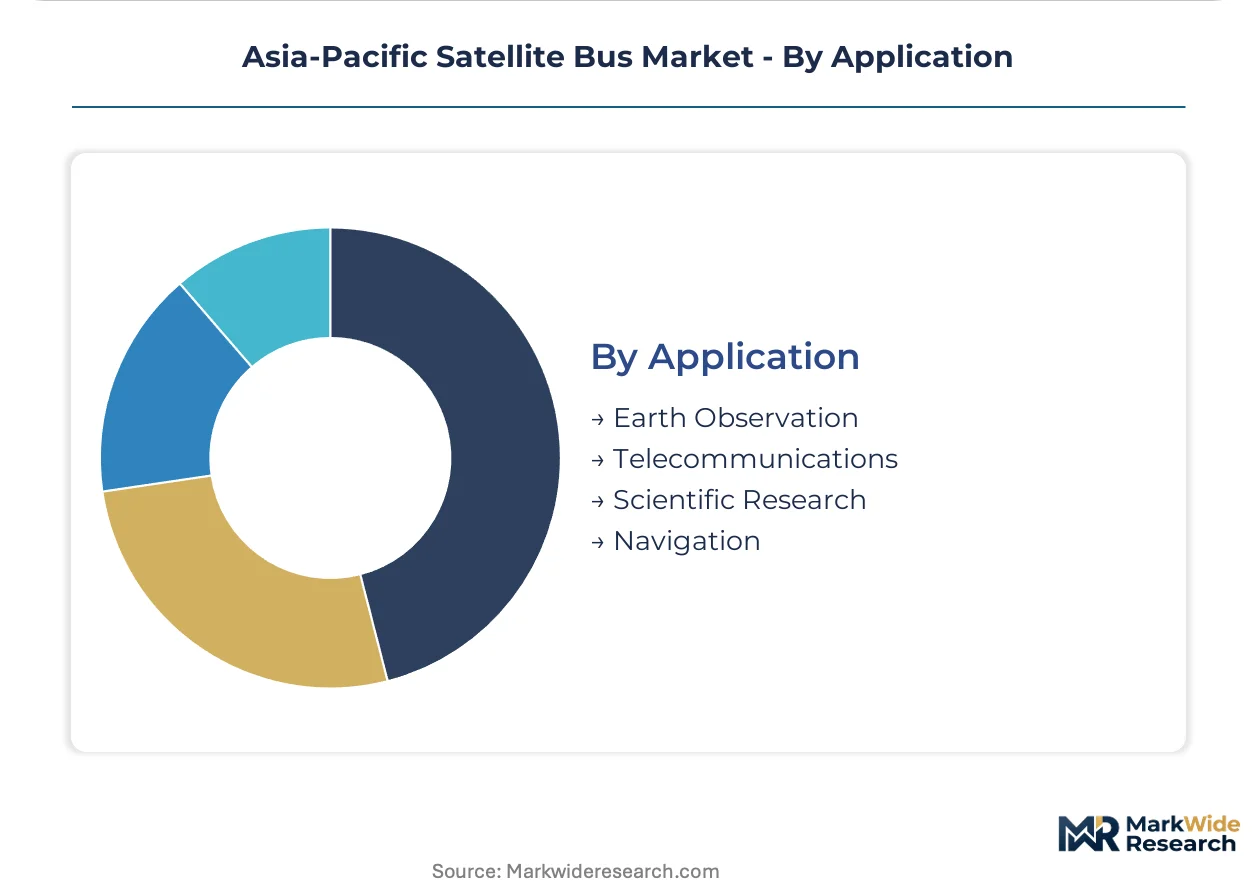
Application:
Mission function determines orbital regime selection, payload sensor specifications, and ground segment integration complexity.
- Earth Observation:Optical and synthetic aperture radar payloads require precise attitude control and high-data-rate downlink capacity. Chinese commercial operators in Shenzhen and Chengdu are deploying dense LEO constellations for agricultural and urban monitoring with sub-daily revisit.
- Telecommunications:Broadband and narrowband relay missions drive high-power bus architectures with inter-satellite link compatibility. South Korea's KT Sat and Japan's Sky Perfect JSAT are procuring platforms with optical laser communications for low-latency backhaul.
- Scientific Research:Space weather and astronomy missions impose unique pointing stability and contamination control requirements.
- Navigation:Precise timing payload integration demands atomic clock thermal stability and redundant timing distribution.
Earth Observation holds active constellation deployment. Telecommunications is gaining share fastest as regional broadband demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese satellite bus manufacturers export precision thermal control subsystems to Australian civil government programs, establishing a technology corridor that channels advanced componentry across the Tasman Sea.
China
Domestic constellation operators in Beijing and Hangzhou procure small satellite buses in batch quantities exceeding fifty units annually for Earth observation networks. MIIT enforces GB standards for electromagnetic compatibility and orbital debris mitigation that dictate design verification protocols for all domestic manufacturers. The Yangtze River Delta hosts captive supply chains serving these constellation deployments with gallium nitride power electronics and autonomous fault-management systems.
India
ISRO Satellite Centre optimizes medium-class bus designs for polar launch services serving Southeast Asian meteorological agencies. The PLI scheme for space manufacturing accelerates domestic component ecosystems for power distribution modules, reducing import dependency. Bengaluru's aerospace cluster concentrates design engineering talent for cost-optimized platforms competing in international launch markets.
Japan
METI tightened spectrum allocation frameworks for inter-satellite links, mandating coordination with domestic constellation licensing windows. Mitsubishi Electric leverages deep vertical integration in power and thermal subsystems to anchor its position in government programs. Tokyo and Osaka metropolitan clusters consolidate procurement with vertically integrated bus suppliers capable of in-house RF subsystem qualification.
South Korea
KT Sat procures platforms with optical laser communications for low-latency telecommunications backhaul. MFDS develops sovereign certification pathways for orbital debris mitigation standards that will create first-mover advantage for early-compliant manufacturers. Busan-Ulsan industrial corridors concentrate electric thruster subsystem suppliers facing supply concentration risks.
Australia
The Department of Defence procures sovereign small satellite buses for signals intelligence under accelerated acquisition pathways. The Australian Space Agency develops sovereign certification pathways that fragment compliance requirements across the region. New South Wales hosts emerging bus integrators targeting civil government meteorological procurement for disaster management agencies.
Asia-Pacific Satellite Bus Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The market structure consolidates around vertically integrated defense contractors and national space agency production arms, with limited independent commercial specialists achieving scale. Three archetypes dominate: captive government program suppliers, constellation-dedicated volume manufacturers, and subsystem-technology licensors. Competitive moves concentrate on strategic partnerships for launch access and portfolio diversification into adjacent orbital services.
Among Japanese and South Korean fabricators, Mitsubishi Electric and NEC Corporation exemplify the captive government program supplier archetype through sustained anchor positions in national space agency procurement. China Academy of Space Technology represents the constellation-dedicated volume manufacturer model, sustaining manufacturing scale through domestic deployment commitments. ISRO Satellite Centre occupies a distinctive cost-optimized position serving international launch customers with medium-class platforms.
| Leading Market Players |
|---|
| NEC Corporation |
| Lockheed Martin Corporation |
| Mitsubishi Electric |
| Thales Group |
| Northrop Grumman Corporation |
| China Academy of Space Technology |
| Airbus SE |
| Astroscale |
| ISRO Satellite Centre |
| Others |
Pricing and Supply Chain Analysis
Electric thruster manufacturing concentrates in Busan-Ulsan industrial corridors and select Japanese precision fabricators, anchoring margin pools in propulsion subsystem tiers where constellation operators face limited supplier alternatives. This upstream concentration cascades into downstream pricing power for qualified electric propulsion integrators serving commercial LEO deployments.
Pricing Analysis
Prior-generation silicon-based power electronics, current-generation gallium nitride modules, and next-generation wide-bandgap architectures stratify across premium, standard, and economy tiers. Bus procurement follows contract-based long-term offtake structures with volume scale and certification grade as primary price differentiation drivers. Cost compression in small satellite platforms intensifies as Chinese constellation operators consolidate batch procurement exceeding fifty units annually. Civil government agencies exhibit least price sensitivity due to fifteen-year design life requirements, while commercial Earth observation operators prioritize unit economics.
Supply Chain Analysis
Extended payment terms from constellation operators to bus integrators strain working capital cycles, prompting supply-chain finance facilities among South Korean component suppliers. Manufacturing draws from China for gallium nitride power electronics, Japan for precision thermal control materials, and India for cost-optimized structural assemblies. Single-source vulnerability concentrates in electric thruster qualified suppliers. Distribution runs through national space agency procurement arms and direct commercial contracts with constellation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as inter-satellite link protocol divergence between Chinese, Indian, and Japanese programs creates specialized integration niches for protocol-agnostic bus architectures.
For Market Incumbents: Insulate market position through backward integration into gallium nitride power electronics manufacturing and captive qualification of electric thruster alternatives. Threat of propulsion system supply concentration demands upstream control over critical wet mass components. Certification investment in South Korea's MFDS orbital debris standards creates channel control advantages. For New Entrants and Emerging Players: Pursue Australia's civil government meteorological procurement segment where sovereign certification pathways remain underpenetrated. Disaster management agencies in New South Wales represent accessible demand with transparent budgeting cycles. Go-to-market angle centers on modular support tiers replacing traditional long-term service agreements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed constellation-dedicated volume manufacturers facing domestic deployment commitment maturities. Long-term viability over five-to-ten year windows hinges on multi-orbit platform reconfigurability. Signal to watch: autonomous fault-management firmware adoption rates as indicator of ground segment staffing reduction demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Gallium nitride module manufacturing captures margin pools concentrated in Chinese Yangtze River Delta suppliers. |
| Multi-Orbit Platform Standardization | Reconfigurable bus architectures reduce development cycles for Earth observation and telecommunications payload swaps. |
| Autonomous Fault-Management Firmware Development | Machine learning-driven anomaly detection enables reduced ground segment staffing for commercial constellation operators. |
| Sovereign Certification Pathway Investment | Early compliance with South Korea's MFDS orbital debris standards creates first-mover advantage in regional procurement. |
| Optical Inter-Satellite Link Pre-Integration | METI spectrum coordination requirements force RF subsystem qualification during manufacturing rather than post-delivery customization. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with satellite bus program managers, constellation procurement leads, launch service integrators, and subsystem engineering directors; and secondary validation against ISRO deployment manifests, MIIT GB standard filings, METI spectrum allocation records, and customs trade data for gallium nitride component flows. Bottom-up unit shipment estimates triangulated with top-down national space budget allocations across the analysis window.
Forecast inputs span mass class segmentation, subsystem technology tiers, end-user procurement structures, and orbital regime application profiles. CAGRs derive from modeled deployment timelines for commercial Earth observation constellations and civil government meteorological programs. Industry-specific inputs include electric thruster manufacturing capacity constraints and autonomous fault-management firmware adoption curves.
Macroeconomic conditions sit as an overlay; deviation in launch cost volatility and ride-share pricing uncertainty would shift the trajectory. Forecasts reflect documented assumptions regarding constellation deployment commitments and regulatory standard-setting timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Nanosatellite and Microsatellite Market
Satellite
Satellite Communication System Market
Satellite
Asia-Pacific Satellite Connectivity Market
Satellite
India Satellite Connectivity Market
Satellite
GEO Satellite Market
Satellite
UAE Satellite Communication Market
Satellite
Satellite Communications Service Market
Satellite
Argentina Satellite Imagery Services Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
Satellite Communication Equipment Market
Satellite
Satellite GPS Receivers Market
Satellite
Commercial Satellite Launch Service Market
Satellite
Satellite Connectivity Market
Satellite
Asia-Pacific Satellite IoT Market
Satellite
Africa Satellite Connectivity Market
Satellite
North America Mobile Satellite Services Market