
 Satellite Market | 2026-2036
Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Market Analysis
Defense agencies is unwinding legacy geostationary contracts in favor of proliferated low-Earth-orbit architectures. SpaceX leverages full vertical integration from rocket production to constellation operations to undercut legacy launch economics. Lockheed Martin Corporation anchors classified government demand through hardened payload integration and secure ground segment control. Airbus Defence and Space competes across dual-use European programs with sovereign manufacturing lines in France and Germany.
A satellite is an artificial object placed into orbit around Earth or another celestial body, typically weighing between one kilogram for CubeSats to over six metric tons for geostationary communications platforms, constructed from aluminum-lithium alloys, composite panels, and gallium arsenide solar cells, designed to relay signals, capture imagery, or broadcast positioning data across continental distances. Communication Satellites still generate the bulk of revenue through transponder leasing and broadband services, though Earth Observation Satellites are narrowing the gap as insurance, agriculture, and urban planning buyers subscribe to tasking-based imagery models rather than owning dedicated assets. Low Earth Orbit technology is displacing Geostationary Orbit dominance for latency-sensitive applications, while Medium Earth Orbit retains its structural role for navigation constellations where signal geometry demands specific altitudes.
The FCC governs U.S. spectrum allocation and orbital debris mitigation, forcing operators to demonstrate collision avoidance and end-of-life disposal before license grant, while the ITU coordinates international frequency registrations that determine market access priority. ESA procurement rules and the EU Space Programme mandate European participation in critical supply chains, shaping vendor selection for institutional missions. Stakeholders must track how national export control regimes and debris liability frameworks evolve as constellation density multiplies.
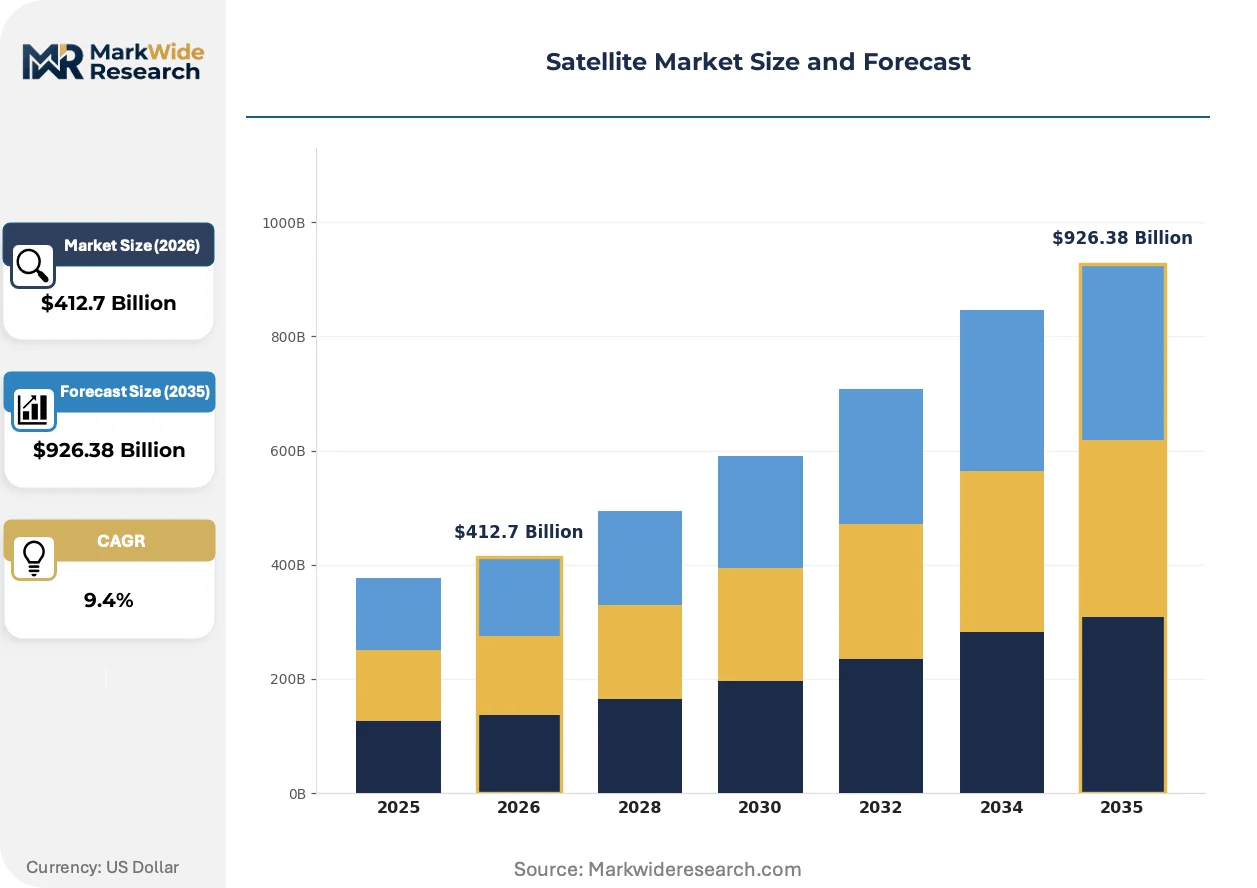
Market Dynamics
Proliferated Low Earth Orbit constellations are compressing launch economics and forcing incumbent operators to abandon geostationary premiums for latency-competitive architectures. The FCC's accelerated spectrum deadlines and ITU coordination queues are squeezing deployment timelines while defense procurement pivots toward distributed resilience.
Growth Catalysts
- LEO Broadband Mandates:Rural connectivity programs in the United States and United Kingdom are channeling public funds toward satellite-based universal service obligations, creating anchor tenancy for emerging constellations.
- REACH Space Debris Amendments:European orbital sustainability standards are mandating active de-orbit capabilities and collision-avoidance systems, stimulating demand for propulsion miniaturization and autonomous navigation.
- Hyperspectral Imaging:Agricultural commodity traders and carbon verification platforms are subscribing to tasking-based Earth observation services rather than acquiring dedicated spacecraft, expanding addressable demand beyond traditional government intelligence buyers.
Market Restraints
- Gallium Arsenide Wafer Concentration:Taiwan and mainland China dominate substrate production for high-efficiency solar cells, exposing constellation operators to single-source geopolitical risk.
- FCC Part 25 Licensing Backlogs:Spectrum application queues exceeding thirty-six months are freezing market entry for second-tier operators while incumbents consolidate orbital filings.
- Optical Ground Station Substitution:Laser-based free-space communication links are threatening radio-frequency transponder economics for high-bandwidth applications, compressing legacy equipment valuations.
Strategic Opportunities
- In-Orbit Servicing:Life-extension and refueling missions are creating aftermarket revenue streams for geostationary assets previously written off at end-of-design-life.
- India's IN-SPACe Liberalization:Private launch pad access and streamlined satellite authorization are attracting foreign constellation operators to establish South Asian ground segments and manufacturing partnerships.
- Quantum Key Distribution:Integration of entanglement-based encryption payloads is opening sovereign secure communications contracts outside traditional NATO procurement channels.
Industry Challenges
- Propulsion Chemist Scarcity:Green propellant formulation expertise remains concentrated within a handful of national laboratories and legacy prime contractors, constraining new entrant staffing.
- ITU Filing Defense Costs:Maintaining spectrum priority against coordination challenges requires dedicated legal and regulatory affairs capacity that absorbs disproportionate overhead for mid-scale operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Market |
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $926.38 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Communication Satellites, Earth Observation Satellites, Navigation Satellites, Scientific Satellites Application: Agriculture Monitoring, Weather Forecasting, Military Surveillance, Disaster Management End User: Government Agencies, Telecommunication Companies, Research Institutions, Private Enterprises Technology: Geostationary Orbit, Low Earth Orbit, Medium Earth Orbit, Manned Spacecraft |
| Companies Covered | SpaceX, Lockheed Martin Corporation, Airbus Defence and Space, Northrop Grumman, Thales Alenia Space, OneWeb, Planet Labs PBC, Maxar Technologies, China Aerospace Science and Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Market Emerging Trajectories
Constellation operators are fragmenting procurement models while hardware architectures split between mass-produced smallsats and precision-classified government payloads. Regulatory jurisdictions are competing to establish de facto standards for orbital traffic management and debris liability.
Software-defined radio payloads are bifurcating the communications satellite market. Commercial broadband providers are adopting reprogrammable transponders to reallocate bandwidth across coverage footprints within hours rather than hardware replacement cycles. This flexibility is compressing traditional satellite manufacturing lead times while enabling dynamic spectrum arbitrage between fixed and mobile service allocations.
EU Space Programme procurement rules are mandating European critical technology content for institutional missions. The F-Gas Regulation is simultaneously restricting fluorinated propellant options, pushing thruster manufacturers toward ammonium dinitramide and water-electrolysis alternatives. French and German prime contractors are responding by consolidating sovereign supply chains for solar array drive mechanisms and reaction wheels.
Defense agencies are unbundling satellite operations from platform ownership. Tasking-as-a-service contracts are displacing dedicated military spacecraft procurement for non-time-critical imagery and signals intelligence. This consumption-pattern shift is most visible in United Kingdom and Australian programs, where commercial data buys now supplement classified national assets for regional monitoring and disaster response.
Satellite Market Segmentation
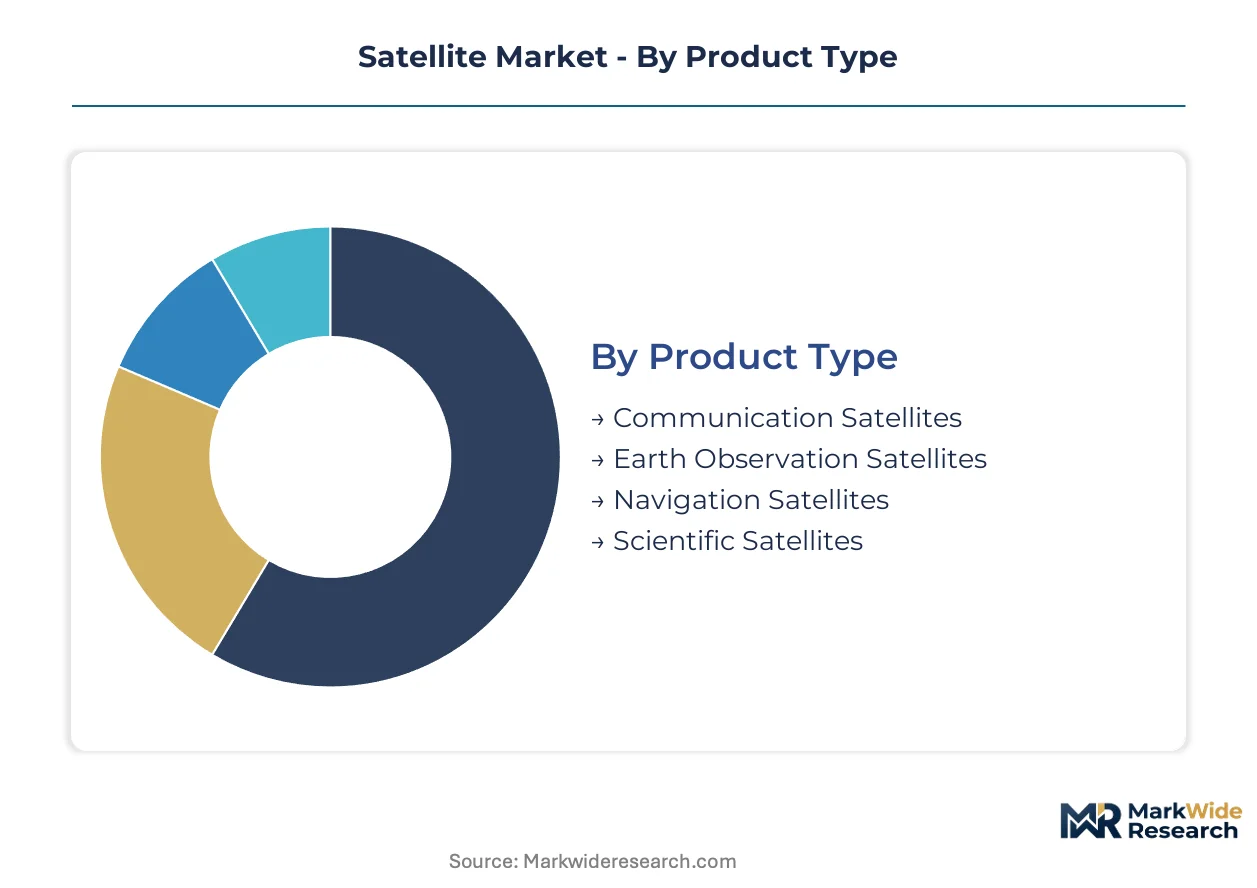
Satellite market segmentation reveals divergent procurement rhythms across defense, commercial, and scientific buyers. Each dimension—product architecture, orbital regime, and end-use application—carries distinct margin profiles and regulatory exposure that reshape vendor prioritization.
Product Type:
Domestic procurement dominates government payloads in the United States, China, and France, while commercial constellations source from international supply chains with manufacturing distributed across Germany, Japan, and South Korea.
- Communication Satellites:Geostationary platforms weighing three to six metric tons carry transponder payloads for broadcast and broadband relay. Demand concentrates with telecommunication companies in the United States and United Kingdom seeking rural connectivity mandates, though LEO constellations are compressing GEO pricing power through latency advantages.
- Earth Observation Satellites:Smallsat architectures under 500 kilograms deploy multispectral and synthetic aperture radar sensors for tasking-based imagery. Agricultural commodity traders in Brazil and carbon verification platforms in the European Union subscribe to commercial data rather than operating dedicated assets, expanding addressable demand beyond traditional intelligence agencies.
- Navigation Satellites:Atomic clock payloads and precise orbit determination enable positioning services with meter-level accuracy.
- Scientific Satellites:Deep-space probes and heliophysics observatories carry specialized instrumentation for astrophysics research.
Communication Satellites holds the largest share; momentum sits with Earth Observation Satellites.
Application:
Cost tier separation runs sharp between mission-critical defense programs with hardened requirements and commercial services competing on price-per-task.
- Military Surveillance:Signals intelligence and imagery reconnaissance demand encrypted downlinks and anti-jam capabilities. The United States Space Force and United Kingdom Strategic Command procure through classified contracts with domestic primes, while allied nations purchase commercial data feeds for regional monitoring.
- Agriculture Monitoring:Normalized difference vegetation index products and soil moisture analytics support precision farming decisions. Large-scale commodity operations in Argentina and Australia subscribe to weekly coverage rather than maintaining in-house ground stations, lowering capital barriers for mid-tier growers.
- Weather Forecasting:Hyperspectral sounders and microwave imagers feed numerical prediction models for national meteorological services.
- Disaster Management:Rapid-tasking SAR penetrates cloud cover for flood and earthquake damage assessment.
Military Surveillance commands premium pricing; Agriculture Monitoring climbs fastest on commercial adoption.
End User:
Customer type determines contracting structure—cost-plus for government, fixed-price for commercial, and grant-funded for academic missions.
- Government Agencies:Civil space programs and defense departments specify mission assurance over unit cost. NASA and ESA institutional procurement mandates domestic technology content, while classified payloads require cleared facilities and personnel.
- Telecommunication Companies:Mobile network operators lease transponder capacity or anchor LEO broadband constellations. Rural universal service obligations in the United States and United Kingdom channel public subsidy toward satellite-based connectivity.
- Research Institutions:University-led CubeSat programs access standardized launch aggregators for technology demonstration.
- Private Enterprises:Insurance underwriters and logistics firms purchase imagery analytics through API-delivered services.
Government Agencies anchor volume commitment; Private Enterprises drive the steepest expansion trajectory.
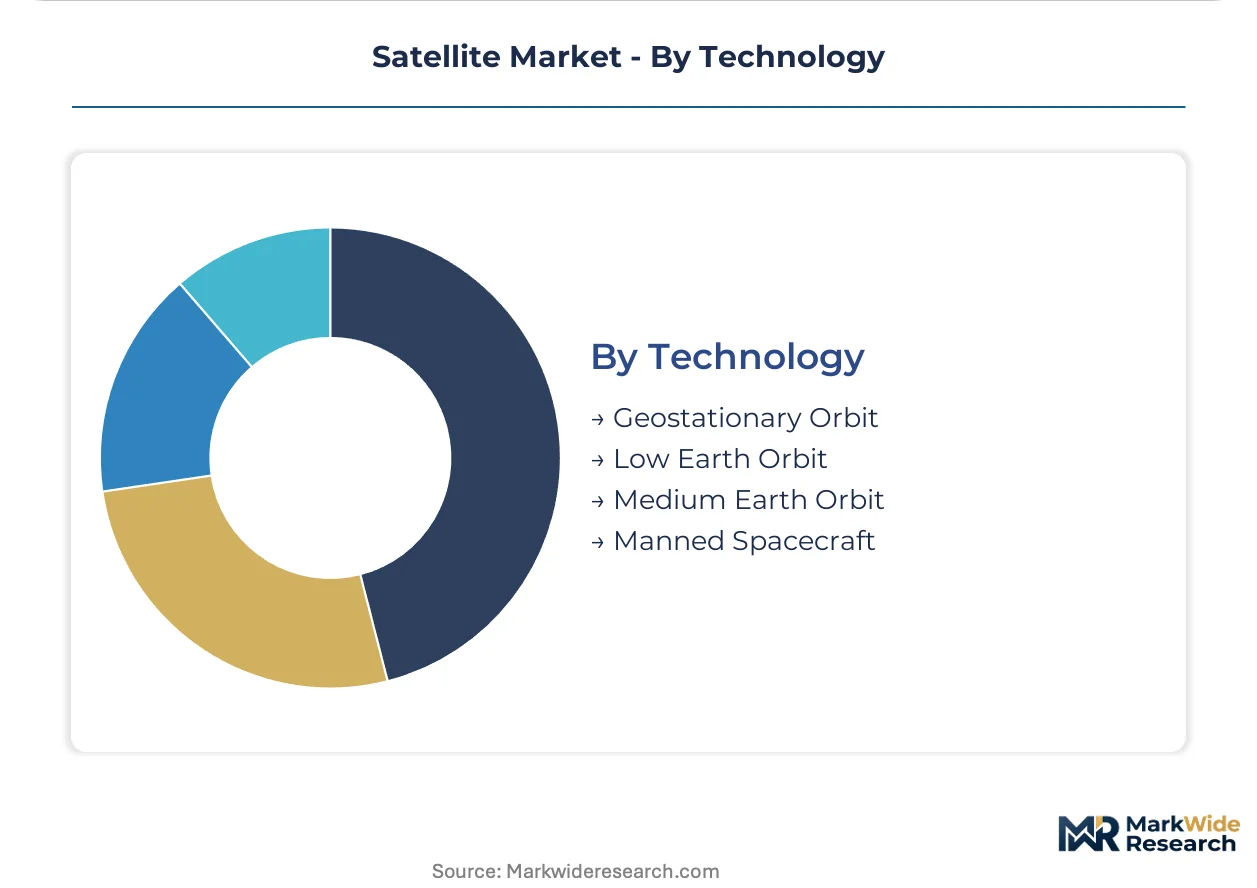
Technology:
Orbital altitude dictates payload mass, launch cost, and regulatory filing complexity in divergent patterns across operator scale.
- Low Earth Orbit:Altitudes of 300 to 1,200 kilometers enable low-latency broadband and high-resolution imaging with smallsat form factors. SpaceX and Amazon's Project Kuiper dominate FCC filing queues, while ITU coordination deadlines compress deployment timelines for second-tier operators.
- Geostationary Orbit:Fixed position at 35,786 kilometers supports broadcast distribution and maritime connectivity with single-satellite coverage. Legacy operators defend transponder leasing margins through long-term media contracts, though video streaming migration erodes growth.
- Medium Earth Orbit:Navigation constellations at 19,000 to 23,000 kilometers optimize signal geometry for positioning accuracy.
- Manned Spacecraft:Crewed platforms and space stations carry life support and docking systems for astronaut transport.
Geostationary Orbit retains revenue concentration; Low Earth Orbit captures deployment momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Space Force's Eastern and Western Ranges at Cape Canaveral and Vandenberg underwrite American launch capacity dominance. China's Wenchang Satellite Launch Center on Hainan Island anchors Asia-Pacific heavy-lift operations. Europe's Guiana Space Centre in French Guiana provides equatorial access for institutional missions.
United States
Defense procurement and commercial constellation deployment drive demand. The FCC enforces Part 25 licensing with spectrum coordination deadlines compressing deployment timelines. SpaceX operates vertically integrated manufacturing in Hawthorne, California, while Blue Origin expands engine production in Huntsville, Alabama.
China
State-directed constellation programs and sovereign navigation expansion accelerate procurement. The MIIT coordinates spectrum allocation with ITU filing priorities for BeiDou augmentation. China Aerospace Science and Technology Corporation concentrates manufacturing in Beijing and Shanghai, supported by launch infrastructure at Jiuquan and Taiyuan.
United Kingdom
Strategic Command contracts and rural broadband mandates shape institutional demand. The UK Space Agency administers licensing under the Outer Space Act with debris mitigation requirements. Satellite applications clusters concentrate in Harwell, Oxfordshire, and Glasgow, Scotland, where Clyde Space manufactures CubeSat platforms.
France
Dual-use military-civilian programs and EU institutional procurement anchor volume. The F-Gas Regulation restricts fluorinated propellants, pushing thruster manufacturers toward green alternatives. Airbus Defence and Space maintains sovereign manufacturing in Toulouse with ground segment operations in Paris-Saclay.
Germany
Earth observation data analytics and automotive connectivity integration expand commercial uptake. ESA procurement rules mandate European technology content for institutional missions. OHB System AG and satellite component suppliers cluster in Bremen and Munich, with optical payload development in Oberpfaffenhofen.
Satellite Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and launch cadence. The vendor base splits between vertically integrated constellation operators and modular payload integrators serving institutional buyers. Three archetypes dominate: full-stack operators controlling rocket-through-service delivery, prime contractors anchoring classified government programs, and commercial imagery specialists selling tasking-as-a-service. Competitive moves concentrate on launch cost reduction through reusable architectures and in-orbit servicing capabilities for life-extension revenue.
Among full-stack operators, SpaceX exemplifies the vertically integrated archetype through captive launch and constellation operations. Lockheed Martin Corporation and Airbus Defence and Space occupy prime contractor positions serving sovereign defense procurement with hardened payload integration. These three entities represent the structural poles of the competitive landscape: private capital-driven disruption, American classified program anchoring, and European dual-use institutional alignment.
| Leading Market Players |
|---|
| SpaceX |
| Lockheed Martin Corporation |
| Airbus Defence and Space |
| Northrop Grumman |
| Thales Alenia Space |
| OneWeb |
| Planet Labs PBC |
| Maxar Technologies |
| China Aerospace Science and Technology Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with launch providers lock in both orbital slot access and price visibility for constellation operators facing FCC deployment deadlines. These arrangements tether unit economics to launch cadence guarantees while exposing buyers to penalty clauses for spectrum non-utilization.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hardened military payloads from commercial broadband satellites and mass-produced CubeSats. Price differentiation rests on radiation tolerance certification and sovereign manufacturing content under ESA procurement rules. Cost compression in commercial LEO tiers is intensifying because SpaceX's vertical integration undercuts legacy prime contractor overhead structures. Telecommunication companies anchor volume commitment with lowest price sensitivity; research institutions exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for gallium arsenide solar cell substrates now stretch eighteen to twenty-four months due to Taiwan and mainland China concentration in wafer production. The satellite supply chain draws from aluminum-lithium alloy mills in the United States, reaction wheel manufacturers in Germany, and propulsion component specialists in France. Single-source vulnerability in high-efficiency photovoltaic substrates exposes constellation operators to export control disruption. Distribution runs through prime contractor integration facilities with government-cleared personnel for classified payloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three dominant constellation operators controlling FCC filing priority, fragmenting pricing leverage for component suppliers and mid-tier launch providers.
For Market Incumbents: Fortify sovereign manufacturing lines in France and Germany to satisfy EU Space Programme domestic content mandates. Deepen captive launch capacity through reusable architecture investment to offset SpaceX cost advantages. Lockheed Martin Corporation and Airbus Defence and Space must accelerate software-defined payload development before commercial broadband providers capture defense-adjacent tasking contracts. For New Entrants and Emerging Players: Differentiate on hyperspectral imaging analytics for agricultural commodity verification and carbon credit monitoring. India's IN-SPACe liberalization offers the most penetrable regulatory entry point for South Asian ground segment establishment. Target tasking-as-a-service contracts with United Kingdom Strategic Command as the primary go-to-market angle outside NATO procurement channels. For Investors and Strategic Acquirers: Capital is best deployed toward in-orbit servicing specialists with life-extension capabilities for geostationary assets approaching design-life expiration. Long-term viability hinges on debris mitigation technology compliance as REACH amendments tighten active de-orbit requirements. Watch ITU coordination queue clearance rates as the inflection signal for second-tier operator market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Launch Architecture Scale-Up | SpaceX's Starship program compresses cost-per-kilogram economics below legacy expendable systems. |
| Software-Defined Payload Integration | Lockheed Martin Corporation adapts commercial reprogrammable transponders for classified government missions. |
| In-Orbit Servicing Capability Development | Northrop Grumman's MEV missions demonstrate life-extension revenue from geostationary asset aftermarket. |
| Green Propellant Formulation Transition | Airbus Defence and Space responds to EU F-Gas Regulation with ammonium dinitramide thruster alternatives. |
| Quantum Key Distribution Payload Deployment | Thales Alenia Space targets sovereign secure communications contracts outside traditional NATO channels. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FCC licensing databases, ITU coordination filings, ESA procurement records, and defense contract announcements. Primary interviews with constellation operations executives, satellite component procurement leads, launch range planning officers, and regulatory affairs specialists informed demand assumptions. Secondary validation drew from SEC 10-K disclosures, national space agency budget documents, and customs trade data for gallium arsenide substrate flows. Bottom-up unit economics modeling triangulated against top-down market sizing across orbital regimes.
Segmentation dimensions modeled include product architecture, orbital altitude tier, end-use application, and customer contracting structure across the projection horizon. CAGRs were derived from deployment schedule analysis against spectrum coordination deadlines. Industry-specific forecast inputs incorporated FCC Part 25 licensing queue velocity and ITU filing defense cost trajectories for mid-scale operators.
The analysis sits within stated boundaries; outcomes outside sustained launch cadence achievement or accelerated debris regulation enforcement would require recalibration. Forecasts reflect assumptions regarding constellation deployment timelines and sovereign procurement continuity. Revision becomes warranted when gallium arsenide supply concentration or ITU coordination backlog crosses critical disruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Europe Satellite Bus Market
Satellite
North America Small Satellite Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
UK Satellite-Based Earth Observation Market
Satellite
Satellite Gateway Market
Satellite
Africa Satellite Connectivity Market
Satellite
France Satellite Connectivity Market
Satellite
Europe Satellite Manufacturing and Launch Systems Market
Satellite
Advanced Satellite Market
Satellite
North America Satellite IoT Market
Satellite
Satellite Sensor Market
Satellite
Spain Satellite Imagery Services Market
Satellite
Saudi Arabia Satellite Communications Market
Satellite
Satellite Amplifier Market
Satellite
Commercial Satellite Launch Service Market
Satellite
Canada Satellite Connectivity Market