
 Satellite Communications Service Market | 2026-2036
Satellite Communications Service Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Communications Service Market Insights
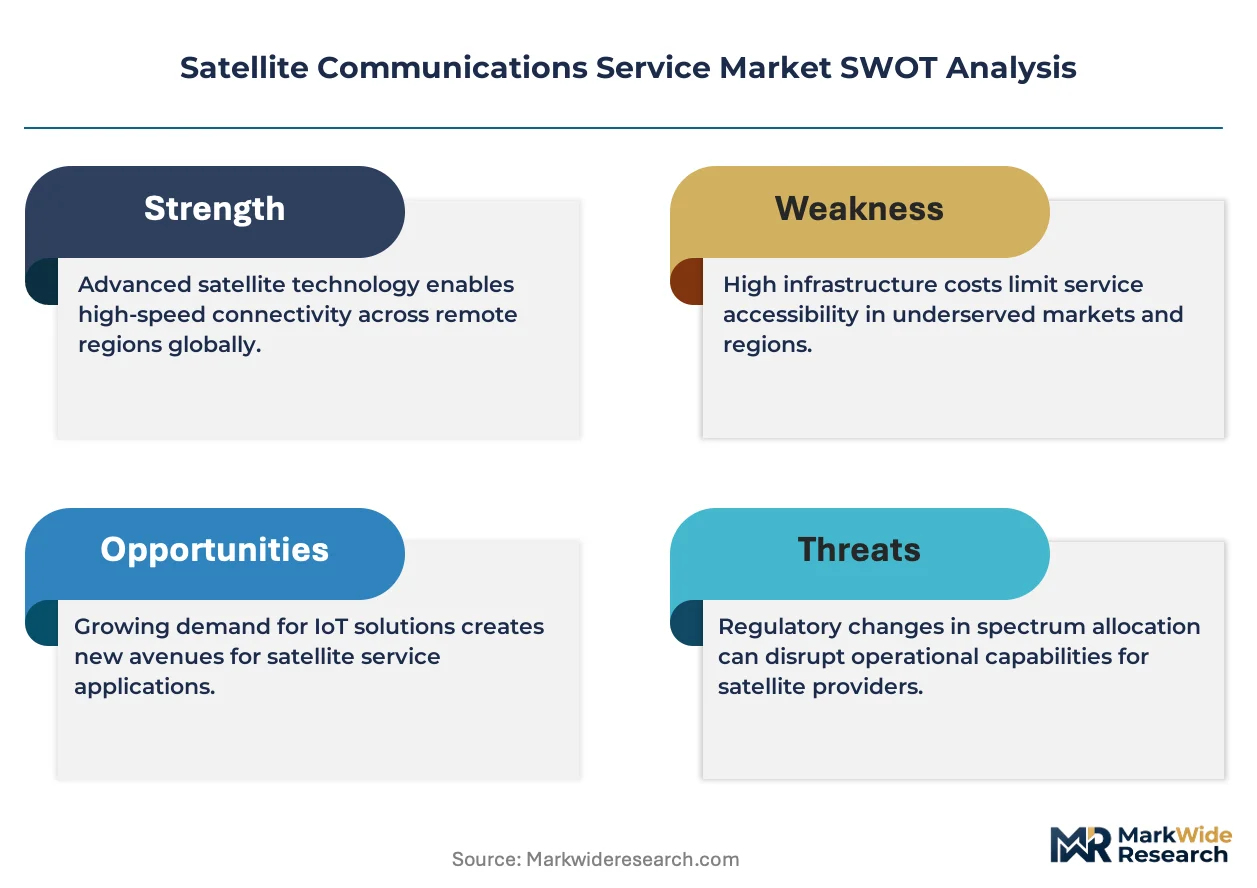
ISO 15118 certification for satellite-to-ground interface compatibility is rotating the competitive threshold for new entrants. SES leverages its geostationary and medium earth orbit fleet to sustain capacity leadership across broadcast and data markets. Viasat anchors its position through vertical integration into terminal manufacturing and network management systems. Iridium Communications specializes in narrowband IoT and push-to-talk services for government and industrial users.
Satellite communications service encompasses the provision of voice, data, and video transmission capabilities via artificial earth-orbiting spacecraft operating across L-band through Ka-band frequencies, typically involving bent-pipe or regenerative onboard processing architectures with round-trip latencies ranging from sub-100 milliseconds for low earth orbit to 500-plus milliseconds for geostationary systems. The primary commercial purpose involves extending connectivity to regions lacking terrestrial infrastructure while providing redundant pathways for mission-critical operations. Broadband service type captures the dominant revenue pool as enterprise and consumer data consumption escalates, while Ka-band technology leads capacity economics through frequency reuse and spot-beam architectures. Government end users represent the fastest-growing demand segment as sovereign nations prioritize secure, sovereign-controlled space assets.
The FCC governs spectrum allocation and orbital slot coordination within the United States, directly constraining launch timelines and constellation densities for operators seeking market access. EASA and national aviation regulators across Europe mandate specific satellite communication standards for commercial air transport under Single European Sky initiatives, shaping equipment retrofit cycles. The ITU Radio Regulations framework governs international frequency coordination and interference mitigation, requiring operators to navigate multi-year notification and recording procedures before service activation. Stakeholders must monitor spectrum reallocation proceedings and debris mitigation rulemakings across multiple jurisdictions to anticipate capacity constraints and compliance cost escalations.
Market Dynamics
The transition from geostationary orbit dominance to low earth orbit constellations is compressing latency benchmarks and forcing incumbent operators to reconfigure fleet architectures or risk capacity obsolescence.
Growth Catalysts
- LEO constellation deployment:Space Force contracts and commercial broadband mandates are accelerating orbital slot utilization across the United States.
- FCC streamlined licensing:Non-geostationary orbit authorization procedures are reducing entry barriers for new constellation operators.
- NATO secure procurement:Defense agencies across member states are expanding sovereign-controlled satellite capacity for tactical communications.
Market Restraints
- Spectrum coordination friction:ITU Radio Regulations notification procedures create multi-year delays before service activation.
- Launch capacity concentration:Reliance on limited heavy-lift providers constrains constellation deployment timelines.
- Debris mitigation compliance:Post-mission disposal mandates from national regulators escalate operational costs for satellite operators.
Strategic Opportunities
- Aviation connectivity retrofit:EASA mandates under Single European Sky initiatives are driving equipment upgrade cycles for commercial air transport.
- IoT narrowband expansion:Industrial asset tracking and maritime monitoring present underpenetrated service addressable markets.
- Ka-band spot-beam economics:Frequency reuse architectures enable premium pricing for high-throughput enterprise data services.
Industry Challenges
- Onboard processing talent scarcity:Regenerative payload engineering expertise concentrates among legacy defense contractors.
- Ground segment integration complexity:Terminal interoperability with ISO 15118 standards requires certification coordination across multiple jurisdictions.
- Legacy bent-pipe asset stranding:Existing geostationary capacity faces utilization pressure as latency-sensitive applications migrate to LEO alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Communications Service Market |
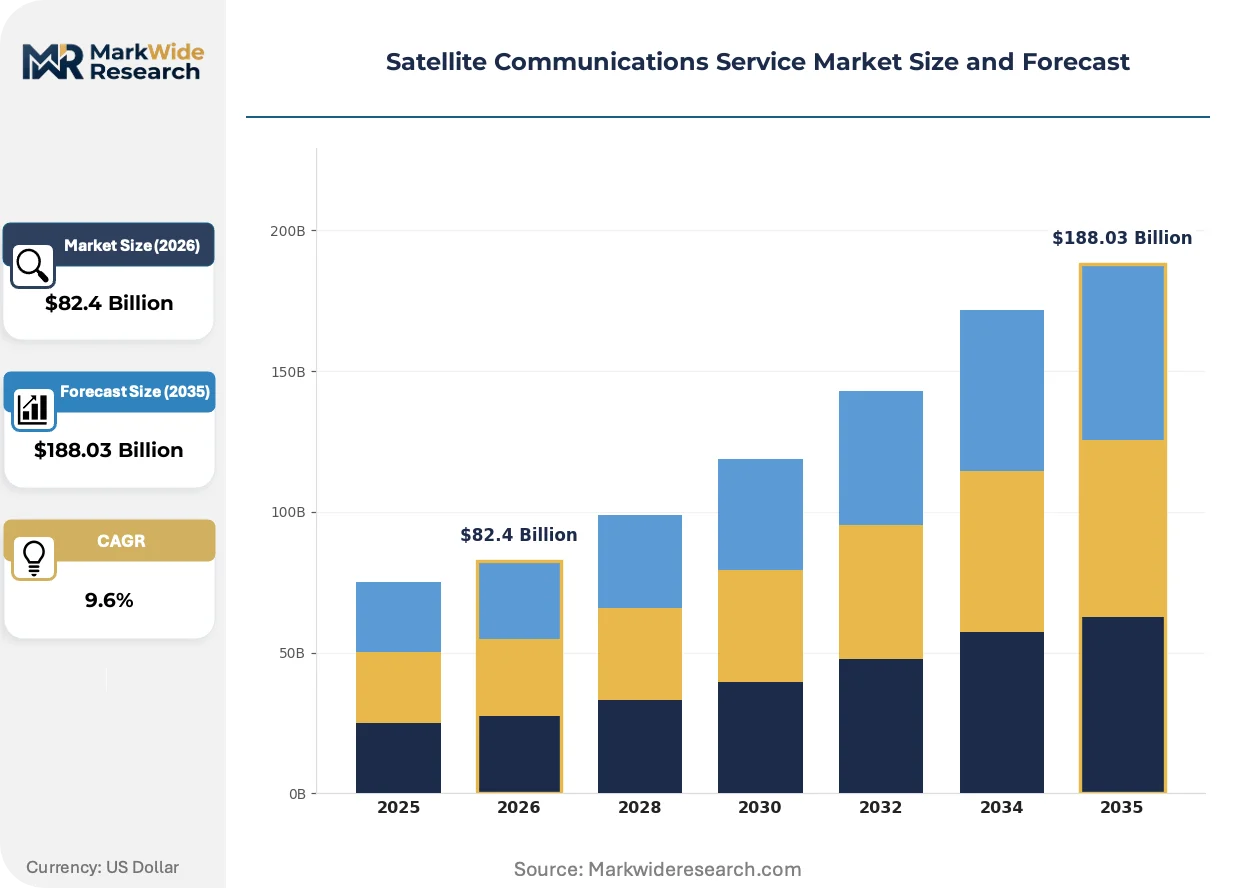
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $188.03 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Broadband, Uplink, Downlink, VSAT End User: Aerospace, Maritime, Telecommunications, Government Deployment: Fixed, Mobile, Portable, Emergency Technology: CBand, KBand, KaBand, LBand |
| Companies Covered | SES, Telesat, Viasat, AST SpaceMobile, Gilat Satellite Networks, Iridium Communications, Inmarsat, ORBCOMM, Globalstar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Communications Service Market Trends and Innovations
Orbital architecture diversification and terrestrial interface standardization are converging to redefine service delivery economics and competitive positioning across frequency bands.
Phased-array flat-panel terminals are replacing parabolic dishes for mobile and fixed applications. Maritime operators and commercial aviation fleets are adopting these units to enable seamless beam switching across satellite footprints. Terminal manufacturing is miniaturizing, reducing installation costs and expanding addressable consumer segments previously excluded by hardware complexity.
Europe's CSRD disclosure requirements are mandating emissions transparency across satellite supply chains. Operators must now document orbital debris mitigation and ground station energy consumption in sustainability reports. This regulatory pressure is most acute for constellation operators seeking European government contracts, driving investment into green propulsion and renewable-powered gateway facilities.
Enterprise buyers are consolidating vendor relationships around integrated managed-service contracts rather than capacity-only leases. Systems integrators and defense contractors are displacing wholesale bandwidth resellers as the primary procurement channel. This pattern is most visible in United States federal contracting, where Space Force and civilian agencies favor single-source accountability for end-to-end mission assurance.
Satellite Communications Service Market Segmentation

Service differentiation across orbital architectures and frequency bands determines pricing power and customer retention in satellite communications. Segmentation reveals where capital deployment concentrates and which technical specifications command premium positioning.
Service Type:
Margin pools concentrate in high-throughput data transmission where enterprise customers pay for guaranteed bandwidth rather than best-effort connectivity.
- Broadband:High-capacity data services deliver internet access, video streaming, and cloud connectivity via spot-beam architectures. Space Force contracts and commercial LEO deployments in the United States are driving procurement volume for low-latency enterprise links.
- VSAT:Very Small Aperture Terminal networks enable two-way satellite communications through compact ground stations. Maritime operators and remote enterprise sites across NATO member states are upgrading legacy Ku-band installations to Ka-band for improved throughput economics.
- Uplink:Transmission paths from ground stations to orbital assets carry command signals and content feeds. Broadcasters and government agencies maintain dedicated uplink capacity for mission-critical content distribution.
- Downlink:Signal reception from satellites to Earth terminals supports content delivery and data retrieval. Direct-to-home television and weather imaging services rely on standardized downlink frequencies for receiver compatibility.
The dominant share belongs to Broadband, while VSAT is closing the gap fastest.
End User:
Application requirements vary sharply across verticals, with sovereign procurement commanding price premiums over commercial contracts.
- Government:Secure communications for defense and civilian agencies demand encrypted, sovereign-controlled infrastructure. NATO expansion of tactical satellite capacity and FCC streamlined licensing are accelerating constellation deployment for federal end users.
- Aerospace:Commercial aviation and business jet connectivity require seamless beam handoff at high velocities. EASA mandates under Single European Sky initiatives are forcing equipment retrofit cycles across European air transport fleets.
- Maritime:Merchant vessels and offshore platforms need continuous coverage across oceanic routes. Phased-array flat-panel terminals are displacing parabolic dishes for crew welfare and operational data links.
- Telecommunications:Mobile network operators lease satellite backhaul for rural coverage extension and disaster recovery. ITU Radio Regulations coordination delays constrain rapid service activation for this price-sensitive segment.
Government holds the dominant share, while Aerospace is expanding most quickly.
Deployment:
Customer mobility requirements dictate ground segment complexity and installation cost structures.
- Fixed:Permanent installations at enterprise sites and gateway facilities maximize antenna size and power availability. Rural broadband subsidies in the United States are concentrating demand for fixed consumer terminals.
- Mobile:Vehicle-mounted and airborne terminals maintain connectivity during platform movement. Maritime and aviation fleets drive procurement of electronically steered arrays for seamless satellite switching.
- Portable:Man-pack and fly-away units deploy rapidly for field operations and emergency response. Defense agencies prioritize ruggedized terminals with cross-band interoperability.
- Emergency:Surge capacity activated during natural disasters and network outages commands premium pricing. First responders and humanitarian organizations require pre-positioned bandwidth reservations with guaranteed access protocols.
Fixed deployments retain the dominant share, though Mobile is gaining share fastest.
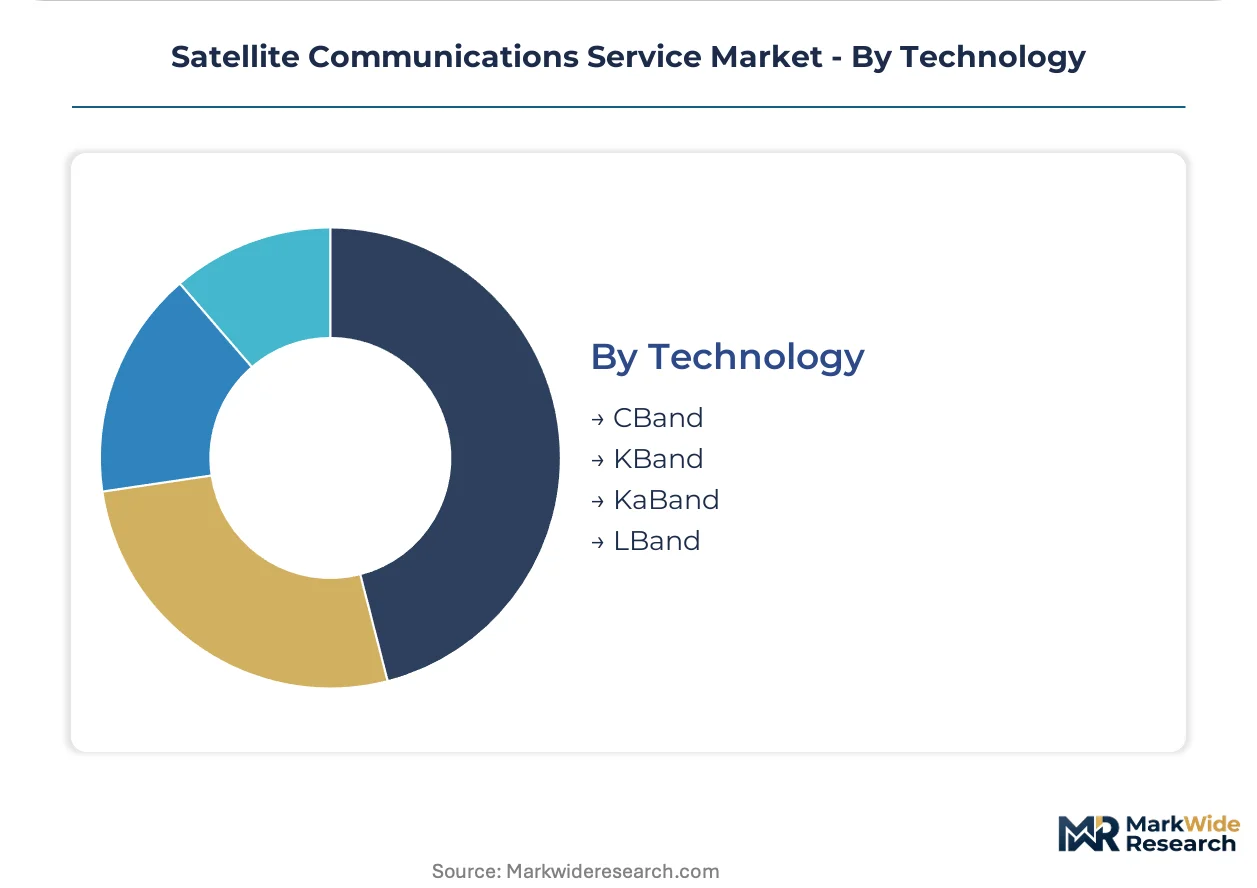
Technology:
Frequency selection trades propagation characteristics against spectrum availability and regulatory clearance timelines.
- KaBand:High-frequency spectrum enables aggressive frequency reuse through narrow spot beams. Enterprise data services and military applications in the United States are concentrating procurement on Ka-band for throughput density.
- KBand:Medium-high frequencies balance rain fade resilience with capacity economics. Broadcast distribution and maritime services maintain significant installed bases in this spectrum.
- CBand:Lower frequencies penetrate weather and vegetation with minimal signal degradation. Legacy television distribution and tropical zone services continue relying on C-band despite spectrum reallocation pressures.
- LBand:Narrow spectrum allocations support mobile and IoT applications with minimal terminal power requirements. Iridium and Inmarsat networks dominate this band for narrowband voice and machine-to-machine communications.
KaBand claims the dominant share, while LBand shows the steepest expansion trajectory in IoT applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC streamlined licensing for non-geostationary orbit constellations is accelerating commercial deployment timelines across multiple jurisdictions. Sovereign procurement programs and defense agency contracts are reshaping capacity allocation priorities in key satellite communications markets.
United States
Space Force contracts and commercial LEO deployments concentrate demand for low-latency enterprise links and secure government communications. The FCC governs spectrum allocation and orbital slot coordination, directly constraining launch timelines for operators seeking market access. Colorado Springs hosts Space Force Space Operations Command, driving procurement coordination for tactical satellite capacity.
Germany
EASA mandates under Single European Sky initiatives are forcing equipment retrofit cycles across commercial air transport fleets. The EU Green Deal and CSRD disclosure requirements mandate emissions transparency across satellite supply chains. Munich anchors aerospace engineering clusters where terminal manufacturers coordinate ISO 15118 certification for satellite-to-ground interfaces.
United Kingdom
NATO secure procurement expansion is driving sovereign-controlled satellite capacity for tactical defense communications. The UK Space Agency coordinates national orbital slot filings through ITU Radio Regulations frameworks. Harwell Space Cluster hosts payload engineering facilities where regenerative onboard processing expertise concentrates among legacy contractors.
France
CNES and defense procurement agencies prioritize encrypted sovereign infrastructure for military and civilian satellite services. REACH and RoHS frameworks constrain component sourcing for European-built spacecraft. Toulouse anchors the aerospace valley where satellite manufacturers coordinate Ka-band spot-beam payload production.
Japan
METI industrial policy supports domestic constellation operators seeking ITU frequency coordination for Asia-Pacific coverage. JIS standards govern terminal interoperability for maritime and aviation applications. Tokyo-Otemachi hosts satellite operator headquarters where enterprise managed-service contracts consolidate vendor relationships.
Satellite Communications Service Market Competitive Landscape
Player mix skews toward vertically integrated operators with geostationary heritage and emerging LEO constellation specialists. Incumbent fleet operators face utilization pressure as latency-sensitive applications migrate to low earth orbit alternatives. Two strategic archetypes dominate: legacy broadcast-capacity incumbents with bent-pipe infrastructure, and regenerative-payload newcomers with onboard processing architectures. Competitive moves center on fleet architecture reconfiguration and strategic partnerships for ground segment integration.
Within the integrated operator tier, SES and Viasat exemplify divergent responses to orbital transition pressure. SES leverages its geostationary and medium earth orbit fleet to sustain capacity leadership across broadcast and data markets. Viasat anchors its position through in-house production of terminal manufacturing and network management systems. Iridium Communications occupies a narrowband specialization position, focusing on IoT and push-to-talk services for government and industrial users.
| Leading Market Players |
|---|
| SES |
| Telesat |
| Viasat |
| AST SpaceMobile |
| Gilat Satellite Networks |
| Iridium Communications |
| Inmarsat |
| ORBCOMM |
| Globalstar |
| Others |
Pricing and Supply Chain Analysis
Heavy-lift launch capacity utilization rates concentrate procurement leverage among three providers, compressing price floors for constellation operators while elevating ground segment costs for new entrants seeking FCC authorization. Scale advantages in bent-pipe manufacturing anchor incumbent margins against regenerative payload newcomers facing ISO 15118 certification burdens.
Pricing Analysis
Certification level (ISO 15118-compliant vs. legacy interfaces) creates the primary spread between premium managed-service contracts and commodity capacity leases. Three-tier pricing structure across premium, standard, and economy levels segments government buyers paying for sovereign control from price-sensitive telecommunications carriers seeking rural backhaul. Cost compression in standard-tier broadband is intensifying because LEO constellation overcapacity is flooding wholesale markets. Mobile network operators exhibit highest price sensitivity, while defense agencies prioritize mission assurance over unit economics.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes elevate inbound logistics costs for phased-array terminal components sourced from East Asian manufacturing clusters. Payload engineering concentrates in France, satellite bus assembly in the United States, and ground station manufacturing in Germany. Supply chains draw from gallium nitride semiconductors, carbon-fiber composite substrates, and radiation-hardened electronics. Single-source vulnerability in heavy-lift launch services threatens deployment timelines. Distribution runs through systems integrators displacing wholesale bandwidth resellers in federal contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent operators face substitution pressure from terrestrial fiber expansion and 5G fixed-wireless alternatives eroding their rural broadband addressable market. Defense procurement remains the final moat against complete displacement.
For Market Incumbents: Shield geostationary fleet utilization through backward integration into managed-service contracts bundling network management with capacity leases. Prioritize Ka-band spot-beam payload upgrades to defend throughput density against LEO latency advantages. Channel control via direct federal contracting relationships offsets margin compression from wholesale price erosion. For New Entrants and Emerging Players: Anchor in narrowband IoT maritime monitoring where Iridium's push-to-talk dominance leaves tracking-data services underpenetrated. Target aviation connectivity retrofit cycles mandated by EASA Single European Sky initiatives as the most penetrable near-term segment. Pursue ISO 15118 pre-certification to accelerate procurement qualification with European systems integrators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated operators with captive terminal manufacturing and sovereign government contracts. Long-term viability hinges on regenerative payload engineering talent concentration at legacy defense contractors. Acquisition target archetype: mid-cap constellation operators with ITU-coordinated orbital slots but underutilized ground infrastructure. Signal to watch: FCC streamlined licensing approval velocity as inflection indicator for competitive entry pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Ka-band Spot-beam Payload Upgrade | Frequency reuse architectures enable premium pricing for Space Force enterprise data services. |
| ISO 15118 Certification Investment | Terminal interoperability compliance unlocks EASA-mandated aviation retrofit procurement channels. |
| Backward Integration into Terminals | In-house production of flat-panel arrays captures margin pools from maritime and aviation mobility segments. |
| Regenerative Payload Engineering Acquisition | Onboard processing expertise concentrates at Harwell Space Cluster and Toulouse aerospace valley facilities. |
| Sovereign Government Contract Consolidation | NATO secure procurement expansion favors single-source accountability for tactical satellite capacity. |
Research Methodology
Desk research of ITU Radio Regulations filings, FCC authorization databases, and EASA certification records preceded structured interviews with constellation operations executives, defense procurement officers, and maritime fleet connectivity managers. Primary fieldwork with satellite terminal manufacturers and systems integrators combined with secondary validation against Space Force budget justifications and EU CSRD sustainability disclosures. Bottom-up capacity deployment models triangulated against top-down sovereign procurement forecasts.
Variance decomposition across orbital architecture, frequency band, and end-user verticals shaped analytical framework development over the projection horizon. Segmentation dimensions modeled include service type, deployment mobility requirement, and sovereign vs. commercial procurement channel. CAGRs derived from unit economics analysis of spot-beam throughput density and launch cost trajectories. Industry-specific forecast inputs encompass ITU coordination timeline assumptions and debris mitigation compliance cost escalations.
Material uncertainties — ITU notification delays, launch vehicle availability shocks, spectrum reallocation proceedings — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding FCC licensing velocity and NATO procurement expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
All-Electric Satellites Market
Satellite
Germany Satellite Imagery Services Market
Satellite
Satellite Communication System Market
Satellite
Satellite Data Analytics Services Market
Satellite
UAE Satellite Communication Market
Satellite
Europe Small Satellite Market
Satellite
Reconnaissance Satellite Market
Satellite
LEO Satellite System Market
Satellite
Global Nanosatellite and Microsatellite Market
Satellite
Optical Satellite Communication Market
Satellite
Europe Satellite Manufacturing Market
Satellite
Global LEO Satellite Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
Satellite Transponder Market
Satellite
Saudi Arabia Satellite Communications Market