
 UK Satellite-Based Earth Observation Market | 2026-2036
UK Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
UK Satellite-Based Earth Observation Market Insights
Synthetic aperture radar resolution gaps between commercial and military-grade systems is narrowing, opening dual-use markets to new entrants. Airbus Defence and Space UK leverages its Portsmouth manufacturing base to sustain sovereign payload production for UK government contracts. Surrey Satellite Technology Limited anchors the smallsat segment with modular bus designs that reduce time-to-orbit for Earth observation missions.
UK Satellite-Based Earth Observation encompasses spacecraft, ground infrastructure, and analytics services that capture multispectral, radar, and hyperspectral imagery from low Earth orbit, typically operating at altitudes of 400–700 km with revisit cycles under 24 hours for commercial constellations. The primary purpose is converting raw sensor data into actionable geospatial intelligence for government and commercial decision-making. Optical Satellites dominate current revenue as legacy programs renew, while Synthetic Aperture Radar is expanding fastest due to all-weather imaging demand from defense and insurance sectors. Data Processing Software captures disproportionate margin pools as value shifts downstream from hardware to AI-enabled analytics.
The UK Space Agency coordinates national strategy alongside the Civil Aviation Authority's spaceport licensing and the Ministry of Defence's Skynet program requirements, creating layered compliance for operators serving both commercial and classified customers. ISO 19115 geospatial metadata standards and the Space Industry Act 2018 shape technical specifications and orbital access protocols for domestic launch. Stakeholders must weigh sovereign supply chain investments against the cost advantages of European and US data partnerships as launch cadence and sensor refresh cycles accelerate.
Market Dynamics
Sovereign capability mandates under the UK Space Agency's National Space Strategy are forcing domestic supply chain localization, compressing procurement timelines for defense and environmental agencies while fragmenting vendor access patterns.
Growth Catalysts
- Skynet program refresh cycles:Ministry of Defence orbital infrastructure investments are sustaining sovereign payload demand across radar and optical sensor categories.
- Harwell-Cornwall space corridor clustering:Co-located launch infrastructure and satellite manufacturing in England's southwest is reducing integration lead times for Earth observation missions.
- Flood mapping procurement expansion:Environment Agency satellite imagery contracts for climate resilience planning are accelerating high-resolution optical sensor deployment.
Market Restraints
- Gallium arsenide substrate volatility:Compound semiconductor supply concentration in East Asian foundries exposes UK payload manufacturers to input cost swings and allocation constraints.
- Space Industry Act 2018 licensing friction:Dual-use payload classification creates extended Civil Aviation Authority review periods for commercial operators seeking defense-adjacent contracts.
- European Space Agency data partnership dependency:Cost advantages of Copernicus program access disincentivize fully sovereign constellation investment for mid-tier analytics providers.
Strategic Opportunities
- Scotland's emerging launch sites:SaxaVord and Sutherland spaceport licensing progress opens northern latitude polar orbit access for synthetic aperture radar constellations.
- AI-enabled change detection analytics:Machine learning integration with raw multispectral feeds creates subscription revenue models displacing per-image licensing.
- Insurance sector parametric coverage expansion:Flood and crop risk modeling demand from Lloyd's of London syndicates is pulling commercial SAR data into agricultural underwriting workflows.
Industry Challenges
- RF engineer scarcity:Synthetic aperture radar payload design expertise concentrates in legacy defense contractors, constraining startup hiring pipelines.
- ISO 19115 metadata compliance timelines:Geospatial standard certification for commercial analytics platforms adds six-to-nine month product launch delays.
- Legacy ground station integration complexity:New constellation operators face interoperability friction with existing Goonhilly Earth Station infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Satellite-Based Earth Observation Market |
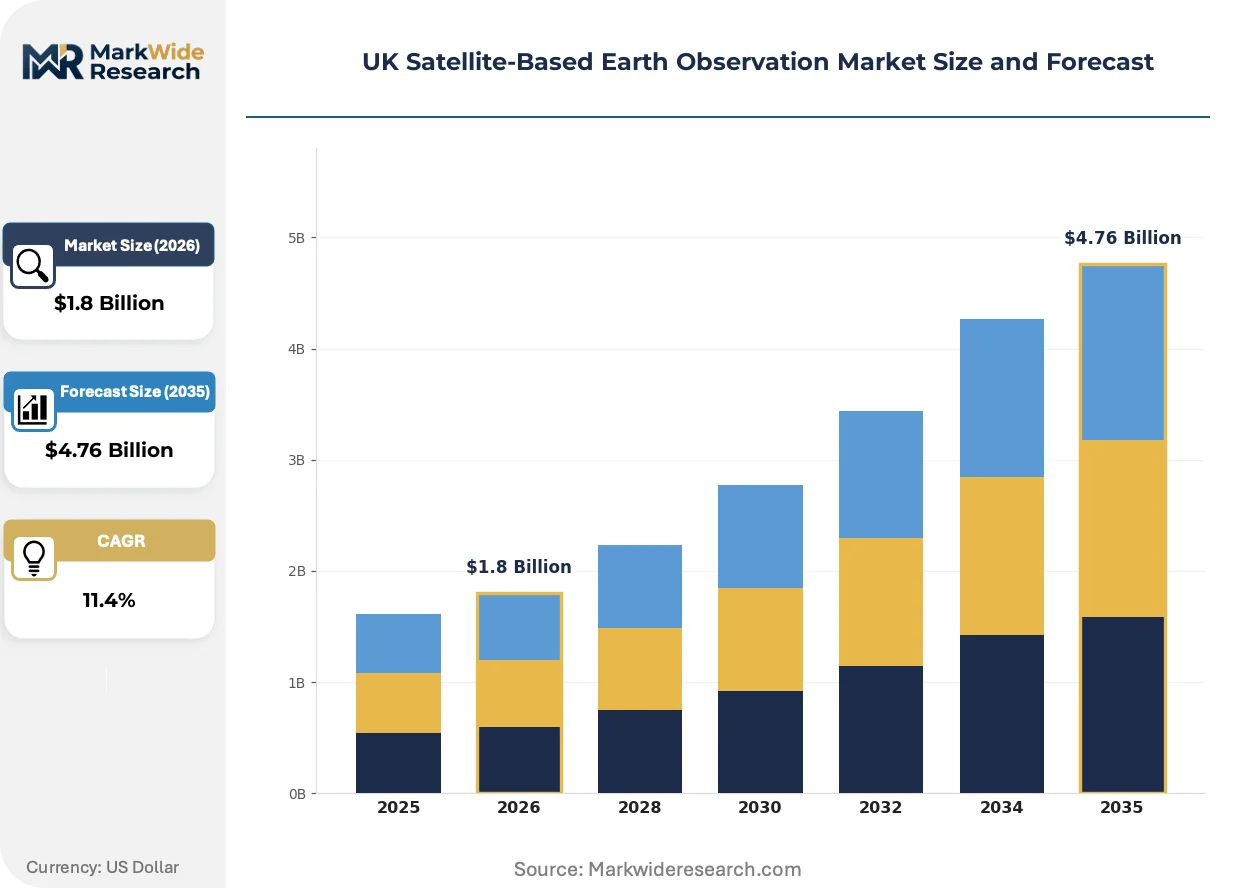
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Satellites, Radar Satellites, Hyperspectral Satellites, Synthetic Aperture Radar End User: Agriculture, Urban Planning, Environmental Monitoring, Defense Application: Disaster Management, Climate Change Studies, Land Use Mapping, Natural Resource Management Technology: Ground Segment Technology, Satellite Constellations, Data Processing Software, Communication Systems |
| Companies Covered | Thales Group, Airbus Defence and Space UK, Surrey Satellite Technology Limited (SSTL), Telespazio UK Ltd, Earth-i Ltd, Maxar Technologies, RAL Space, SatVu, Rezatec Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Satellite-Based Earth Observation Market Trends and Innovations
Downstream value capture is migrating from hardware manufacturing toward AI-powered analytics, compressing traditional satellite operator business models while opening specialized service layers for defense and climate applications.
Synthetic aperture radar miniaturization is collapsing the cost differential between commercial and military-grade imaging systems. Defense procurement offices are adopting commercial SAR constellations for border surveillance, displacing legacy classified platform dependency. This compression is enabling dual-use market entry for payload startups previously excluded from classified supply chains.
The Space Industry Act 2018 is mandating orbital debris mitigation protocols that reshape spacecraft design specifications. UK-licensed operators must now demonstrate end-of-life deorbit capability prior to launch authorization, adding propulsion subsystem requirements to smallsat bus architectures. Environmental monitoring missions are absorbing these compliance costs fastest due to public funding visibility requirements.
Subscription-based analytics contracts are displacing per-scene imagery licensing across insurance and agricultural buyer segments. Lloyd's syndicates and agritech platforms are consolidating procurement through API-integrated data feeds, bypassing traditional value-added reseller channels. This behavioral shift concentrates most visibly in England's commercial hub, where fintech-agritech crossover demand is strongest.
UK Satellite-Based Earth Observation Market Segmentation
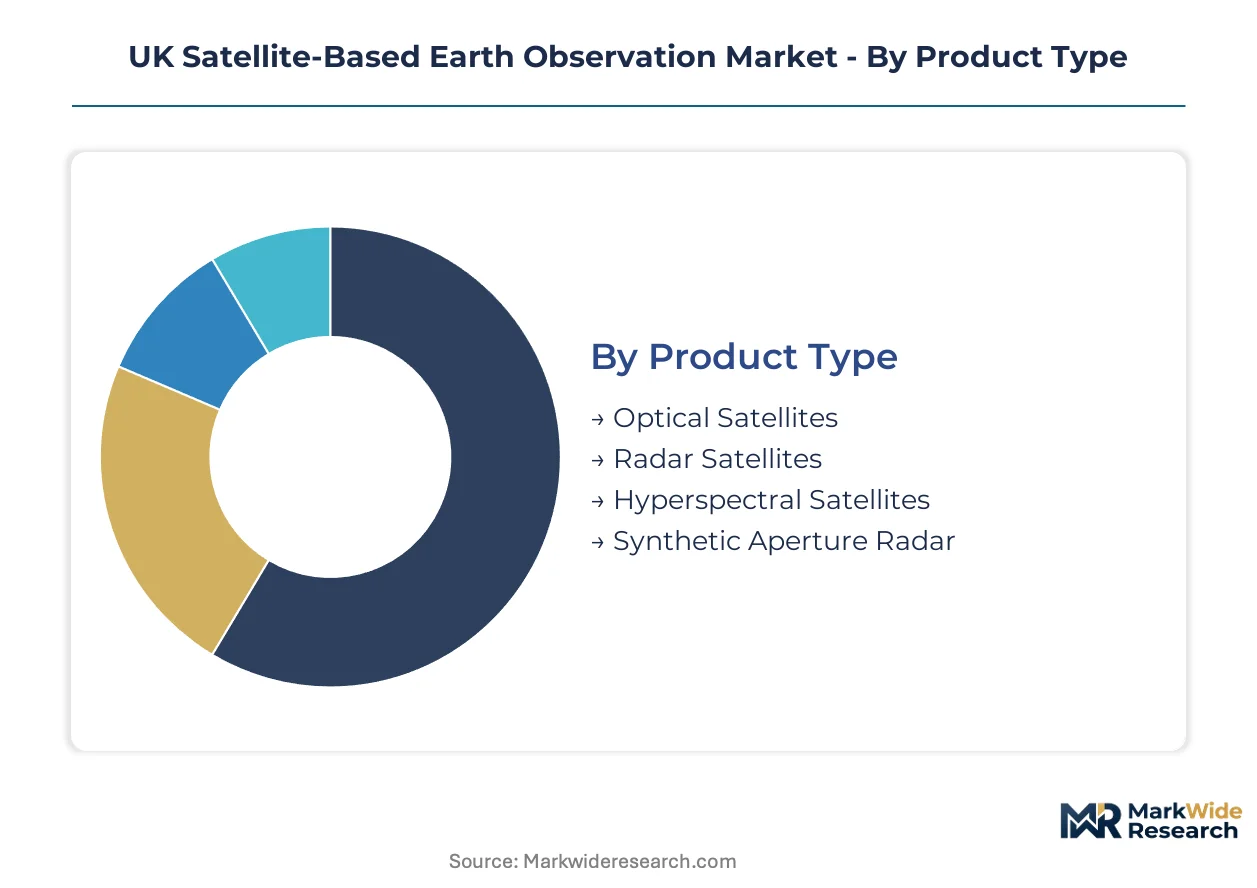
UK Satellite-Based Earth Observation Market segmentation reveals how value migrates across hardware, software, and service layers. Distinct procurement patterns emerge across defense, environmental, and commercial buyer segments, each imposing unique technical specifications and compliance requirements.
Product Type:
Cost tier differentiation separates legacy optical platforms from emerging radar architectures, with payload complexity driving procurement budget allocation across government and commercial programs.
- Optical Satellites:Multispectral and panchromatic imaging systems operating in visible and near-infrared wavelengths. England's space corridor from Harwell to Cornwall concentrates manufacturing demand as the Environment Agency expands flood mapping contracts requiring sub-meter resolution.
- Radar Satellites:Active microwave sensing platforms enabling all-weather, day-night imaging capability. Defense procurement through the Ministry of Defence's Skynet refresh cycles is pulling commercial-grade SAR into border surveillance applications previously reserved for classified systems.
- Hyperspectral Satellites:Narrow-band spectral imaging for material identification and vegetation stress detection.
- Synthetic Aperture Radar:Advanced radar processing achieving fine spatial resolution through signal synthesis.
Optical Satellites command the established base. The steepest expansion runs through Synthetic Aperture Radar.
End User:
Application urgency varies sharply across customer types, with defense and environmental agencies operating on sovereign capability mandates while agriculture and urban planning follow commercial ROI timelines.
- Agriculture:Precision farming and crop yield optimization through vegetation index monitoring. Lloyd's of London syndicates are integrating satellite-derived crop health data into parametric insurance underwriting workflows.
- Urban Planning:Land use change detection and infrastructure development tracking. Local authorities across England's southeast are procuring high-resolution imagery for housing density assessments and green belt monitoring.
- Environmental Monitoring:Climate resilience and ecosystem health assessment.
- Defense:Intelligence, surveillance, and reconnaissance for national security applications.
Defense commands the established base. The steepest expansion runs through Agriculture.
Application:
Maturity gradients separate operational disaster response systems from emerging climate analytics platforms, with data latency requirements dictating technology selection.
- Disaster Management:Rapid damage assessment and emergency response coordination using pre- and post-event imagery. The Environment Agency's flood mapping procurement is accelerating deployment of sub-24-hour revisit constellations for real-time inundation monitoring.
- Climate Change Studies:Long-term trend analysis for carbon accounting and ecosystem modeling. UK Research and Innovation funding is concentrating demand in Scotland's emerging spaceports for polar-orbiting missions capturing cryosphere dynamics.
- Land Use Mapping:Cadastral boundary verification and property registration support.
- Natural Resource Management:Forestry, water, and mineral asset monitoring.
Land Use Mapping commands the established base. Disaster Management shows the steepest climb.
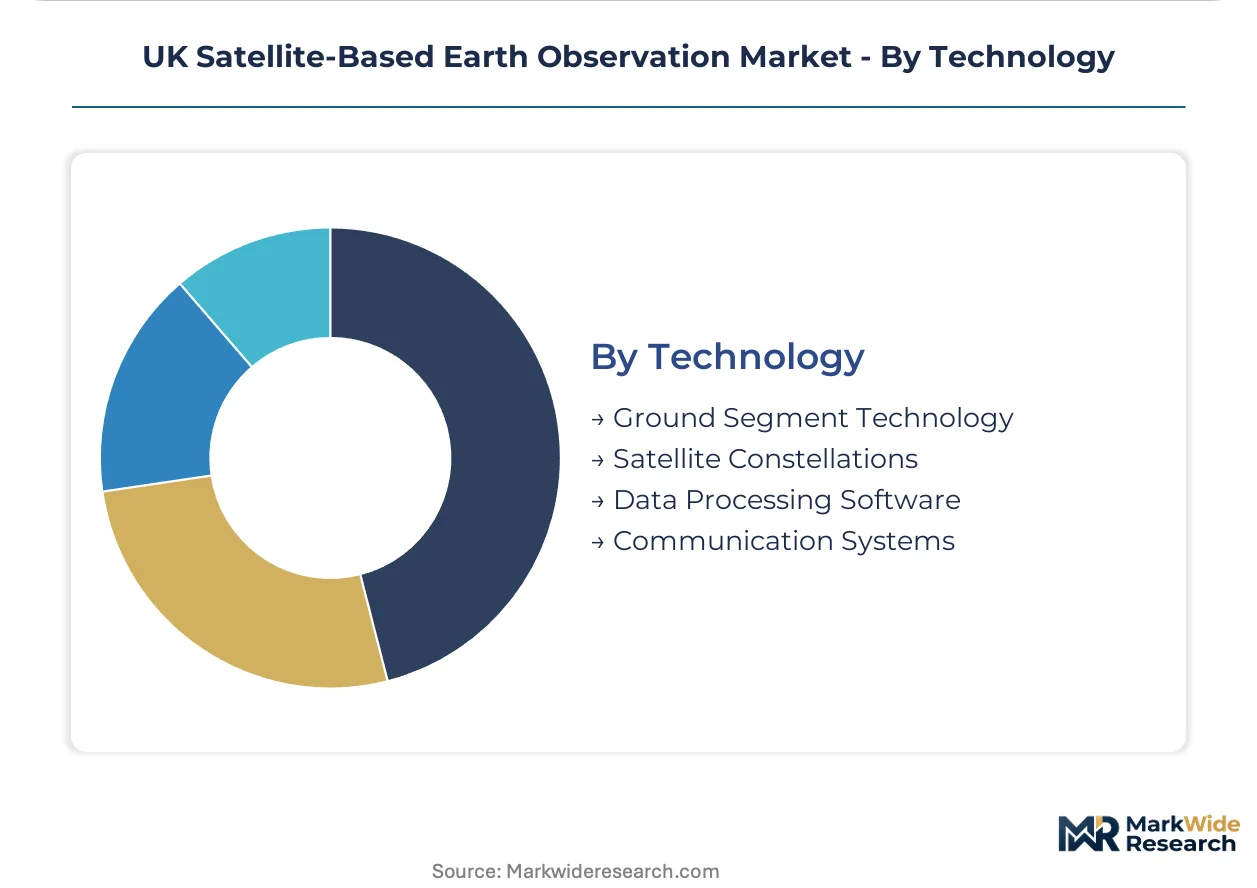
Technology:
Margin capture is concentrating downstream from spacecraft manufacturing toward analytics and connectivity infrastructure, reshaping vendor competitive position.
- Ground Segment Technology:Antenna networks, mission control systems, and data reception infrastructure. Goonhilly Earth Station in Cornwall anchors UK sovereign downlink capability, though new constellation operators face legacy integration friction.
- Satellite Constellations:Coordinated multi-satellite architectures for enhanced revisit frequency. Surrey Satellite Technology Limited's modular bus designs are reducing integration lead times for Earth observation missions launched from England's southwest.
- Data Processing Software:AI-enabled analytics and geospatial intelligence platforms.
- Communication Systems:Inter-satellite links and broadband backhaul for data relay.
Ground Segment Technology commands the established base. Data Processing Software shows the steepest climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UK satellite-based Earth Observation exports flow primarily to European defense and environmental agencies, with downstream analytics services extending into North American insurance markets. Domestic demand concentrates in England's space corridor, where launch infrastructure and manufacturing clusters generate procurement gravity for sovereign payload programs.
England
The Harwell-to-Cornwall corridor anchors UK Earth Observation manufacturing, with the Environment Agency driving sub-meter optical sensor demand for flood mapping contracts. The UK Space Agency's National Space Strategy mandates sovereign capability investment through the Space Industry Act 2018 licensing framework. Cornwall's co-located launch infrastructure and Goonhilly Earth Station downlink capacity are compressing integration lead times for commercial constellation operators.
Scotland
SaxaVord and Sutherland spaceports are advancing polar orbit access for synthetic aperture radar constellations serving cryosphere monitoring. UK Research and Innovation funding concentrates climate analytics demand in northern latitude missions. Glasgow's emerging satellite manufacturing base is absorbing RF engineering talent from legacy defense contractors for smallsar payload development.
Wales
Cardiff-based analytics providers are processing multispectral feeds for agricultural underwriting workflows serving Lloyd's of London syndicates. The country's national space regulator coordinates with the Civil Aviation Authority on dual-use payload classification reviews. Snowdonia's radio-quiet zones support calibration activities for radar sensor validation prior to orbital deployment.
Northern Ireland
Belfast's aerospace supply chain feeds composite structures and precision optics into UK-wide satellite bus assembly lines. The region's universities collaborate with RAL Space on hyperspectral instrument development for environmental monitoring missions. Local manufacturing clusters specialize in lightweight materials reducing launch mass for smallsat constellations.
UK Satellite-Based Earth Observation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware manufacturing, ground infrastructure, and analytics service layers. The vendor base separates into three tiers: legacy defense contractors holding sovereign payload contracts, agile smallsat manufacturers with modular bus architectures, and AI-enabled analytics platforms capturing downstream value. Consolidation pressures concentrate in the ground segment, where established earth station operators face interoperability demands from new constellation entrants. Dominant competitive moves include strategic partnerships between launch providers and satellite manufacturers, plus vertical integration into data processing software.
Among UK-based system integrators, Airbus Defence and Space UK and Surrey Satellite Technology Limited exemplify contrasting scale archetypes within sovereign payload production. Airbus Defence and Space UK occupies a position aligned with Ministry of Defence Skynet program requirements, while Surrey Satellite Technology Limited represents the modular smallsat approach reducing time-to-orbit for commercial Earth observation missions. Earth-i Ltd sits within the analytics-specialist tier, converting raw sensor data into subscription intelligence feeds for insurance and agricultural buyer segments.
| Leading Market Players |
|---|
| Thales Group |
| Airbus Defence and Space UK |
| Surrey Satellite Technology Limited (SSTL) |
| Telespazio UK Ltd |
| Earth-i Ltd |
| Maxar Technologies |
| RAL Space |
| SatVu |
| Rezatec Ltd |
| Others |
Pricing and Supply Chain Analysis
Harwell's concentrated payload engineering capacity feeds directly into pricing power for synthetic aperture radar manufacturers serving Ministry of Defence border surveillance contracts. Gallium arsenide substrate allocation constraints from East Asian foundries compress margins for optical sensor producers while elevating premiums for sovereign-qualified supply chains.
Pricing Analysis
Next-generation commercial SAR platforms undercut legacy military-grade pricing by forty to sixty percent, collapsing the historical technology-generation gap that protected classified program premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by resolution grade and sovereign certification status under the Space Industry Act 2018. Cost compression in standard-tier optical imagery is intensifying because Environment Agency flood mapping contracts consolidate procurement volume. Agricultural buyers exhibit highest price sensitivity, while defense agencies accept premium positioning for guaranteed supply security.
Supply Chain Analysis
Tariff exposure between UK operators and Taiwanese compound semiconductor foundries dominates supply chain risk planning for payload manufacturers. Satellite bus assembly draws from UK composite structures, German precision optics, and US radiation-hardened electronics. Gallium arsenide substrates, star tracker components, and solid-state propulsion systems anchor critical input dependencies. Single-source vulnerability concentrates in East Asian gallium arsenide supply. Distribution runs through sovereign procurement channels for defense applications and API-integrated data feeds for commercial analytics buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
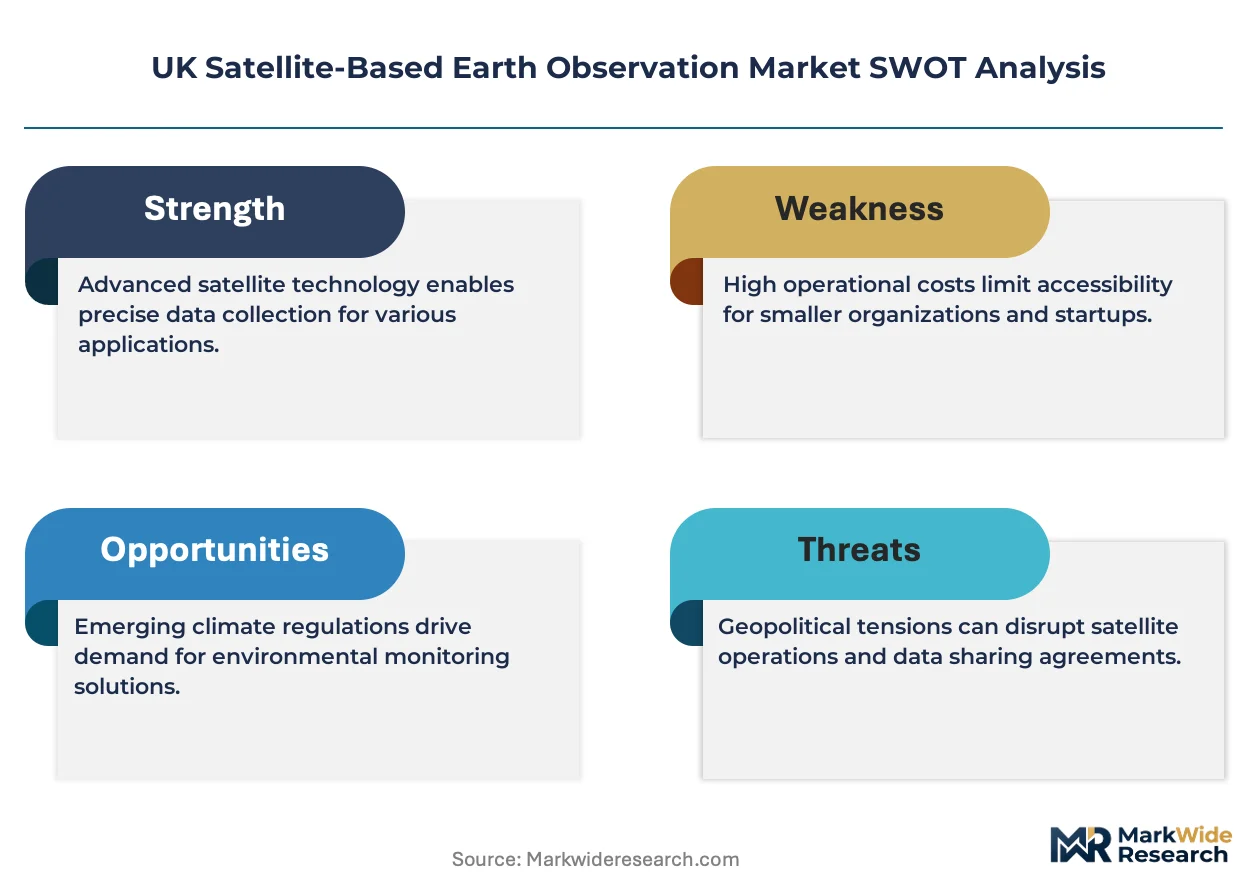
The UK Satellite-Based Earth Observation Market is shifting toward platform economics as subscription-based analytics APIs displace per-image licensing, with interoperability demands from Lloyd's syndicates and agritech platforms forcing data standardization across previously siloed provider ecosystems.
For Market Incumbents: Harden sovereign payload production positions by securing gallium arsenide substrate offtake agreements with Taiwanese foundries before allocation constraints tighten. Deepen backward integration into optical component manufacturing at Portsmouth and Harwell facilities to offset margin compression from commercial SAR entrants. Channel control through Goonhilly Earth Station downlink capacity represents the critical defensive lever against Scotland-based constellation operators.
For New Entrants and Emerging Players: Build out AI-enabled change detection capabilities for agricultural underwriting workflows, where Lloyd's of London syndicates show lowest switching costs and highest willingness to adopt new data feeds. Scotland's emerging spaceports offer the most penetrable geographic entry point for polar-orbiting SAR constellations serving cryosphere monitoring demand. A go-to-market angle anchored in parametric insurance API integration bypasses entrenched value-added reseller channels.
For Investors and Strategic Acquirers: Long-term, this sits as a data-layer consolidation play because downstream analytics platforms capture disproportionate margin pools as hardware commoditizes. Acquisition targets should emphasize modular smallsat bus designers with proven Civil Aviation Authority licensing traction and established RF engineering teams. The signal to watch is Environment Agency procurement shifting from per-scene to subscription-based contracts, indicating tipping point adoption for platform economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native data feeds displace per-image licensing for Lloyd's agricultural underwriting workflows. |
| Strategic Partnership | Launch provider alliances with Cornwall spaceport operators compress constellation deployment timelines. |
| Acquisition of Specialist Firm | RF engineering talent pools in Glasgow and Portsmouth address payload design scarcity constraints. |
| Geographic Expansion | SaxaVord and Sutherland licensing opens polar orbit access for cryosphere monitoring missions. |
| Product Launch | AI-enabled change detection analytics create subscription revenue models displacing legacy licensing. |
Research Methodology
Desk research of UK Space Agency procurement databases, Civil Aviation Authority licensing records, and Environment Agency contract awards preceded structured interviews with satellite bus engineering directors, SAR payload specialists, Earth observation data procurement officers at defense agencies, and agricultural insurance underwriters at Lloyd's syndicates. Secondary validation incorporated Ministry of Defence Skynet program disclosures, UK Research and Innovation funding announcements, and ISO 19115 geospatial standard documentation. Bottom-up constellation deployment modeling triangulated against top-down sovereign capability investment forecasts.
Assumptions held fixed across the analysis window include UK Space Agency National Space Strategy funding continuity and Space Industry Act 2018 regulatory framework stability, while launch cadence at Cornwall and Scotland spaceports and gallium arsenide substrate pricing were varied as sensitivity inputs. Segmentation dimensions modeled encompassed payload type, end-user vertical, application urgency, and technology layer. CAGRs derived from installed base refresh cycles and procurement pipeline visibility across defense and environmental agency budgets. Industry-specific forecast inputs incorporated Skynet program refresh timelines and Environment Agency flood mapping contract award patterns.
Sensitivities concentrate around Civil Aviation Authority licensing delays for dual-use payloads and gallium arsenide supply allocation disruptions from East Asian foundries. Forecasts reflect documented assumptions regarding sovereign capability mandate durability and commercial SAR miniaturization trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
India Satellite Communication Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
North America Small Satellite Market
Satellite
United Kingdom Satellite Communications Market
Satellite
Sudan Satellite Transponder Market
Satellite
Satellite Communication Subsystem Market
Satellite
Global Broadband Satellite Services Market
Satellite
Global Satellite Modem Market
Satellite
Electric Propulsion Satellite Market
Satellite
North America Satellite Bus Market
Satellite
Low-Cost Satellite Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
UAE Satellite Imagery Services Market
Satellite
India Satellite Connectivity Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Satellite Communication Equipment Market