
 Mexico Satellite Connectivity Market | 2026-2036
Mexico Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Satellite Connectivity Market Insights
A wide capital-intensity divergence between players is redrawing competitive boundaries in Mexico's satellite sector. Starlink leverages its vertically integrated launch-to-terminal stack to undercut legacy pricing in underserved municipalities. Viasat Inc anchors its position through high-throughput GEO capacity contracts with federal connectivity programs. Embratel competes by bundling satellite backhaul with its existing fiber infrastructure across the Yucatan Peninsula.
Mexico satellite connectivity encompasses the transmission of data, voice, and video signals via orbiting spacecraft to ground-based terminals operating across L-band through Ka-band frequencies, with latency profiles ranging from sub-50 milliseconds for low Earth orbit systems to 500-plus milliseconds for geostationary platforms. This infrastructure serves commercial and government users requiring communications beyond the reach of terrestrial networks. Broadband services dominate revenue as remote enterprises and residential subscribers purchase fixed and mobility data plans. LEO technology captures the fastest expansion due to its superior latency performance for real-time applications. Ground station infrastructure represents a concentrated margin pool given Mexico's strategic equatorial-adjacent geography for satellite tracking.
Mexico's Federal Telecommunications Institute governs spectrum allocation and orbital slot coordination, while the Secretariat of Infrastructure, Communications and Transportation oversees satellite earth station licensing and national security compliance for foreign-operated constellations. These frameworks shape market access by requiring domestic gateway presence and data sovereignty provisions for government contracts. Stakeholders must monitor pending reforms to the Federal Telecommunications and Broadcasting Law that could mandate local partnership structures for non-Mexican operators.
Market Dynamics
The Federal Telecommunications Institute's spectrum reforms for non-geostationary constellations are compressing permit timelines and accelerating LEO deployment across southern states where terrestrial fiber economics fail.
Growth Catalysts
- IFT Spectrum Reforms:The Federal Telecommunications Institute streamlined non-geostationary orbital slot allocation, reducing regulatory lag for constellation operators seeking Mexican market entry.
- Chiapas Backhaul Demand:Telecom operators in this southern state are deploying satellite links to extend mobile coverage where mountainous terrain blocks terrestrial infrastructure deployment.
- Ka-band Terminal Proliferation:Flat-panel antenna manufacturing advances are lowering subscriber hardware costs for residential broadband adoption in Oaxaca's remote municipalities.
Market Restraints
- Gateway Infrastructure Concentration:Domestic earth station capacity clusters around Mexico City and Querétaro, creating single-point vulnerabilities for national connectivity.
- Import Tariff Volatility:Satellite terminal equipment faces unpredictable customs duties under Mexico's Harmonized Tariff Schedule, distorting operator capex planning.
- Terrestrial Wireless Substitution:4G and emerging 5G fixed wireless access from Altán Redes is capturing price-sensitive subscribers in semi-urban transition zones.
Strategic Opportunities
- Yucatan Peninsula Maritime:Offshore oil platforms and cruise shipping lanes present untapped mobility service demand for low-latency LEO connectivity.
- Federal Connectivity Programs:The Secretariat of Infrastructure's Internet para Todos initiative reserves budget for satellite backhaul in designated underserved localities.
- AgTech Convergence:Precision agriculture operators in Sinaloa and Sonora are integrating satellite IoT with drone-based crop monitoring for real-time irrigation management.
Industry Challenges
- RF Engineer Scarcity:Mexican universities produce insufficient Ka-band system specialists, forcing operators to recruit from Spain and Argentina at premium compensation.
- Legacy GEO Integration:Federal agencies maintaining geostationary contracts face operational friction when blending LEO services into existing procurement frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Satellite Connectivity Market |
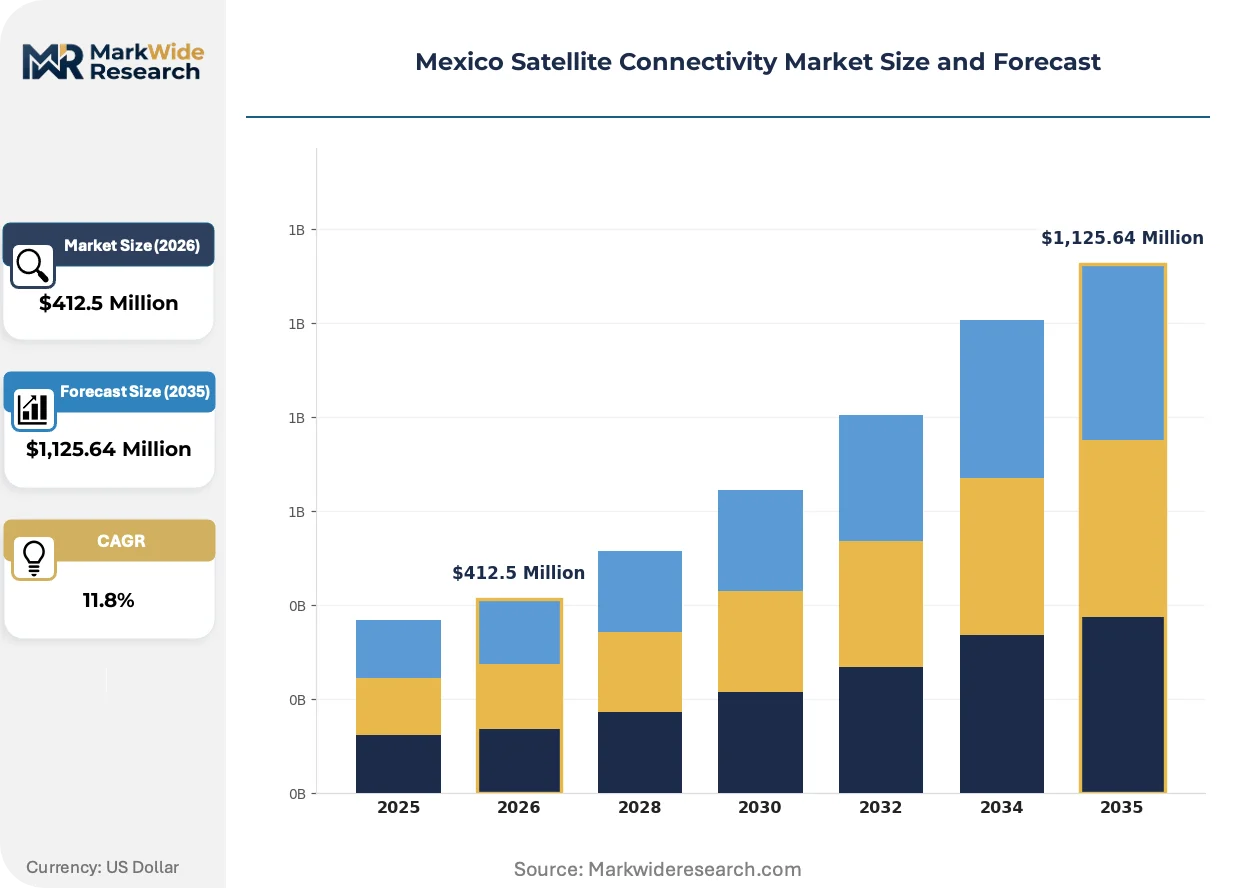
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,125.64 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Station, Satellite Terminal, Antenna, Router Service Type: Broadband Services, Data Services, Voice Services, Video Services End User: Aerospace, Defense, Telecom, Oil & Gas Technology: LEO, MEO, GEO, Hybrid |
| Companies Covered | Starlink, Viasat Inc, EchoStar Corp, Eutelsat Communications, Hispasat, Thuraya Telecommunications, Singapore Telecommunications Ltd, Embratel, Foxconn, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Satellite Connectivity Market Trends and Innovations
Active electron beam steering and software-defined radio architectures are compressing terminal form factors while expanding frequency agility across Mexico's diverse terrain and regulatory zones.
Phased-array flat-panel technology is miniaturizing. These solid-state antennas eliminate mechanical steering components, reducing weight and power draw for residential installations. Ranching cooperatives in Chihuahua and Durango are adopting these units for remote estate management. The technology is miniaturizing deployment logistics, allowing direct-to-consumer shipping that bypasses specialized installation crews.
The Federal Telecommunications Institute's 2023 orbital debris mitigation guidelines now mandate end-of-life deorbit plans for all non-geostationary license applicants. This policy elevates compliance costs for constellation aspirants but favors established operators with proven disposal track records. Small-satellite ventures targeting Mexican spectrum are responding by partnering with European launch providers carrying certified deorbit mechanisms.
Enterprise buyers in mining and energy verticals are unbundling connectivity from managed service packages. These firms now procure raw satellite capacity directly, layering their own cybersecurity and application management. The shift compresses margins for traditional systems integrators. This pattern is most visible in Campeche's offshore oil fields, where Pemex subsidiaries negotiate direct LEO contracts rather than routing through incumbent telecom resellers.
Mexico Satellite Connectivity Market Segmentation
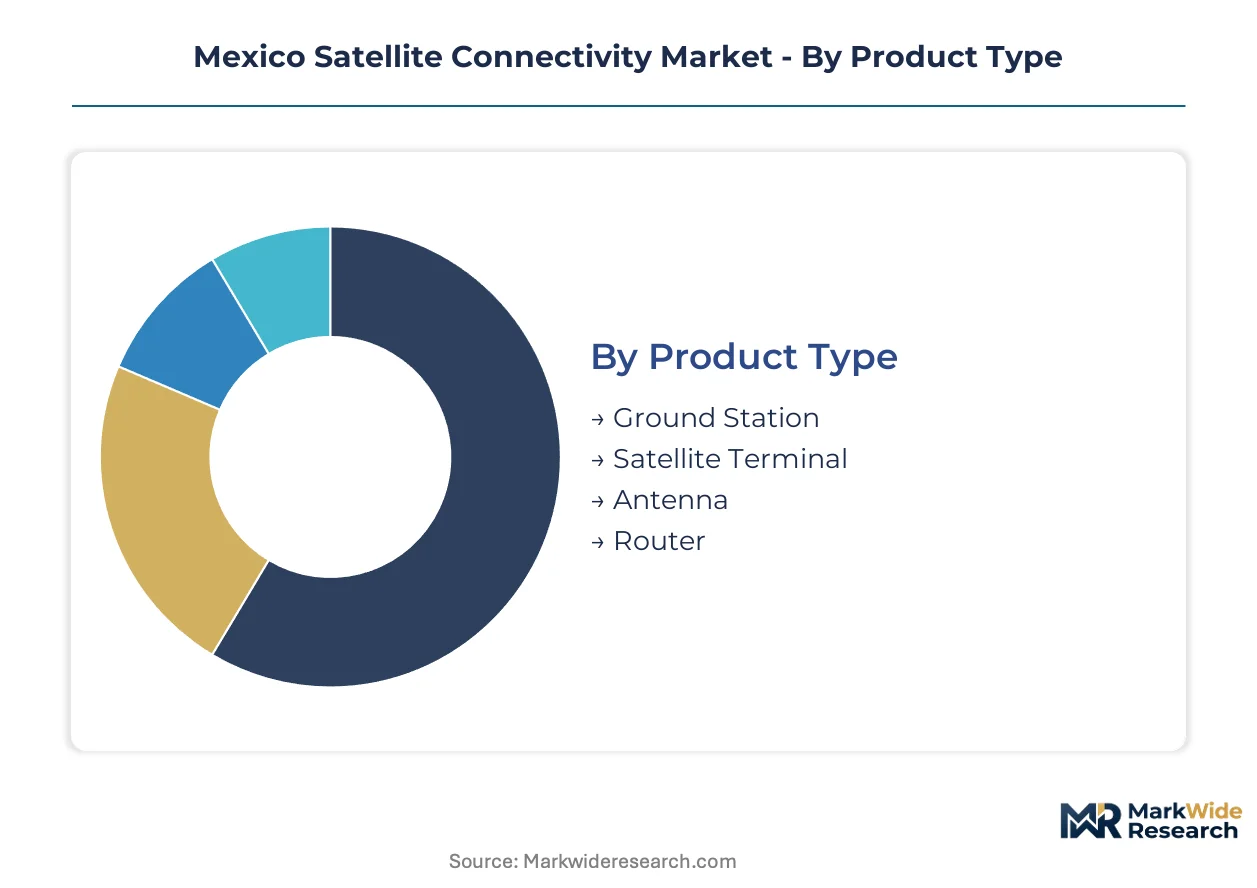
Mexico's satellite connectivity market fragments across hardware, service, vertical, and orbital technology dimensions. Each segmentation layer reveals distinct procurement patterns shaped by geography, latency requirements, and federal program eligibility.
Product Type:
Domestic manufacturing concentrates in Querétaro's aerospace corridor for ground station assemblies, while terminal imports dominate consumer-facing hardware.
- Ground Station:Earth station facilities integrate antenna arrays, RF equipment, and network operations centers for signal uplink and downlink. Demand clusters around Mexico City and Querétaro where IFT licensing requirements mandate domestic gateway presence for foreign constellation operators.
- Satellite Terminal:User equipment spans fixed VSAT installations and mobility-grade flat-panel units for maritime and aeronautical applications. Chiapas and Oaxaca municipalities drive residential adoption through federal subsidy programs targeting unserved localities.
- Antenna:Parabolic reflectors and phased-array systems convert electromagnetic signals for terrestrial network integration.
- Router:CPE devices manage last-mile distribution of satellite backhaul to local area networks.
Ground station infrastructure commands the established base. The steepest expansion runs through satellite terminal shipments to southern state broadband initiatives.
Service Type:
Revenue concentration follows bandwidth intensity, with high-throughput applications outpacing legacy narrowband offerings.
- Broadband Services:High-speed internet delivery via Ka-band and Ku-band capacity supports residential, enterprise, and mobility subscribers. Telecom operators in mountainous southern states deploy these services where fiber trenching costs exceed satellite economics by order of magnitude.
- Data Services:Machine-to-machine connectivity and IoT backhaul enable remote asset monitoring. Precision agriculture operators in Sinaloa integrate these links with drone-based irrigation systems for real-time field telemetry.
- Voice Services:Satellite telephony provides primary communications for maritime vessels and isolated mining camps.
- Video Services:Broadcast contribution and distribution feeds serve television networks and emergency response coordination.
Broadband services anchor current revenue pools. Data services for industrial IoT are gaining share fastest as AgTech and energy verticals digitize operations.
End User:
Procurement authority splits between federal agencies with sovereignty requirements and commercial operators seeking cost-optimized capacity.
- Aerospace:Airlines and business aviation fleets require continuous connectivity across Mexican airspace. Low-latency LEO contracts are displacing legacy GEO agreements for cockpit communications and passenger WiFi.
- Defense:Military and national security applications mandate encrypted, sovereign-controlled satellite links. Secretariat of National Defense installations prioritize domestic gateway routing for classified traffic.
- Telecom:Mobile network operators lease satellite backhaul to extend coverage into terrain-blocked regions.
- Oil & Gas:Offshore platforms and pipeline monitoring systems depend on reliable connectivity beyond terrestrial infrastructure reach.
Telecom backhaul commands the established base. Aerospace mobility contracts are climbing the fastest as Mexican carriers modernize fleets.
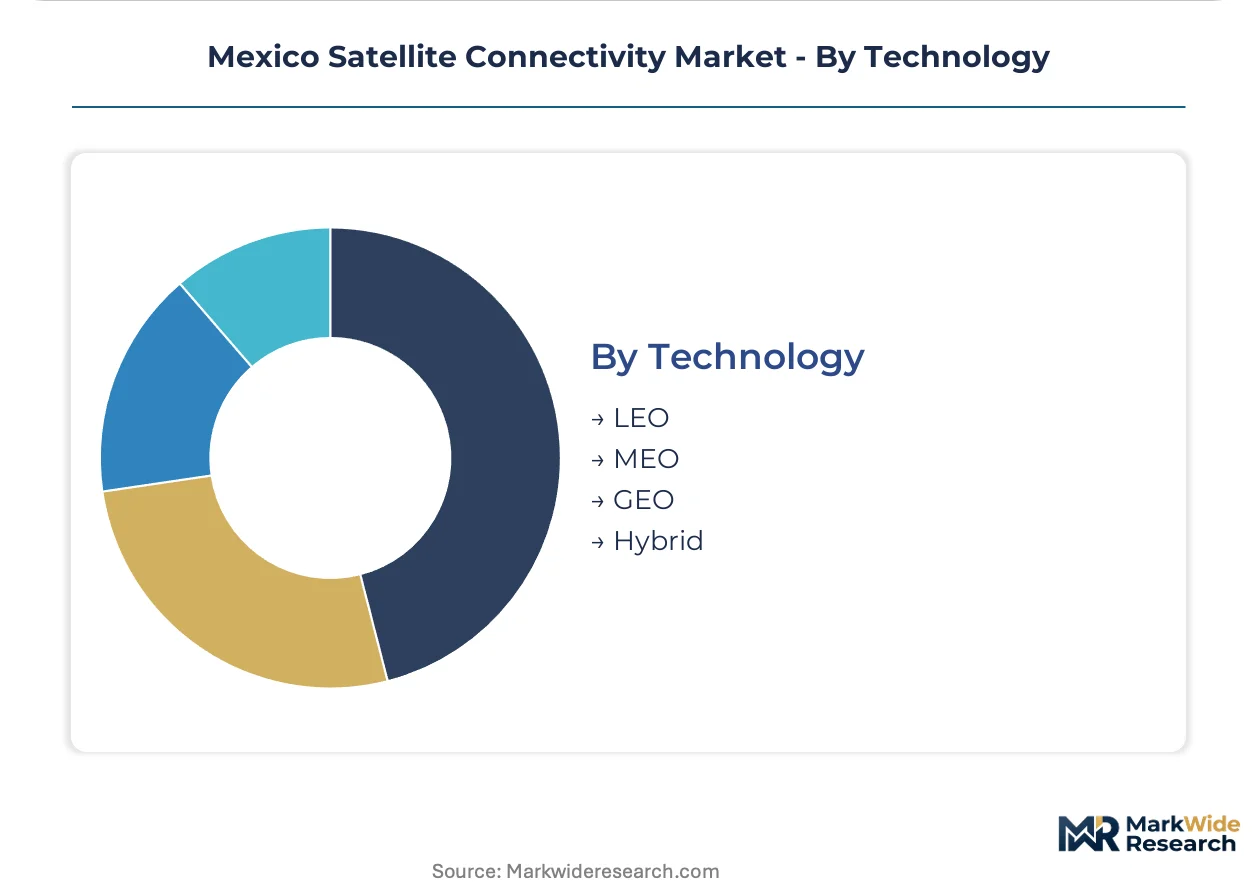
Technology:
Orbital architecture selection trades latency performance against coverage economics and regulatory compliance burden.
- LEO:Low Earth orbit constellations deliver sub-50 millisecond latency through dense satellite shells at 550-1200 kilometer altitudes. IFT's streamlined non-geostationary permitting is accelerating constellation gateway deployment across Mexican territory.
- GEO:Geostationary platforms at 35,786 kilometers provide persistent regional coverage with proven reliability. Federal agencies maintain these contracts for broadcast and emergency communications where latency tolerance permits.
- MEO:Medium Earth orbit systems balance latency and coverage for specialized maritime and aeronautical applications.
- Hybrid:Multi-orbit service aggregation blends LEO responsiveness with GEO resilience for mission-critical enterprise networks.
GEO technology commands the established base. LEO infrastructure is expanding most quickly as constellation operators secure Mexican spectrum allocations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southern Mexico deploys satellite connectivity for residential broadband where fiber economics collapse, while northern states concentrate capacity on industrial IoT and cross-border logistics tracking. This consumption-mix differential shapes procurement patterns across sub-regions.
Mexico City Metro
Federal agencies and financial institutions dominate demand for low-latency LEO services in the capital region. The Federal Telecommunications Institute maintains its headquarters here, streamlining spectrum coordination for constellation operators seeking national permits. Querétaro's aerospace corridor supplies ground station assemblies to gateway facilities clustered around the metropolitan area.
Nuevo León
Industrial manufacturers in Monterrey integrate satellite IoT for cross-border supply chain visibility into Texas manufacturing hubs. State economic development incentives support precision agriculture pilots in adjacent rural municipalities. The concentration of automotive assembly plants drives private network demand for backup connectivity beyond terrestrial infrastructure.
Jalisco
Guadalajara's technology sector consumes high-throughput capacity for data center disaster recovery and cloud edge extensions. State government connectivity programs target unserved communities in the Sierra Madre Occidental where terrain blocks cellular deployment. The Guadalajara metro area anchors software development for satellite-enabled application platforms.
Yucatán Peninsula
Offshore oil platforms and cruise shipping lanes generate mobility service demand across Campeche Bay waters. Embratel bundles satellite backhaul with fiber infrastructure for tourism-dependent coastal municipalities. The Secretariat of Infrastructure's Internet para Todos initiative reserves dedicated budget for Quintana Roo's underserved localities.
Northern Border States
Chihuahua and Sonora ranching cooperatives adopt flat-panel terminals for remote estate management and precision livestock monitoring. Import-dependent hardware distribution faces customs duty volatility under the Harmonized Tariff Schedule. Cross-border logistics operators track freight movements via satellite links where cellular coverage drops along remote highway corridors.
Mexico Satellite Connectivity Market Competitive Landscape
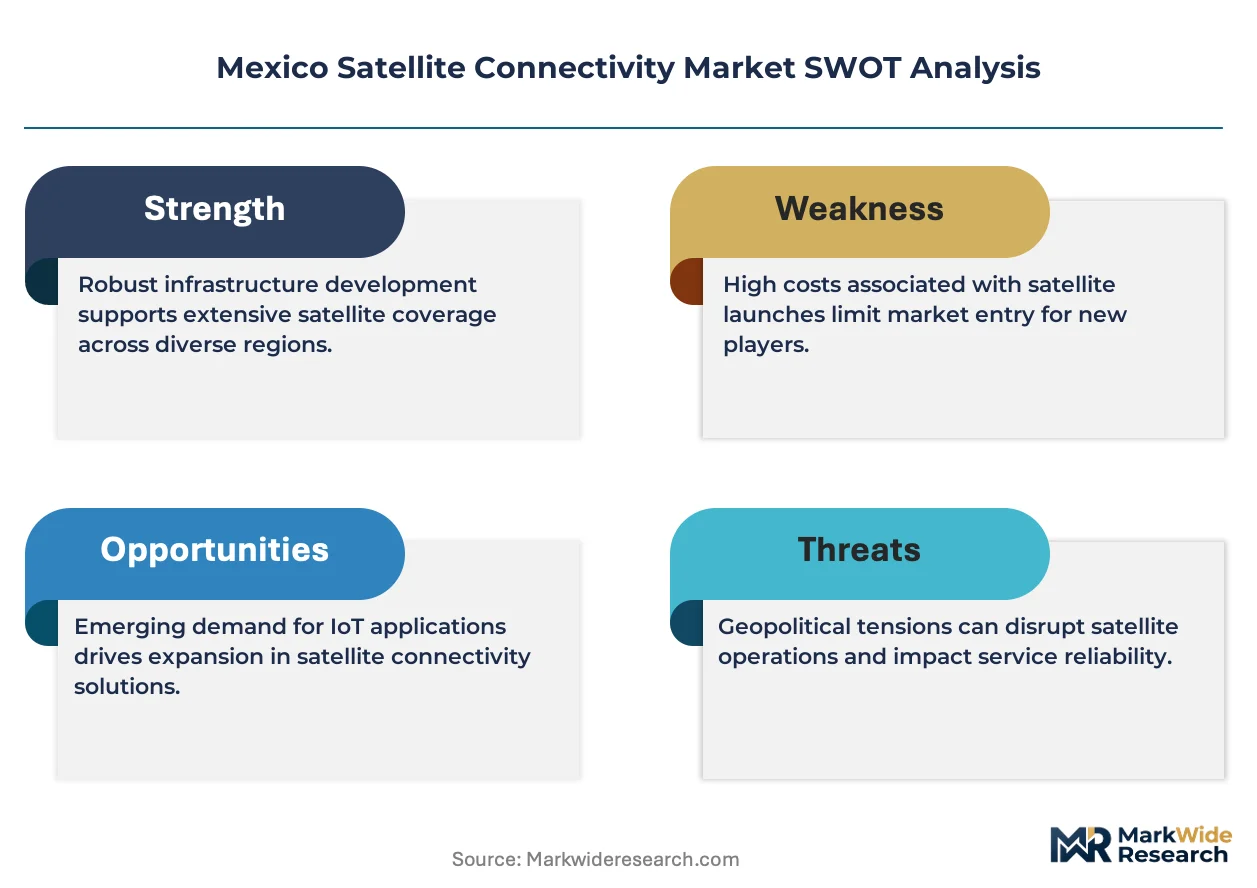
A small set of integrated leaders sits above a broader specialist tier that fragments across orbital technologies and vertical applications. The upper tier commands gateway infrastructure and spectrum holdings that constrain market entry. Three archetypes define competitive positioning: vertically integrated constellation operators, regional telecom bundlers, and specialized maritime-aerospace service providers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing terrestrial backhaul integration and federal program eligibility.
Within the constellation operator tier, Starlink and Viasat Inc occupy positions representing divergent orbital strategies—LEO latency optimization versus GEO reliability anchoring. Embratel exemplifies the regional bundler archetype, leveraging existing infrastructure relationships to capture government connectivity program awards. These three companies collectively illustrate how market access depends on regulatory navigation capabilities and domestic partnership structures rather than technology specifications alone.
| Leading Market Players |
|---|
| Starlink |
| Viasat Inc |
| EchoStar Corp |
| Eutelsat Communications |
| Hispasat |
| Thuraya Telecommunications |
| Singapore Telecommunications Ltd |
| Embratel |
| Foxconn |
| Others |
Pricing and Supply Chain Analysis
Ninety-day gateway equipment lead times concentrate pricing power with Querétaro-based integrators who control domestic earth station assembly. This inventory compression amplifies margin capture for terminal manufacturers while forcing constellation operators to pre-position hardware ahead of IFT licensing decisions.
Pricing Analysis
Long-term capacity offtakes dominate enterprise procurement, with federal connectivity programs locking in three-year backhaul contracts at fixed rates. Subscription-tier pricing separates sovereign-grade encrypted links from standard residential broadband, with after-sales service bundling commanding premiums in Chiapas and Oaxaca. Cost compression in consumer terminals intensifies as flat-panel manufacturing scales, though import tariff volatility under Altán Redes' fixed wireless access captures price-sensitive subscribers in semi-urban transition zones. Government buyers exhibit lowest price sensitivity due to sovereignty mandates, while ranching cooperatives in northern states negotiate aggressively on hardware costs.
Supply Chain Analysis
Laredo customs clearance chokepoints govern terminal import velocity into Mexican distribution networks. Semiconductor fabrication draws from Taiwan and South Korea for RF chipsets, while phased-array antenna substrates source from Japan and Germany. Single-source vulnerability concentrates in Ka-band power amplifier modules where domestic alternatives remain unqualified. Distribution runs through Mexico City and Querétaro logistics hubs before final-mile deployment to southern state municipalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's satellite connectivity market functions as a regulatory-moat arena where IFT licensing entrenchment creates defensible positions. Switching costs for federal agencies escalate due to sovereign gateway requirements and encrypted traffic routing mandates.
For Market Incumbents: Fortify domestic gateway infrastructure in Querétaro to preempt LEO constellation entrants seeking rapid market access. Deepen backward integration into flat-panel terminal assembly to offset Harmonized Tariff Schedule volatility. Altán Redes' fixed wireless expansion in semi-urban zones threatens satellite residential subscriptions, requiring differentiated latency positioning for real-time applications. For New Entrants and Emerging Players: Lead with precision agriculture IoT in Sinaloa and Sonora where terrestrial coverage gaps persist and federal subsidy eligibility attaches to satellite-specific procurement. Maritime mobility off Campeche presents the most penetrable white space, with direct Pemex subsidiary contracting bypassing incumbent telecom resellers. Channel strategy should prioritize AgTech dealer networks over consumer retail distribution. For Investors and Strategic Acquirers: Carve-out targets emerge from Latin American telecom holding companies with stranded GEO capacity contracts and underutilized earth station assets. Five-to-ten-year viability hinges on successful LEO-GEO service blending for federal agency accounts. Monitor IFT orbital debris compliance enforcement as inflection signal—operators with certified deorbit mechanisms will capture accelerated permitting timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Gateway Infrastructure Expansion | Querétaro facility additions satisfy IFT domestic presence mandates for LEO entrants. |
| Vertical Integration into Terminal Manufacturing | In-house flat-panel production mitigates Harmonized Tariff Schedule duty exposure. |
| Federal Program Certification | Internet para Todos eligibility unlocks dedicated backhaul budgets in Oaxaca and Chiapas. |
| AgTech Channel Partnership | Sinaloa irrigation cooperative networks provide embedded routes for IoT service distribution. |
| Multi-Orbit Service Aggregation | Hybrid LEO-GEO offerings address federal agency latency tolerance and resilience requirements. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with satellite network engineers, federal procurement officers, and AgTech systems integrators, alongside secondary validation through IFT spectrum allocation records, Secretariat of Infrastructure connectivity program disclosures, and customs import databases. Primary fieldwork encompassed ground station operators in Querétaro, terminal distribution channels in Mexico City, and precision agriculture deployments in Sinaloa. Secondary sources included FCC filings by constellation operators, ITU satellite coordination notices, and trade data from Mexico's National Institute of Statistics and Geography. Bottom-up terminal shipment estimates triangulated against top-down federal program budget allocations.
Across the analysis window, the forecast framework modeled demand by orbital technology, service type, and end-user vertical, with additional segmentation for federal program eligibility zones. CAGRs derived from installed base growth curves, replacement cycles for legacy VSAT equipment, and LEO constellation gateway deployment timelines. Key inputs encompassed IFT permitting velocity assumptions, flat-panel cost decline trajectories, and Altán Redes fixed wireless coverage expansion maps.
The analysis sits within stated boundaries; outcomes outside sustained federal connectivity program funding or accelerated IFT spectrum reform timelines would require recalibration. Forecasts reflect documented assumptions regarding constellation launch schedules and terminal manufacturing scale-up. Practitioners should keep alternative scenarios live as regulatory enforcement patterns and terrestrial wireless substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Indonesia Satellite Communications Market
Satellite
Europe Satellite Attitude and Orbit Control System Market
Satellite
Spain Satellite Imagery Services Market
Satellite
South Korea Satellite Communication Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
Saudi Arabia Satellite Imagery Services Market
Satellite
Satellite Data Analytics Services Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Russia Satellite Connectivity Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
All-Electric Propulsion Satellites Market
Satellite
Satellite Antenna Market
Satellite
ASEAN Satellite Imagery Services Market
Satellite
US Satellite-Based Earth Observation Market
Satellite
Reusable Satellite Launch Vehicle (RSLV) Market