
 Latin America Satellite Connectivity Market | 2026-2036
Latin America Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Satellite Connectivity Market Analytics
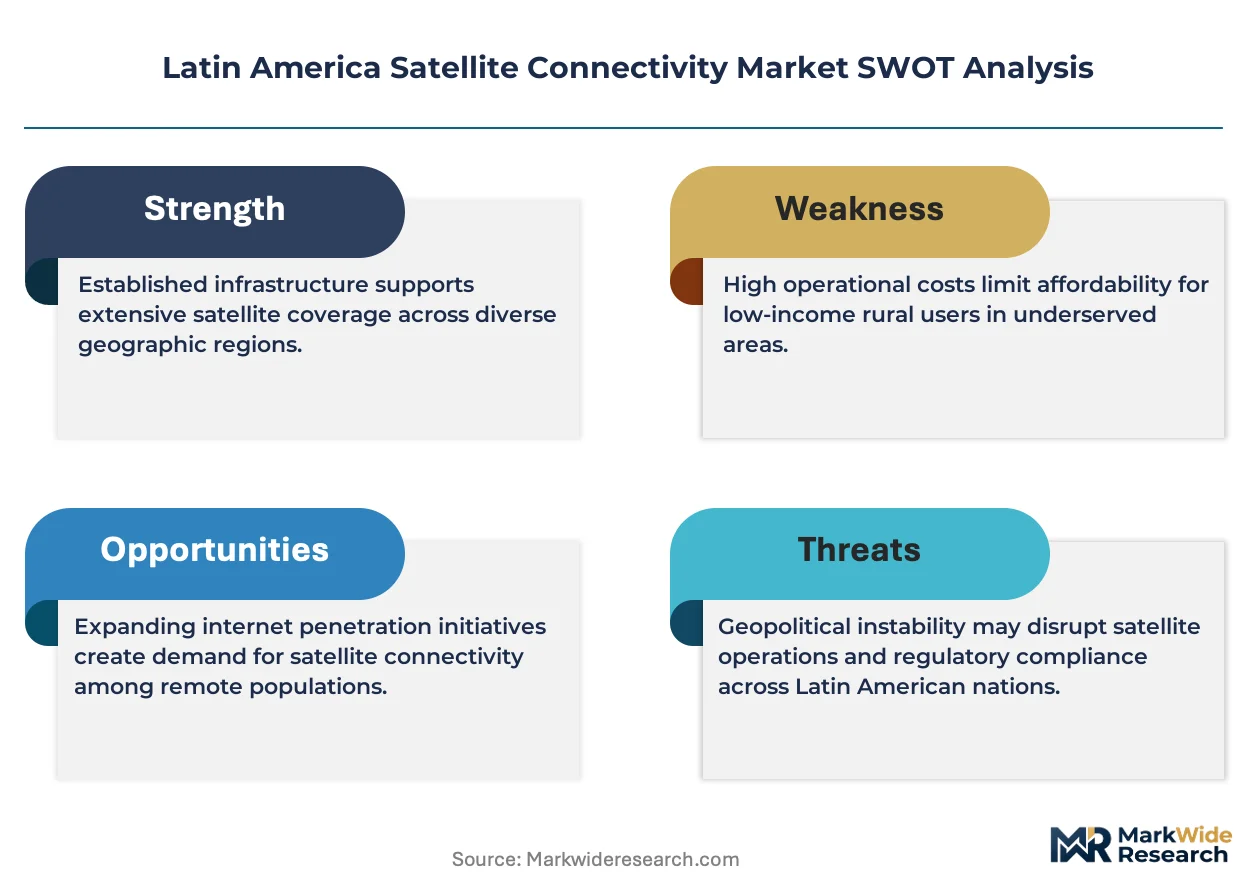
Multi-source procurement from dedicated GEO fleets and emerging LEO constellations is rebalancing vendor relationships across Latin America. SES anchors its position through extensive Ku-band coverage over the Andean ridge. Intelsat competes with flexible managed-service contracts tailored to enterprise clients. Starlink leverages its growing LEO shell to reach remote mining camps and rural clinics beyond fiber reach.
Latin America satellite connectivity encompasses orbital and ground-based systems transmitting voice, data, and video across C-band, Ku-band, Ka-band, and optical frequencies to serve regions lacking terrestrial infrastructure. GEO satellites maintain fixed orbital positions at 35,786 kilometers, delivering persistent broadcast and broadband coverage to dispersed populations. LEO satellites represent the fastest-expanding product category as constellation operators deploy compact, low-latency platforms for real-time applications. Internet access commands the dominant application share where fiber backhaul remains uneconomical, while maritime communication builds margin pools through specialized stabilized terminals and dedicated bandwidth agreements.
Brazil's Anatel, Mexico's IFT, and Argentina's ENACOM shape market access through spectrum allocation rules and orbital slot coordination requirements that favor licensed operators with proven compliance records. These regulators increasingly scrutinize debris mitigation plans and gateway security standards as constellation density rises. Stakeholders must track pending spectrum harmonization decisions across Mercosur and the Pacific Alliance that could unify equipment certification or fragment operational requirements.
Market Dynamics
The collision between legacy geostationary infrastructure and proliferating low-earth-orbit constellations is fragmenting procurement patterns across Latin America. Buyers now arbitrage latency, coverage, and price across orbital regimes, forcing incumbents to restructure service architectures.
Growth Catalysts
- IFT Licensing Reform:Mexico's streamlined non-geostationary orbit authorization rules compress market entry timelines for constellation operators seeking gateway deployment rights.
- Precision Agriculture Uptake:Brazil's expanding soybean and cattle operations deploy satellite-guided variable-rate application systems across Mato Grosso and Goiás states.
- Offshore Energy Demand:Deepwater pre-salt platforms in Brazil's Santos Basin require redundant high-throughput links for real-time drilling telemetry and crew welfare services.
Market Restraints
- Gateway Infrastructure Concentration:Terrestrial fiber backhaul for satellite ground stations clusters in São Paulo and Mexico City, creating single-point vulnerabilities for regional networks.
- Spectrum Coordination Friction:Pending harmonization disputes across Mercosur member states delay unified equipment certification and raise compliance costs for multi-country operators.
- Terrestrial Wireless Substitution:Expanding 4G and early 5G coverage in Colombia's Andean corridors and Chile's central valley erodes addressable market for satellite broadband in semi-urban zones.
Strategic Opportunities
- Amazon Basin Connectivity Gap:Roraima and Acre states in Brazil plus Loreto Department in Peru present underserved populations beyond fiber economics and cellular backhaul reach.
- LEO-GEO Hybrid Architectures:Converged managed services blending Starlink's low-latency shells with SES's persistent Ku-band broadcast coverage enable tiered enterprise offerings.
- Maritime IoT Expansion:Argentine and Uruguayan fishing fleets plus Chilean salmon aquaculture operations seek vessel tracking and cold-chain monitoring via dedicated MSS terminals.
Industry Challenges
- RF Engineering Talent Scarcity:Ground station operations and satellite network operations centers across the region compete for limited pools of Ka-band link budget specialists and orbital mechanics analysts.
- Debris Mitigation Compliance:ANATEL and ENACOM increasingly mandate end-of-life deorbiting plans and collision avoidance system documentation, extending licensing review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Satellite Connectivity Market |
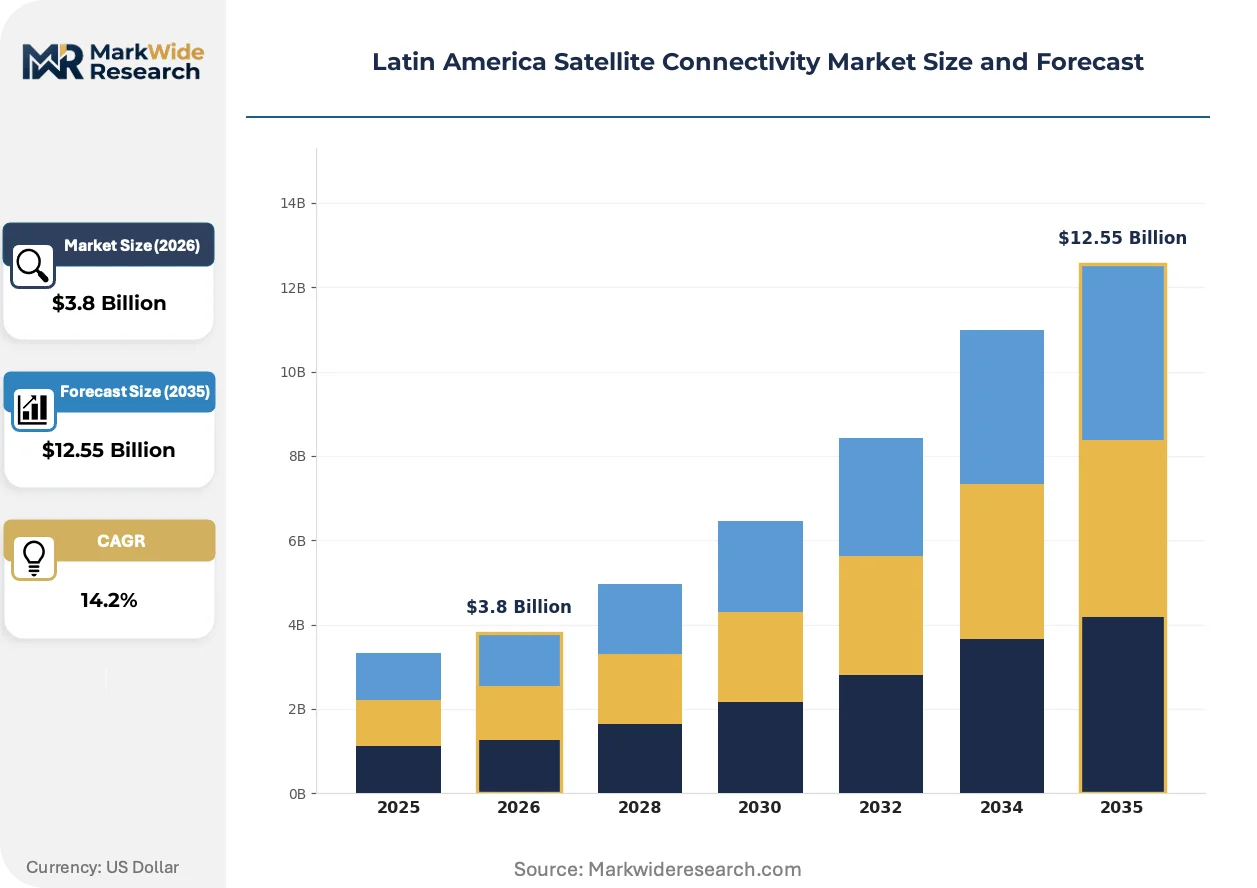
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VSAT, GEO Satellites, LEO Satellites, MEO Satellites Application: Emergency Services, Maritime Communication, Remote Sensing, Internet Access End User: Government, Telecommunications, Oil & Gas, Aviation Technology: Ku-band, Ka-band, C-band, Optical Communication |
| Companies Covered | SES, Intelsat, Viasat, Starlink, Hispasat, Telesat, Hughes, Entel, Eutelsat, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Satellite Connectivity Market Evolving Landscape
Orbital diversification and ground-segment virtualization are collapsing traditional service boundaries. Operators now compete on orchestration capabilities rather than spectrum ownership alone.
Software-defined satellite payloads are integrating digital beam-forming and frequency-agile transponders across new GEO orders. Brazilian and Mexican enterprise customers adopt these flexible capacity leases to match variable bandwidth demand across agricultural harvest cycles and oil platform maintenance windows. This capability is integrating spot-beam reconfiguration as a standard procurement specification, compressing contract durations from annual to quarterly terms.
ANATEL's updated satellite licensing framework mandates gateway cybersecurity audits and supply chain disclosure for critical infrastructure designation. Industrial consequence includes mandatory encryption standards for government and energy sector contracts. Brazilian state-owned oil operator procurement divisions now require ISO 27001-certified ground segment operations as a baseline qualification.
Managed service unbundling is fragmenting traditional end-to-end contracts. Enterprise buyers in Chile's mining sector and Colombia's logistics corridors now separately procure terminal hardware, bandwidth, and network management. This pattern is most visible in Antofagasta's copper belt, where mining consortia direct-lease transponder capacity while self-managing CPE deployments through in-house telecommunications teams.
Latin America Satellite Connectivity Market Segmentation
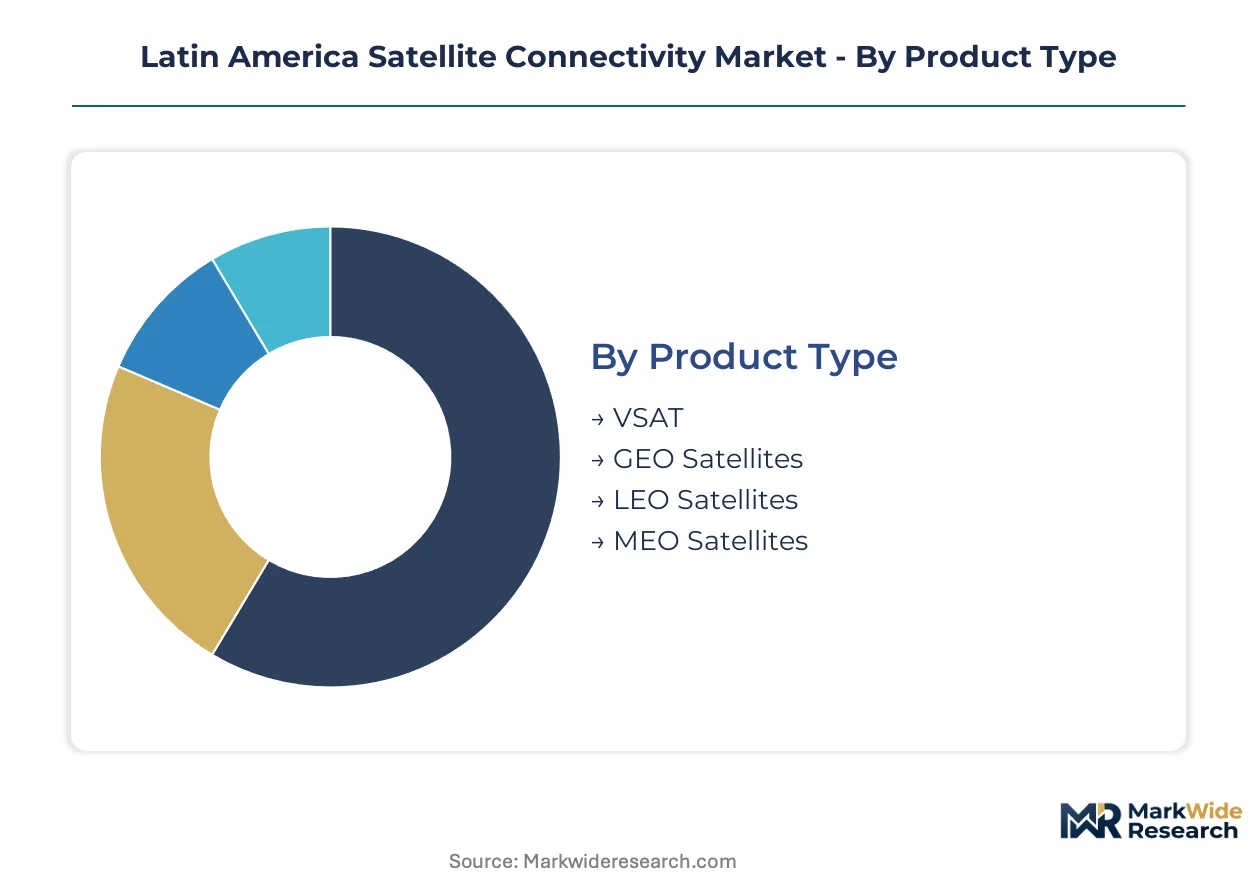
Segmentation in Latin America satellite connectivity reveals how procurement patterns split between legacy infrastructure and emerging constellation architectures. Buyers arbitrage orbital regimes based on latency tolerance, coverage persistence, and terrestrial backhaul economics across Brazil's pre-salt platforms and Peru's Amazon communities.
Product Type:
Customization intensity spans from standardized VSAT terminals to bespoke orbital configurations, with procurement teams weighing capex flexibility against managed service simplicity.
- VSAT:Two-way satellite ground stations using compact antennas under 2.4 meters, typically Ku-band or Ka-band, with integrated modems for enterprise networks. Demand concentrates in Colombia's logistics corridors and Chile's mining belts where self-managed CPE deployments reduce recurring service costs.
- LEO Satellites:Compact low-earth-orbit platforms operating below 2,000 kilometers altitude, delivering sub-50ms latency through dense constellation shells. Brazil's Roraima state and offshore drilling operators in the Santos Basin drive procurement as fiber economics fail in these zones.
- GEO Satellites:Geostationary platforms at 35,786 kilometers providing persistent coverage via fixed orbital slots, favored for broadcast and broadband to dispersed populations.
- MEO Satellites:Medium-earth-orbit systems bridging latency and coverage gaps, positioned for maritime trunking and government backhaul across the Southern Cone.
Leading the category by volume: VSAT terminals across enterprise and government deployments. Growing fastest: LEO Satellites as constellation operators expand gateway infrastructure in São Paulo and Mexico City.
Application:
Margin structure differentiates this category, with specialized verticals commanding premium pricing against commoditized consumer access.
- Internet Access:Consumer and enterprise broadband delivery to regions beyond fiber economics, spanning C-band rural coverage through Ka-band high-throughput beams. Brazil's Amazon basin communities and Peru's Loreto Department represent concentrated demand where cellular backhaul remains uneconomical.
- Maritime Communication:Stabilized terminal systems for vessel tracking, crew welfare, and operational telemetry across fishing fleets and offshore energy. Argentine and Uruguayan fishing operators plus Chilean salmon aquaculture drive terminal procurement through dedicated MSS agreements.
- Emergency Services:Resilient communication infrastructure for disaster response and humanitarian operations, requiring rapid-deploy VSAT and interoperable spectrum.
- Remote Sensing:Earth observation data acquisition for agriculture, forestry, and environmental monitoring, with downstream analytics integration.
Internet Access dominates absolute volume through subscriber scale. Maritime Communication generates the steepest expansion trajectory as fishing and energy fleets digitize operations.
End User:
Procurement sophistication varies sharply across this dimension, from rigid government tender processes to agile enterprise direct leasing.
- Oil & Gas:Exploration, production, and midstream operations requiring redundant high-throughput links for real-time drilling telemetry, platform automation, and crew connectivity. Brazil's Petrobras pre-salt developments in the Santos Basin mandate ISO 27001-certified ground segment operations under ANATEL's critical infrastructure framework.
- Government:Defense, civil administration, and emergency response networks with mandated encryption standards and supply chain disclosure requirements. Mexico's federal procurement increasingly specifies gateway cybersecurity audits under IFT licensing reforms.
- Telecommunications:Mobile backhaul, trunking, and service extension for carriers filling coverage gaps in remote territories.
- Aviation:In-flight connectivity and air traffic management for commercial and general aviation across transcontinental routes.
Oil & Gas leads capital deployment per site. Government represents the fastest-climbing segment as regulatory mandates expand secure satellite procurement.
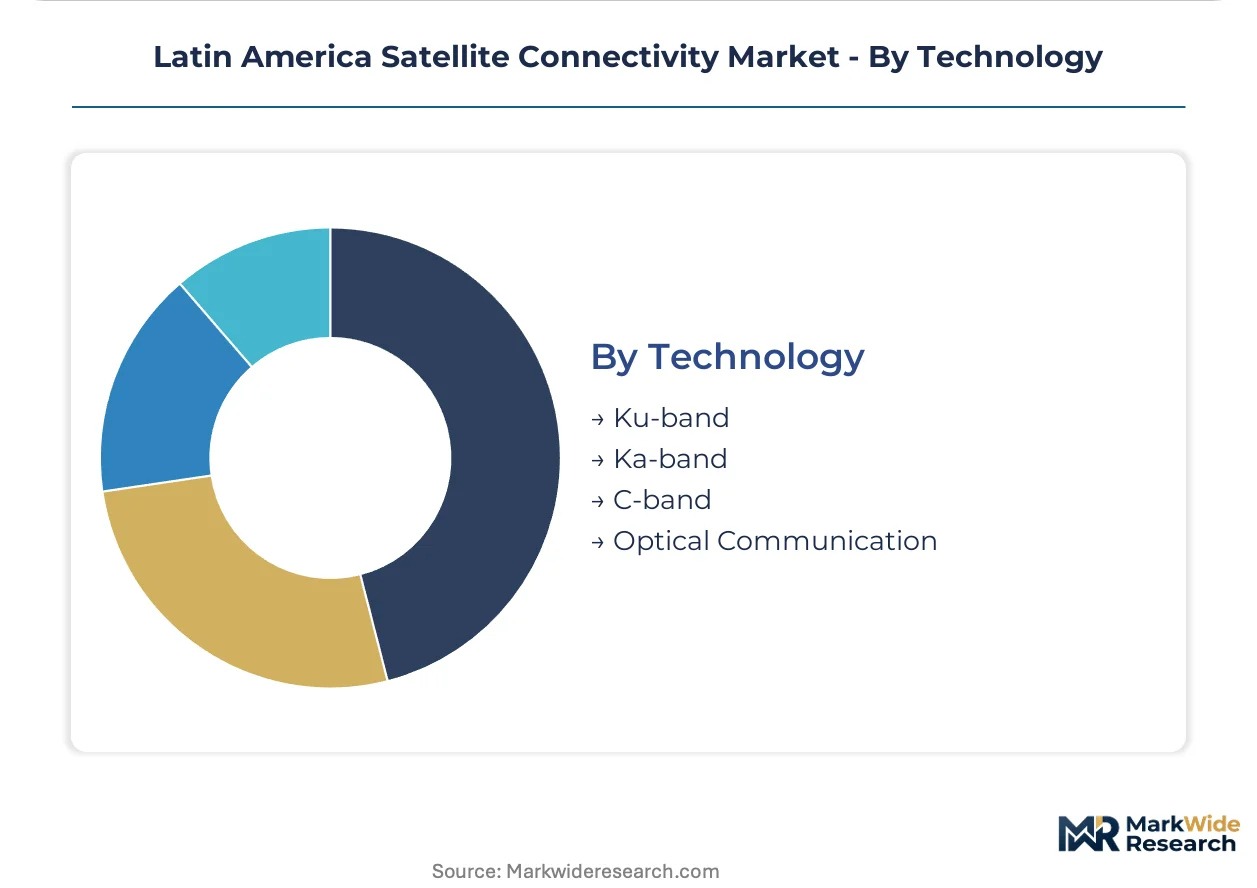
Technology:
Spectrum economics and interference tolerance shape technology selection, with higher frequencies trading rain fade vulnerability for throughput density.
- Ka-band:High-frequency spectrum above 26.5 GHz enabling spot-beam architectures with concentrated power and frequency reuse. SES anchors regional coverage through extensive Ku-band and Ka-band deployments over the Andean ridge, serving enterprise clients with flexible managed-service contracts.
- Ku-band:Established spectrum between 12-18 GHz balancing rain resilience and antenna compactness, dominant in broadcast and enterprise VSAT.
- C-band:Lower frequencies below 8 GHz prized for tropical rain-zone reliability and broad geographic coverage, though spectrum pressure from terrestrial 5G intensifies.
- Optical Communication:Laser-based inter-satellite and ground links offering terabit-scale capacity without radiofrequency licensing constraints, emerging for constellation backhaul.
Ku-band retains the largest installed base across Latin America. Ka-band gains share fastest as high-throughput satellites and LEO constellations deploy spot-beam density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates satellite connectivity demand through its pre-salt offshore platforms and Amazon basin communities where terrestrial infrastructure fails. Mexico and Argentina follow with regulatory reforms and mining sector procurement. Chile and Colombia round out the regional landscape with maritime and logistics applications.
Brazil
Petrobras pre-salt developments in the Santos Basin drive redundant high-throughput link procurement for real-time drilling telemetry. ANATEL mandates gateway cybersecurity audits and ISO 27001-certified ground segment operations for critical infrastructure designation. São Paulo hosts concentrated gateway infrastructure serving as the terrestrial fiber backhaul hub for regional networks.
Mexico
IFT licensing reforms compress market entry timelines for constellation operators seeking gateway deployment rights across federal procurement. The streamlined non-geostationary orbit authorization rules accelerate spectrum allocation for emerging LEO services. Mexico City clusters terrestrial fiber backhaul for satellite ground stations, creating single-point vulnerabilities that operators address through redundant routing.
Argentina
Fishing fleets and agricultural operations in the Pampas region deploy vessel tracking and precision farming systems via dedicated MSS terminals. ENACOM mandates end-of-life deorbiting plans and collision avoidance system documentation, extending licensing review cycles for constellation operators. Buenos Aires anchors enterprise procurement for managed satellite services across the Southern Cone.
Chile
Salmon aquaculture operations and copper mining consortia in the Antofagasta belt drive terminal procurement through self-managed CPE deployments. Mining enterprises direct-lease transponder capacity while separating hardware, bandwidth, and network management contracts. Santiago serves as the procurement coordination center for logistics corridors spanning the Andean ridge.
Colombia
Logistics corridors and remote Andean communities generate VSAT demand where expanding 4G coverage erodes semi-urban satellite broadband addressable markets. Regulatory harmonization disputes across Mercosur member states delay unified equipment certification. Bogotá concentrates enterprise procurement for hybrid connectivity solutions blending terrestrial and satellite infrastructure.
Latin America Satellite Connectivity Market Competitive Landscape
Capacity expansion dominates the current landscape as constellation operators deploy gateway infrastructure in São Paulo and Mexico City while legacy GEO fleets refresh orbital assets. The market structure spans three tiers: established fleet operators with extensive Ku-band coverage, emerging LEO constellation providers with low-latency shells, and regional specialists serving national enterprise accounts. Strategic archetypes include spectrum-anchored incumbents defending broadcast and broadband positions, latency-focused disruptors targeting real-time applications, and vertically integrated energy sector contractors. Portfolio diversification and geographic gateway expansion constitute the dominant competitive moves across all tiers.
Within the established fleet tier, SES and Intelsat exemplify spectrum-anchored positioning through extensive Ku-band deployments over the Andean ridge and flexible managed-service contracts tailored to enterprise clients. Among emerging constellation operators, Starlink occupies a position representing low-latency disruption, reaching remote mining camps and rural clinics beyond fiber economics through dense LEO shell deployment. These three companies collectively represent the competitive tension between persistent GEO coverage and real-time LEO responsiveness reshaping procurement patterns across Brazilian offshore platforms and Amazon communities.
| Leading Market Players |
|---|
| SES |
| Intelsat |
| Viasat |
| Starlink |
| Hispasat |
| Telesat |
| Hughes |
| Entel |
| Eutelsat |
| Others |
Value Network & Pricing Analysis
Ka-band RF engineering specialists concentrated in São Paulo and Mexico City create labor-cost differentials that widen pricing-tier spreads between managed service bundles and self-managed CPE deployments. ANATEL's cybersecurity audit requirements for critical infrastructure designation add compliance premiums to Petrobras contracts while unbundled procurement in Chile's mining belt compresses margins for pure bandwidth resellers.
Pricing Analysis
Warranty and service-bundling unbundling distinguishes contract structures across the region. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified managed services from self-managed VSAT terminals and basic bandwidth leases. Price differentiation hinges on after-sales support intensity and gateway redundancy guarantees. Cost compression in standard-tier enterprise contracts is intensifying because mining consortia now direct-lease transponder capacity. Government and oil sector buyers show lowest price sensitivity due to mandated security specifications.
Supply Chain Analysis
Gateway hardware supply rests on US, European, and Chinese specialty component producers for solid-state power amplifiers and digital beam-forming chipsets. Raw material dependencies span gallium nitride substrates, precision waveguide assemblies, and radiation-hardened processors. Single-source vulnerability concentrates in Ka-band MMIC fabrication. Distribution runs through São Paulo-based system integrators serving Brazilian offshore platforms and Mexico City distributors covering federal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around gateway infrastructure ownership as ANATEL's cybersecurity mandates and IFT's streamlined licensing together squeeze capital-constrained regional resellers.
For Market Incumbents: Anticipate LEO constellation encroachment by hardening Ku-band managed service contracts with flexible quarterly terms and embedded cybersecurity certification. SES and Intelsat should deepen backward integration into São Paulo gateway operations to control fiber backhaul costs. Defensive consolidation through spectrum portfolio swaps with regional specialists preserves Andean ridge coverage advantages.
For New Entrants and Emerging Players: Enter via the Amazon basin connectivity gap in Roraima and Acre states where fiber economics fail and cellular backhaul remains uneconomical. Peru's Loreto Department presents parallel white-space opportunity for low-latency services beyond existing GEO reach. Go-to-market positioning as precision agriculture telemetry specialists bypasses direct competition with entrenched broadband providers.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated gateway operators with proven ANATEL compliance records. Long-term viability hinges on spectrum position durability and ground segment asset ownership. Acquisition target archetype: regional VSAT specialists holding Petrobras framework agreements. Watch ENACOM's debris mitigation enforcement as inflection indicator for constellation operator licensing costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Gateway Infrastructure Expansion | São Paulo and Mexico City fiber backhaul hubs reduce single-point vulnerabilities for regional networks. |
| LEO-GEO Hybrid Service Architecture | Converged offerings blend Starlink latency with SES persistent coverage for tiered enterprise procurement. |
| Cybersecurity Certification Investment | ISO 27001 ground segment operations qualify vendors for Petrobras critical infrastructure contracts. |
| Spectrum Portfolio Optimization | Ka-band spot-beam density investments match variable bandwidth demand across agricultural harvest cycles. |
| Maritime MSS Terminal Deployment | Argentine fishing fleets and Chilean salmon aquaculture drive dedicated bandwidth agreement growth. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with satellite network operations center directors, ANATEL licensing officials, Petrobras telecommunications procurement managers, and precision agriculture systems integrators validated demand assumptions. Secondary sources included ANATEL spectrum allocation databases, IFT administrative resolutions, ENACOM orbital slot registries, and ITU satellite network filings. Bottom-up terminal deployment counts and top-down capacity lease valuations were triangulated against gateway infrastructure investment disclosures.
Data-stream reconciliation across orbital regime, application vertical, and end-user sophistication dimensions shaped the analytical framework. Segmentation modeling spanned product type, application, end user, and technology band throughout the forecast period. CAGRs were derived from capacity expansion timelines and pricing trajectory assumptions. Industry-specific inputs included gateway deployment schedules, regulatory licensing velocity, and offshore platform drilling activity correlations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under spectrum harmonization disputes across Mercosur member states or accelerated terrestrial 5G substitution in Colombian Andean corridors. Forecasts reflect documented assumptions about constellation deployment cadence and regulatory enforcement intensity. A small set of named triggers—ANATEL critical infrastructure designation expansion, IFT gateway authorization velocity, ENACOM debris compliance stringency—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Japan Satellite Communication Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
Global Maritime Satellite Communication Market
Satellite
GEO Satellite Market
Satellite
LEO Satellite System Market
Satellite
High-Throughput Satellite Market
Satellite
Israel Satellite Imagery Services Market
Satellite
Satellite Payload Market
Satellite
Low-Cost Satellite Market
Satellite
US Remote Sensing Technology Market
Satellite
Satellite Transponder Market
Satellite
Israel Satellite Communications Market
Satellite
Satellite Data Analytics Services Market
Satellite
UAE Satellite Communication Market
Satellite
Saudi Arabia Satellite Imagery Services Market
Satellite
Russia Satellite Communications Market