
 Japan Satellite-Based Earth Observation Market | 2026-2036
Japan Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Satellite-Based Earth Observation Market Insights
Synthetic aperture radar miniaturization is narrowing the cost-performance gap between government-grade and commercial Earth observation platforms. Synspective leverages its StriX constellation to dominate all-weather surface deformation monitoring for infrastructure clients. iQPS sustains rapid revisit capabilities through its small SAR satellite fleet, competing aggressively on maritime surveillance contracts. JAXA anchors institutional demand through its ALOS program and technology transfer partnerships with domestic vendors.
Japan satellite-based Earth observation encompasses spacecraft systems and downstream services that collect, process, and distribute geospatial intelligence using orbital sensor platforms operating at altitudes from 400 to 700 kilometers, with spatial resolutions ranging from sub-meter to tens of meters depending on payload configuration. These systems serve defense mapping, environmental compliance, and commercial asset management by transforming raw electromagnetic measurements into actionable terrain and object information. Optical satellites occupy the mature revenue tier where pricing pressure from foreign providers compresses margins, while radar satellites capture the fastest expansion as all-weather, day-night imaging becomes non-negotiable for disaster response protocols. Data analytics represents the emerging margin pool where geospatial solutions transform raw imagery into subscription intelligence products for insurance and logistics buyers.
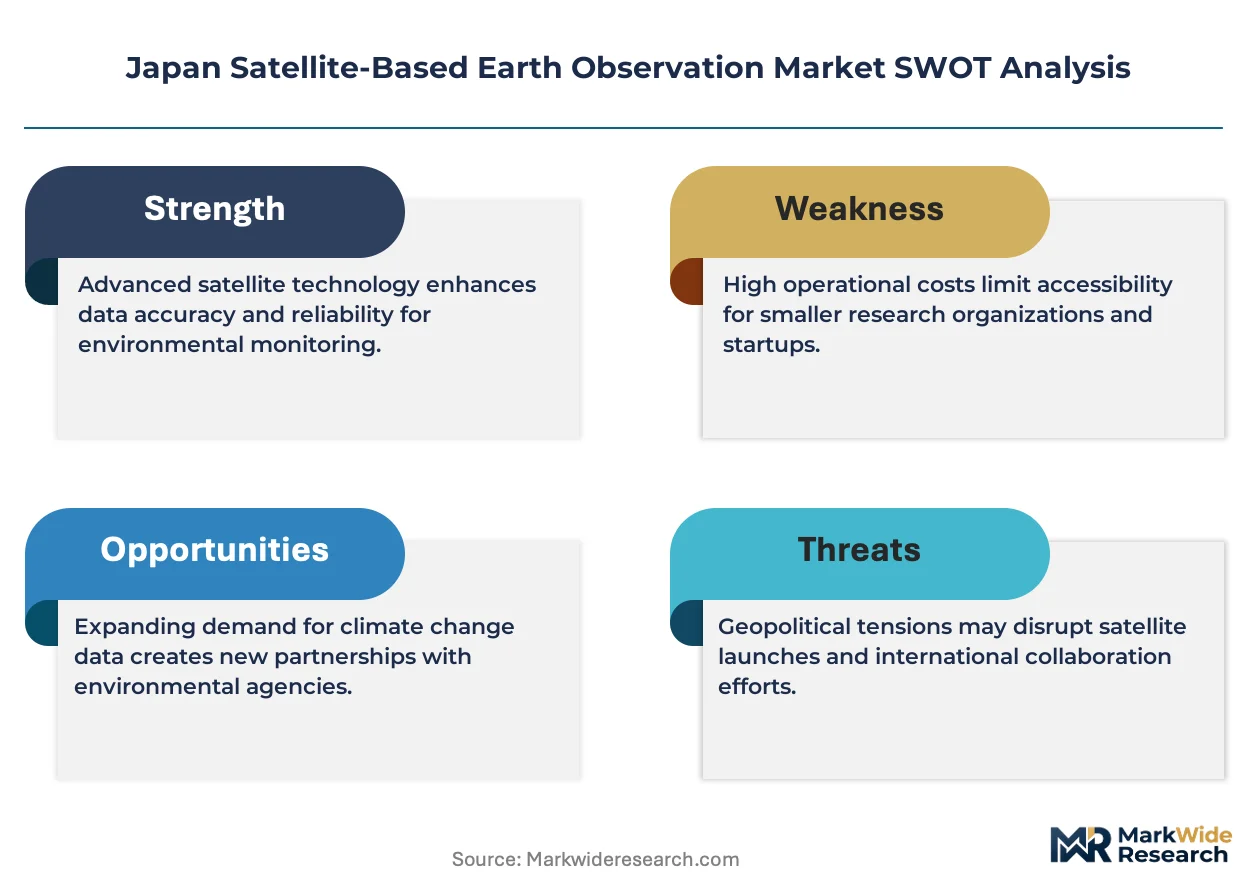
METI's Space Industry Vision 2030 and JAXA's technology licensing frameworks shape domestic market access by mandating local supply chain participation for government Earth observation contracts. JIS standards and PMDA-adjacent quality protocols extend into commercial satellite manufacturing, raising compliance costs for new entrants while protecting incumbent positions. Stakeholders must monitor how Japan's national security classification reforms affect foreign data provider participation in defense-adjacent segments.
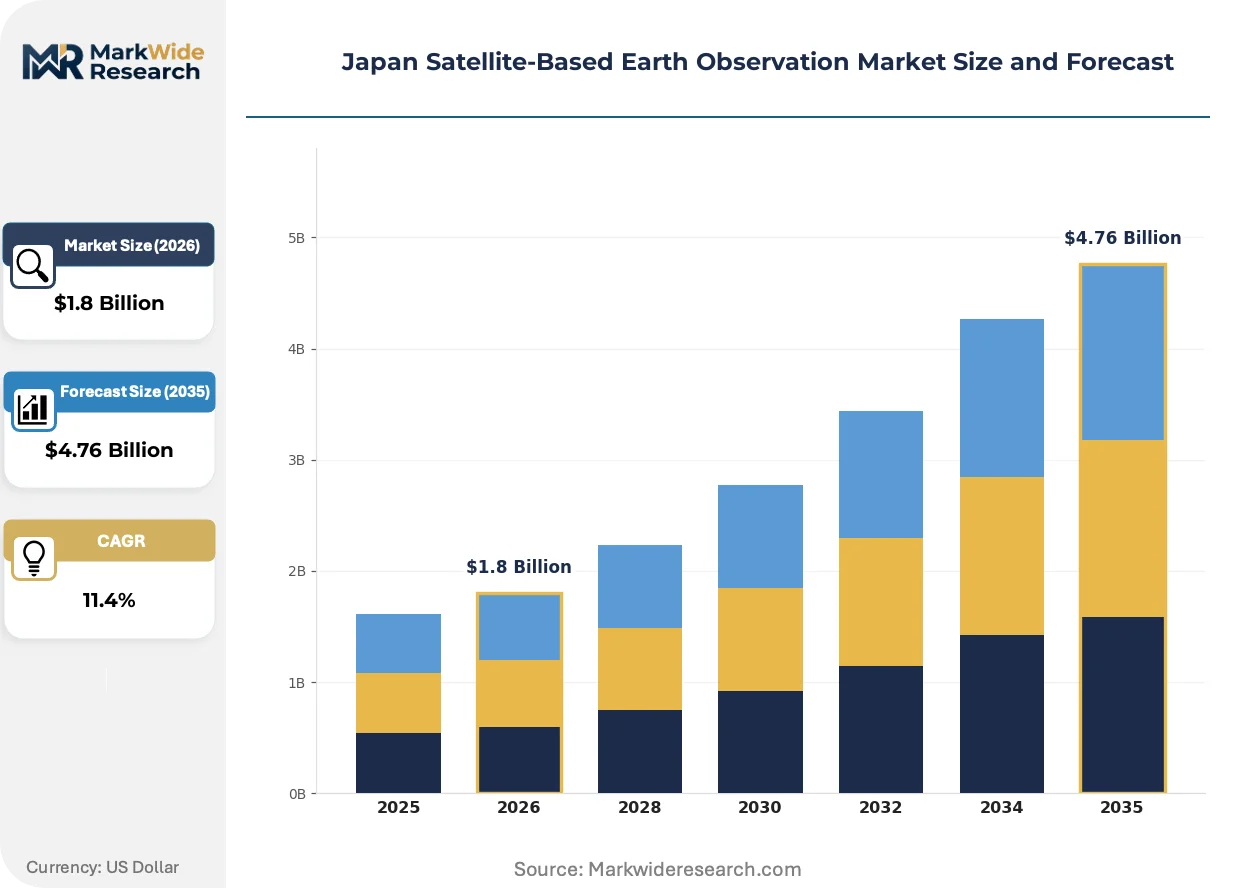
Market Dynamics
Synthetic aperture radar miniaturization is compressing unit economics for Japanese constellation operators while METI's local content mandates reshape procurement flows toward domestic supply chains.
Growth Catalysts
- METI Space Industry Vision 2030:Government procurement rules now require domestic manufacturing participation for Earth observation satellite contracts, channeling institutional demand toward Japanese vendors.
- Disaster response protocols:Japan's Cabinet Office mandates all-weather imaging capabilities for flood and landslide monitoring, accelerating SAR satellite deployment over optical alternatives.
- Precision agriculture clustering:Tokyo's satellite data analytics hub serves Hokkaido and Tohoku farming cooperatives with subscription-based crop health monitoring.
Market Restraints
- Launch cost volatility:Japanese operators depend on foreign launch providers for small satellite deployment, exposing margins to SpaceX and ISRO pricing swings.
- Optical satellite margin compression:European and American providers flood the commercial imagery market with sub-meter resolution products, eroding pricing power for domestic optical platforms.
- JIS certification timelines:Quality protocols for satellite manufacturing extend development cycles by 18-24 months versus unregulated foreign competitors.
Strategic Opportunities
- Kyushu spaceport infrastructure:Tanegashima and Uchinoura launch complexes offer domestic vertical integration potential for constellation operators seeking supply chain control.
- Insurance risk modeling:Property and casualty underwriters in Osaka and Tokyo seek subscription-based surface deformation data for earthquake and landslide premium calibration.
- Maritime surveillance mandates:Japan Coast Guard expansion of illegal fishing monitoring creates dedicated procurement channels for rapid-revisit SAR constellations.
Industry Challenges
- SAR signal processing talent scarcity:Domestic universities produce insufficient radar engineering specialists to staff constellation operators and analytics firms.
- Legacy system integration friction:Defense and disaster agencies operate decades-old ground station infrastructure incompatible with modern small satellite data protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Satellite-Based Earth Observation Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Satellites, Radar Satellites, Multi-Spectral Satellites, Hyperspectral Satellites Application: Agriculture Monitoring, Urban Planning, Disaster Management, Climate Research End User: Government Agencies, Environmental Organizations, Research Institutions, Private Sector Technology: Remote Sensing, Image Processing, Data Analytics, Geospatial Solutions |
| Companies Covered | Synspective, iQPS, Sky Perfect JSAT, AstroX, Space BD, NTT Data, Axelspace, JAXA, IHI, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Satellite-Based Earth Observation Market Trends and Innovations
Japanese Earth observation is pivoting from hardware sales toward analytics-as-a-service models, with constellation operators vertically integrating into downstream intelligence products.
Edge computing payloads aboard small SAR satellites are digitizing onboard image processing, eliminating ground station bottlenecks. Infrastructure monitoring clients in Kansai and Chubu regions receive automated change detection alerts within 90 minutes of data acquisition. This compression is digitizing the traditional value chain where raw imagery distributors once captured margin.
METI's 2023 revision of space industry procurement guidelines tightens local content thresholds for government Earth observation contracts. Domestic satellite manufacturers must now source 60% of subsystem value from Japanese suppliers to qualify for JAXA technology transfer support. Small SAR constellation builders are responding by qualifying local component vendors for power management and attitude control systems.
Subscription pricing is displacing per-image licensing across commercial Earth observation in Japan. Insurance and logistics buyers in Tokyo's Marunouchi district prefer fixed-fee access to continuous surface monitoring rather than transactional imagery purchases. This shift is most visible in precision agriculture, where Hokkaido dairy cooperatives pay annual fees for pasture condition intelligence rather than acquiring raw satellite data.
Japan Satellite-Based Earth Observation Market Segmentation
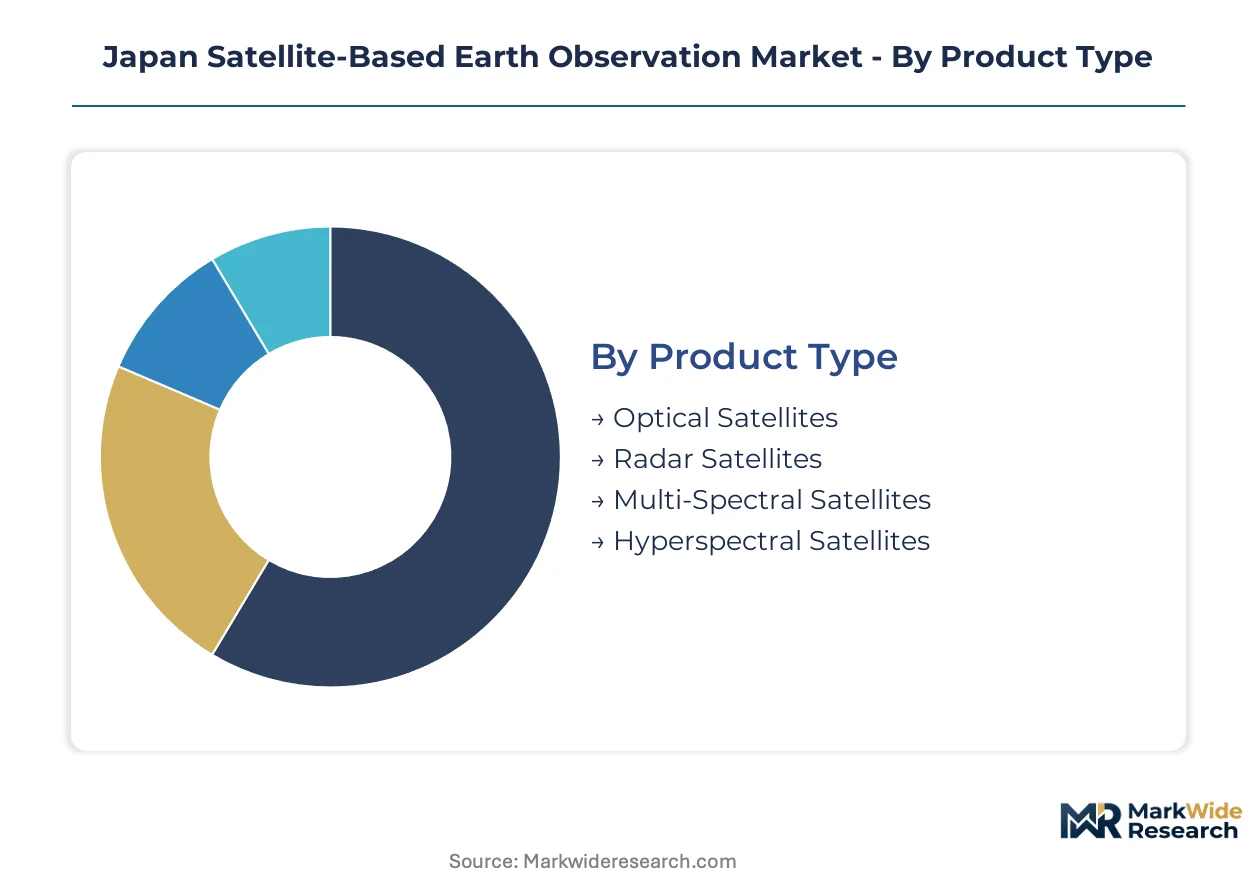
Segmentation reveals how Japanese Earth observation procurement splits across sensor technologies, institutional mandates, and downstream intelligence services. Each dimension carries distinct margin profiles and regulatory exposure that shape vendor positioning strategies.
Product Type:
Use-case spectrum spans weather-dependent optical platforms through all-weather radar systems to specialized spectral imagers for precision agriculture and mineral detection.
- Optical Satellites:These platforms capture visible and near-infrared imagery at sub-meter resolution for urban mapping and environmental compliance. Tokyo metropolitan planners and Chubu industrial corridor regulators dominate procurement, though foreign providers compress domestic pricing power through oversupply of commercial imagery.
- Radar Satellites:Synthetic aperture radar payloads penetrate cloud cover and darkness for continuous surface monitoring. Japan Coast Guard and Cabinet Office disaster agencies drive institutional demand, with METI local content mandates channeling contracts toward domestic constellation operators like Synspective and iQPS.
- Multi-Spectral Satellites:Narrow-band sensors across 5-10 spectral bands support crop health assessment and forest inventory. Hokkaido agricultural cooperatives represent the core commercial demand cluster for these mid-resolution platforms.
- Hyperspectral Satellites:Continuous spectral sampling across hundreds of bands enables mineral identification and pollution detection. JAXA research partnerships and select mining sector clients in Kyushu sustain limited deployment volumes.
The dominant share belongs to Radar Satellites, while Hyperspectral Satellites is closing the gap fastest through JAXA technology transfer acceleration.
Application:
Cost tier separation runs from subscription-based precision agriculture through capital-intensive urban infrastructure to emergency-response disaster protocols.
- Agriculture Monitoring:Subscription crop health intelligence transforms raw imagery into actionable yield optimization for Hokkaido and Tohoku farming cooperatives. Tokyo data analytics clusters package NDVI-derived pasture condition alerts for dairy operations.
- Urban Planning:High-resolution change detection supports Tokyo-Osaka megacity expansion and Chubu regional infrastructure corridors. Municipal procurement concentrates on optical and SAR fusion products for construction compliance verification.
- Disaster Management:All-weather imaging mandates from Japan's Cabinet Office prioritize SAR rapid-revisit capabilities for flood and landslide response. Prefectural emergency management agencies maintain dedicated procurement budgets independent of annual planning cycles.
- Climate Research:Long-term atmospheric and oceanic observation supports JAXA and university consortium studies. Institutional funding flows through competitive academic grants rather than operational procurement channels.
Disaster Management commands the highest unit pricing, with Agriculture Monitoring expanding most quickly through subscription model adoption.
End User:
Customer type fragmentation separates sovereign procurement with local content requirements from commercial buyers prioritizing cost and speed.
- Government Agencies:METI, JAXA, and Cabinet Office contracts mandate 60% domestic subsystem sourcing under Space Industry Vision 2030 guidelines. Defense-adjacent segments face additional security classification restrictions on foreign data provider participation.
- Environmental Organizations:Non-profit and NGO buyers seek cost-effective monitoring for conservation and climate accountability reporting. These users favor open data portals and shared subscription models over dedicated satellite capacity.
- Research Institutions:University consortiums and national laboratories access JAXA technology transfer programs for experimental payload development. Academic procurement emphasizes data archive access over real-time acquisition.
- Private Sector:Insurance underwriters in Osaka and logistics operators in Tokyo Marunouchi drive commercial analytics demand. These buyers prefer fixed-fee intelligence subscriptions over per-image licensing structures.
Government Agencies retain the largest committed budget share, while Private Sector is climbing the fastest through insurance risk modeling adoption.
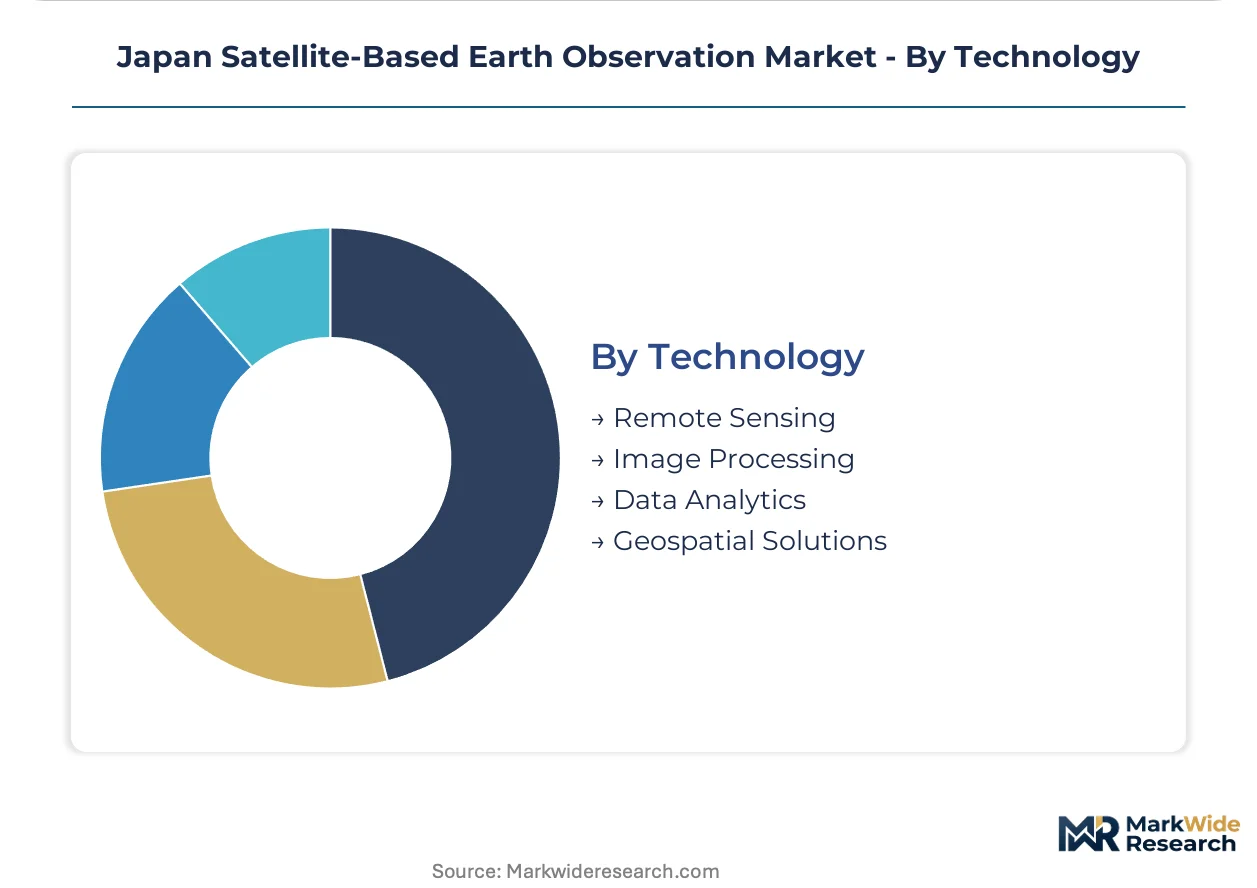
Technology:
Supply concentration tracks upstream hardware manufacturing through midstream data processing to downstream intelligence platform development.
- Remote Sensing:Orbital sensor platforms and ground station networks constitute the capital-intensive foundation layer. Domestic manufacturers in Kyushu and Tokyo satellite industrial clusters compete for METI-qualified subsystem contracts.
- Image Processing:Raw data calibration, orthorectification, and atmospheric correction transform sensor measurements into geospatial products. Edge computing payloads aboard small SAR satellites are digitizing this layer through onboard processing automation.
- Data Analytics:Machine learning-derived change detection and predictive surface modeling represent the emerging margin pool. Tokyo analytics startups and established geospatial firms compete for subscription intelligence contracts.
- Geospatial Solutions:Integrated platform delivery combining imagery, analytics, and decision support tools for specific industry verticals. Insurance and precision agriculture buyers in Kansai and Hokkaido drive demand for packaged solutions over component procurement.
Remote Sensing captures the largest capital deployment, with Data Analytics gaining share fastest through subscription pricing displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports synthetic aperture radar data services to Southeast Asian disaster management agencies and maritime surveillance operators. Domestic constellation operators leverage METI's local content mandates to secure regional procurement contracts. The analysis window tracks demand concentration across five sub-regional industrial clusters.
Kanto/Tokyo
Tokyo's Marunouchi financial district drives insurance risk modeling subscriptions for surface deformation monitoring. METI's Space Industry Vision 2030 channels government Earth observation contracts toward domestic vendors headquartered in this corridor. Satellite data analytics startups cluster in Shibuya and Otemachi, packaging crop health intelligence for Hokkaido agricultural cooperatives.
Kansai/Osaka
Osaka-based property and casualty underwriters procure earthquake and landslide premium calibration data from SAR constellation operators. The Osaka Bay industrial corridor maintains legacy ground station infrastructure requiring modernization to interface with small satellite protocols. Kobe's maritime logistics sector generates commercial demand for rapid-revisit vessel tracking services.
Chubu/Nagoya
Nagoya's automotive and aerospace manufacturing belt employs precision agriculture data for supply chain crop monitoring. JAXA's Tsukuba Space Center technology transfer partnerships extend into Chubu regional satellite component suppliers. Local manufacturers qualify for METI's 60% domestic subsystem sourcing thresholds through Nagoya industrial cluster participation.
Kyushu
Tanegashima and Uchinoura launch complexes anchor Japan's domestic vertical integration potential for constellation operators. Kyushu-based satellite manufacturers compete for power management and attitude control system contracts under JAXA technology licensing frameworks. The region's spaceport infrastructure reduces dependence on foreign launch providers for small SAR satellite deployment.
Hokkaido
Hokkaido dairy and farming cooperatives represent the core commercial demand cluster for subscription-based pasture condition intelligence. Tokyo analytics firms serve this geography through NDVI-derived crop health monitoring products. Prefectural emergency management agencies maintain dedicated procurement budgets for all-weather flood and landslide response imaging.
Japan Satellite-Based Earth Observation Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: domestic constellation operators with METI-qualified supply chains, legacy aerospace conglomerates with JAXA technology partnerships, and downstream analytics specialists converting raw imagery into subscription intelligence. Competitive positioning hardens through backward integration into launch infrastructure, captive supply of radar signal processing talent, and exclusive data distribution agreements with prefectural disaster agencies.
Within the domestic constellation tier, Synspective and iQPS exemplify the SAR-first positioning that METI procurement rules now favor. Sky Perfect JSAT occupies a position bridging satellite operations with downstream service delivery. JAXA represents the institutional anchor archetype, transferring technology to qualified vendors while maintaining its own ALOS program. These three entities collectively illustrate how local content mandates and security classification reforms are reshaping vendor selection criteria across government Earth observation contracts.
| Leading Market Players |
|---|
| Synspective |
| iQPS |
| Sky Perfect JSAT |
| AstroX |
| Space BD |
| NTT Data |
| Axelspace |
| JAXA |
| IHI |
| Others |
Pricing and Supply Chain Analysis
Kyushu-based launch infrastructure concentration and METI's 60% domestic subsystem mandates concentrate margin capture among Japanese constellation operators with qualified supply chains. Foreign launch provider dependence in the small satellite tier compresses pricing power for new entrants lacking Tanegashima access.
Pricing Analysis
Next-generation SAR miniaturization against legacy optical platforms and emerging hyperspectral alternatives creates a three-tier pricing structure across premium, standard, and economy levels. Subscription-based analytics services command premium positioning over per-image licensing, with volume scale and JIS certification grade driving price differentiation. Cost compression in the optical tier intensifies because European and American providers flood the commercial imagery market. Insurance underwriters in Tokyo Marunouchi exhibit least price sensitivity for surface deformation monitoring, while Hokkaido agricultural cooperatives remain most cost-conscious.
Supply Chain Analysis
Extended payment terms from JAXA technology transfer programs and supply-chain finance facilities anchor working capital for domestic satellite manufacturers. Component sourcing draws from Japan, South Korea, and the United States for power management systems, attitude control modules, and radar signal processors. Single-source vulnerability concentrates in foreign launch provider slots for small SAR deployment. Distribution runs through Tokyo data analytics clusters packaging raw imagery into subscription intelligence for downstream verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens across the analytics layer as subscription pricing displaces transactional licensing, creating niche entry points for specialized intelligence providers.
For Market Incumbents: Insulate market position through captive supply of radar signal processing talent and exclusive distribution agreements with prefectural disaster agencies. METI's tightening local content thresholds threaten foreign data provider participation in defense-adjacent segments. Backward integration into Kyushu launch infrastructure secures supply chain control against SpaceX pricing volatility. For New Entrants and Emerging Players: Establish a beachhead in insurance risk modeling for Osaka property and casualty underwriters seeking earthquake premium calibration data. Maritime surveillance mandates from Japan Coast Guard expansion offer the most penetrable procurement channel. Go-to-market through Tokyo Marunouchi financial district relationships accelerates subscription intelligence adoption. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across small SAR constellation operations as miniaturization compresses unit economics. Long-term viability favors vertically integrated operators combining orbital assets with downstream analytics platforms. Monitor JAXA technology transfer acceleration as the inflection signal for domestic vendor qualification rates.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Launch Infrastructure Investment | Tanegashima and Uchinoura access reduces foreign provider dependence for constellation operators. |
| Analytics Platform Integration | Vertical combination of SAR data with insurance underwriting workflows captures subscription margin pools. |
| JIS Certification Pathway | Quality protocol compliance qualifies vendors for METI's 60% domestic sourcing procurement mandates. |
| Maritime Surveillance Partnership | Japan Coast Guard contracts create dedicated revenue channels for rapid-revisit SAR constellations. |
| Radar Engineering Talent Acquisition | Domestic university pipeline scarcity makes signal processing specialists a defendable competitive moat. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with constellation operators, satellite data analytics executives, and prefectural disaster agency procurement officers; and secondary validation through JAXA technology transfer disclosures, METI procurement guidelines, and Cabinet Office disaster response protocols. Bottom-up triangulation across sensor platform deployment schedules and top-down reconciliation against institutional budget allocations anchored market sizing.
Forecast inputs considered technology adoption curves across optical, radar, and hyperspectral platforms, with segmentation by application tier and end-user procurement authority. CAGRs derived from installed base expansion rates and pricing trajectory analysis across the projection horizon. Edge computing payload penetration and subscription model displacement served as satellite-specific forecast variables.
Sensitivities concentrate around foreign launch provider pricing volatility and METI local content threshold revisions. Forecasts reflect assumptions on JAXA technology transfer acceleration and Cabinet Office all-weather imaging mandate enforcement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Argentina Satellite Imagery Services Market
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
Healthcare Satellite Connectivity Market
Satellite
Global Satellite Propulsion System Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
Vehicle Mounted Satellite Communication Station Market
Satellite
Satellite Communications Service Market
Satellite
Asia-Pacific Remote Sensing Satellites Market
Satellite
North America Satellite Bus Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
Global Remote Sensing Services Market
Satellite
Satellite Sensor Market
Satellite
Global Dish Antennas Market
Satellite
Canada Satellite Connectivity Market
Satellite
EMEA Satellite Antenna Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market