
 Low Altitude Radar Market | 2026-2036
Low Altitude Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Low Altitude Radar Market Insights
Modular sensor packaging is realigning procurement patterns across defense and civil aviation buyers. Raytheon Technologies Corporation leverages its integrated command-and-control architectures to sustain long-term service contracts with US military end users. Thales Group competes through specialized naval and coastal surveillance configurations that anchor its position in European maritime safety applications.
Low altitude radar encompasses ground-based and airborne detection systems operating typically below 3,000 meters altitude, utilizing X-band, Ku-band, or L-band frequencies with pulse repetition frequencies optimized for clutter suppression in complex terrain. These systems serve primarily to detect, track, and classify small, slow, and low-flying objects including unmanned aerial vehicles, helicopters, and terrain-following aircraft in environments where conventional air surveillance radar suffers multipath interference and ground clutter degradation. Pulse Doppler Radar dominates current procurement volumes due to its proven moving target indication capability in adverse weather, while Active Electronically Scanned Array technology captures expanding investment as beam agility enables simultaneous multi-target tracking for counter-UAS missions. Civil Aviation Authorities represent a maturing end-user segment with predictable replacement cycles, whereas Homeland Security Agencies constitute the fastest-growing demand pool as border agencies deploy networked radar grids for asymmetric threat detection.
The FAA enforces Part 89 Remote ID requirements that mandate broadcast capabilities for most unmanned aircraft, directly expanding the addressable market for cooperative and non-cooperative detection infrastructure. EASA's U-space regulatory framework across EU member states establishes comparable low-altitude surveillance obligations that shape product certification pathways for radar manufacturers seeking European market access. Stakeholders must monitor evolving frequency allocation decisions by national regulators and prioritize software-defined architectures that adapt to shifting classification protocols without hardware replacement.
Market Dynamics
The FAA's Remote ID mandate is compressing procurement timelines for counter-UAS radar infrastructure, forcing defense contractors and civil aviation authorities to synchronize sensor deployments with regulatory deadlines rather than traditional budget cycles.
Growth Catalysts
- Part 89 Remote ID Mandate:The FAA's broadcast requirement for unmanned aircraft expands the installed base of cooperative detection nodes across US controlled airspace.
- Drone Detection:NATO border surveillance agencies are procuring networked radar suites to address asymmetric aerial threats at European frontier installations.
- Active Electronically Scanned Array:Beam agility enabling simultaneous multi-target tracking is accelerating replacement of mechanically scanned systems in military counter-UAS programs.
Market Restraints
- Gallium Nitride Supply Concentration:Foundry capacity for high-frequency power amplifiers concentrates in East Asian semiconductor manufacturing clusters, creating single-source vulnerability for AESA transmit-receive module production.
- Spectrum Allocation Friction:National regulators in densely populated regions are restricting X-band and Ku-band assignments for radar operations, compressing available bandwidth for clutter suppression algorithms.
- Optical-IR Substitution:Electro-optical and infrared sensors for short-range drone detection are capturing procurement share in urban environments where radar multipath interference degrades performance.
Strategic Opportunities
- Indian Border Infrastructure:The country's frontier surveillance modernization program under the Ministry of Home Affairs is creating demand for mobile low-altitude radar platforms in Himalayan terrain.
- Software-Defined Architectures:Firmware-upgradable signal processing enables radar operators to adapt classification protocols without hardware replacement as U-space frameworks evolve.
- Urban Air Mobility Corridors:EASA's U-space regulatory framework mandates cooperative surveillance infrastructure for crewed and uncrewed traffic integration above European metropolitan areas.
Industry Challenges
- RF Engineer Scarcity:The specialized workforce for phased array calibration and digital beamforming algorithm development is concentrated among defense contractors with limited talent mobility.
- Legacy System Integration:Military installations with decades-old command-and-control architectures face protocol incompatibility when grafting modern counter-UAS radar feeds into existing air defense networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Altitude Radar Market |
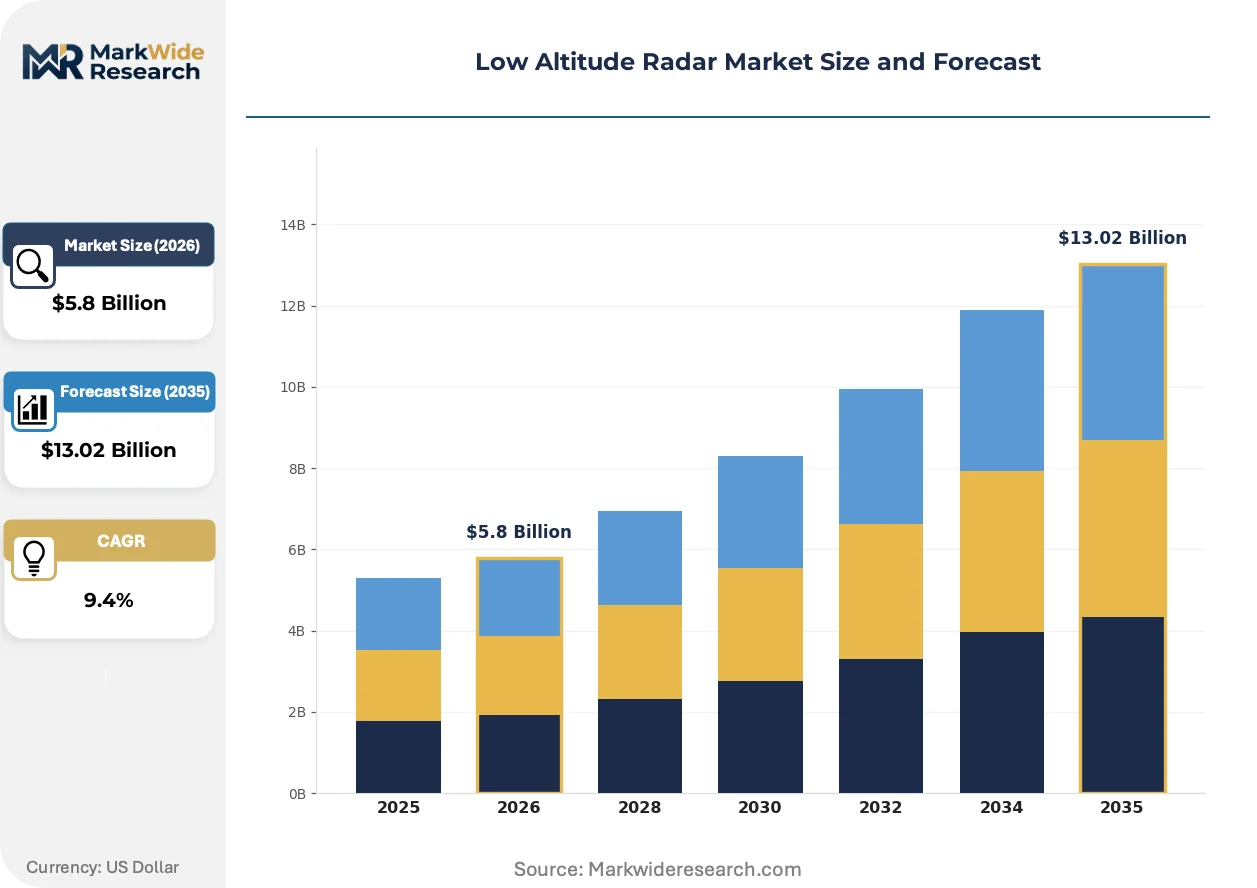
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulse Doppler Radar, Continuous Wave Radar, Phased Array Radar, Synthetic Aperture Radar Technology: Active Electronically Scanned Array, Passive Electronically Scanned Array, Frequency Modulated Continuous Wave, Ultra Wideband Application: Air Traffic Control, Border Surveillance, Weather Monitoring, Maritime Safety End User: Defense Forces, Homeland Security Agencies, Civil Aviation Authorities, Research Institutes |
| Companies Covered | Raytheon Technologies Corporation, Lockheed Martin Corporation, Northrop Grumman Corporation, Thales Group, Leonardo S.p.A., BAE Systems plc, Saab AB, Hensoldt AG, L3Harris Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Altitude Radar Market Trends and Innovations
Signal processing architectures are migrating from hardware-defined to software-configurable platforms, enabling radar operators to reconfigure detection parameters through firmware updates rather than physical component swaps.
Gallium Nitride power amplifiers are overtaking Gallium Arsenide in AESA transmit-receive modules due to higher power density and thermal efficiency. Military procurement offices in the United States and United Kingdom are specifying GaN-based radar suites for next-generation counter-UAS programs. This semiconductor transition is compressing maintenance intervals and extending operational availability in forward-deployed installations.
REACH restrictions on hazardous substances in electronics manufacturing are compelling radar OEMs to reformulate printed circuit board substrates and solder compositions. The European Chemicals Agency's substance of very high concern listings are affecting supply chains for legacy radar components with lead-based finishes. Manufacturers seeking CE marking compliance are accelerating qualification of halogen-free laminates and tin-silver-copper solder alloys for coastal surveillance applications.
Performance-based service contracts are displacing traditional capital purchase models for civil aviation radar installations. Airport authorities in Germany and France are procuring guaranteed availability agreements where OEMs retain ownership of radar assets and charge per aircraft detection event. This arrangement transfers obsolescence risk to manufacturers while binding operators to multi-year maintenance commitments with limited vendor switching flexibility.
Low Altitude Radar Market Segmentation
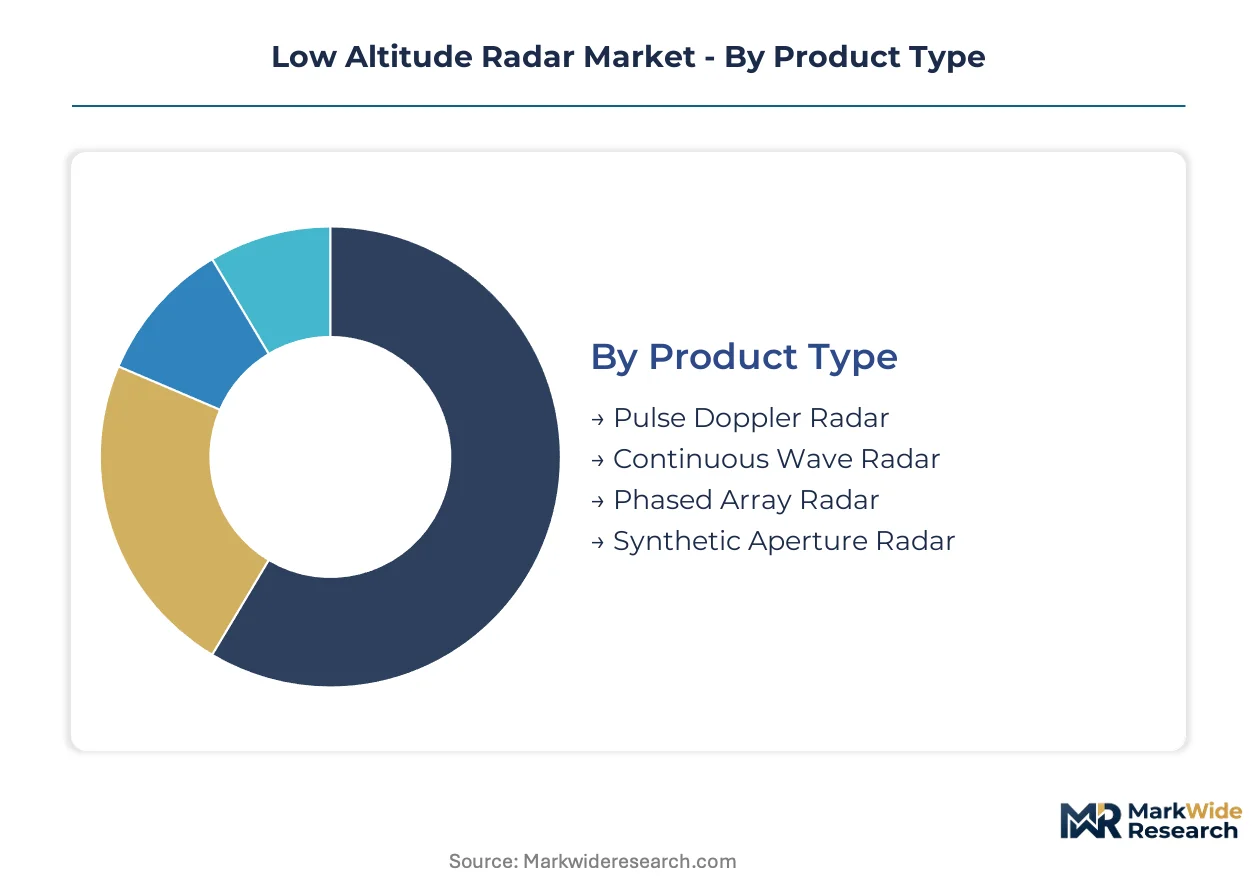
Low altitude radar procurement diverges sharply across buyer types, with defense programs prioritizing threat classification accuracy while civil aviation authorities optimize for lifecycle cost. Technology selection determines integration complexity and determines whether systems can adapt to evolving drone detection protocols without hardware replacement.
Product Type:
Defense procurement offices evaluate detection range against clutter suppression capability when specifying radar architecture for counter-UAS installations.
- Pulse Doppler Radar:Moving target indication through Doppler shift measurement enables reliable detection of small UAVs in adverse weather conditions. NATO border agencies in Poland and Romania specify these systems for frontier surveillance installations facing asymmetric aerial threats.
- Phased Array Radar:Electronic beam steering eliminates mechanical scan latency and supports simultaneous multi-target tracking for dense drone swarms. AESA configurations are displacing mechanically scanned systems in US military counter-UAS programs at domestic installations.
- Continuous Wave Radar:Uninterrupted transmission enables precise velocity measurement for helicopter identification in complex terrain.
- Synthetic Aperture Radar:High-resolution imaging supports terrain mapping applications beyond pure target detection.
Pulse Doppler Radar leads on scale; Phased Array Radar leads on momentum.
Technology:
Semiconductor substrate selection constrains thermal performance and determines maintenance intervals for forward-deployed installations.
- Active Electronically Scanned Array:Solid-state transmit-receive modules with GaN power amplifiers deliver higher power density than GaAs predecessors. The FAA's Remote ID mandate is accelerating AESA procurement for cooperative and non-cooperative detection infrastructure across US controlled airspace.
- Frequency Modulated Continuous Wave:Continuous transmission with linear frequency modulation enables low-probability-of-intercept operation for covert surveillance. German and French airport authorities specify FMCW architectures for urban drone detection where spectrum congestion limits pulsed system deployment.
- Passive Electronically Scanned Array:Reduced component count lowers acquisition cost for budget-constrained homeland security programs.
- Ultra Wideband:Fine range resolution supports classification of micro-drones through signature analysis.
AESA technology dominates defense procurement volumes; FMCW is expanding most quickly in civil aviation applications.
Application:
Operational environment dictates frequency band selection and determines susceptibility to multipath interference from urban structures.
- Border Surveillance:Networked radar grids with overlapping coverage zones enable tracking of low-flying aircraft across extended frontiers. India's Ministry of Home Affairs is procuring mobile platforms for Himalayan terrain where altitude and weather extremes degrade conventional surveillance performance.
- Air Traffic Control:Integration with existing surveillance infrastructure requires protocol compatibility with legacy command-and-control architectures. EASA's U-space framework is mandating cooperative surveillance infrastructure for crewed and uncrewed traffic integration above European metropolitan areas.
- Weather Monitoring:Doppler capability supports precipitation measurement and wind shear detection for aviation safety.
- Maritime Safety:Coastal installations require corrosion-resistant packaging and clutter suppression algorithms optimized for sea surface reflection.
Border Surveillance commands the largest program budgets; Air Traffic Control is climbing the fastest as U-space deadlines approach.
End User:
Funding mechanism and procurement timeline vary substantially across institutional buyer categories.
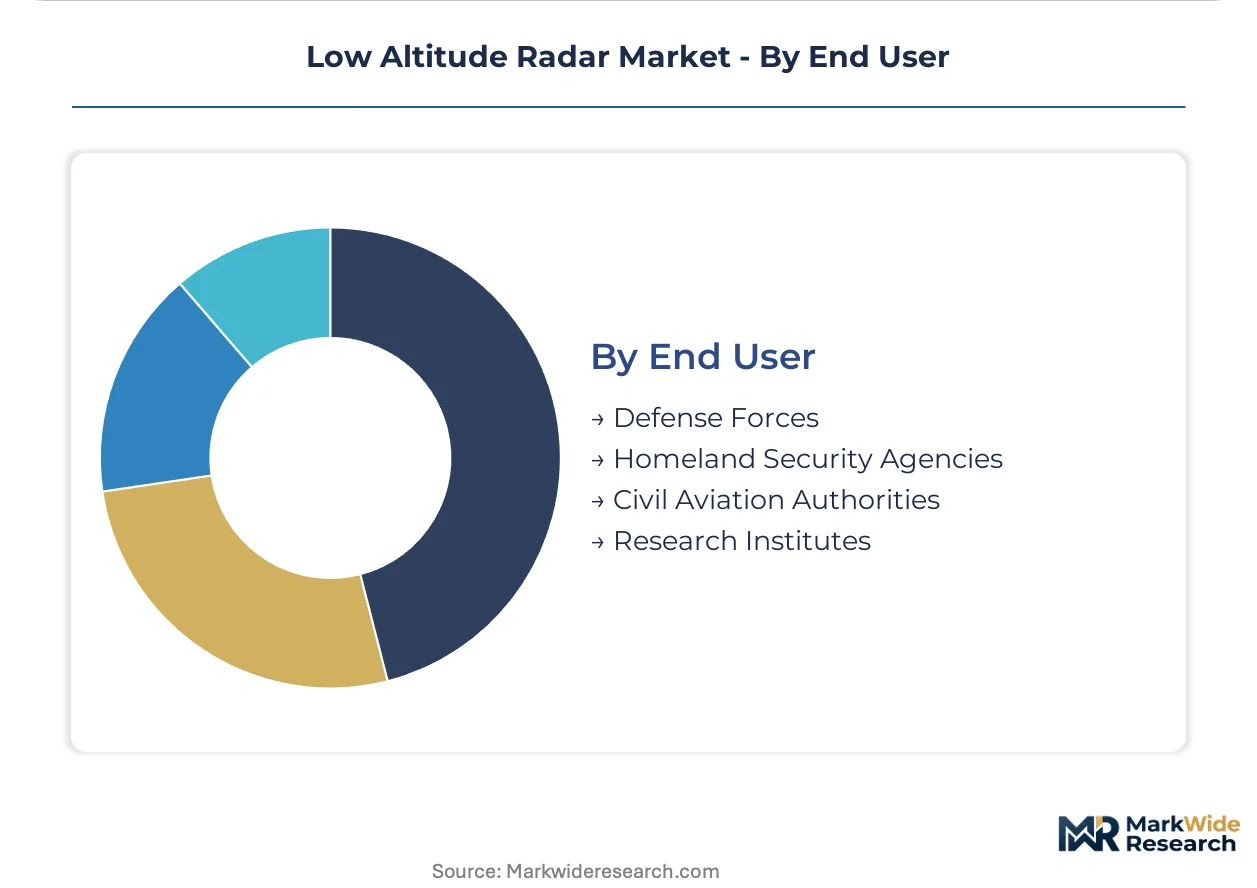
- Homeland Security Agencies:Asymmetric threat detection mandates drive networked sensor deployment at critical infrastructure and frontier installations. US Customs and Border Protection is expanding radar procurement for drone detection along the southwest border corridor.
- Civil Aviation Authorities:Predictable replacement cycles and performance-based service contracts are displacing capital purchase models at German and French airport authorities.
- Defense Forces:Classified threat libraries and kill-chain integration requirements constrain vendor selection to cleared contractors.
- Research Institutes:Experimental platforms support algorithm development for emerging classification protocols.
Defense Forces anchor procurement volumes; Homeland Security Agencies are gaining share fastest as border threats diversify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Low altitude radar technology first achieved operational scale through US military investment in ground-based air defense during the Cold War, establishing design paradigms that persist in modern counter-UAS architectures. European maritime surveillance programs and Asian border modernization initiatives now drive procurement diversification across distinct regulatory environments.
United States
Domestic military installations sustain the largest procurement volumes through counter-UAS programs managed by the Department of Defense. The FAA's Part 89 Remote ID mandate accelerates sensor integration timelines for cooperative and non-cooperative detection infrastructure. Boston's technology corridor hosts multiple radar signal processing firms developing classification algorithms for dense urban environments.
Germany
Airport authorities in Frankfurt and Munich pioneer performance-based service contracts that transfer obsolescence risk to OEMs. EASA's U-space regulatory framework mandates cooperative surveillance infrastructure for crewed and uncrewed traffic integration. Bavaria's defense electronics cluster concentrates AESA module manufacturing for NATO border surveillance applications.
India
The Ministry of Home Affairs procures mobile low-altitude radar platforms for Himalayan terrain where altitude extremes degrade conventional surveillance. BIS certification requirements shape product qualification pathways for foreign manufacturers seeking defense procurement access. Gujarat's industrial corridor hosts assembly facilities for coastal surveillance radar destined for maritime boundary installations.
United Kingdom
Military procurement offices specify GaN-based radar suites for next-generation counter-UAS programs at domestic installations. REACH restrictions on hazardous substances compel OEMs to reformulate printed circuit board substrates for CE marking compliance. Scotland's defense electronics sector specializes in naval radar configurations for North Atlantic maritime safety applications.
Japan
METI funding supports development of low-probability-of-intercept architectures for urban drone detection in dense metropolitan corridors. JIS standards govern electromagnetic compatibility certification for radar systems deployed at civil aviation facilities. The Nagoya industrial zone manufactures precision mechanical components for mechanically scanned radar systems serving regional airport authorities.
Low Altitude Radar Market Competitive Landscape
The competitive structure tilts toward integrated defense conglomerates with established command-and-control architectures. Long-term service contracts and classified threat library access create substantial barriers for new entrants. Two strategic archetypes dominate: full-spectrum defense contractors leveraging platform integration capabilities, and specialized sensor houses competing through maritime and coastal surveillance expertise. Dominant competitive moves include technology licensing arrangements for AESA transmit-receive modules and strategic partnerships with semiconductor foundries to secure GaN supply.
Among US-based defense conglomerates, Raytheon Technologies Corporation and Lockheed Martin Corporation anchor the full-spectrum contractor archetype through sustained military service relationships. Thales Group represents the European specialist model, with Leonardo S.p.A. occupying a comparable position in Mediterranean maritime applications. These three exemplify how geographic origin and institutional customer relationships shape competitive positioning more than pure technology differentiation.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Thales Group |
| Leonardo S.p.A. |
| BAE Systems plc |
| Saab AB |
| Hensoldt AG |
| L3Harris Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Gallium Nitride foundry capacity in Taiwan and South Korea feeds through to transmit-receive module costs, compressing margins for AESA radar manufacturers while elevating pricing power for integrated defense conglomerates with captive semiconductor sourcing.
Pricing Analysis
Performance-based availability contracts now dominate civil aviation procurement, transferring obsolescence risk from airport authorities to OEMs. Price differentiation hinges on GaN versus GaAs semiconductor grade and FAA certification tier for Remote ID integration. Pricing pressure stems from electro-optical substitution in urban drone detection, where radar multipath degradation forces cost compression. Homeland security agencies exhibit highest price sensitivity due to budget fragmentation across federal and state procurement channels, while defense forces tolerate premium positioning for classified threat library access.
Supply Chain Analysis
Refurbishment flows for mechanically scanned radar systems create secondary supply channels as military installations phase out legacy architectures. GaN wafer fabrication concentrates in Taiwan, South Korea, and Japan, with raw material dependencies spanning high-purity gallium substrates, ceramic packaging materials, and specialized thermal interface compounds. Single-source vulnerability in East Asian foundry capacity exposes AESA production to geopolitical disruption. Distribution runs through defense prime contractors with established command-and-control integration capabilities, locking out independent sensor houses from direct military procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds on regulatory mandate density, with the FAA's Part 89 Remote ID deadline forcing synchronized procurement across defense and civil aviation buyers.
For Market Incumbents: Extend service contract durations to capture multi-decade maintenance revenue as performance-based models displace capital purchases. Lock in GaN foundry partnerships through advance purchase agreements to neutralize single-source supply risk. Counter electro-optical substitution by emphasizing all-weather detection superiority in alpine and maritime environments. For New Entrants and Emerging Players: EASA's U-space framework in Germany and France opens a window for software-defined radar architectures that adapt to evolving classification protocols without hardware replacement. Target mobile border surveillance platforms for Himalayan terrain where altitude extremes degrade conventional systems. Pursue joint development agreements with Indian defense electronics clusters to satisfy BIS localization requirements. For Investors and Strategic Acquirers: Roll-up economics work for specialized maritime radar houses because coastal surveillance expertise anchors sticky relationships with European maritime safety authorities. Five-to-ten year viability favors targets with software-configurable signal processing and existing EASA certification pathways. Monitor FAA enforcement actions on Remote ID compliance as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Partnership | Secures transmit-receive module supply for AESA counter-UAS programs against East Asian concentration risk. |
| Software-Defined Architecture Launch | Enables firmware-upgradable classification protocols that adapt to evolving U-space regulatory requirements. |
| Performance-Based Service Contract | Transfers obsolescence risk to OEMs while binding German and French airport authorities to multi-year commitments. |
| Himalayan Terrain Platform Development | Addresses India's Ministry of Home Affairs procurement for mobile radar in altitude-extreme border surveillance. |
| REACH-Compliant Component Qualification | Secures CE marking access for coastal surveillance radar through halogen-free laminate and lead-free solder reformulation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with radar program managers at NATO border agencies, FAA certification leads, GaN foundry operations directors, and defense procurement officers with secondary validation against FAA Remote ID rulemaking dockets, EASA U-space regulatory publications, and defense contractor SEC disclosures. Bottom-up installation counts across military and civil aviation sites triangulated against top-down budget allocation analysis from homeland security and defense appropriations documentation.
Historical reference periods anchored the projection horizon through verified procurement timelines for counter-UAS radar deployments and civil aviation sensor replacement cycles. The analytical framework modeled segmentation across product type, semiconductor technology, application environment, and end-user funding mechanism. CAGR derivation incorporated GaN cost curve trajectories, regulatory deadline compression effects, and electro-optical substitution elasticity in urban detection markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under spectrum reallocation decisions and foundry disruption scenarios. Practitioners should monitor FAA enforcement patterns on Remote ID compliance and EASA U-space implementation timelines for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
C4ISR Market
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
Airborne ISR Market
ISR
Land Based C4ISR Market
ISR
Saudi Arabia C4ISR Market
ISR
Infrared Suppression Systems Market
ISR
Japan C4ISR Market
ISR
Naval ISR Market
ISR
United States C4ISR Market
ISR
C5ISR Market
ISR
C6ISR Market
ISR
North America Airborne ISR Market
ISR
Air Based C4ISR Market
ISR
Asia-Pacific C4ISR Market
ISR
NATO C4ISR Market
ISR
Active Phased Array Radar (APAR) Market