
 Europe Satellite Manufacturing and Launch Systems Market | 2026-2036
Europe Satellite Manufacturing and Launch Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Satellite Manufacturing and Launch Systems Market Foresight
Platform licensing revenue is reshaping margin distribution across the Europe Satellite Manufacturing and Launch Systems value chain, pulling profitability upstream from pure hardware sales toward recurring software and operations contracts. Airbus Defence and Space leverages its integrated prime-contractor position to capture full-lifecycle value across both geostationary and low-Earth-orbit programs. ArianeGroup anchors European heavy-lift independence through the Ariane 6 program while sustaining dual-use capabilities for institutional and commercial customers. Thales Alenia Space specializes in payload electronics and digital telecom missions, occupying a differentiated tier between full-platform primes and component suppliers.
Europe Satellite Manufacturing and Launch Systems encompasses the design, fabrication, integration, and orbital deployment of spacecraft and their associated launch vehicles, with typical satellite masses ranging from sub-100-kilogram CubeSats to multi-ton geostationary platforms requiring precision thermal-vacuum testing and pyroshock-qualified structures. The primary commercial purpose is to place functional assets into targeted orbital regimes for telecommunications, navigation, Earth observation, or strategic surveillance. Satellite manufacturing retains the largest value share within the product-type dimension, driven by persistent demand for high-reliability platforms in government and defense end-user segments. Reusable launch system technology is expanding fastest among propulsion categories, though solid and liquid propellant systems still dominate current European flight manifests due to heritage reliability and established ground infrastructure.
EU Space Programme governance, ESA procurement frameworks, and national export-control regimes collectively shape market access and technology-transfer boundaries for European suppliers. REACH chemical regulations and CE marking requirements impose material-traceability and safety-certification obligations that extend through subcontractor tiers. Stakeholders must monitor how IRIS² security-classification rules and evolving F-Gas Regulation limits on fluorinated propellants will reshape supplier qualifications and manufacturing-location decisions across the continent.
Market Dynamics
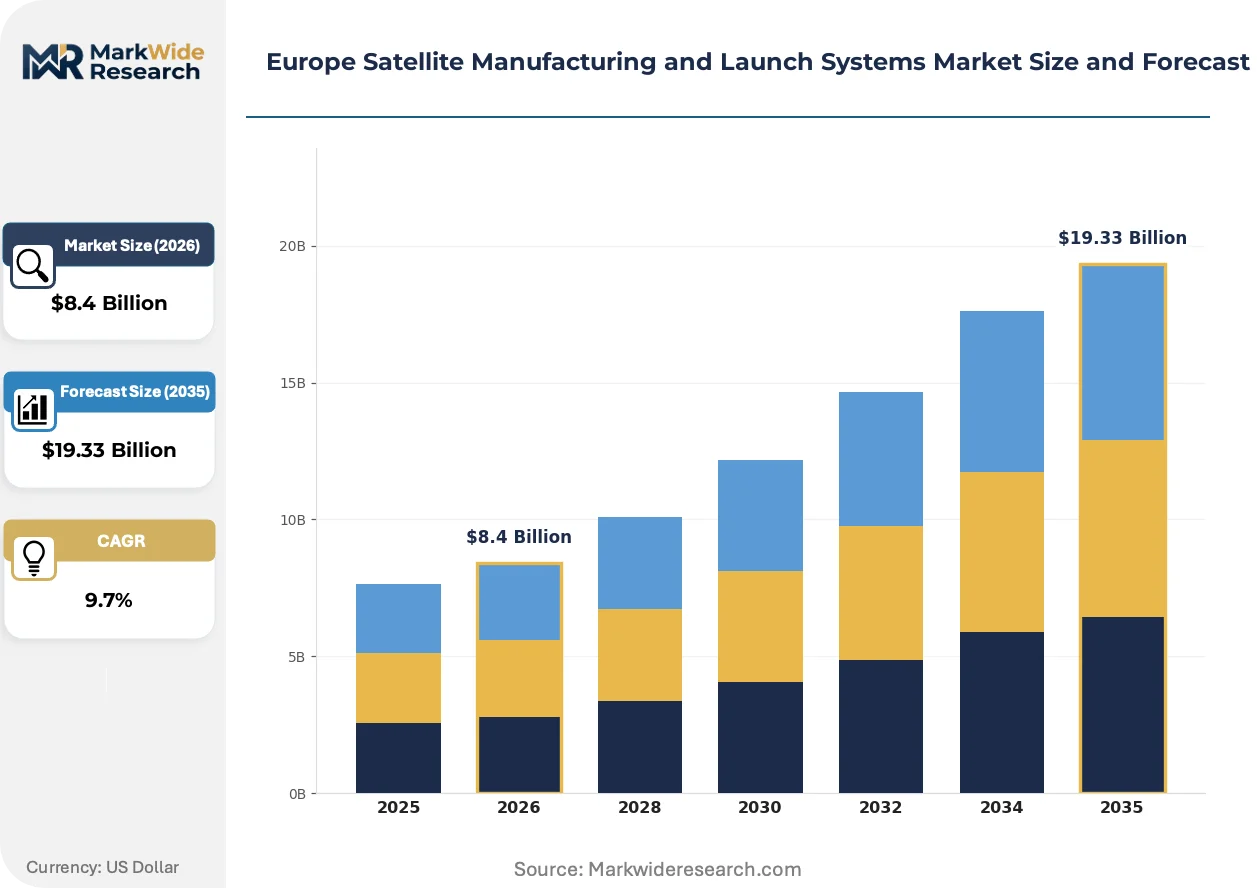
Platform licensing revenue is pulling profitability upstream from hardware sales toward recurring software contracts across European satellite manufacturing. ESA procurement frameworks and national export controls are reshaping supplier qualifications and cross-border technology flows.
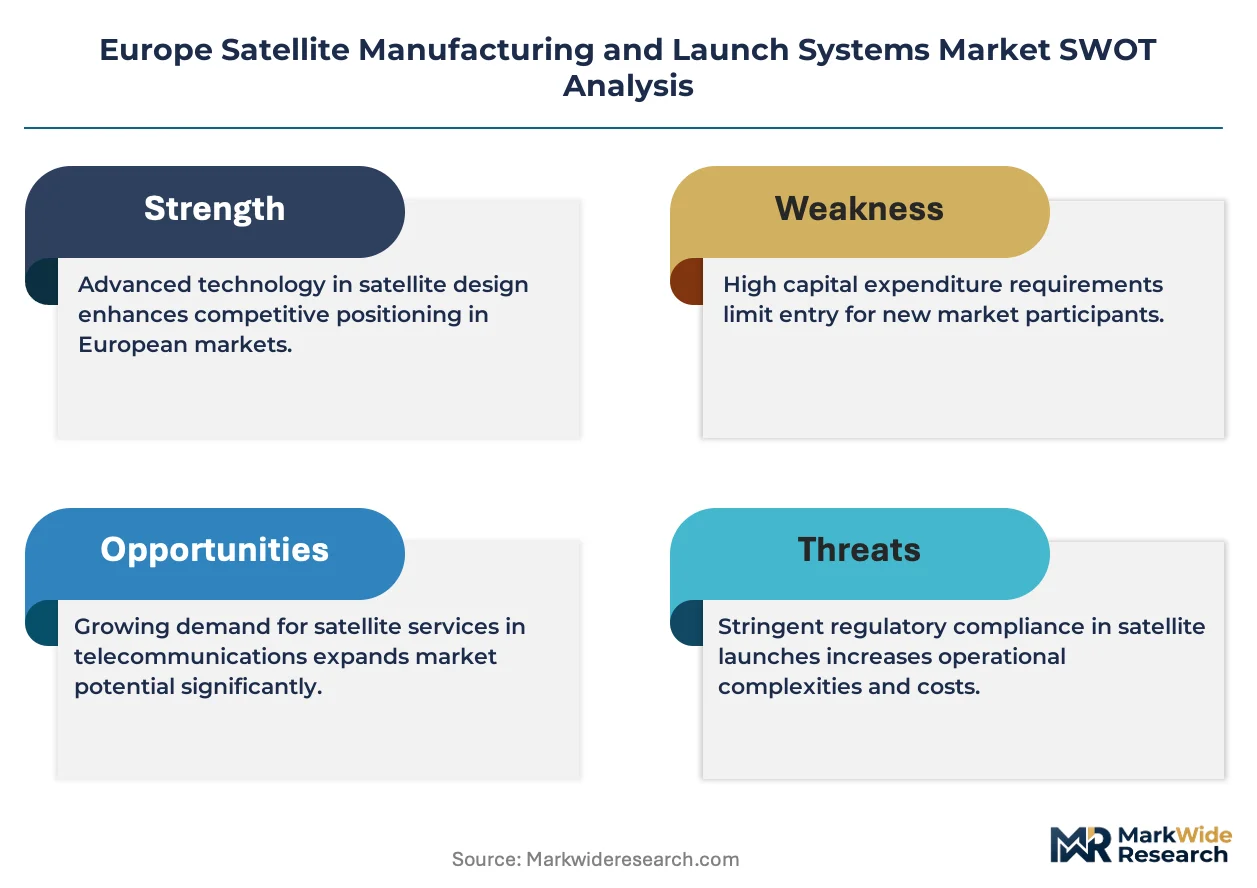
Growth Catalysts
- IRIS² constellation mandate:The EU's secure connectivity initiative is accelerating demand for indigenous launch capacity and sovereign payload manufacturing across member states.
- Earth observation expansion:Government agencies in France, Germany, and Italy are scaling constellation programs for climate monitoring and strategic surveillance applications.
- Reusable propulsion maturation:Liquid methane engine development is reducing per-launch costs and enabling higher flight cadence for commercial operators.
Market Restraints
- Heritage infrastructure lock-in:Solid and liquid propellant systems dominate European flight manifests due to established ground facilities and certification heritage, slowing reusable adoption.
- REACH chemical compliance:Material-traceability obligations extend through subcontractor tiers, raising qualification costs for non-European component suppliers.
- Fluorinated propellant restrictions:Evolving F-Gas Regulation limits are constraining cold-gas thruster options and forcing propulsion architecture redesigns.
Strategic Opportunities
- Sub-regional manufacturing clusters:Italy's satellite electronics corridor and Germany's propulsion test facilities offer underutilized capacity for scaled production.
- Dual-use capability expansion:Military-civilian payload convergence is opening procurement channels beyond traditional institutional customers.
- Digital twin integration:Virtual spacecraft qualification is compressing development timelines and reducing thermal-vacuum test cycle demands.
Industry Challenges
- Pyroshock-qualified workforce scarcity:Specialized structural testing expertise is concentrating at legacy primes, constraining new entrant scale-up.
- CE marking timeline compression:Safety-certification obligations for novel materials are extending qualification phases and delaying first-flight revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Satellite Manufacturing and Launch Systems Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellite, Launch Vehicle, Ground Equipment, Payload Technology: Solid Propellant, Liquid Propellant, Hybrid Propellant, Reusable Launch System End User: Government Agencies, Private Operators, Research Institutions, Defense Organizations Service Type: Manufacturing, Launch, Integration, Testing |
| Companies Covered | ArianeGroup, Avio, Airbus Defence and Space, Surrey Satellite Technology Ltd, RUAG Space, Thales Alenia Space, Arianespace, Isar Aerospace, OHB SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Satellite Manufacturing and Launch Systems Market Shifts & Advancements
Digital engineering workflows are compressing satellite development cycles while regulatory pressure on materials and emissions intensifies. Procurement patterns are shifting toward full-lifecycle service contracts rather than discrete hardware transactions.
Model-based systems engineering is digitizing spacecraft design verification across European prime contractors. ESA and national space agencies are mandating digital twin deliverables for major platform competitions. This methodology is digitizing thermal and structural analysis, reducing physical prototype iterations and compressing program schedules by months.
F-Gas Regulation amendments are restricting hydrofluorocarbon use in satellite propulsion and thermal control systems. Manufacturers are reformulating cold-gas thrusters and heat-pipe working fluids to maintain performance under tightened emission limits. Small-satellite builders in France and Germany are most affected, accelerating alternative refrigerant qualification programs.
Outcome-based service contracts are displacing traditional build-and-deliver procurement for Earth observation constellations. Institutional buyers in Germany and Italy are contracting guaranteed data availability rather than satellite ownership. This restructures supplier cash flows toward recurring revenue and extends platform operational responsibility across fifteen-year service windows.
Europe Satellite Manufacturing and Launch Systems Market Segmentation
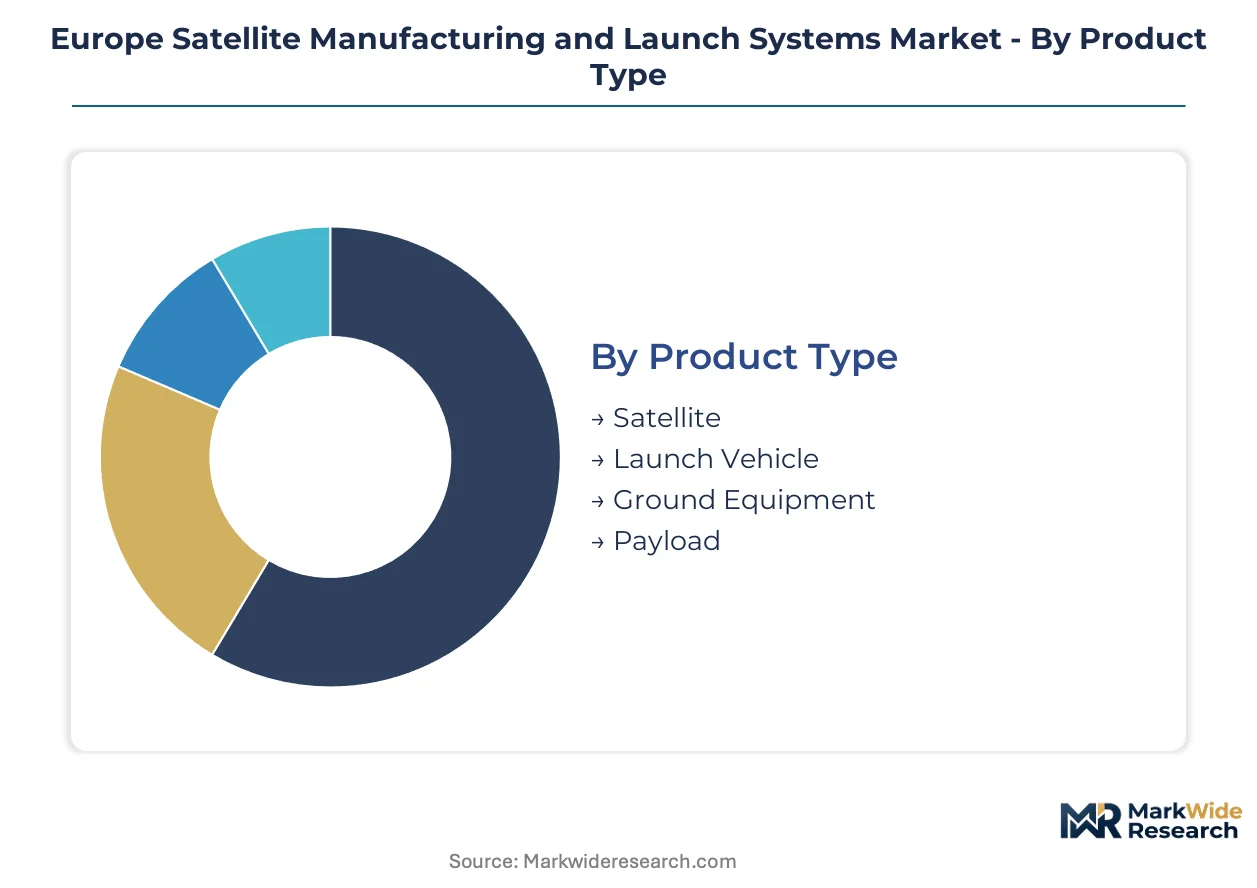
Segmentation in the Europe Satellite Manufacturing and Launch Systems market reveals distinct procurement patterns across institutional and commercial buyers. Each dimension carries different margin profiles, certification requirements, and lifecycle service intensities that reshape supplier positioning across France, Germany, and Italy.
Product Type:
After-sales service intensity varies dramatically across hardware categories, with multi-decade orbital operations contracts generating recurring revenue streams that dwarf initial manufacturing margins.
- Satellite:Geostationary and low-Earth-orbit platforms require precision thermal-vacuum testing and pyroshock-qualified structures. Demand concentrates in French and Italian government constellation programs for Earth observation and secure communications, driven by IRIS² sovereignty mandates and ESA procurement frameworks.
- Launch Vehicle:Heavy-lift and small-lift configurations span solid, liquid, and emerging reusable propulsion architectures. German and French institutional buyers anchor demand for Ariane 6 and Vega-C programs, constrained by heritage infrastructure lock-in and established ground facility networks.
- Ground Equipment:Telemetry, tracking, and command infrastructure supports constellation operations.
- Payload:Sensor packages and transponder electronics integrate with platform buses.
Satellite holds the largest share; momentum sits with Launch Vehicle as reusable propulsion matures.
Technology:
Propulsion technology selection determines ground infrastructure compatibility, certification timelines, and per-mission cost structures across European launch sites.
- Solid Propellant:Cast-composite motor casings with ammonium perchlorate oxidizers deliver high thrust-to-weight ratios for booster stages. Italian and French flight manifests retain solid heritage for Vega-C and Ariane 6 strap-ons, constrained by established ground handling facilities and pyrotechnic workforce concentration.
- Liquid Propellant:Cryogenic hydrogen-oxygen and storable hypergolic systems power core stages and orbital insertion. German propulsion test facilities at Lampoldshausen anchor liquid engine development, with demand accelerating for liquid methane variants to reduce per-launch costs.
- Hybrid Propellant:Combines solid fuel grains with liquid oxidizers for throttleable thrust profiles.
- Reusable Launch System:Vertical landing architectures and flyback boosters enable flight cadence expansion.
Liquid Propellant retains institutional dominance; Reusable Launch System is climbing the fastest as commercial operators pressure cost structures.
End User:
Customer type dictates contracting structures, from cost-plus ESA procurements to fixed-price commercial service agreements with diverging risk allocations.
- Government Agencies:ESA, national space agencies, and EU institutions fund sovereign capability development. French CNES and German DLR procurement concentrates on Earth observation constellations and navigation infrastructure, with IRIS² security requirements mandating European payload manufacturing.
- Private Operators:Telecommunications and Earth observation service providers contract for constellation deployment. Italian and German commercial buyers are expanding demand for small-lift launch services and standardized satellite buses, driven by outcome-based data availability contracts.
- Research Institutions:Universities and scientific consortia access rideshare and dedicated small-satellite missions.
- Defense Organizations:Military buyers procure dual-use platforms with classified payload capabilities.
Government Agencies command the largest procurement volume; Private Operators are gaining share fastest as service-based contracting displaces hardware ownership.
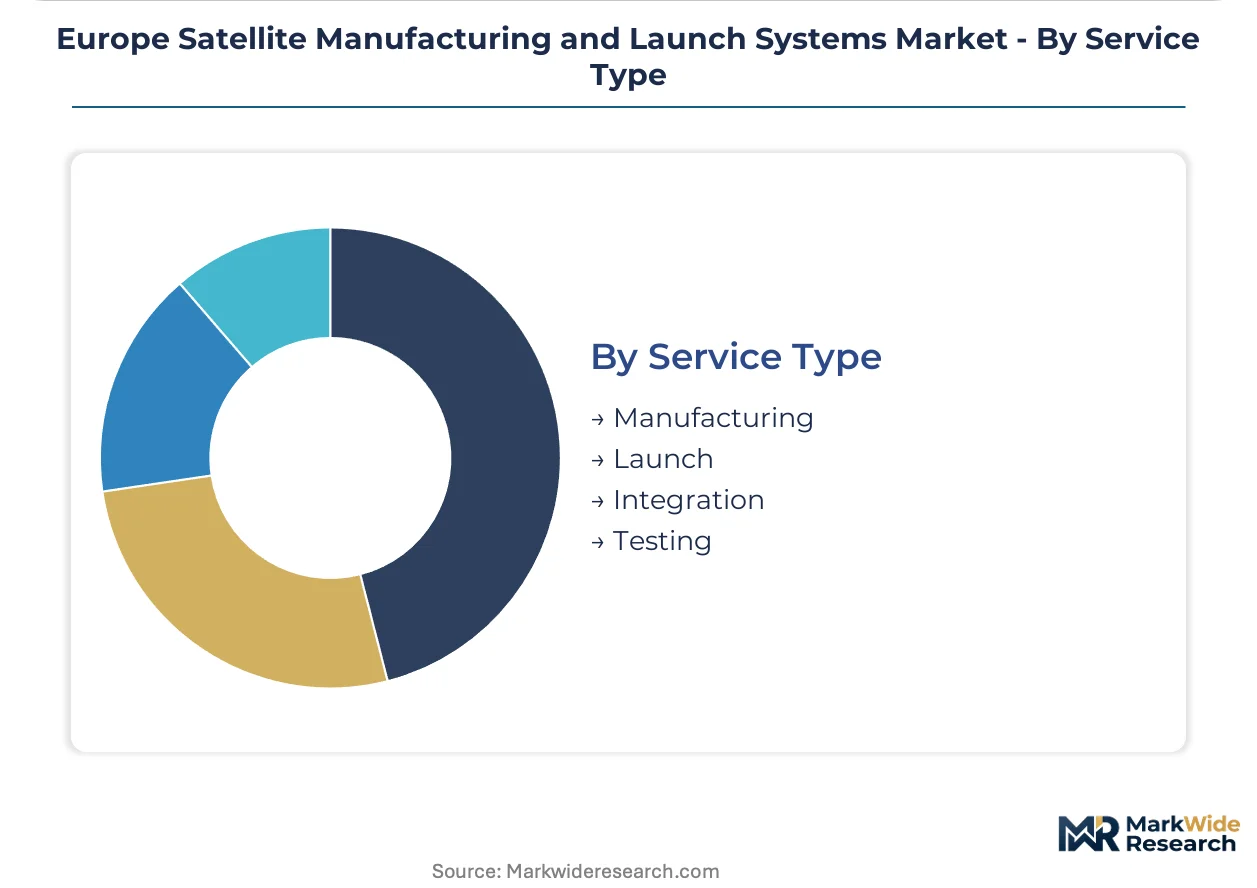
Service Type:
Value chain positioning determines margin capture, with full-lifecycle primes extracting software and operations revenue beyond discrete manufacturing.
- Manufacturing:Platform fabrication, payload integration, and structural qualification. French and Italian prime contractors concentrate high-reliability geostationary production, while German suppliers scale small-satellite serial manufacturing for constellation programs.
- Launch:Mission integration, range operations, and orbital insertion services. ArianeGroup and Arianespace anchor European heavy-lift independence from Kourou, with demand intensifying for indigenous capacity to serve IRIS² deployment timelines.
- Integration:Payload-to-bus mating and system-level verification.
- Testing:Thermal-vacuum, vibration, and electromagnetic compatibility qualification.
Manufacturing captures the greatest value share; Launch is expanding most quickly as flight cadence targets rise across institutional and commercial manifests.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France consumes satellite manufacturing capacity through sovereign constellation mandates, while Germany and Italy deploy production differently across propulsion test infrastructure and electronics corridors respectively. National procurement frameworks fragment demand patterns across member states.
France
CNES anchors institutional demand through Earth observation constellations and secure communications payloads under IRIS² sovereignty requirements. REACH chemical regulations from ECHA constrain material sourcing for Toulouse-based prime contractors. The aerospace cluster around Toulouse concentrates geostationary platform manufacturing and Ariane 6 integration.
Germany
DLR procurement drives demand for liquid methane engine development and small-satellite serial manufacturing for climate monitoring networks. F-Gas Regulation amendments from Brussels force propulsion architecture redesigns at Lampoldshausen test facilities. Bavaria's propulsion corridor hosts cryogenic hydrogen-oxygen development and reusable system qualification programs.
Italy
ASI funding scales Vega-C solid motor production and satellite electronics manufacturing for dual-use applications. CE marking requirements extend qualification timelines for Rome-based payload integrators. The aerospace district in Turin concentrates composite structures fabrication and pyroshock testing capabilities.
United Kingdom
Surrey Satellite Technology and emerging launch operators generate demand for small-lift services and standardized satellite buses. UK Space Agency procurement frameworks diverge from ESA cost-plus structures, favoring fixed-price commercial contracts. Scotland's spaceport cluster at Sutherland and SaxaVord advances vertical launch capability for polar orbits.
Spain
INTA and regional governments invest in ground segment infrastructure and satellite component manufacturing for export markets. EU Green Deal emission targets reshape supplier qualifications for Madrid-based electronics suppliers. Andalusia's aerospace corridor around Seville hosts payload integration facilities and thermal-vacuum test chambers.
Europe Satellite Manufacturing and Launch Systems Market Competitive Landscape
Capability concentration sits with full-lifecycle primes; scale advantage sits with specialized component fabricators. The vendor base organizes into three tiers: integrated platform manufacturers capturing software and operations revenue, propulsion specialists anchoring launch infrastructure, and payload electronics suppliers occupying intermediate positions. Dominant competitive moves include backward integration into critical subsystems and geographic expansion through sub-regional manufacturing clusters.
Among French integrated primes, ArianeGroup and Airbus Defence and Space exemplify full-lifecycle positioning across launch vehicles and satellite platforms. Thales Alenia Space occupies a differentiated tier between platform primes and component suppliers, specializing in payload electronics and digital telecom missions. Isar Aerospace represents the emerging commercial launch archetype, developing reusable liquid methane systems outside traditional institutional procurement channels.
| Leading Market Players |
|---|
| ArianeGroup |
| Avio |
| Airbus Defence and Space |
| Surrey Satellite Technology Ltd |
| RUAG Space |
| Thales Alenia Space |
| Arianespace |
| Isar Aerospace |
| OHB SE |
| Others |
Supply & Pricing Matrix
Rhine-Alpine corridor freight dynamics concentrate component flows through German propulsion test hubs and French integration facilities, amplifying cost pass-through to satellite primes while enabling three-tier pricing stratification across premium qualification-grade platforms, standard constellation buses, and economy small-satellite kits.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement from ESA and national space agencies, locking in cost-plus structures for Ariane 6 and IRIS² constellation builds. Price differentiation hinges on CE marking certification tier and after-sales service bundling across fifteen-year operational windows. Cost compression in small-satellite manufacturing intensifies as Isar Aerospace and emerging launch operators force fixed-price competition. Private telecommunications operators exhibit highest price sensitivity; defense organizations with classified payload requirements show lowest.
Supply Chain Analysis
Upstream feedstock for solid propellant motors draws from Italian ammonium perchlorate suppliers and French cast-composite casing fabricators, while liquid engine development rests on German cryogenic hydrogen-oxygen supply chains. Critical dependencies include pyroshock-qualified aluminum-lithium alloys, radiation-hardened semiconductors, and REACH-compliant thermal control materials. Single-source vulnerability concentrates in Turin-based composite structures and Lampoldshausen propulsion testing. Distribution runs through Toulouse prime contractor integration hubs to Kourou launch facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's satellite manufacturing sector enters a cyclical recovery phase as IRIS² constellation deployment schedules and Ariane 6 operational ramp restore institutional procurement velocity.
For Market Incumbents: Insulate sovereign manufacturing margins by deepening backward integration into payload electronics and cold-gas thruster production, countering emerging commercial launch cost pressure. Capture recurring software revenue through digital twin service contracts that extend platform operational responsibility. Prioritize CE marking pre-certification for novel refrigerant formulations ahead of tightened F-Gas Regulation enforcement.
For New Entrants and Emerging Players: Pursue standardized small-satellite bus architectures for German climate monitoring networks and Italian dual-use electronics corridors, where institutional buyers accept fixed-price risk transfer. Target Scotland's emerging spaceport cluster for polar orbit launch services, leveraging UK Space Agency procurement divergence from ESA cost-plus structures. Lead with outcome-based data availability contracts rather than hardware ownership models.
For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace conglomerates divesting non-core ground segment operations and legacy thermal-vacuum testing facilities. Long-term viability favors suppliers with captive propulsion qualification infrastructure and IRIS² security-cleared manufacturing locations. Monitor Ariane 6 flight cadence attainment as the critical inflection signal for European heavy-lift market depth.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Payload Electronics | Thales Alenia Space and Airbus Defence capture margin upstream from component suppliers through in-house transponder production. |
| Digital Twin Service Contracting | Virtual spacecraft qualification compresses ESA program schedules while locking in fifteen-year recurring revenue streams. |
| Reusable Propulsion Qualification | Liquid methane engine development at Isar Aerospace and ArianeGroup reduces per-launch costs for commercial constellation operators. |
| Sub-regional Manufacturing Cluster Expansion | Turin composite structures and Bavaria propulsion corridors offer scaled capacity for IRIS² sovereign payload mandates. |
| Alternative Refrigerant Certification | F-Gas Regulation compliance for cold-gas thrusters maintains European small-satellite export competitiveness under tightened emission limits. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ESA procurement databases, REACH chemical registration filings, and EU Space Programme policy documents. Interviews with satellite platform engineering directors, launch range operations managers, propulsion test facility leads, and institutional procurement officers at CNES and DLR inform demand-side validation. Customs trade data for aerospace-grade aluminum-lithium alloys, radiation-hardened semiconductor import records, and Arianespace manifest disclosures anchor supply-side triangulation. Bottom-up segment sizing cross-checks against top-down European space budget allocations.
Forecast inputs incorporate satellite mass class distributions, propulsion technology adoption curves, and IRIS² deployment timeline assumptions across the projection horizon. Segmentation dimensions span product type, propulsion architecture, end-user contracting structure, and service intensity. CAGRs derive from regression analysis against historical ESA and national space agency expenditure patterns, adjusted for reusable launch cost elasticity and digital twin service contract penetration. Industry-specific inputs include Ariane 6 production ramp schedules and F-Gas Regulation amendment implementation trajectories.
Macroeconomic conditions sit as an overlay; deviation in eurozone defense spending commitments or EU Green Deal enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding constellation program funding continuity and launch site operational readiness. Cross-checking against ESA Director General annual reports and national space agency budget appropriations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
EMEA Satellite Antenna Market
Satellite
Global Remote Sensing Services Market
Satellite
Nanosatellite Market
Satellite
Global Satellite Modem Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
North America Satellite Manufacturing Market
Satellite
Satellite Backhaul Market
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
Vehicle Mounted Satellite Communication Station Market
Satellite
Medium and Large Satellite Market
Satellite
Reconnaissance Satellite Market
Satellite
High-Throughput Satellite Market
Satellite
Global Commercial Satellite Broadband Market
Satellite
United Kingdom Satellite Communications Market
Satellite
Earth Observation Satellite Market
Satellite
Indonesia Satellite Communications Market