
 UK Satellite Connectivity Market | 2026-2036
UK Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
UK Satellite Connectivity Market Insights
Market Context
UK ground station infrastructure is consolidating around Cornwall and Goonhilly clusters as launch capacity expands from Scottish spaceports. OneWeb leverages its LEO constellation manufacturing presence in Florida and UK gateway operations to anchor government and enterprise contracts. Inmarsat Plc sustains its geostationary heritage through GX network upgrades while competing with newer LEO entrants for maritime and aviation clients. Avanti Communications specializes in Ka-band fixed VSAT services across rural Britain and Africa, occupying a distinct pricing tier from constellation operators.
Technical Definition and Segment Structure
UK satellite connectivity encompasses orbital and ground-based systems that relay data, voice, and video signals between earth stations and spacecraft operating across geostationary, low, medium, and highly elliptical orbits, with terminal aperture sizes ranging from sub-1m portable units to 2.4m+ fixed installations and link budgets engineered for rain fade margins exceeding 6dB in temperate maritime climates. Fixed VSAT terminals dominate enterprise and government backhaul revenue pools due to longer contract tenors and higher installation values, while portable and flyaway terminals represent the fastest-growing product category as emergency services and broadcast journalists demand rapid-deploy connectivity. Low Earth Orbit deployment modes capture disproportionate investment flow given latency advantages for real-time military and financial applications, though geostationary orbit retains margin strength in broadcast services where orbital slot scarcity creates pricing power.
Regulatory Framework and Outlook
Ofcom governs spectrum licensing and orbital filing coordination for UK-registered operators, while the Civil Aviation Authority and Maritime and Coastguard Agency mandate safety-of-life satellite communication standards for respective transport modes. The UK Space Agency's national space strategy and export control regulations administered through the Department for International Trade shape market access for foreign constellation providers seeking gateway earth station rights. Stakeholders must monitor Ofcom's forthcoming non-geostationary spectrum sharing rules and their interaction with EU ITU coordination procedures post-Brexit.
Market Dynamics
LEO constellation deployment is compressing latency benchmarks across UK defence and maritime contracts, forcing legacy geostationary operators to re-engineer service architectures or surrender high-value accounts to lower-orbit rivals.
Growth Catalysts
- Scottish spaceport activation:Vertical launch sites at Sutherland and SaxaVord are expanding domestic orbital insertion capacity, reducing reliance on foreign launch providers for UK-registered spacecraft.
- Ofcom NGSO spectrum framework:Non-geostationary licensing reforms are accelerating gateway earth station approvals for constellation operators seeking UK territorial coverage.
- Maritime safety mandates:The Maritime and Coastguard Agency's updated Global Maritime Distress and Safety System requirements are compelling shipping operators to upgrade satellite communication terminals.
Market Restraints
- Ground station capex concentration:Cornwall and Goonhilly clusters dominate gateway infrastructure, creating geographic single-point vulnerability for national connectivity resilience.
- Rain fade engineering costs:Ka-band and Q/V-band link budgets require 6dB+ fade margins in temperate maritime climates, elevating terminal hardware costs versus lower-frequency alternatives.
- ITU coordination friction:Post-Brexit orbital filing procedures with EU member states are lengthening spectrum harmonization timelines for UK-registered constellations.
Strategic Opportunities
- Rural enterprise backhaul:Fixed VSAT deployment in Scottish Highlands and Welsh valleys remains underpenetrated versus terrestrial fibre alternatives, creating white space for satellite operators.
- LEO-GEO service blending:Hybrid constellations combining low-latency LEO routing with geostationary broadcast capacity are enabling new service tiers for financial trading applications.
- Defence sovereign connectivity:UK Space Agency procurement frameworks are mandating domestic gateway operations for classified military traffic, privileging UK-based infrastructure providers.
Industry Challenges
- RF engineering talent scarcity:Specialist microwave and antenna design skills for phased-array terminals are concentrating among a narrow cohort of defence-sector veterans.
- Legacy Inmarsat integration:Maritime clients operating GX network terminals face hardware obsolescence cycles as LEO alternatives require entirely new antenna form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Satellite Connectivity Market |
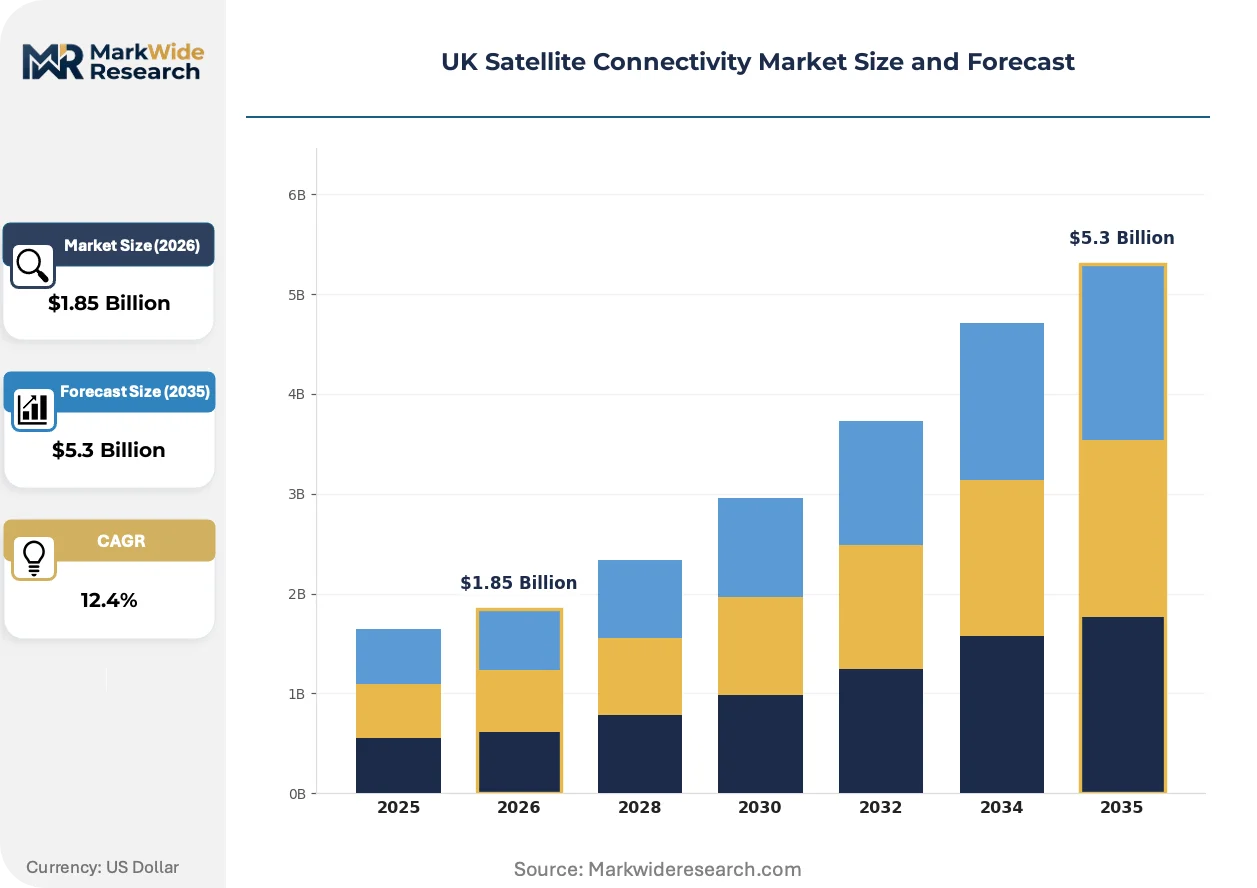
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.3 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Very Small Aperture Terminal, Mobile VSAT, Fixed VSAT, Portable VSAT, Flyaway Terminals Application: Maritime Communications, Remote Area Networking, Emergency Response, Military Operations, Broadcast Services End User: Telecom Operators, Government Agencies, Non-Governmental Organizations, Media Houses, Research Institutions Deployment Mode: Geostationary Orbit, Low Earth Orbit, Medium Earth Orbit, Highly Elliptical Orbit |
| Companies Covered | OneWeb, Inmarsat Plc, Avanti Communications, Surrey Satellite Technology Ltd, Goonhilly Earth Station, Freedomsat, Talia Communications Ltd, Satlink Ltd, ETL Systems Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Satellite Connectivity Market Trends and Innovations
Electronically steered antennas are displacing mechanical gimbal systems across mobile platforms, while regulatory pressure on spectrum efficiency is accelerating terminal miniaturization and power-density improvements.
Flat-panel phased-array technology is absorbing the bulk of R&D investment from terminal manufacturers seeking to serve aviation and maritime mobility markets. British Airways and ferry operators are piloting these antennas for continuous connectivity during cross-Channel routes. The technology is absorbing market share from parabolic dishes in applications where aerodynamic drag or deck space constraints previously blocked satellite adoption.
Ofcom's forthcoming non-geostationary spectrum sharing rules are tightening coordination requirements between LEO constellations and incumbent fixed-link operators. The Civil Aviation Authority is aligning safety certification timelines with these spectrum reforms, delaying some aeronautical terminal approvals. Maritime and aviation service providers are responding by pre-positioning gateway capacity ahead of formal licensing clearance.
Enterprise buyers are consolidating satellite procurement under managed service contracts rather than capital-intensive terminal ownership models. Defence and broadcast verticals are leading this shift, with Ministry of Defence frameworks now specifying availability-based payment structures. Scotland's rural enterprise networks are exhibiting similar consolidation, with local authorities pooling connectivity demand across multiple remote sites.
UK Satellite Connectivity Market Segmentation
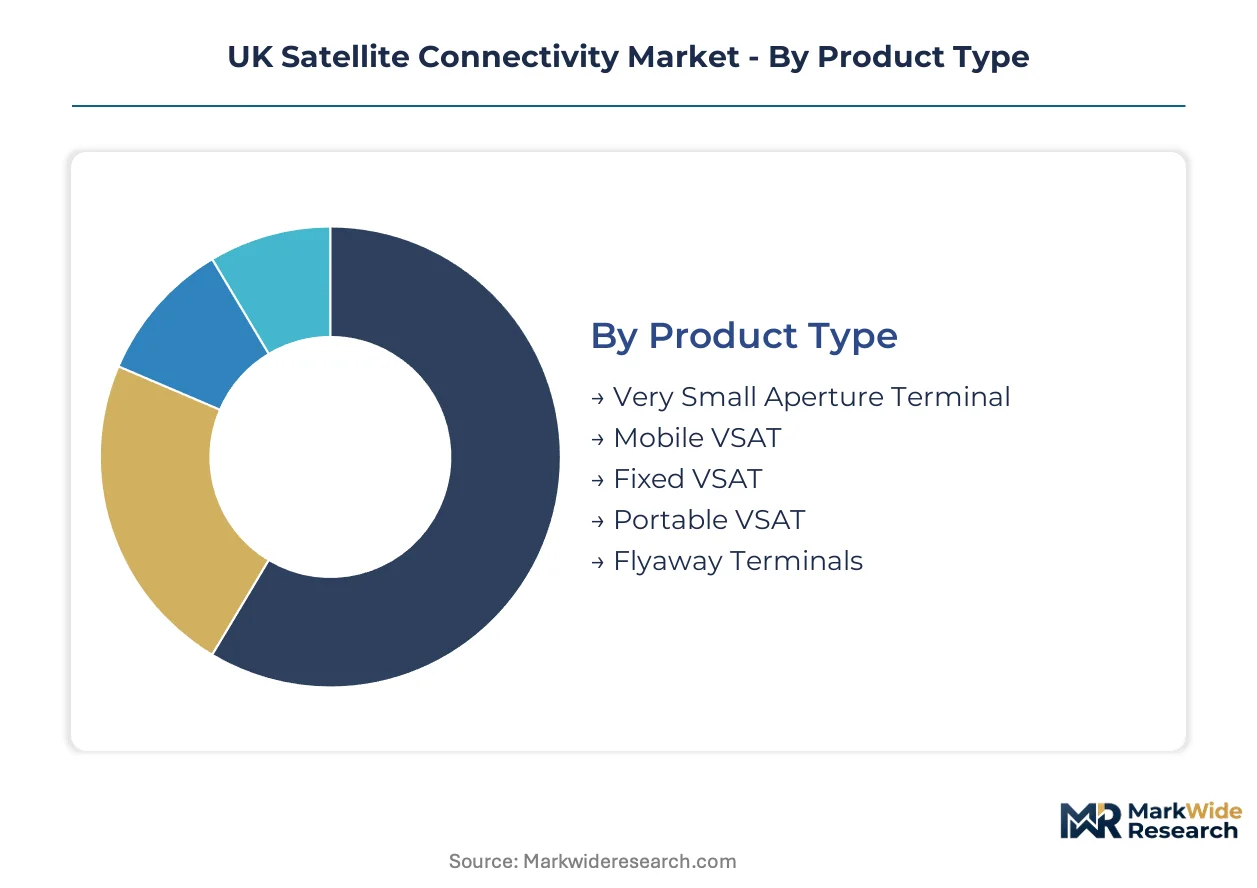
Segmentation in the UK satellite connectivity market reveals distinct procurement patterns across terminal hardware, orbital architectures, and end-use verticals. Each dimension carries different margin profiles, contract tenors, and regulatory exposure that shape vendor positioning and investment allocation.
Product Type:
Capital intensity varies sharply across terminal categories, with fixed installations demanding substantial upfront earth station investment while portable units prioritize miniaturization R&D over infrastructure.
- Fixed VSAT:Stationary terminals with 2.4m+ aperture dishes anchor enterprise backhaul and government gateway operations. Scottish Highlands councils and Cornwall cluster operators concentrate procurement here, driven by long-term sovereign connectivity contracts requiring 99.95% availability SLAs.
- Portable VSAT:Rapid-deploy sub-1m terminals with integrated power systems serve emergency services and disaster response teams. Welsh mountain rescue services and Environment Agency flood response units are expanding fleets, constrained by battery energy density limits on extended deployments.
- Very Small Aperture Terminal:Compact sub-0.75m dishes dominate consumer broadband and small enterprise markets.
- Mobile VSAT:Vehicle-mounted stabilized antennas address in-motion connectivity for defence and broadcast journalism.
- Flyaway Terminals:Man-portable cases with auto-acquisition systems deploy within 15 minutes for temporary events.
Fixed VSAT absorbs the bulk of installed capacity; Portable VSAT is expanding most quickly.
Application:
Application segmentation tracks funding source divergence, with defence and maritime budgets exhibiting procurement cycle stability versus broadcast and emergency services facing discretionary spending volatility.
- Maritime Communications:Safety-of-life and crew welfare connectivity for shipping operators traversing UK territorial waters. Maritime and Coastguard Agency GMDSS mandates are compelling terminal upgrades across ferry fleets and offshore supply vessels operating North Sea routes.
- Military Operations:Sovereign gateway-dependent classified communications for UK defence networks. Ministry of Defence frameworks are mandating domestic earth station operations, privileging Cornwall and Goonhilly infrastructure providers with security-cleared personnel.
- Remote Area Networking:Enterprise backhaul for terrestrial fibre gaps in rural Britain.
- Emergency Response:Resilient communications for blue-light services and humanitarian deployment.
- Broadcast Services:Contribution and distribution links for television production and live event transmission.
Military Operations commands the highest contract values per site; Maritime Communications shows the steepest expansion trajectory as regulatory deadlines approach.
End User:
End user segmentation reflects divergent technical specifications, with government agencies mandating domestic gateway control while commercial operators prioritize cost-optimized international capacity.
- Government Agencies:Central and devolved administration departments with classified traffic requirements. UK Space Agency procurement frameworks specify availability-based payment structures, shifting risk to service providers.
- Telecom Operators:Mobile network operators and fixed-line providers using satellite for backhaul extension. Rural 4G/5G site aggregation in Scotland and Wales concentrates demand here, limited by spectrum coordination with terrestrial microwave links.
- Media Houses:Television broadcasters and streaming platforms requiring contribution feeds.
- Non-Governmental Organizations:Humanitarian and development organizations with field deployment needs.
- Research Institutions:Universities and environmental monitoring stations requiring data relay.
Government Agencies anchor premium pricing tiers; Telecom Operators are gaining share fastest as mobile backhaul substitution accelerates.
Deployment Mode:
Deployment mode segmentation captures the fundamental latency-versus-coverage trade-off, with orbital altitude determining terminal tracking complexity and gateway density requirements.
- Low Earth Orbit:Constellations below 2,000km altitude delivering sub-50ms latency for real-time applications. OneWeb's Florida manufacturing and UK gateway operations are capturing defence and financial trading contracts, though sustained capital deployment for constellation replenishment strains operator balance sheets.
- Geostationary Orbit:Fixed-position satellites at 35,786km serving broadcast and maritime safety applications. Inmarsat's GX network upgrades sustain incumbent position in aviation and shipping markets where antenna pointing simplicity outweighs latency sensitivity.
- Medium Earth Orbit:Intermediate altitude systems balancing coverage and latency performance.
- Highly Elliptical Orbit:Elongated paths optimized for high-latitude coverage in polar regions.
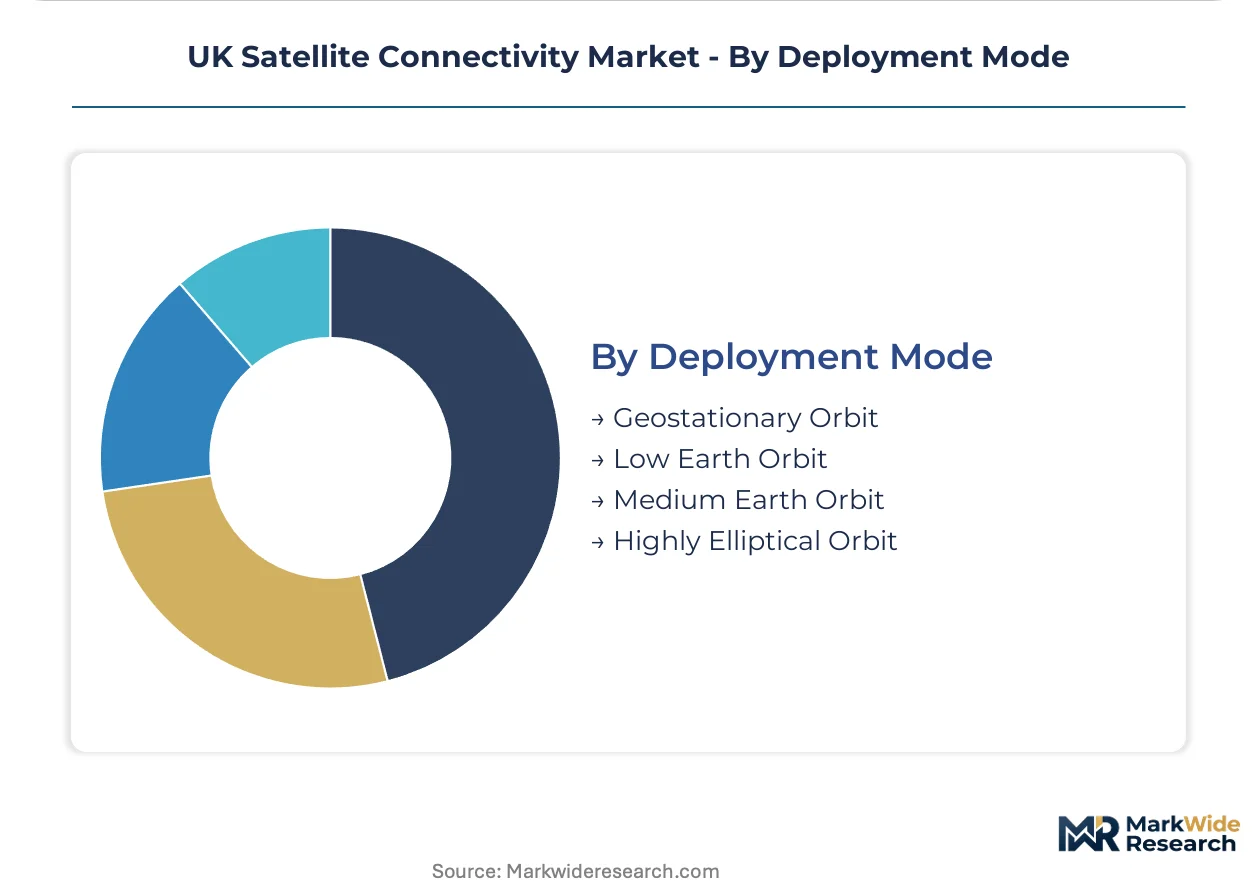
Geostationary Orbit retains the largest installed base; Low Earth Orbit is climbing the fastest as constellation deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cornwall's ground station cluster anchors UK satellite infrastructure capacity, with Scottish spaceports expanding domestic launch access for orbital insertion missions.
Scotland
Sutherland and SaxaVord vertical launch sites are activating orbital insertion capacity for domestic spacecraft deployment. Scottish Enterprise funding streams support spaceport infrastructure development across the Highlands. Edinburgh and Glasgow house satellite manufacturing and data analytics clusters serving defence procurement frameworks.
England
Cornwall's Goonhilly Earth Station cluster processes gateway traffic for LEO constellation operators seeking UK territorial coverage. Ofcom's spectrum allocation reforms are streamlining earth station licensing for non-geostationary systems. London hosts service provider headquarters managing government and enterprise connectivity contracts.
Wales
Rural valley networks drive fixed VSAT demand where terrestrial fibre penetration remains limited. Welsh Government digital connectivity programs subsidize satellite backhaul for remote enterprise sites. Snowdonia and Brecon Beacons terrain concentrates emergency services portable terminal procurement for mountain rescue operations.
Northern Ireland
Cross-border spectrum coordination with Ireland shapes orbital filing procedures for operators serving both jurisdictions. Belfast harbours maritime connectivity providers supporting Irish Sea shipping routes. Department for the Economy funding targets space sector supply chain development for ground station component manufacturing.
UK Satellite Connectivity Market Competitive Landscape
Global constellation operators compete with regional service providers across terminal distribution and gateway operations. The vendor structure tiers between LEO constellation owners, geostationary incumbents, and specialized VSAT service providers. Three archetypes dominate: orbital infrastructure owners controlling constellation assets, gateway operators managing earth station capacity, and service aggregators bundling multi-orbit connectivity. Capacity expansion and spectrum portfolio diversification represent the primary competitive vectors as latency benchmarks compress.
Among UK-anchored operators, OneWeb and Inmarsat Plc occupy positions across the orbital infrastructure tier, while Avanti Communications exemplifies the specialized VSAT service archetype focused on fixed broadband markets. These three represent distinct strategic postures within the competitive structure—constellation ownership versus legacy geostationary networks versus regional service specialization.
| Leading Market Players |
|---|
| OneWeb |
| Inmarsat Plc |
| Avanti Communications |
| Surrey Satellite Technology Ltd |
| Goonhilly Earth Station |
| Freedomsat |
| Talia Communications Ltd |
| Satlink Ltd |
| ETL Systems Ltd |
| Others |
Pricing and Supply Chain Analysis
Flat-panel phased-array manufacturing is displacing mechanical gimbal production across UK terminal suppliers, simultaneously compressing unit economics and concentrating component sourcing among microwave semiconductor foundries in the United States and Taiwan. This technology transition elevates upfront R&D amortization while reducing field maintenance costs, reshaping how vendors structure service contracts and warranty bundles.
Pricing Analysis
Warranty and lifecycle service bundling separates premium-tier offerings from unbundled hardware-only transactions in the UK satellite connectivity market. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by terminal aperture size, rain-fade engineering certification, and gateway redundancy guarantees. Pricing pressure stems from LEO constellation overcapacity as OneWeb and rival operators expand UK gateway footprints. Government agencies exhibit lowest price sensitivity due to sovereign security mandates, while rural telecom operators face acute cost constraints when substituting satellite for terrestrial fibre backhaul.
Supply Chain Analysis
Regional distribution centers in Cornwall and Hampshire operate hub-and-spoke patterns radiating to Scottish spaceport clusters and Welsh emergency services depots. Component manufacturing concentrates in the United States, Taiwan, and Germany for gallium nitride power amplifiers and beamforming chips. Raw material dependencies include rare earth elements for magnet assemblies, high-purity silicon for phased-array substrates, and specialized aluminium alloys for terminal housings. Single-source vulnerability characterizes gallium arsenide wafer supply, with distribution running through aerospace-qualified logistics channels subject to export control screening.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK satellite connectivity market sits in a technology-transition phase as electronically steered antennas replace parabolic dish architectures across maritime and aviation mobility segments.
For Market Incumbents: To counter LEO constellation latency advantages, geostationary operators must accelerate hybrid service architectures blending GEO broadcast capacity with LEO routing partnerships. Incumbents should deepen backward integration into gateway earth station operations across Cornwall and Goonhilly clusters, securing security-cleared personnel pools for defence contract eligibility. Certification investment in flat-panel terminal interoperability represents a critical defensive lever against hardware obsolescence cycles. For New Entrants and Emerging Players: Rural enterprise backhaul in Scottish Highlands and Welsh valleys offers the most penetrable white space, with local authority pooled procurement creating aggregated demand blocks. Maritime safety mandate deadlines present a second entry avenue for terminal vendors offering GMDSS-compliant rapid-deploy systems. A managed-service go-to-market angle, shifting capital burden to availability-based payment structures, aligns with Ministry of Defence framework preferences and Scotland's rural connectivity programs. For Investors and Strategic Acquirers: Exit pathways concentrate in gateway infrastructure consolidation and phased-array terminal manufacturing capability. Long-term viability hinges on constellation replenishment capital deployment sustainability and spectrum portfolio depth. The signal to watch is Ofcom's non-geostationary licensing clearance velocity, which gates revenue recognition for LEO operators seeking UK territorial coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Gateway Infrastructure Consolidation | Cornwall and Goonhilly cluster expansion captures defence sovereign connectivity mandates requiring domestic earth station operations. |
| Flat-Panel Terminal Manufacturing Scale-Up | Electronically steered antenna production absorbs R&D investment from vendors seeking aviation and maritime mobility contracts. |
| Hybrid LEO-GEO Service Architecture | Combining low-latency routing with broadcast capacity enables new financial trading application tiers for enterprise buyers. |
| Spectrum Portfolio Diversification | Ofcom's non-geostationary framework approvals determine competitive access to UK territorial coverage for constellation operators. |
| Managed Service Contract Transition | Availability-based payment structures shift capital risk to service providers across Ministry of Defence and rural authority frameworks. |
Research Methodology
Document review covered Ofcom spectrum licensing records, UK Space Agency procurement frameworks, and Maritime and Coastguard Agency safety mandates, complemented by interviews with satellite terminal procurement leads at defence contractors, gateway operations directors in Cornwall, and rural connectivity program managers in Scottish local authorities. Secondary validation drew from Civil Aviation Authority certification timelines, Department for International Trade export control guidance, and operator gateway capacity disclosures. Bottom-up terminal deployment estimates triangulated against top-down orbital capacity supply projections.
Segmented outputs across the projection horizon model terminal product categories, orbital deployment modes, and end-use verticals including defence, maritime, and emergency services. CAGRs derived from installed base growth curves weighted by contract tenor distributions and gateway licensing velocity. Industry-specific inputs incorporated Scottish spaceport activation timelines and rain-fade engineering cost premiums for Ka-band link budgets in temperate maritime climates.
Revisions become necessary when Ofcom regulatory clearance delays, ITU coordination friction with EU member states, or constellation replenishment funding disruptions materialize. Forecasts reflect documented assumptions regarding spectrum allocation reform implementation and launch capacity availability from Sutherland and SaxaVord. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Commercial Satellite Broadband Market
Satellite
Asia-Pacific Satellite IoT Market
Satellite
Satellite Data Analytics Services Market
Satellite
North America Small Satellite Market
Satellite
Communication Satellite Launch Services Market
Satellite
Global Satellite Modem Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
Europe Satellite Manufacturing and Launch Systems Market
Satellite
Brazil Satellite-Based Earth Observation Market
Satellite
Mexico Satellite Connectivity Market
Satellite
Asia-Pacific Satellite Attitude and Orbit Control System Market
Satellite
LEO Satellite System Market
Satellite
Global Commercial Satellite Imagery Market
Satellite
United Kingdom Satellite Communications Market
Satellite
Nanosatellite Market